
 Heptafluoropropane Fire Suppression System Market | 2026-2036
Heptafluoropropane Fire Suppression System Market Size, Share, and Industry Trends Forecast 2026-2036
Heptafluoropropane Fire Suppression System Market Insights
Market Context with Strategic Players
Chinese specialty chemical producers is consolidating heptafluoropropane feedstock supply, tightening global availability of the HFC-227ea agent. Honeywell International Inc. leverages its fluorochemical heritage to sustain vertical integration from raw material through finished suppression system distribution. Tyco Fire Protection Products anchors its position through extensive channel control across commercial and industrial installation networks. Kidde Fire Systems competes on brand strength in residential and light commercial segments where code compliance simplicity drives selection.
Technical Definition and Structural Segments
Heptafluoropropane fire suppression systems deploy HFC-227ea (CF3CHFCF3), a colorless, electrically non-conductive gas stored at 360 psig that extinguishes fires through heat absorption and oxygen displacement without residue damage to sensitive electronics. Fixed systems dominate commercial and industrial deployment due to permanent piping infrastructure integration with building alarm and ventilation controls, while portable systems serve specialized maintenance and marine applications where mobility outweighs coverage scale. Data center application demand leads value generation as hyperscale facilities prioritize zero-downtime protection for server racks and power distribution units, with oil and gas representing a mature segment where established halon replacement cycles sustain replacement volumes rather than expansion.
Regulatory Framework and Forward Outlook
EPA SNAP program classifications and EU F-Gas Regulation phase-down schedules directly constrain heptafluoropropane formulation eligibility and import volumes in their respective jurisdictions, while NFPA 2001 and ISO 14520 establish agent concentration and discharge performance benchmarks that manufacturers must certify against for market access. China's MEE oversees domestic production quotas under its hydrofluorocarbon consumption baseline commitments. Stakeholders must monitor emerging per- and polyfluoroalkyl substance restrictions that could reclassify HFC-227ea precursors and accelerate investment in fluorine-free clean agent alternatives.
Market Dynamics
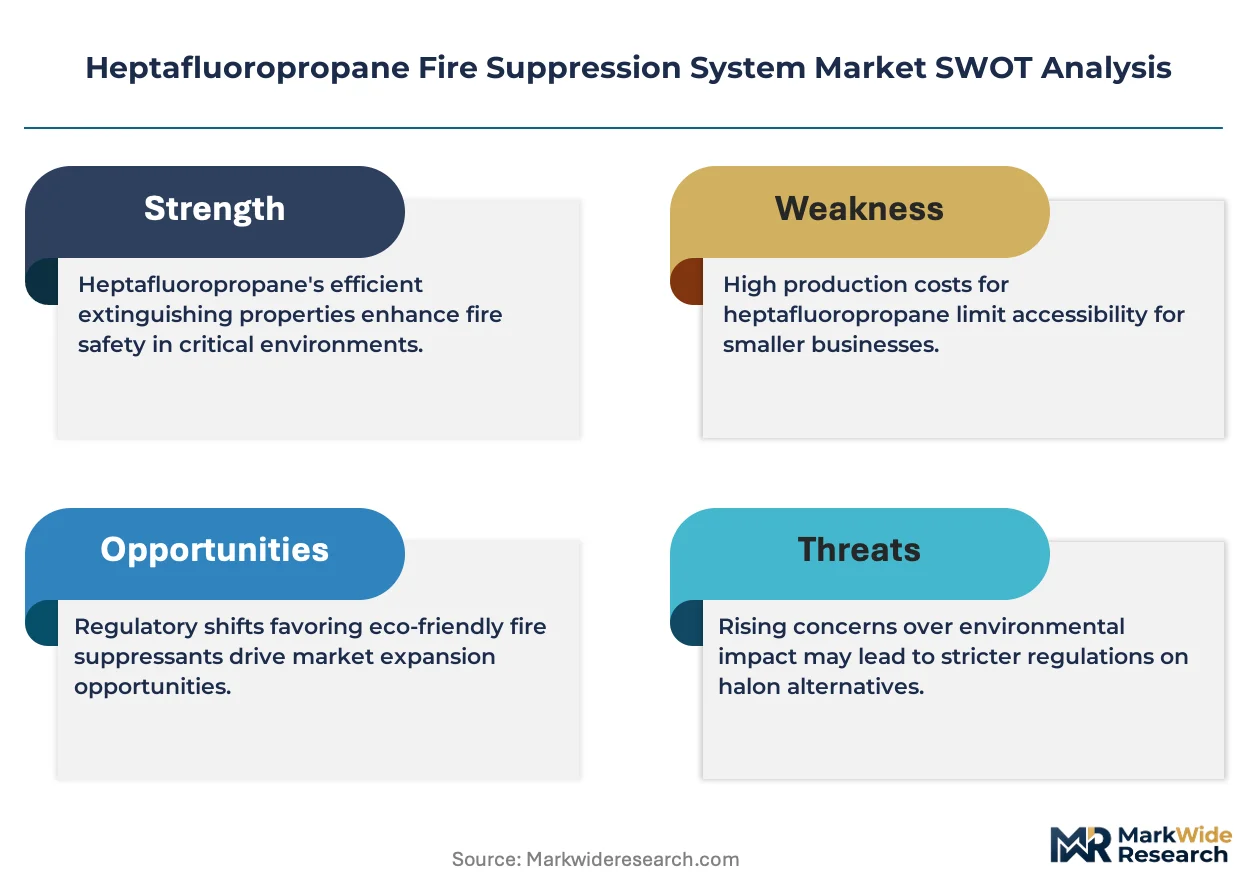
Chinese feedstock concentration is tightening global HFC-227ea availability, forcing system integrators to secure multi-year agent supply contracts before committing to large installation projects.
Growth Catalysts
- Semiconductor fabrication expansion:China's eastern coastal manufacturing corridor requires zero-residue protection for cleanroom environments, driving specification of fixed heptafluoropropane systems in new wafer fabs.
- EPA SNAP approvals:The Significant New Alternatives Policy program continues validating halocarbon-based suppression chemistry for U.S. data center deployment, sustaining agent demand against fluorine-free alternatives.
- Hyperscale data center densification:Southeast Asian facility operators prioritize clean-agent systems that enable higher server rack densities without water damage risk.
Market Restraints
- Fluorochemical feedstock volatility:Chinese specialty chemical producers control heptafluoropropane precursor supply, exposing system manufacturers to input cost spikes and allocation constraints.
- EU F-Gas phase-down schedules:The regulation constrains HFC-227ea import volumes and formulation eligibility, compressing addressable market scope in European jurisdictions.
- Fluorine-free agent substitution:Novec 1230 and inert gas systems displace heptafluoropropane in environmentally sensitive procurement specifications.
Strategic Opportunities
- Marine and offshore applications:Specialized maintenance crews and vessel operators represent underpenetrated demand for portable heptafluoropropane systems where mobility outweighs coverage scale.
- India's manufacturing corridor:Battery cell plants and electronics assembly facilities along the Delhi-Mumbai Industrial Corridor require zero-residue protection systems with limited local clean-agent infrastructure.
- NFPA 2001 compliance convergence:The standard's agent concentration and discharge performance benchmarks create specification lock-in for certified system providers across North American commercial real estate.
Industry Challenges
- Fluorochemical technician scarcity:System installation and maintenance require specialized handling certification for pressurized halocarbon agents, constraining installer network expansion.
- Legacy halon system integration:Retrofit projects face piping infrastructure incompatibility and control system synchronization complexity when upgrading to heptafluoropropane discharge mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heptafluoropropane Fire Suppression System Market |
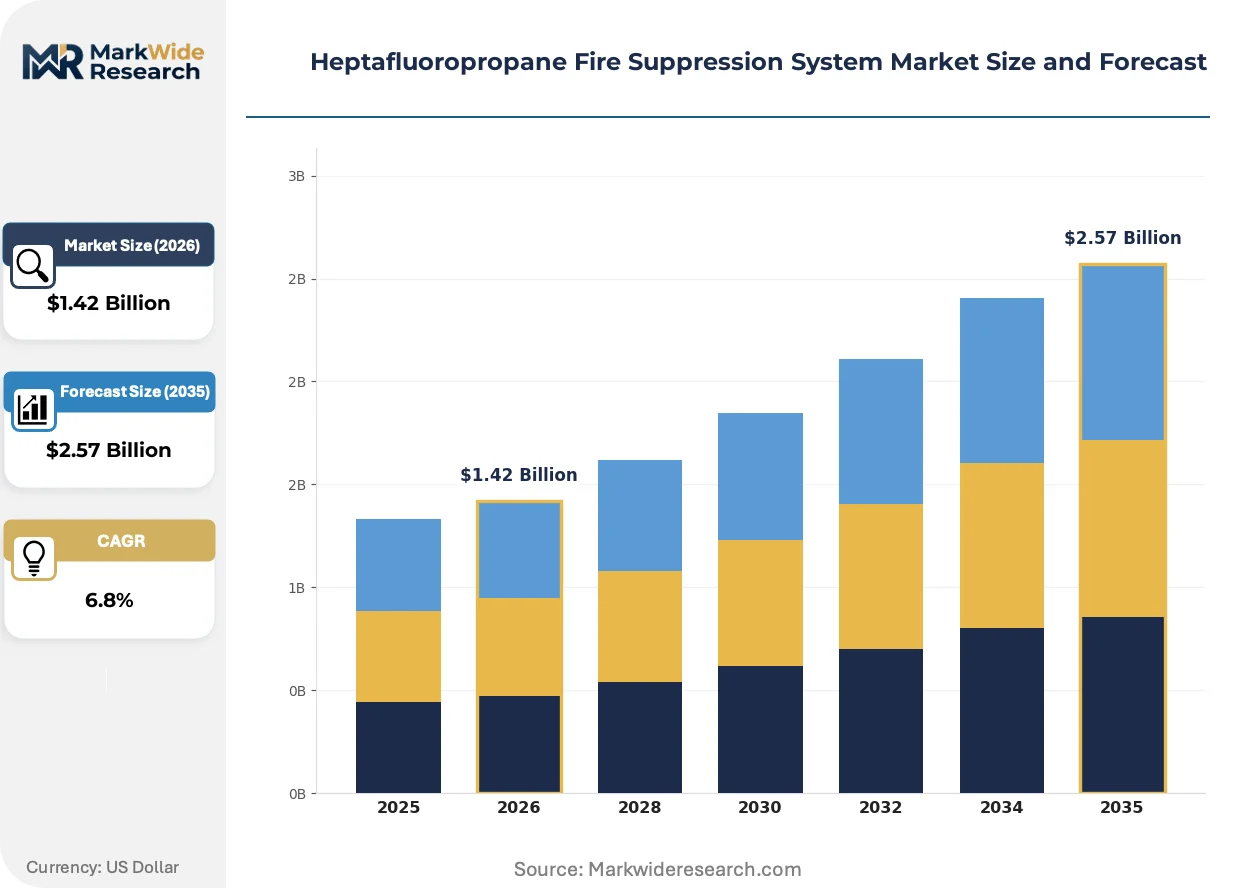
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Mobile Units, Custom Solutions Application: Data Centers, Manufacturing Facilities, Oil & Gas, Marine Vessels End User: Commercial, Industrial, Government, Residential Installation Type: New Installations, Retrofit Installations, Continuous Monitoring, System Upgrades |
| Companies Covered | Honeywell International Inc., Tyco Fire Protection Products, Kidde Fire Systems, Minimax GmbH & Co. KG, Siemens Building Technologies, Fike, Johnson Controls, Ansul, NAFFCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heptafluoropropane Fire Suppression System Market Trends and Innovations
Agent containment and monitoring technologies are reshaping system architecture, while regulatory chemistry approvals and procurement centralization compress competitive differentiation around certification compliance rather than performance claims.
Smart pressure monitoring and IoT-enabled cylinder integrity verification is consolidating maintenance workflows for heptafluoropropane installations. Data center operators in Singapore and Taiwan deploy continuous agent weight telemetry to eliminate manual inspection downtime. This technology is consolidating aftermarket service contracts into predictive maintenance platforms that displace traditional annual inspection visits.
China's MEE hydrofluorocarbon consumption baseline commitments enforce domestic production quotas that constrain export availability. The policy forces multinational system integrators to localize manufacturing or secure captive agent supply through joint ventures with Chinese feedstock producers. Semiconductor fabrication facilities in South Korea and Japan face extended procurement timelines as they navigate quota-allocation negotiations.
Centralized procurement by hyperscale cloud providers has compressed vendor selection criteria toward total-cost-of-ownership metrics and multi-site service capability. System specifications now prioritize standardized agent recharge protocols and cross-border technician dispatch networks over unit pricing. This concentration is most visible in Southeast Asian data center clusters where Microsoft, Google, and Amazon Web Services coordinate regional suppression system standards through shared engineering consultants.
Heptafluoropropane Fire Suppression System Market Segmentation
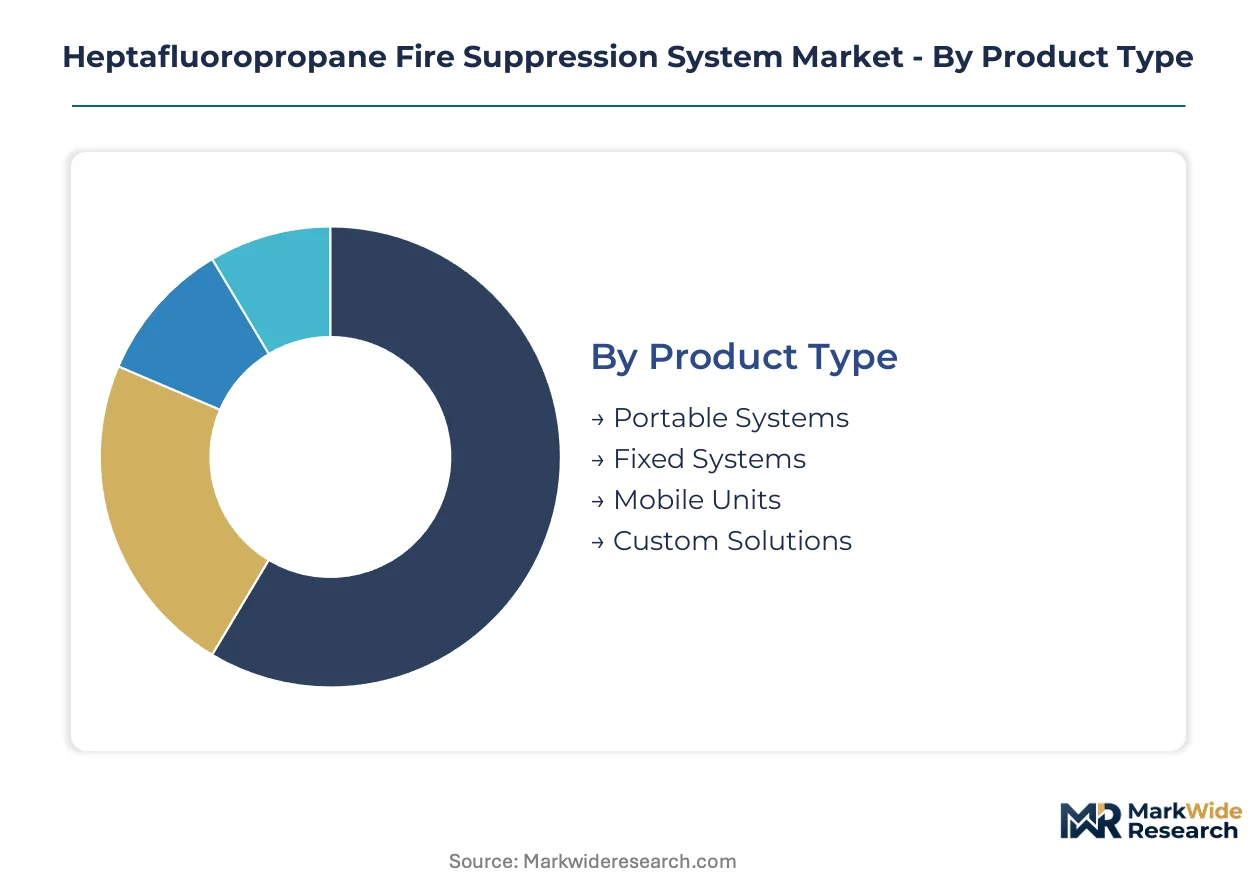
Segmentation in the heptafluoropropane fire suppression system market reveals how deployment architecture, end-use criticality, and procurement pathways shape vendor positioning. Understanding these divisions clarifies where specification power concentrates and which integration models command premium positioning.
Product Type:
Fixed systems embed permanently into building infrastructure with dedicated piping and alarm integration, while portable configurations operate as standalone units for tactical deployment. Mobile and custom variants occupy specialized niches where mobility or non-standard hazard geometries dominate procurement criteria.
- Portable Systems:Self-contained HFC-227ea cylinders with manual or automatic discharge triggers, typically 25-100 lb agent capacity. Marine maintenance crews and offshore platform operators in Singapore and Taiwan specify these for engine room hot work protection where permanent piping proves impractical.
- Fixed Systems:Engineered networks of storage cylinders, distribution piping, and nozzles integrated with building fire alarm and ventilation controls. Hyperscale data centers across China's eastern coastal corridor mandate these for server hall protection, with NFPA 2001 concentration requirements driving specification rigor.
- Mobile Units:Trailer-mounted or skid-based configurations for temporary hazard coverage during construction or maintenance shutdowns. Refinery turnarounds in Saudi Arabia and the UAE represent primary demand pockets.
- Custom Solutions:Non-standard agent storage geometries and discharge patterns for heritage buildings or irregular industrial layouts. Museums and archive facilities in Japan and South Korea commission these where structural preservation constraints override standard system templates.
Volume placements concentrate in Fixed Systems; the faster expansion belongs to Portable Systems as offshore energy and marine segments accelerate procurement.
Application:
End-use context determines agent concentration requirements, discharge timing protocols, and regulatory certification pathways. Criticality gradients from irreplaceable data assets to routine industrial hazard management create distinct specification tiers.
- Data Centers:Zero-downtime protection for server racks, power distribution units, and battery energy storage systems. Operators in Malaysia and Indonesia prioritize these systems as facility densities climb and water-based suppression risks intensify.
- Manufacturing Facilities:Cleanroom protection for semiconductor wafer fabs and lithium-ion battery cell production lines. China's eastern coastal manufacturing corridor dominates specification volumes, with MEE quota constraints complicating agent procurement timelines.
- Oil & Gas:Control room, switchgear, and turbine enclosure protection in upstream and downstream facilities. This segment sustains replacement-driven demand as halon phase-out cycles continue across mature North American and European installations.
- Marine Vessels:Engine rooms, pump rooms, and cargo holds on commercial shipping and offshore platforms. IMO SOLAS compliance mandates and classification society approvals shape vendor selection, with South Korean shipbuilders representing concentrated specification authority.
Specification authority clusters in Data Centers; Manufacturing Facilities are climbing the fastest as battery and semiconductor capacity expands across Asia-Pacific.
End User:
Procurement sophistication and total-cost-of-ownership scrutiny vary sharply across customer categories, compressing vendor margins in price-sensitive segments while enabling premium positioning where technical compliance complexity dominates.
- Commercial:Office buildings, retail complexes, and hospitality properties where code compliance and insurance certification drive selection. Property managers in India's Delhi-Mumbai Industrial Corridor increasingly specify heptafluoropropane for high-value equipment rooms.
- Industrial:Heavy manufacturing, chemical processing, and energy facilities with customized hazard analysis and engineered system designs. These buyers command the deepest technical evaluation capabilities and longest procurement cycles.
- Government:Military installations, critical infrastructure, and public facilities with security-cleared installation requirements and multi-year maintenance contracts. Defense procurement in the US and UK sustains specialized vendor relationships.
- Residential:High-net-worth properties and multi-unit developments with luxury positioning requirements. This remains a marginal segment given cost thresholds and sprinkler code alternatives.
Contract values peak in Industrial; Government is gaining share fastest as critical infrastructure protection budgets expand across NATO-aligned jurisdictions.
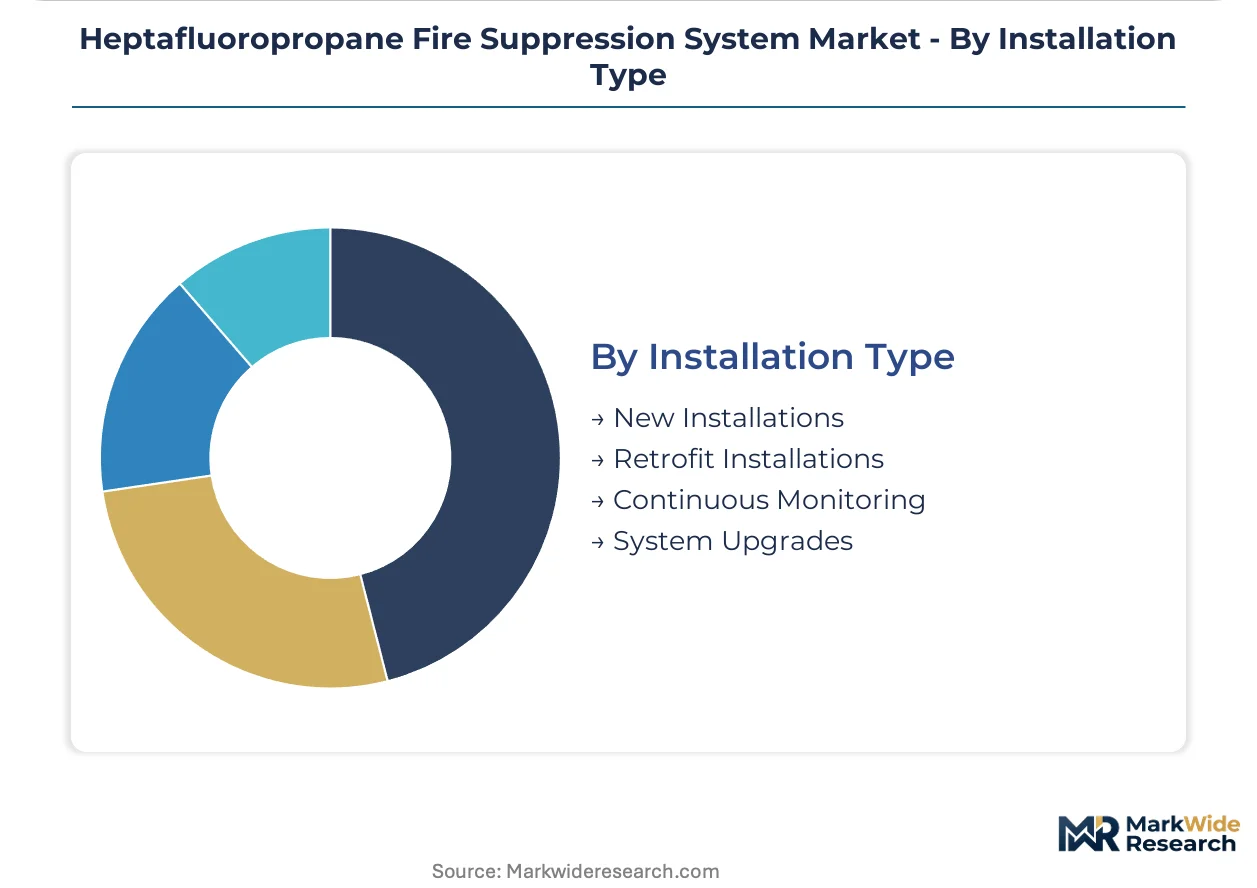
Installation Type:
Project origin—greenfield versus brownfield—shapes system architecture constraints, integration complexity, and vendor service revenue potential. Installation pathway also determines whether procurement flows through construction contractors or direct facility owner relationships.
- New Installations:Greenfield deployments with coordinated fire suppression, alarm, and HVAC design from project inception. These enable optimal agent distribution modeling and seamless control integration.
- Retrofit Installations:Brownfield upgrades replacing halon or water-based systems in operating facilities. Legacy piping incompatibility and control system synchronization dominate technical risk.
- Continuous Monitoring:IoT-enabled cylinder pressure and agent weight telemetry for predictive maintenance. Data center operators in Singapore and Taiwan deploy these to eliminate manual inspection downtime.
- System Upgrades:Capacity expansions, agent recharges, and control system modernizations for existing installations. These generate recurring aftermarket revenue for established service providers.
Project pipelines favor New Installations; Continuous Monitoring is expanding most quickly as predictive maintenance platforms displace traditional annual inspection contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fluorochemical feedstock concentration in Zhejiang and Shandong provinces anchors global HFC-227ea agent availability, forcing multinational system integrators to localize manufacturing or secure captive supply through joint ventures with domestic producers.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth sustains clean-agent system specification volumes. The EPA SNAP program validates halocarbon-based suppression chemistry for facility deployment, sustaining agent demand against fluorine-free alternatives. Microsoft and Amazon Web Services coordinate regional suppression standards through shared engineering consultants across these clusters.
China
Semiconductor fabrication expansion along the eastern coastal manufacturing corridor drives zero-residue protection demand in new wafer fabs. The MEE enforces domestic production quotas under hydrofluorocarbon consumption baseline commitments, constraining export availability and forcing procurement timeline extensions. Battery cell plants in Jiangsu and Fujian provinces require extensive fixed system installations.
Germany
Industrial automation facilities in Bavaria and Baden-Württemberg specify engineered suppression networks for cleanroom protection. The EU F-Gas Regulation phase-down schedules constrain HFC-227ea import volumes and formulation eligibility, compressing addressable market scope. Automotive battery gigafactories in Lower Saxony are accelerating procurement for zero-residue systems.
Singapore
Data center operators deploy continuous agent weight telemetry to eliminate manual inspection downtime, consolidating aftermarket service contracts into predictive maintenance platforms. The Maritime and Port Authority mandates clean-agent systems for vessel engine room protection, sustaining portable system demand. Hyperscale facilities in Tuas and Changi prioritize higher server rack densities without water damage risk.
South Korea
Semiconductor fabrication facilities in Pyeongtaek and Hwaseong face extended procurement timelines as they navigate Chinese quota-allocation negotiations for agent supply. The MFDS oversees chemical safety compliance in manufacturing environments. Shipbuilders in Busan and Ulsan represent concentrated specification authority for marine vessel applications under IMO SOLAS mandates.
Heptafluoropropane Fire Suppression System Market Competitive Landscape
Global majors compete with regional champions across feedstock access and installation network density. The market structure consolidates around vertically integrated fluorochemical heritage players and specialized fire protection engineering firms with deep channel control. Three archetypes dominate: upstream-integrated chemical conglomerates, system engineering specialists with certification authority, and regional installation contractors with local regulatory relationships. Competitive moves center on captive agent supply contracting and predictive maintenance platform deployment.
Among diversified industrial technology conglomerates, Honeywell International Inc. and Siemens Building Technologies occupy positions that exemplify scale-driven coverage across global data center and industrial verticals. Tyco Fire Protection Products anchors the specialized fire protection tier with extensive channel infrastructure. Johnson Controls and Kidde Fire Systems sit within the building technology integration segment where code compliance simplicity drives residential and light commercial selection. Minimax GmbH & Co. KG represents European engineering-focused positioning with certification-heavy industrial relationships.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Tyco Fire Protection Products |
| Kidde Fire Systems |
| Minimax GmbH & Co. KG |
| Siemens Building Technologies |
| Fike |
| Johnson Controls |
| Ansul |
| NAFFCO |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud providers' centralized procurement programs compress vendor selection toward total-cost-of-ownership metrics, forcing three-tier pricing differentiation across premium certified, standard compliant, and economy unbundled service tiers.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium system providers from commodity competitors in heptafluoropropane installations. Three-tier pricing structure across premium, standard, and economy levels reflects NFPA 2001 certification grade, agent recharge protocol standardization, and cross-border technician dispatch capability. Cost compression in economy tiers intensifies because Chinese feedstock producers constrain global HFC-227ea availability. Industrial end users demonstrate lowest price sensitivity given engineered system complexity, while commercial property managers exhibit highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
UL and FM Global certification requirements gate market access for cylinder manufacturers and system integrators, creating qualification backlogs that extend procurement timelines. Production concentrates in China, South Korea, and Germany, with feedstock chemistry anchored in Zhejiang and Shandong provinces. HFC-227ea agent, specialized pressure vessels, and IoT-enabled monitoring sensors constitute critical input dependencies. Single-source vulnerability runs through Chinese precursor supply, exposing integrators to allocation constraints and quota-driven export restrictions. Distribution runs through authorized fire protection engineering contractors with direct facility owner relationships in data center and industrial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA SNAP program classifications and EU F-Gas Regulation phase-down schedules erect regulatory moats that favor incumbents with established chemistry approvals and certification authority.
For Market Incumbents: To counter fluorine-free agent substitution threats from Novec 1230 and inert gas systems, secure captive HFC-227ea supply through joint ventures with Chinese feedstock producers and deploy predictive maintenance platforms to lock in aftermarket service contracts. Channel control across commercial and industrial installation networks remains essential for specification authority retention. For New Entrants and Emerging Players: Launch via portable system specialization targeting marine maintenance crews and offshore platform operators in Singapore and Taiwan, where mobility requirements outweigh coverage scale and incumbent fixed system dominance weakens. India's battery cell plant corridor along the Delhi-Mumbai Industrial Corridor presents the most penetrable geography given limited local clean-agent infrastructure and accelerating zero-residue protection demand. For Investors and Strategic Acquirers: The window for entry favors engineering-focused specialists with deep NFPA 2001 certification relationships and established service networks across hyperscale data center clusters. Acquisition targets should demonstrate captive agent contracting capability and cross-border technician dispatch infrastructure. Monitor EPA SNAP program chemistry approval decisions as the critical inflection signal for halocarbon-based suppression viability against fluorine-free alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Agent Supply Agreement | Joint ventures with Chinese feedstock producers in Zhejiang secure HFC-227ea allocation priority for multinational integrators facing MEE quota constraints. |
| Predictive Maintenance Platform Deployment | IoT-enabled cylinder weight telemetry consolidates aftermarket contracts for Singapore data center operators eliminating manual inspection downtime. |
| NFPA 2001 Certification Investment | UL and FM Global listing authority creates specification lock-in across North American commercial real estate and hyperscale facility procurement. |
| Marine and Offshore Specialization | IMO SOLAS compliance and classification society approvals open vessel engine room and platform hot work protection segments with limited incumbent presence. |
| India Manufacturing Corridor Expansion | Battery cell and electronics assembly facility demand along the Delhi-Mumbai Industrial Corridor requires zero-residue systems with constrained local supplier base. |
Research Methodology
Document review covered regulatory filings with EPA SNAP and EU F-Gas Regulation databases, complemented by interviews with fire protection system integrators, data center facility engineers, and Chinese specialty chemical procurement managers. Secondary validation drew from NFPA technical standards documentation, MEE hydrofluorocarbon quota disclosures, and IMO SOLAS classification society records. Bottom-up installation volume estimates triangulated against top-down agent consumption projections across the analysis window.
Segment-level outputs for fixed and portable system architectures, data center and manufacturing facility applications, and new versus retrofit installation pathways were generated through driver-based modeling. CAGRs were derived from agent demand elasticity tied to semiconductor fabrication capacity expansion and hyperscale data center densification trends. Forecast inputs incorporated MEE production quota trajectories and EPA chemistry approval timelines without year-specific anchoring.
Chinese feedstock export restriction tightening, accelerated EU F-Gas phase-down implementation, and breakthrough fluorine-free agent performance parity are the dominant revision risks to modeled agent demand and system placement volumes. A model refresh is warranted upon material change in EPA SNAP program halocarbon approval status or MEE hydrofluorocarbon consumption baseline enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Fire Rated Cables Market