
 Fire Protection Systems Market | 2026-2036
Fire Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Protection Systems Market Intelligence
Data center operators is redrawing procurement priorities across the fire protection systems landscape. Johnson Controls leverages its building automation integration to capture premium retrofit contracts in hyperscale facilities. Siemens AG anchors European demand through its Sinorix suppression platform certified to stringent clean-agent protocols. Honeywell International competes on sensor density and software analytics, extending its footprint in intelligent detection networks.
Fire protection systems encompass active and passive technologies engineered to detect, suppress, or contain combustion events across commercial, industrial, and residential environments; active systems deploy water, foam, gas, or chemical agents through networked sprinklers and deluge equipment, while passive systems integrate fire-resistant materials, compartmentation barriers, and structural intumescent coatings to inhibit flame propagation. Smoke detectors and fire alarms dominate installed base volume, though IoT-based systems represent the fastest-expanding margin pool as connectivity protocols enable predictive maintenance and remote monitoring. Fire suppression commands the highest capital intensity per project, particularly in critical infrastructure segments where gaseous clean-agent systems replace water-based alternatives to protect sensitive electronics.
The National Fire Protection Association shapes product certification and installation protocols across North America, while the EU Construction Products Regulation mandates CE marking for passive fire protection materials entering European markets. China's Ministry of Emergency Management enforces GB standards for building fire safety that drive replacement cycles in aging commercial stock. Stakeholders must monitor evolving refrigerant regulations under the F-Gas Regulation, as suppression agent chemistry faces phase-down pressures that could disrupt existing system architectures and service revenue models.
Market Dynamics
The transition from water-based suppression to gaseous clean-agent systems in hyperscale data centers is compressing traditional sprinkler margins while elevating certification requirements for specialized installers. This technology substitution cascades through specification chains, retrofit timelines, and service revenue models.
Growth Catalysts
- NFPA 75 compliance mandates:US data center operators face intensified inspection schedules for clean-agent system integrity, forcing replacement of aging halon banks with modern alternatives.
- Hyperscale facility construction:Cloud computing infrastructure in Northern Virginia, Frankfurt, and Singapore generates concentrated demand for integrated detection-suppression architectures.
- EN 12094 certification expansion:European manufacturers accelerate product line upgrades to capture CE-marked market access as the EU Construction Products Regulation tightens material traceability.
Market Restraints
- Fluorinated gas phase-down:The EU F-Gas Regulation restricts HFC-based suppression agents, forcing chemistry transitions that strand existing installed bases and service contracts.
- Specialized installer scarcity:Clean-agent system commissioning requires certified technicians concentrated in Germany, Japan, and the United States, creating bottlenecked deployment capacity.
- Water mist substitution ceiling:Mechanical damage risk to precision electronics limits water mist penetration in semiconductor fabrication and financial trading floors.
Strategic Opportunities
- India commercial stock modernization:Aging office buildings in Mumbai and Bangalore face GB standard enforcement that will accelerate detector replacement cycles through 2030.
- Predictive maintenance convergence:IoT sensor networks married to building management systems enable remote monitoring contracts that capture recurring revenue from industrial facilities.
- Green building certification tailwinds:LEED and BREEAM point systems reward advanced suppression technologies, tilting specification toward clean-agent solutions in premium commercial developments.
Industry Challenges
- Cross-protocol integration complexity:Facility operators struggle to synchronize proprietary detection networks with third-party suppression actuators, delaying commissioning timelines.
- Certification timeline compression:UL and FM Global testing queues for novel suppression chemistries extend product launch windows, advantaging incumbents with approved portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Protection Systems Market |
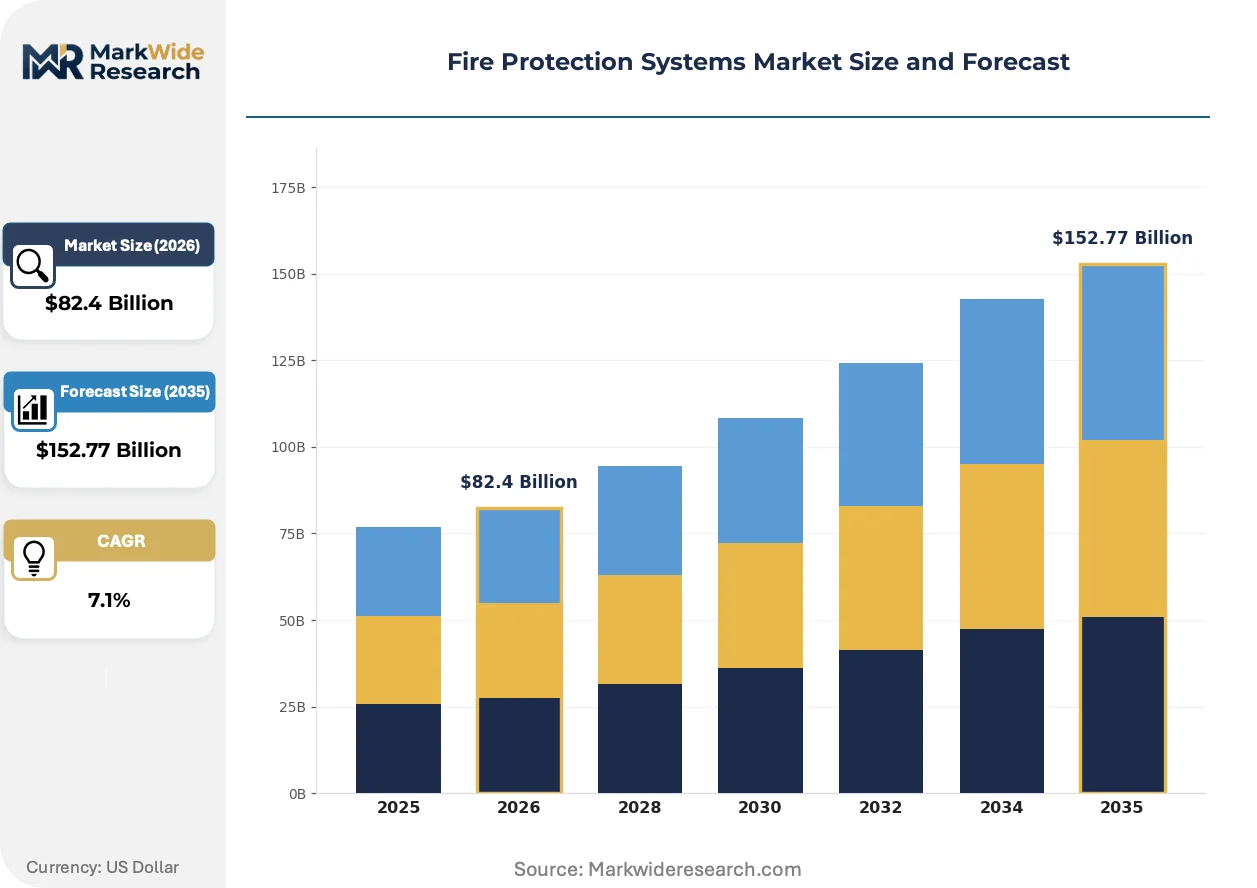
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $152.77 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Alarms, Fire Suppression, Fire Extinguishers, Smoke Detectors Technology: Active Systems, Passive Systems, Hybrid Systems, IoT-based Systems End User: Manufacturing, Healthcare, Residential, Commercial Installation Type: New Installation, Retrofit, Maintenance, Inspection |
| Companies Covered | Robert Bosch GmbH, Carrier Global Corporation, Johnson Controls, Gentex Corporation, Hochiki Corporation, Honeywell International, Halma plc, Minimax Viking Group, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Protection Systems Market Strategic Shifts & Innovations
Intelligent detection architectures are displacing conventional point-source sensors as connectivity protocols enable centralized monitoring and predictive intervention. This shift reconfigures value capture toward software analytics and remote service platforms.
Aerosol-based suppression chemistry is fragmenting the clean-agent landscape as an alternative to fluorinated gases. Data center operators in Singapore and the Netherlands pilot potassium-based condensed aerosol systems for occupied-space protection. The technology is fragmenting procurement specifications, forcing engineering consultants to develop new hazard analysis protocols and complicating insurer risk assessment frameworks.
The EU F-Gas Regulation accelerates agent chemistry transitions across European industrial facilities. Manufacturers reformulate blends to meet GWP thresholds, while end-users face stranded asset risk in existing halocarbon banks. German chemical facilities and Dutch semiconductor plants confront the steepest compliance curves, driving demand for reclamation services and alternative agent validation.
Integrated service contracts displace equipment-only procurement in critical infrastructure segments. Hyperscale operators in Northern Virginia and Frankfurt bundle detection hardware with decade-long maintenance and monitoring agreements. This bundling concentrates vendor selection authority with procurement teams rather than engineering departments, compressing supplier margins while extending contract durations and switching costs.
Fire Protection Systems Market Segmentation

Fire protection systems fragment across four distinct category axes, each with divergent margin profiles and specification dynamics. Procurement teams weight capital intensity against lifecycle service revenue when allocating budgets across product categories.
Product Type:
Margin pools concentrate in suppression hardware and intelligent detection networks, while commoditized equipment faces pricing compression.
- Fire Alarms:Audible and visual notification appliances integrated with control panels for occupant evacuation. Demand clusters in US healthcare facilities undergoing Joint Commission compliance upgrades, where addressable loop technology replaces conventional zone-based architectures.
- Fire Suppression:Gaseous clean-agent and water-based systems engineered for hazard-specific extinguishment. Hyperscale data centers in Northern Virginia and Frankfurt drive specification toward FM-200 and Novec 1230 alternatives as halon banks reach end-of-life.
- Fire Extinguishers:Portable handheld units containing dry chemical, CO2, or foam agents for localized response. Commercial office retrofits in Mumbai and Bangalore generate replacement volume under tightened GB standard enforcement.
- Smoke Detectors:Ionization and photoelectric sensors for early combustion detection. Residential markets in Germany and Japan absorb volume through mandatory installation laws in multi-family housing.
Fire alarms hold installed capacity. Fire suppression is rotating up the share rankings.
Technology:
Revenue concentration shifts toward connected architectures that bundle hardware with recurring monitoring contracts.
- Active Systems:Sprinkler, deluge, and gaseous discharge equipment that physically suppress combustion events. Semiconductor fabrication plants in the Netherlands and Singapore specify clean-agent alternatives to protect wafer processing equipment from water damage.
- Passive Systems:Fire-resistant materials, compartmentation barriers, and intumescent coatings that inhibit flame propagation. High-rise commercial developments in Dubai and London integrate cementitious spray and board systems to satisfy extended fire resistance ratings.
- Hybrid Systems:Combined active-passive architectures with coordinated detection and containment. Critical infrastructure projects in Germany deploy integrated solutions where suppression triggers align with smoke evacuation dampers.
- IoT-based Systems:Sensor networks with cloud connectivity enabling predictive maintenance and remote diagnostics. Industrial facilities in the United States adopt these platforms to reduce inspection labor costs and accelerate alarm verification.
Active systems anchor current procurement volume. IoT-based systems are climbing the fastest as connectivity protocols mature.
End User:
Application-specific hazard profiles dictate specification complexity and service contract duration.
- Manufacturing:Heavy industrial environments with flammable liquid and dust explosion risks. Chemical processing facilities in Germany face F-Gas Regulation compliance deadlines that accelerate clean-agent system replacement cycles.
- Healthcare:Patient-occupied spaces requiring notification systems with intelligible voice evacuation. US hospital construction in Texas and Florida drives demand for addressable networks with redundant signaling paths.
- Residential:Single and multi-family dwellings with code-mandated detection requirements. India's urban housing stock modernization in Bangalore and Mumbai absorbs photoelectric detector volume as GB standards tighten.
- Commercial:Office, retail, and hospitality properties with mixed occupancy patterns. Premium developments pursuing LEED certification in Singapore and Frankfurt specify advanced suppression technologies for credit accumulation.
Commercial applications dominate retrofit activity. Manufacturing is gaining share fastest as process safety regulations intensify.
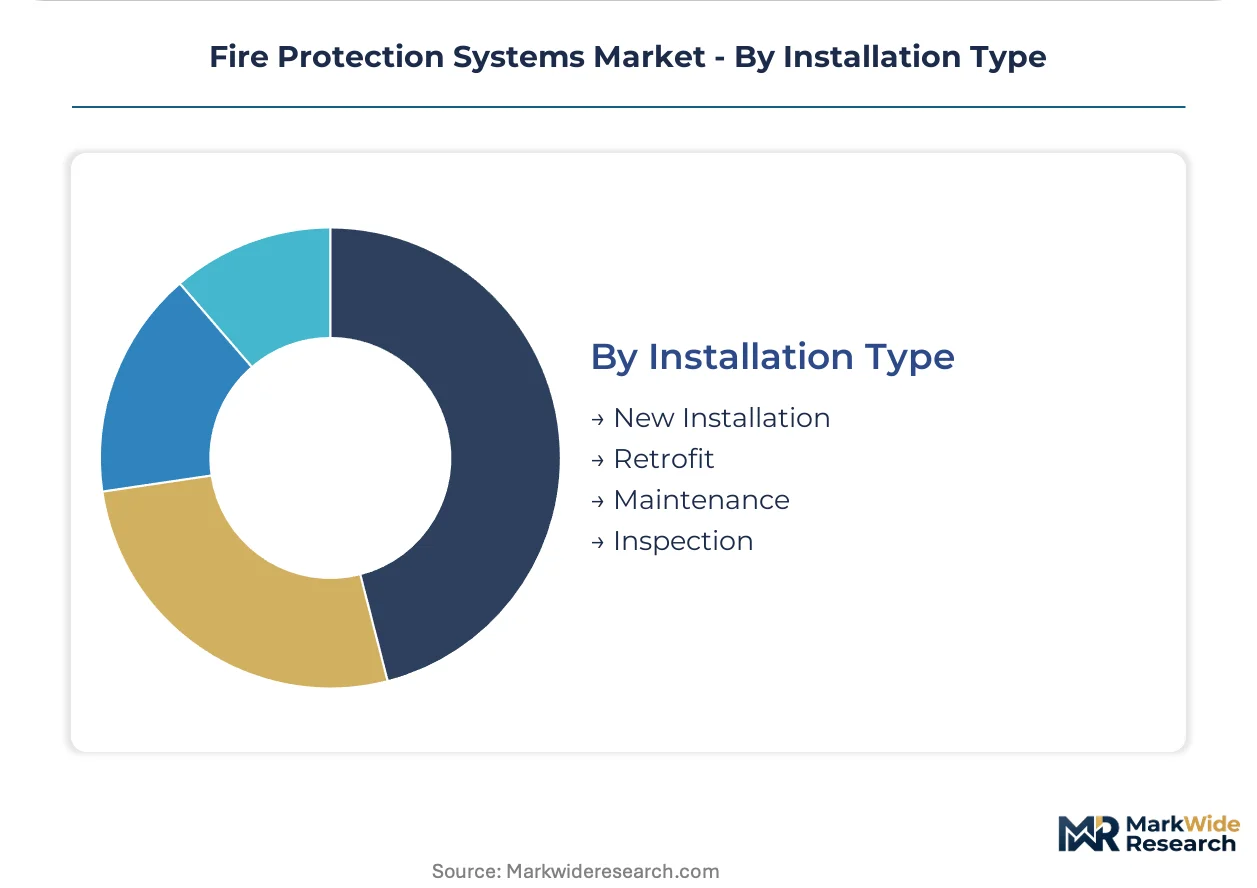
Installation Type:
Revenue stability increases with service attachment, shifting vendor economics from equipment margins to recurring contracts.
- New Installation:Greenfield system deployment in construction projects. Hyperscale data center builds in Northern Virginia concentrate demand for integrated detection-suppression architectures with decade-long service bundling.
- Retrofit:Replacement and upgrade of aging systems in existing structures. Aging commercial stock in Frankfurt and London drives sprinkler modernization as insurers impose stricter risk assessment criteria.
- Maintenance:Scheduled inspection, testing, and component replacement services. US facilities face NFPA 25 and NFPA 72 inspection mandates that create recurring revenue pools for certified service providers.
- Inspection:Regulatory compliance verification and system integrity documentation. German industrial facilities require documented EN 12094 certification maintenance that sustains third-party inspection demand.
New installation captures project value. Maintenance is rotating up the share rankings as installed bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northern Virginia data center corridor anchors United States demand through hyperscale construction pipelines. Frankfurt's Rhine-Main fiber hub concentrates European procurement for integrated suppression architectures. Singapore's submarine cable landing stations drive clean-agent specification across Southeast Asian facilities.
United States
Hyperscale data center construction in Loudoun County and Prince William County generates concentrated demand for FM-200 and Novec 1230 systems. NFPA 75 compliance mandates intensify inspection schedules for clean-agent integrity across legacy halon banks. Northern Virginia operators bundle decade-long maintenance contracts with detection hardware procurement.
Germany
Chemical processing facilities in Ludwigshafen and Leverkusen face steep F-Gas Regulation compliance curves for HFC phase-down. EN 12094 certification requirements tighten material traceability for CE-marked suppression equipment. Frankfurt's banking sector specifies integrated detection-suppression architectures for trading floor protection.
China
GB standard enforcement accelerates detector replacement cycles in aging Shanghai and Beijing commercial stock. The Ministry of Emergency Management mandates building fire safety upgrades across tier-one cities. Yangtze River Delta data center clusters pilot aerosol-based suppression for occupied-space electronics protection.
India
Mumbai and Bangalore office retrofits absorb photoelectric detector volume under tightened GB standard enforcement. The Bureau of Indian Standards drives certification alignment for imported suppression equipment. Maharashtra's pharmaceutical manufacturing corridors specify clean-agent systems for solvent handling areas.
Singapore
Tuas data center precinct construction concentrates demand for gaseous suppression with minimal residue. The country's national fire safety regulator enforces stringent commissioning protocols for critical infrastructure. Marina Bay financial district operators pilot potassium-based condensed aerosol systems for server room protection.
Fire Protection Systems Market Key Industry Players
Listed leaders compete with private specialists across certification capacity and service contract duration. The vendor base clusters around three tiers: integrated building automation conglomerates, standalone suppression specialists, and regional installation contractors. Strategic differentiation hinges on UL/FM Global pre-approval portfolios and captive technician certification networks. Consolidation pressure concentrates among mid-scale European fabricators facing F-Gas transition costs.
Among Germany-based conglomerates, Siemens AG occupies a position exemplifying the integrated automation archetype through its Sinorix platform certification. Johnson Controls and Honeywell International represent the North American tier where sensor density and software analytics anchor competitive positioning. Hochiki Corporation and Halma plc exemplify specialist positioning across Asian and European detection segments respectively.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Carrier Global Corporation |
| Johnson Controls |
| Gentex Corporation |
| Hochiki Corporation |
| Honeywell International |
| Halma plc |
| Minimax Viking Group |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Scale economies in gaseous agent manufacturing concentrate pricing power among German and US chemical conglomerates, compressing margin floors for regional system integrators while elevating certification premiums for specialized installers. This concentration cascades through specification chains, where NFPA 75 and EN 12094 compliance tiers separate premium clean-agent architectures from commoditized water-based alternatives.
Pricing Analysis
Volume-discount tiering structures dominate procurement for hyperscale data center operators, with FM-200 and Novec 1230 systems commanding three-tier pricing stratification across premium certified-installer, standard regional-fabricator, and economy maintenance-only bundles. Price differentiation hinges on UL/FM Global pre-approval status and captive technician certification networks, with German and Japanese installers extracting premiums for EN 12094 commissioning. Cost compression in water-based sprinkler segments intensifies as Chinese manufacturers expand export capacity, while semiconductor fabrication and financial trading floors exhibit lowest price sensitivity due to electronics damage risk.
Supply Chain Analysis
China and Germany anchor global production of fluorinated suppression agents and precision detection sensors, with the United States concentrating clean-agent system integration for critical infrastructure. Raw material flows draw from specialty chemical feedstocks, rare-earth sensor components, and intumescent coating minerals, creating dependency on South African platinum group metals for catalytic detector elements. Single-source vulnerability concentrates in HFC-227ea and FK-5-1-12 agent supply, where EU F-Gas Regulation phase-downs threaten stranded inventory. Distribution runs through certified installer networks rather than open wholesale channels, locking end-users into geographic service territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire protection systems sit in early-cycle expansion as IoT-enabled predictive maintenance penetrates industrial facilities and data center construction accelerates clean-agent specification. EN 12094 certification expansion and F-Gas chemistry transitions create temporary supply bottlenecks that reward prepared participants.
For Market Incumbents: Compound certification portfolio depth to capture decade-long service bundling contracts from hyperscale operators in Northern Virginia and Frankfurt. Defend against aerosol-based suppression substitution by accelerating Novec 1230 reclamation services and backward integration into agent chemistry. Prioritize captive technician training networks in Germany, Japan, and the United States to bottleneck competitor deployment capacity. For New Entrants and Emerging Players: Predictive maintenance software layers represent the most penetrable white-space, as incumbent hardware vendors under-serve remote diagnostics for aging sprinkler installed bases in India and Southeast Asia. Target Mumbai and Bangalore commercial retrofits with GB-standard-aligned detector platforms bundled with cloud monitoring subscriptions. Pursue acquisition of regional inspection contractors to shortcut certification timelines and establish immediate service revenue. For Investors and Strategic Acquirers: Specialist clean-agent fabricators with EN 12094 pre-approval portfolios and established reclamation infrastructure represent the priority acquisition archetype, positioned to capture F-Gas transition spending across European chemical facilities. Long-term viability centers on chemistry-agnostic system architectures that accommodate regulatory phase-downs without full replacement. Monitor EU HFC quota auction prices as the inflection signal for agent cost trajectories and stranded asset risk timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | EN 12094 and UL pre-approvals unlock hyperscale data center procurement in Northern Virginia and Frankfurt. |
| Backward Integration into Agent Chemistry | In-house FK-5-1-12 formulation insulates margins from EU F-Gas quota compression and supply disruption. |
| Predictive Maintenance Platform Launch | IoT sensor networks with cloud analytics capture recurring revenue from US industrial facility inspection mandates. |
| Regional Installer Network Acquisition | Certified technician capacity in Germany and Japan bottlenecks competitor deployment and extends contract duration. |
| Aerosol Suppression Pilot Programs | Potassium-based condensed aerosol validation in Singapore data centers diversifies chemistry exposure beyond fluorinated gases. |
Research Approach
Operator-level perspectives from data center facility managers, fire protection system specifiers, certified installation contractors, and industrial safety officers anchored the qualitative base. Primary interviews combined with secondary validation against NFPA technical committee filings, EU Construction Products Regulation documentation, SEC 10-K disclosures from listed building automation conglomerates, and Chinese GB standard enforcement bulletins. Bottom-up project pipeline tracking across Northern Virginia, Frankfurt, and Singapore triangulated against top-down chemical agent production estimates.
Sensitivity analysis frameworks tested agent chemistry transition timelines, hyperscale construction cadence, and certification backlog durations across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-use hazard profile, installation category, and regional regulatory cluster. CAGRs derived from weighted average of agent volume forecasts, system unit shipments, and service contract attach rates, with cross-referencing to F-Gas quota allocation trajectories and data center power capacity announcements.
Underlying assumptions cover EN 12094 certification expansion pacing, F-Gas phase-down compliance curves, and IoT protocol standardization, with deviation risk concentrated in aerosol suppression technology validation and Chinese GB enforcement intensity. Forecasts reflect these conditions with explicit scenario branches for accelerated chemistry substitution. Recalibration cycles align with material shifts in EU quota auctions, NFPA code revision cycles, and hyperscale operator procurement bundling practices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Firefighting Hose Market