
 Cryoglobulinemia Treatment Market | 2026-2036
Cryoglobulinemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cryoglobulinemia Treatment Market Outlook
Precision biologics manufacturing is rewriting therapeutic development pathways for cryoglobulinemia. F. Hoffmann-La Roche Ltd leverages its monoclonal antibody infrastructure to sustain leadership in targeted immunotherapy. GlaxoSmithKline plc anchors its position through deep R&D investment in autoimmune modulation, while Pfizer Inc. competes via broad commercial distribution across hospital networks.
Cryoglobulinemia treatment addresses abnormal immunoglobulin precipitation at low temperatures, primarily through monoclonal antibodies that selectively deplete B-cell populations and plasma exchange procedures that physically remove circulating cryoglobulins from patient bloodstreams. The indication landscape reveals Type II and mixed cryoglobulinemia as the most commercially active segments, driven by their association with hepatitis C and autoimmune comorbidities. Monoclonal antibodies command the dominant product category due to superior efficacy in refractory cases, while intravenous delivery maintains primacy despite growing subcutaneous formulation development.
FDA biologics licensing requirements, EMA orphan drug frameworks, and Japan's PMDA regenerative medicine pathways collectively elevate clinical evidence standards and prolong development timelines. These regulatory structures channel investment toward larger sponsors with established pharmacovigilance systems and restrict market entry for emerging developers. Stakeholders must weigh biosimilar preparedness against novel mechanism exploration as patent cliffs approach for established monoclonal therapies.
Market Dynamics
Precision biologics manufacturing is compressing development timelines while elevating evidence requirements for cryoglobulinemia therapeutics. FDA biologics licensing pathways and EMA orphan drug frameworks now demand extensive pharmacovigilance infrastructure that favors established sponsors with integrated manufacturing capabilities.
Growth Catalysts
- EMA Orphan Drug Incentives:Extended market exclusivity provisions accelerate investment in rare autoimmune indications, channeling R&D toward cryoglobulinemia subtypes with unmet need.
- Hepatitis C Eradication Programs:Declining HCV prevalence in developed markets is shifting treatment focus toward idiopathic and lymphoproliferative-associated cryoglobulinemia, expanding addressable patient pools.
- Subcutaneous Formulation Advances:Self-administration technologies reduce infusion center dependency, opening specialty clinic and home care channels previously inaccessible to intravenous therapies.
Market Restraints
- Plasma-Derived Input Volatility:Fractionation capacity constraints and donor pool limitations create supply uncertainty for plasma exchange procedures and immunoglobulin adjunct therapies.
- PMDA Regenerative Medicine Pathway Complexity:Japan's stringent cell and gene therapy frameworks prolong approval timelines for novel mechanism biologics, delaying commercial entry in a high-value market.
- Monoclonal Antibody Manufacturing Concentration:Contract manufacturing organization capacity for mammalian cell culture concentrates among three dominant suppliers, creating single-source vulnerability for emerging developers.
Strategic Opportunities
- German Reference Pricing Gaps:AMNOG assessment procedures for orphan indications create pricing latitude for therapies demonstrating mortality benefit in mixed cryoglobulinemia.
- AI-Driven Patient Stratification:Machine learning integration with cryoglobulin typing assays enables predictive response modeling, supporting value-based contracting with payers.
- Direct-to-Specialist Digital Platforms:Telemedicine infrastructure bypasses primary care bottlenecks, accelerating diagnosis in underpenetrated rural United States markets.
Industry Challenges
- Immunogenicity Assessment Expertise Scarcity:Anti-drug antibody testing and neutralizing antibody characterization require specialized bioanalytical capabilities that outpace current workforce training pipelines.
- Cold Chain Integrity at Last Mile:Temperature-sensitive biologics distribution to dispersed rheumatology practices demands infrastructure investment that erodes margin in low-volume territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryoglobulinemia Treatment Market |
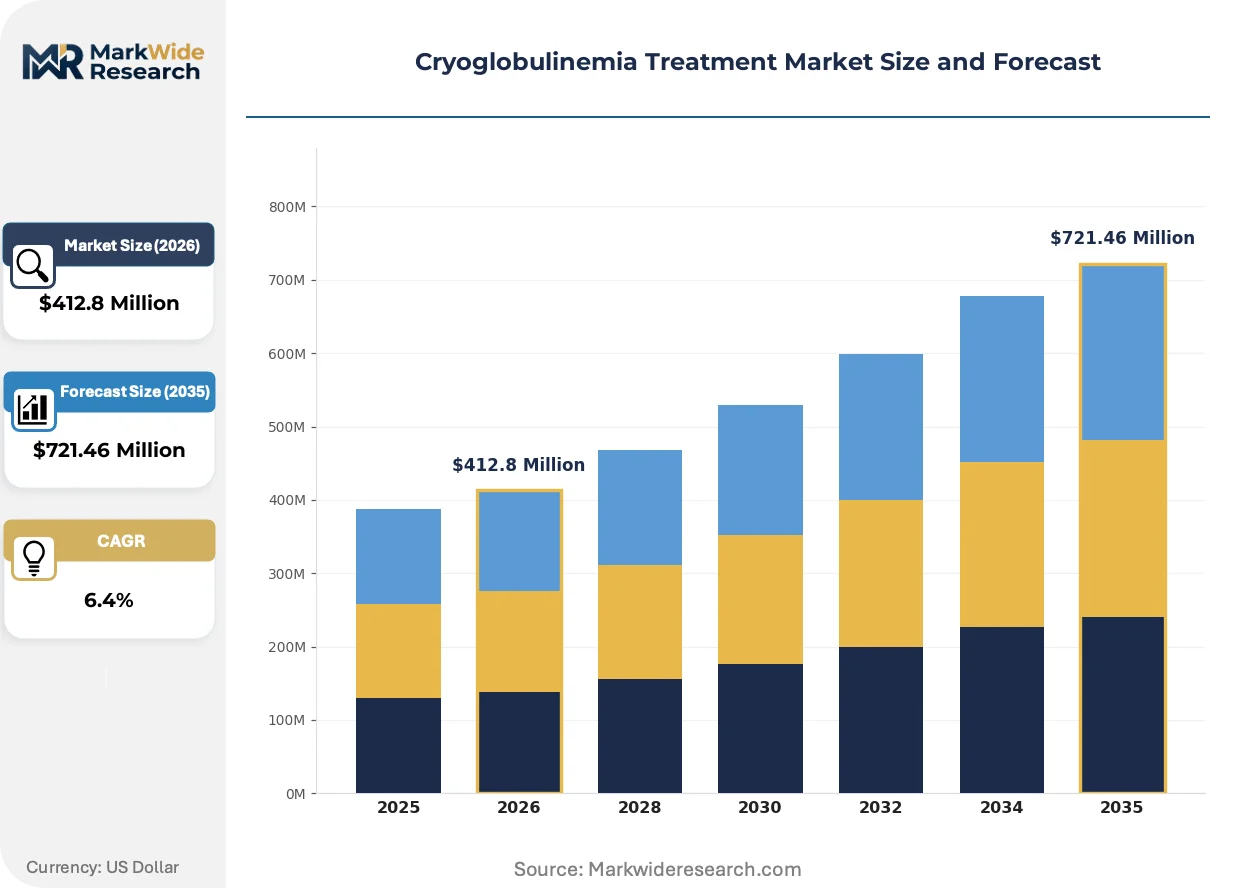
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $721.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Immunosuppressants, Plasma Exchange Indication: Type I Cryoglobulinemia, Type II Cryoglobulinemia, Type III Cryoglobulinemia, Mixed Cryoglobulinemia Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Specialty Clinics, Homecare, Research Institutions |
| Companies Covered | GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd, Pfizer Inc., Merck Sharp & Dohme Corp., Apotex Inc., Emcure Pharmaceuticals, Medimetriks Pharmaceuticals Inc., Asahi Kasei Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryoglobulinemia Treatment Market Strategic Shifts
Therapeutic modalities for cryoglobulinemia are fragmenting across mechanism classes as precision immunology advances. Convergence of B-cell depletion science with personalized dosing algorithms is compressing the gap between clinical trial endpoints and real-world effectiveness.
Next-generation B-cell depleting agents are migrating from rituximab-originator dominance toward bioengineered alternatives with enhanced antibody-dependent cellular cytotoxicity. Academic medical centers in the United States and Germany are piloting these constructs in refractory Type II cohorts. The shift is enabling mechanism-based patient stratification that separates rapid responders from prolonged treatment cycles.
REACH authorization requirements for novel biologics are forcing early-stage developers to integrate environmental risk assessment into manufacturing design. EMA's extended guidance on persistent organic pollutant traceability now applies to monoclonal antibody production solvents. European sponsors are responding by retrofitting purification processes ahead of clinical Phase III initiation.
Specialty pharmacy consolidation is altering how cryoglobulinemia therapies reach patients. Large infusion center networks are displacing hospital-based administration for stable maintenance regimens, particularly in United States metropolitan corridors. This channel migration concentrates purchasing leverage among three dominant distributors, compressing net pricing for manufacturers while expanding patient access in previously underserved Texas and Florida sub-markets.
Cryoglobulinemia Treatment Market Segmentation
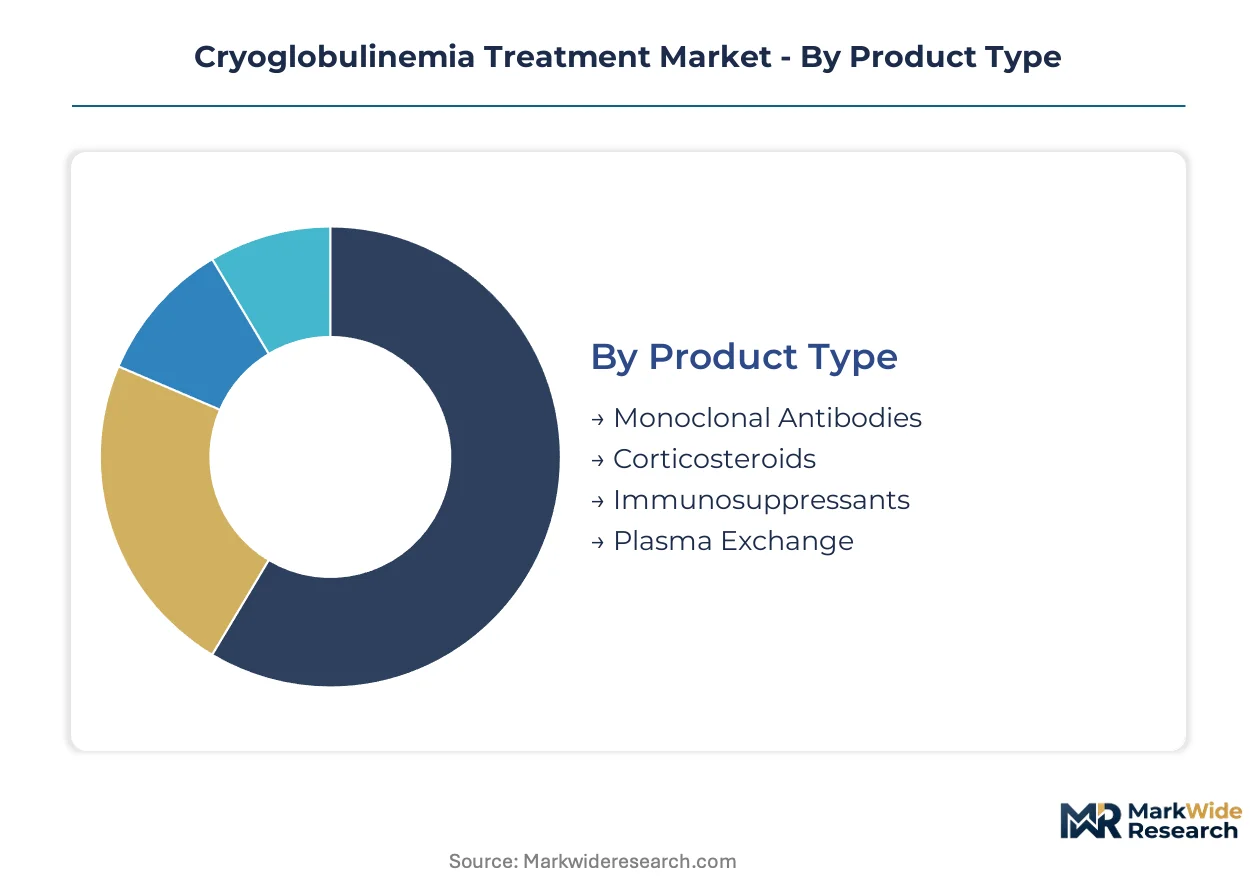
Therapeutic complexity in cryoglobulinemia demands precise segment targeting. Patient stratification by cryoglobulin type, comorbidity profile, and access infrastructure determines both clinical outcomes and commercial viability across treatment modalities.
Product Type:
After-sales service intensity varies sharply across product categories, with biologics requiring specialized cold chain maintenance and immunogenicity monitoring that oral agents do not demand.
- Monoclonal Antibodies:Engineered immunoglobulins selectively deplete B-cell populations through complement-dependent cytotoxicity. Demand concentrates in United States academic medical centers and German university hospitals managing refractory Type II cases with hepatitis C clearance failure. Rituximab-originator and bioengineered alternatives dominate formulary placement where prior authorization infrastructure supports high-cost biologic access.
- Corticosteroids:Systemic glucocorticoids suppress inflammatory cascades and vascular permeability in acute cryoglobulinemic vasculitis flares. Volume leadership sits with oral prednisone in Japan's rheumatology practices and United States community hospital emergency departments, driven by immediate availability and payer preference for generic substitution.
- Immunosuppressants:Cyclophosphamide and azathioprine provide steroid-sparing alternatives in lymphoproliferative-associated disease.
- Plasma Exchange:Extracorporeal removal of circulating cryoglobulins addresses hyperviscosity emergencies and rapidly progressive renal involvement.
Monoclonal antibodies hold the largest share; momentum sits with plasma exchange as rescue therapy protocols expand.
Indication:
Cost tier stratification separates maintenance therapies for indolent presentations from intensive interventions for organ-threatening complications.
- Type II Cryoglobulinemia:Monoclonal IgM rheumatoid factor complexes drive systemic vasculitis with predilection for skin, peripheral nerves, and kidneys. United States hepatology and rheumatology co-management models concentrate demand where hepatitis C eradication has failed or autoimmune etiology predominates.
- Mixed Cryoglobulinemia:Polyclonal IgG with monoclonal IgM components produces the most clinically heterogeneous presentation. German nephrology centers and Japanese vascular medicine departments drive procedure volume for renal-limited and cutaneous-predominant variants respectively.
- Type I Cryoglobulinemia:Monoclonal IgG or IgM paraproteinemias associate with Waldenström macroglobulinemia and multiple myeloma.
- Type III Cryoglobulinemia:Polyclonal immune complexes typically follow connective tissue disease or infection.
Mixed cryoglobulinemia holds the largest share; Type II is expanding most quickly as diagnostic specificity improves.
Delivery Mode:
Volume concentration follows administration infrastructure, with intravenous dependence in hospital settings yielding to subcutaneous and oral migration where patient stability permits.
- Intravenous:Infusion center administration ensures bioavailability for large-molecule biologics and enables rapid intervention in acute presentations. United States metropolitan hospital networks and German ambulatory care centers maintain dominant capacity for rituximab and immunoglobulin delivery.
- Subcutaneous:Self-administration formulations reduce facility dependency and enable home-based maintenance. Japanese home nursing infrastructure and United States specialty pharmacy networks are piloting subcutaneous rituximab in stable maintenance populations.
- Oral:Corticosteroid and immunosuppressant tablets dominate outpatient prescribing.
- Intramuscular:Depot formulations provide sustained corticosteroid release in select maintenance scenarios.
Intravenous holds the largest share; subcutaneous is gaining share fastest as formulation technology matures.
End User:
Customer type determines purchasing authority, with hospital pharmacy and therapeutics committees controlling biologic access while specialty clinics exercise greater autonomy in procedure selection.
- Specialty Clinics:Rheumatology, nephrology, and hepatology-focused practices concentrate disease-specific expertise and manage complex case portfolios. United States multi-specialty group practices and German university-affiliated outpatient centers drive monoclonal antibody demand through prior authorization navigation capabilities.
- Hospitals:Inpatient and emergency departments handle acute vasculitis flares, hyperviscosity crises, and plasma exchange procedures. Japanese tertiary centers and United States safety-net hospitals anchor procedure volume where multidisciplinary coordination is essential.
- Homecare:Subcutaneous administration and telemedicine monitoring enable stable patient maintenance.
- Research Institutions:Academic medical centers conduct mechanistic studies and early-phase trials.
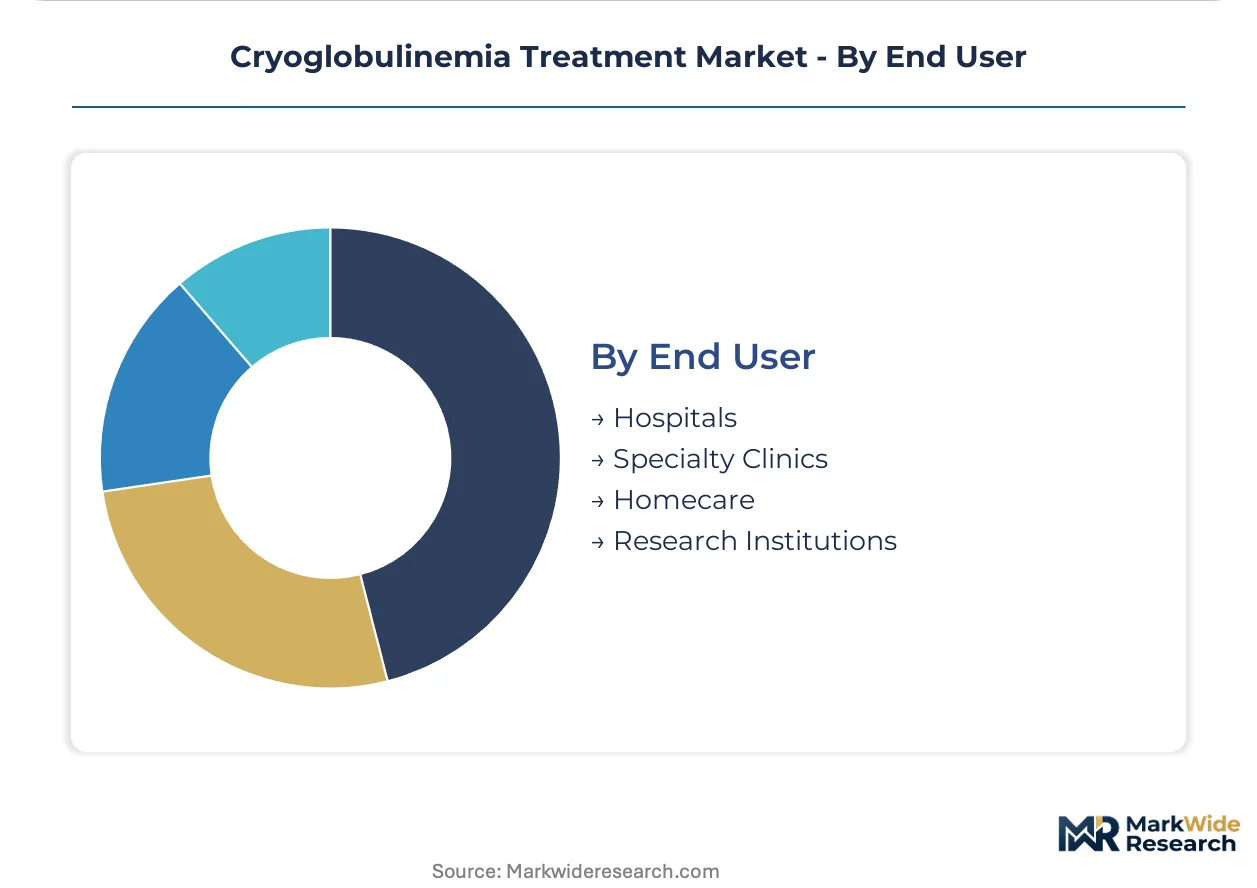
Specialty clinics hold the largest share; homecare shows the steepest expansion trajectory as subcutaneous formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialty clinics in the United States, Germany, and Japan concentrate purchasing authority for cryoglobulinemia therapeutics. These institutions anchor demand for monoclonal antibodies and plasma exchange procedures.
United States
FDA biologics licensing pathways and prior authorization infrastructure concentrate rituximab demand within academic medical centers managing refractory Type II cases. The 21st Century Cures Act provisions accelerate rare disease therapy development. Boston and New York metropolitan hospital networks pilot subcutaneous formulation transitions in stable maintenance populations.
Germany
AMNOG assessment procedures for orphan indications create pricing latitude for therapies demonstrating mortality benefit in mixed cryoglobulinemia. EMA extended guidance on persistent organic pollutant traceability now applies to monoclonal antibody production solvents. Munich and Heidelberg university hospitals anchor procedure volume for renal-limited variants.
Japan
PMDA regenerative medicine pathway complexity prolongs approval timelines for novel mechanism biologics. METI standards govern cold chain distribution infrastructure for temperature-sensitive biologics. Tokyo and Osaka tertiary centers maintain dominant capacity for plasma exchange in hyperviscosity emergencies.
United Kingdom
NHS England specialized commissioning frameworks concentrate cryoglobulinemia treatment within designated vasculitis centers. MHRA post-Brexit regulatory autonomy maintains alignment with EMA orphan drug incentives. London and Manchester academic networks drive demand for AI-driven patient stratification tools.
Switzerland
Swissmedic accelerated assessment pathways for rare diseases compress evaluation timelines for B-cell depleting agents. Federal health insurance mandates guarantee reimbursement for plasma exchange in organ-threatening complications. Basel and Zurich university hospitals concentrate bioengineered antibody pilot programs.
Cryoglobulinemia Treatment Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement environments. Hospital pharmacy and therapeutics committees exercise gatekeeping authority over biologic access, while specialty clinics navigate prior authorization with greater autonomy. Three archetypes dominate: integrated pharmaceutical conglomerates with monoclonal antibody infrastructure, regional generic manufacturers supplying corticosteroid and immunosuppressant tablets, and medical device specialists providing plasma exchange equipment. Competitive moves concentrate on biosimilar preparedness against novel mechanism exploration, and subcutaneous formulation development to bypass infusion center dependency.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd and GlaxoSmithKline plc occupy positions anchored by established immunotherapy infrastructure. Pfizer Inc. exemplifies the scale-driven archetype through broad commercial distribution across hospital networks. These three entities represent the dominant competitive anchors in a market where manufacturing concentration among contract manufacturing organizations creates single-source vulnerability for emerging developers.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Merck Sharp & Dohme Corp. |
| Apotex Inc. |
| Emcure Pharmaceuticals |
| Medimetriks Pharmaceuticals Inc. |
| Asahi Kasei Medical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Basel's monoclonal antibody manufacturing cluster anchors global capacity for B-cell depleting therapies, concentrating upstream bargaining power among three dominant contract manufacturing organizations and compressing margin capture for emerging developers downstream.
Pricing Analysis
Cost-plus contracts with plasma-derived input indexation dominate procurement between fractionators and hospital pharmacy committees. Price differentiation separates rituximab-originator formulations from bioengineered alternatives and corticosteroid generics, with certification tier and after-sales immunogenicity monitoring bundling as key drivers. Cost compression in the corticosteroid tier intensifies as Indian and Chinese generic manufacturers expand volume share. Community hospital emergency departments exhibit highest price sensitivity, while United States academic medical centers demonstrate lowest sensitivity due to prior authorization infrastructure and mortality-based value demonstration.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Swiss and German distributors ease working capital constraints for specialty clinic networks purchasing high-value biologics. Manufacturing concentration rests on the United States, Switzerland, and Ireland for mammalian cell culture capacity, while plasma collection draws from the United States and Germany. Single-source vulnerability in contract manufacturing organization capacity for antibody-dependent cellular cytotoxicity enhancement creates structural exposure. Distribution runs through consolidated specialty pharmacy networks in United States metropolitan corridors and hospital-based procurement committees in German university hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as AI-driven patient stratification tools interoperate with cryoglobulin typing assays, creating ecosystem lock-in for integrated diagnostic-therapeutic developers.
For Market Incumbents: Harden pharmacovigilance infrastructure against EMA extended guidance on persistent organic pollutant traceability, which threatens manufacturing retrofit costs for purification processes. Deepen backward integration into plasma collection networks to offset fractionation capacity constraints. Anchor formulary position through mortality benefit demonstration in mixed cryoglobulinemia subtypes, defending against biosimilar entrants with real-world evidence generation.
For New Entrants and Emerging Players: Pursue subcutaneous formulation development for stable maintenance populations in Japanese home nursing infrastructure and United States rural markets, where infusion center dependency creates access barriers. Target German nephrology centers for renal-limited mixed cryoglobulinemia, where AMNOG assessment procedures reward mortality benefit with pricing latitude. Deploy direct-to-specialist digital platforms to bypass primary care diagnostic bottlenecks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with integrated AI-driven response prediction and subcutaneous delivery platforms over pure monoclonal antibody plays. Long-term viability over the coming decade hinges on biosimilar preparedness against novel mechanism exploration balance. Watch FDA biologics licensing pathway acceleration for rare autoimmune indications as the inflection signal for portfolio rebalancing toward mechanism-based patient stratification capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Self-administration technologies bypass infusion center dependency and unlock homecare channels. |
| AI-Driven Patient Stratification Integration | Machine learning with cryoglobulin typing assays enables predictive response modeling for payers. |
| Plasma Collection Network Expansion | Backward integration into fractionation inputs secures supply against donor pool limitations. |
| EMA Orphan Drug Pathway Navigation | Extended market exclusivity provisions accelerate investment in rare autoimmune indications. |
| Specialty Pharmacy Partnership Consolidation | Channel concentration among dominant distributors expands patient access in underserved sub-markets. |
Study Parameters
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary validation anchors the qualitative findings. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases provide regulatory and pipeline intelligence. Bottom-up patient population modeling and top-down pharmaceutical market sizing triangulate volume estimates across the cryoglobulinemia treatment landscape.
Calibration against historical biologics launch curves and immunotherapy adoption patterns shapes the analytical framework. Segmentation dimensions span cryoglobulin type, therapeutic modality, delivery mode, and regional regulatory cluster. CAGRs derive from epidemiological trend extrapolation, pricing trajectory analysis, and penetration rate modeling across specialty clinic, hospital, and homecare channels. Hepatitis C eradication program impact and subcutaneous formulation migration serve as industry-specific forecast inputs.
Sensitivities concentrate around plasma-derived input volatility, PMDA regenerative medicine pathway timeline revisions, and monoclonal antibody manufacturing concentration disruptions. Forecasts reflect assumptions on regulatory approval velocity, biosimilar entry timing, and patient stratification technology adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market