
 Global Feed Software Market | 2026-2036
Global Feed Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Software Market Foresight
Modular subscription tiers is realigning buyer choice across the feed software landscape. Cargill Incorporated leverages its captive agronomy data to anchor premium analytics modules for integrated protein producers. Evonik Industries AG differentiates through amino acid formulation algorithms embedded within nutrition planning suites. Adifo Software specializes in batch-optimization tools that dominate European compound feed operations.
Feed software encompasses digital platforms that formulate, track, and optimize animal nutrition programs through algorithm-driven ration balancing and real-time ingredient cost modeling. These systems integrate least-cost formulation engines with livestock performance databases to maximize feed conversion ratios across swine, poultry, and ruminant operations. Cloud-Based deployment leads the solution architecture as processors prioritize remote access across distributed mill networks. Data Integration offerings capture expanding margin pools as buyers demand seamless connectivity between ERP systems and on-farm sensor networks. On-Premise configurations retain footholds among operators in regions with intermittent broadband infrastructure.
The USDA enforces feed ingredient safety standards through the Food Safety Modernization Act, compelling software vendors to embed traceability workflows. China's SAMR mandates GB-compliant labeling for imported premixes, shaping product localization requirements for platform providers. The EU Green Deal's farm-to-fork targets are accelerating carbon-footprint tracking modules within nutrition management tools. Stakeholders must monitor how evolving methane-emission accounting rules reshape the functional specifications that buyers prioritize in procurement cycles.
Market Dynamics
Cloud migration is compressing deployment timelines across feed software procurement cycles as processors abandon refrigerant-dependent on-premise infrastructure. The EU F-Gas Regulation's phase-down schedule is accelerating this structural shift toward distributed data architectures.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Methane-emission accounting mandates are forcing nutrition management platforms to embed carbon-footprint tracking modules. Livestock integrators in the Netherlands are piloting these capabilities first.
- Least-cost formulation engines:Real-time ingredient cost modeling is rewriting procurement workflows for swine and poultry operations. Compound feed mills in Iowa are standardizing these tools across distributed mill networks.
- Wageningen University R&D clustering:Netherlands-based feed-tech pipelines are commercializing precision nutrition algorithms. Dutch protein producers are beta-testing amino acid optimization modules ahead of broader European rollout.
Market Restraints
- Intermittent broadband infrastructure:Rural feed mill networks in Brazil and India cannot sustain cloud-dependent platforms. On-premise configurations retain footholds but carry higher total cost of ownership.
- GB-compliant labeling mandates:China's SAMR requirements for imported premixes impose localization friction on foreign software vendors. Compliance timelines extend platform deployment cycles by 8-14 months.
- Data integration complexity:ERP-to-sensor connectivity gaps persist across legacy livestock management systems. Mid-scale ruminant operations lack technical staff to configure API bridges.
Strategic Opportunities
- Carbon credit monetization modules:EU Green Deal compliance tools can extend into voluntary carbon market participation. Dutch and Danish integrators are exploring feed-efficiency credits as revenue streams.
- Subscription-based sensor bundling:Hardware-as-a-service models are penetrating Brazilian and Vietnamese poultry operations. Remote access platforms combined with IoT deployments reduce upfront capital barriers.
- USDA FSMA traceability workflows:Food Safety Modernization Act enforcement is creating mandatory upgrade cycles. Mid-tier feed manufacturers face 2026 compliance deadlines requiring platform replacement.
Industry Challenges
- Livestock data science talent scarcity:Animal nutrition expertise rarely overlaps with cloud architecture skills. Feed software vendors compete with agritech firms for the same limited hiring pool.
- Multi-generational system integration:1990s-era formulation databases persist in family-owned mill operations. API standardization gaps force expensive custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Software Market |
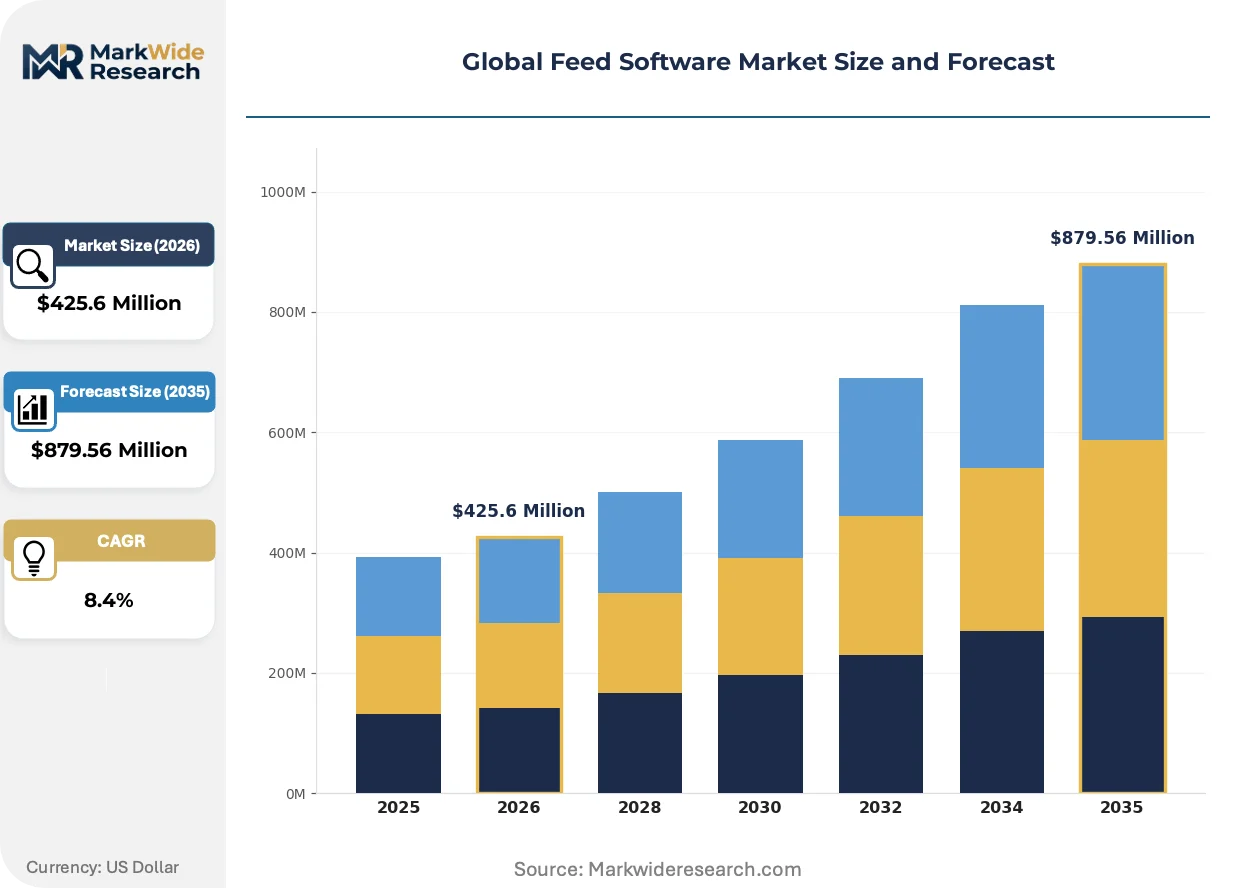
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $879.56 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution/Offering: Content Management, Data Integration, User Analytics, Reporting Tools, API Management Use Case: News Aggregation, Social Media Monitoring, Market Intelligence, Real-Time Alerts, Sentiment Analysis End User Industry: Publishing Houses, Financial Firms, Digital Agencies, Research Organizations, E-Learning Providers |
| Companies Covered | Adifo Software, Alltech Inc., Cargill Incorporated, Evonik Industries AG, Kemin Industries, Cultura Technologies Inc., Dalex Livestock Solutions LLC, Format Solutions, Feedlogic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Software Market Shifts & Advancements
Algorithmic nutrition planning is displacing static ration tables as the core decision architecture across commercial livestock operations. Three convergent developments are compressing innovation cycles in this space.
Machine learning-based feed conversion prediction is rewriting performance optimization workflows for integrated protein producers. Iowa-based swine operators are deploying these models across 10,000-head finishing barns. The technology is compressing the feedback loop between formulation adjustments and weight-gain outcomes from weeks to hours.
The EU F-Gas Regulation's refrigerant phase-down is accelerating data center consolidation into cloud-native architectures. On-premise server farms face compliance costs exceeding $50,000 per facility for refrigerant retrofits. European compound feed software vendors are sunsetting local installation options ahead of the 2030 ban timeline.
Outcome-based pricing models are displacing perpetual licenses across North American dairy nutrition advisory services. Nutrition consultants in Wisconsin are bundling software access with milk-yield improvement guarantees. This shift concentrates vendor risk while aligning payment schedules with producer cash-flow patterns tied to commodity milk pricing cycles.
Global Feed Software Market Segmentation
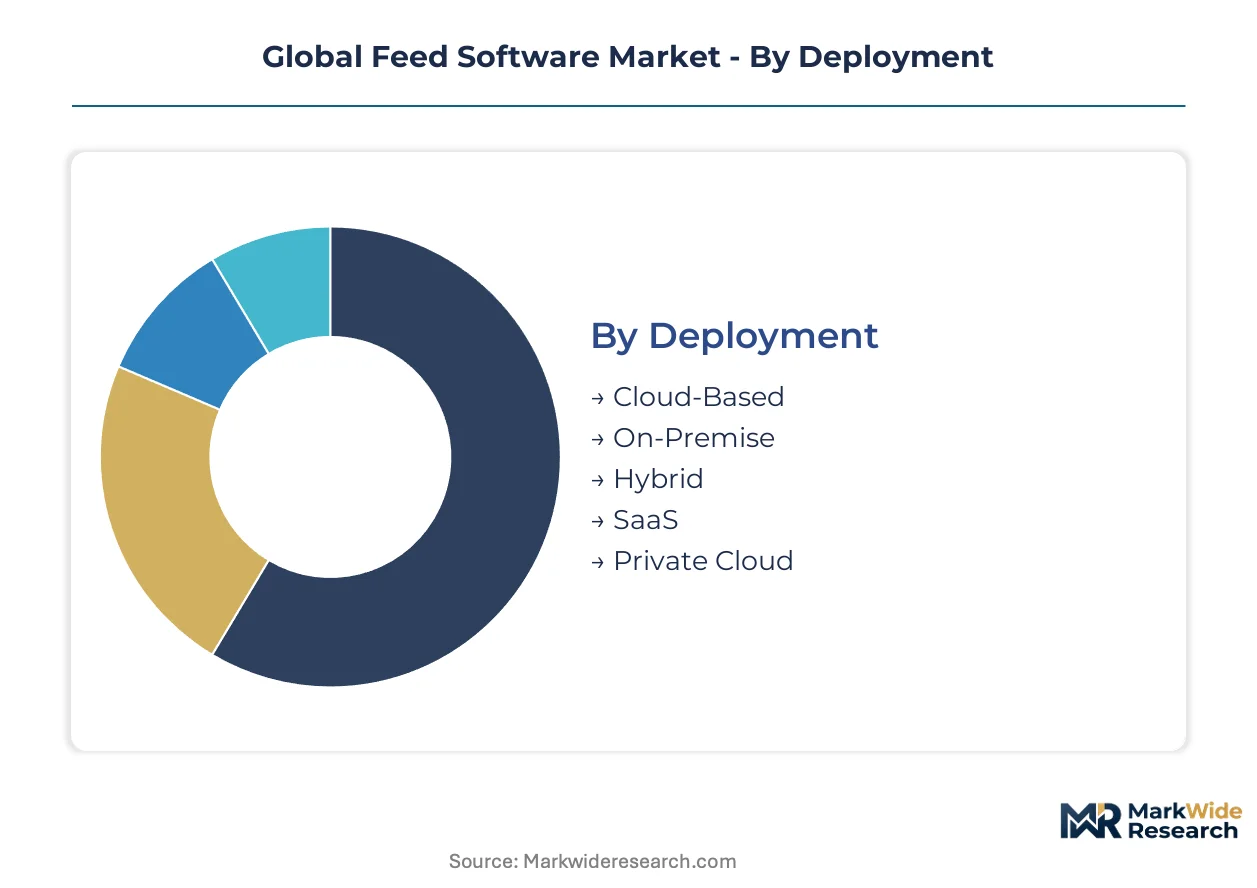
Feed software segmentation reveals how deployment architecture and functional depth determine integration pathways with livestock management systems. Procurement patterns diverge sharply between processors seeking standalone nutrition tools versus those embedding capabilities within broader enterprise platforms.
Deployment:
Standalone cloud installations dominate distributed mill networks, while embedded on-premise systems persist where broadband infrastructure limits connectivity.
- Cloud-Based:Distributed architectures enable remote formulation access across multi-site operations. Iowa-based swine integrators deploy these platforms across 50+ finishing barns with centralized nutrition oversight.
- On-Premise:Local server installations retain footholds in regions with intermittent connectivity. Brazilian compound feed mills in Mato Grosso sustain operations despite unreliable rural broadband.
- Hybrid:Split workloads process sensitive formulation data locally while syncing cost models to cloud analytics.
- SaaS:Subscription licensing reduces capital barriers for mid-scale poultry operations in Vietnam.
- Private Cloud:Dedicated infrastructure serves protein producers with stringent data sovereignty requirements.
Cloud-Based leads volumes today; SaaS is gaining share fastest.
Solution/Offering:
Cost tier stratification separates premium analytics modules from baseline content tools, with integration capabilities commanding margin premiums.
- Data Integration:API bridges connecting ERP systems to on-farm sensor networks command highest price points. Dutch dairy cooperatives prioritize seamless milk-yield data flows into ration optimization engines.
- Content Management:Ingredient specification databases with real-time pricing updates anchor procurement workflows. North American feed mills standardize these tools across distributed sourcing networks.
- User Analytics:Performance dashboards track feed conversion ratios across barn-level populations.
- Reporting Tools:Compliance documentation generators automate EU Green Deal carbon-footprint submissions.
- API Management:Middleware layers enable legacy system connectivity without full platform replacement.
Content Management anchors installed base; Data Integration expands most quickly.
Use Case:
Application maturity varies sharply, with operational optimization tools outpacing market-facing intelligence functions in deployment velocity.
- Real-Time Alerts:Automated notifications trigger formulation adjustments when ingredient prices shift beyond threshold bands. Iowa pork processors deploy these systems to lock in least-cost rations within 15-minute windows.
- Market Intelligence:Commodity price forecasting modules guide forward contracting decisions for soybean meal and corn.
- News Aggregation:Curated regulatory feeds track USDA FSMA updates and EU F-Gas Regulation amendments.
- Social Media Monitoring:Consumer sentiment tracking supports sustainability messaging for retail-facing protein brands.
- Sentiment Analysis:Natural language processing evaluates supplier reliability from trade publication coverage.
Real-Time Alerts dominates current deployments; Market Intelligence shows steepest expansion trajectory.
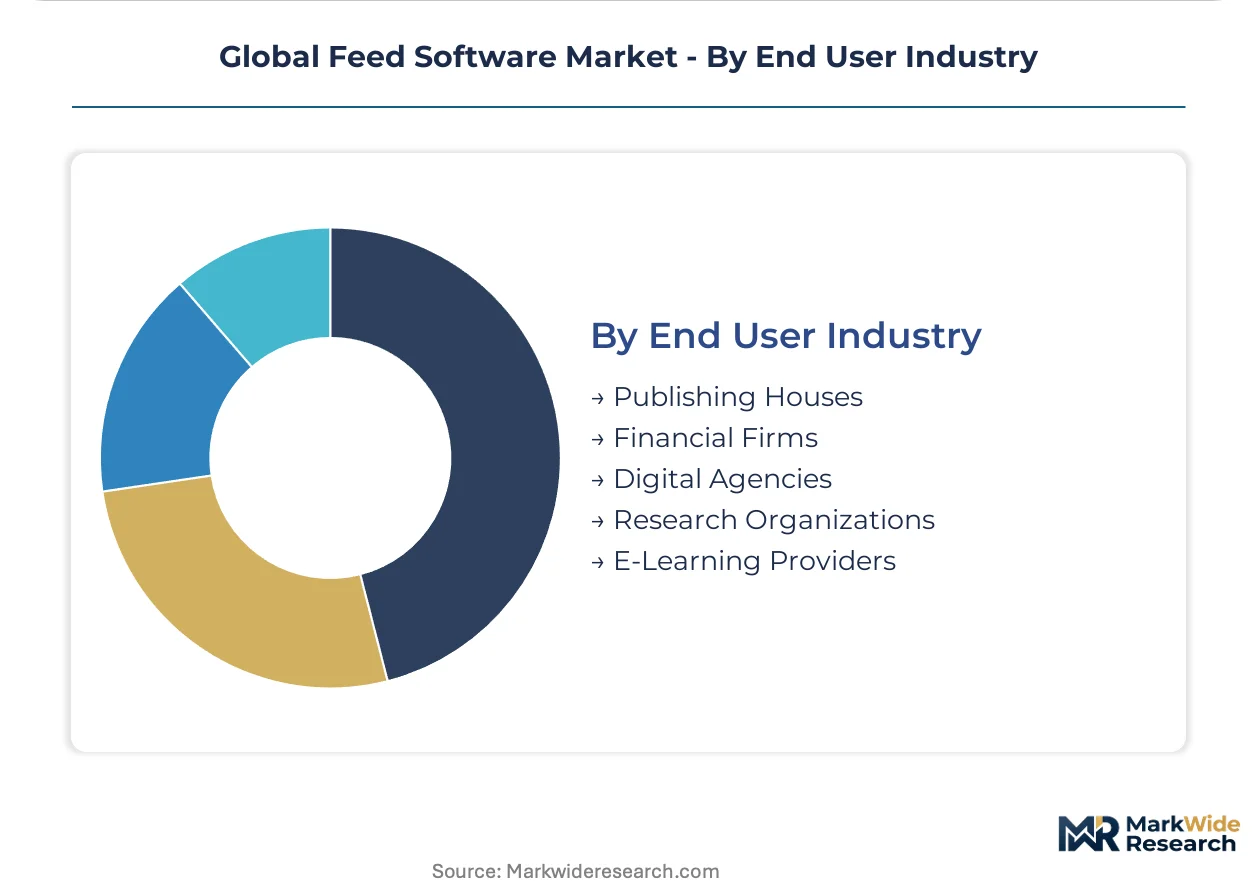
End User Industry:
Customer type segmentation maps directly to procurement sophistication, with integrated protein producers driving premium module adoption versus fragmented advisory services.
- Publishing Houses:Agricultural media platforms license feed software APIs to embed nutrition calculators within subscriber content.
- Financial Firms:Commodity trading desks leverage formulation cost models to forecast margin compression across protein sectors.
- Digital Agencies:Marketing services for farm equipment manufacturers integrate feed efficiency dashboards into client retention programs.
- Research Organizations:Wageningen University clusters anchor precision nutrition algorithm development pipelines.
- E-Learning Providers:Veterinary continuing education platforms embed simulation tools for ration balancing certification.
Publishing Houses represent largest installed base; Financial Firms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed software originated in Dutch agricultural research clusters during the 1980s, when Wageningen University pioneered algorithmic ration balancing for intensive livestock systems. This academic foundation seeded commercial platforms that now serve protein producers across five continents.
United States
Iowa-based swine integrators deploy cloud-based formulation tools across 50,000-head finishing networks. The USDA Food Safety Modernization Act mandates traceability workflows that compress software upgrade cycles. Chicago commodity trading desks anchor demand for real-time ingredient cost modeling modules.
Netherlands
Dairy cooperatives in Friesland and Gelderland prioritize carbon-footprint tracking ahead of EU Green Deal enforcement timelines. The EU F-Gas Regulation accelerates data center consolidation into cloud-native architectures. Wageningen University clusters commercialize precision nutrition algorithms for European protein producers.
Brazil
Mato Grosso compound feed mills sustain operations through hybrid deployment models despite unreliable rural broadband. ANVISA enforcement of feed ingredient safety standards shapes platform localization requirements. São Paulo-based poultry processors pilot subscription-based sensor bundling to reduce capital barriers.
China
Shandong Province livestock integrators adopt least-cost formulation engines for 100-million-head swine operations. SAMR mandates GB-compliant labeling for imported premixes, extending deployment cycles. Yangtze River Delta feed manufacturers prioritize ERP-to-sensor connectivity for distributed mill networks.
Germany
Baden-Württemberg dairy nutrition consultants bundle software access with milk-yield improvement guarantees. REACH compliance requirements shape ingredient specification database architectures. Bavarian compound feed operations standardize batch-optimization tools across cooperative mill networks.
Global Feed Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data integration depth and algorithmic sophistication. The vendor base stratifies into three tiers: integrated agribusiness conglomerates with captive agronomy data, specialized formulation software houses with decades of industry-specific codebases, and emerging SaaS platforms attacking mid-market price points. Dominant competitive moves include strategic partnerships with sensor hardware manufacturers and geographic expansion through regulatory-compliant localization.
Among diversified agribusiness conglomerates, Cargill Incorporated and Evonik Industries AG exemplify the premium-tier archetype, anchoring market positioning through embedded nutrition science and captive supply chain data. Adifo Software occupies a specialist position within the European compound feed segment. These three entities represent distinct strategic postures: conglomerate-backed platform breadth, chemical-nutrition algorithm integration, and regional software specialization.
| Leading Market Players |
|---|
| Adifo Software |
| Alltech Inc. |
| Cargill Incorporated |
| Evonik Industries AG |
| Kemin Industries |
| Cultura Technologies Inc. |
| Dalex Livestock Solutions LLC |
| Format Solutions |
| Feedlogic Corporation |
| Others |
Supply & Pricing Matrix
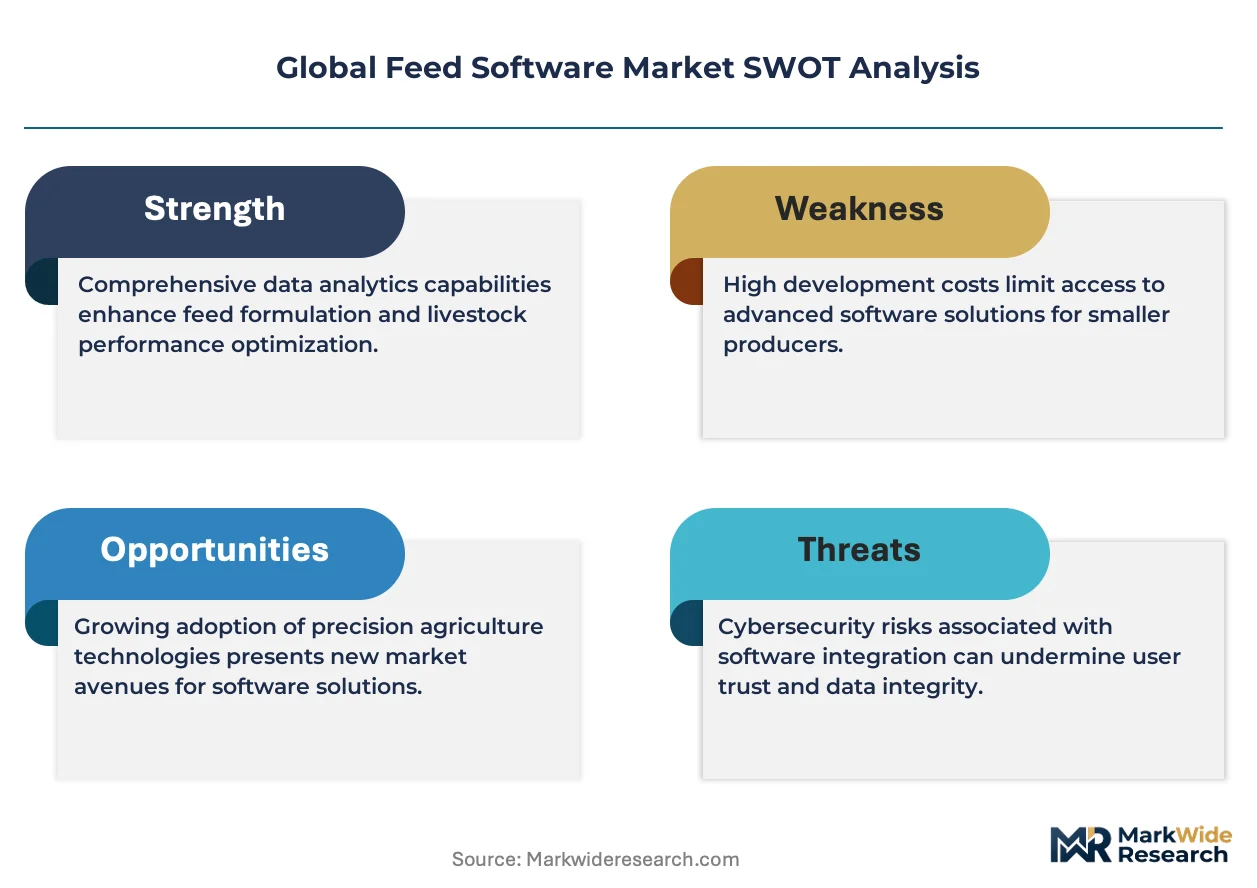
Captive agronomy data integration anchors both supply positioning and pricing power for integrated protein producers. Cargill Incorporated leverages its upstream grain origination networks to bundle premium analytics modules at margin-protected price points, while specialized vendors without captive supply chains compete on narrower formulation toolsets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the installed base by integration depth and algorithmic sophistication. Premium tiers command price differentiation through embedded amino acid optimization engines and real-time ERP-to-sensor connectivity, while economy tiers serve batch-optimization fundamentals for standalone compound feed mills. Pricing pressure stems from SaaS entrants attacking mid-market price points with subscription-based sensor bundling. Mid-scale poultry operations in Vietnam exhibit highest price sensitivity; integrated swine producers in Iowa demonstrate lowest sensitivity due to yield-gain guarantees.
Supply Chain Analysis
China's SAMR labeling mandates and the EU F-Gas Regulation are reshaping sourcing patterns for software localization and data center infrastructure. Development talent concentrates in the Netherlands, the United States, and Germany, with Wageningen University clusters feeding algorithm pipelines. Cloud-native architectures draw from hyperscaler infrastructure in Ireland, Singapore, and Virginia, while on-premise hardware feeds from Taiwanese server component networks. Single-source vulnerability runs through concentrated hyperscaler regions for European deployments. Distribution runs through direct enterprise sales for integrated protein producers and channel partnerships for mid-scale advisory services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where compliance deadlines generate mandatory upgrade cycles. The USDA Food Safety Modernization Act's traceability mandates are forcing platform replacements across mid-tier feed manufacturers.
For Market Incumbents: Deploy carbon-footprint tracking modules ahead of EU Green Deal enforcement timelines. Consolidate position by acquiring specialized batch-optimization vendors in European cooperative mill networks. Threaten substitution from cloud-native SaaS platforms with lower total cost of ownership demands defensive bundling of sensor hardware with software subscriptions. For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for cloud-native architectures displacing refrigerant-dependent on-premise installations. White-space targets include Brazilian compound feed mills in Mato Grosso seeking hybrid deployment models and Vietnamese poultry operations receptive to subscription-based sensor bundling. Go-to-market angle: outcome-based pricing tied to feed conversion ratio improvements with minimal upfront capital requirements. For Investors and Strategic Acquirers: Roll-up economics work for specialized formulation software houses because algorithmic nutrition expertise rarely overlaps with cloud architecture skills, creating scarcity value for technical talent pools. Long-term viability centers on platforms with embedded regulatory compliance workflows rather than standalone content tools. Acquisition target archetype: European compound feed software vendors with decades of industry-specific codebases and established ANVISA or SAMR localization pathways. Signal to watch: methane-emission accounting rule finalization triggering carbon credit monetization module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API bridges connecting ERP systems to on-farm sensor networks command highest price points in Dutch dairy cooperatives. |
| Acquisition of Specialist Firm | Batch-optimization vendors in European cooperative mill networks extend reach into compound feed operations. |
| Strategic Partnership | Sensor hardware manufacturers enable subscription-based sensor bundling reducing capital barriers in Brazilian poultry. |
| Geographic Expansion | GB-compliant labeling localization opens SAMR-mandated deployment pathways in Shandong Province swine operations. |
| Product Launch | Carbon credit monetization modules extend EU Green Deal compliance tools into voluntary carbon market participation. |
Research Methodology
Direct dialogue with livestock nutrition consultants, feed mill operations managers, software platform engineers, and ERP integration specialists grounded the qualitative foundation. Secondary validation drew from USDA FSMA guidance documents, EU F-Gas Regulation amendment tracking, SAMR premix labeling directives, and ANVISA feed safety enforcement records. Bottom-up sizing of deployment models and solution tiers triangulated against top-down protein production volume estimates across analyzed geographies.
Bottom-up demand modeling segmented by deployment architecture, solution depth, and end-user sophistication layered against top-down livestock production capacity estimates. Segmentation dimensions included cloud versus on-premise versus hybrid deployment, data integration versus content management versus analytics solution tier, and integrated protein producer versus cooperative mill versus independent advisory service end-user type. CAGRs derived from algorithmic nutrition adoption curves and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated broadband infrastructure penetration rates and refrigerant phase-down compliance cost curves.
Revisions become necessary when methane-emission accounting rules reshape functional specifications, hyperscaler concentration triggers data sovereignty restrictions, or livestock data science talent scarcity accelerates beyond projected training pipeline outputs. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and cloud migration cost compression rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Android Emulator Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Global UIUX Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Global Mobile Application Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Global Construction Management Software Market
Software & Services
Global Childcare Management Software Market