
 Global Childcare Management Software Market | 2026-2036
Global Childcare Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Childcare Management Software Market Foresight
Multi-source platform procurement is expanding across mid-sized daycare chains as operators seek to avoid vendor lock-in while integrating specialized modules. Procare Software LLC leverages deep integration with state subsidy reporting systems to anchor its position among large licensed centers. Jackrabbit Technologies Inc. competes through specialized class-scheduling tools designed for gymnastics and dance academies that extend into early childhood programming. Hi Mama Inc. differentiates via parent-engagement features that sustain renewal rates above category averages.
Childcare management software comprises cloud-native and on-premise applications that automate enrollment tracking, tuition billing, staff credential verification, and regulatory compliance reporting for licensed early-education facilities. These systems typically integrate biometric or RFID-based check-in protocols with real-time parent notification APIs to satisfy state-mandated child-staff ratio documentation. Cloud-based deployment now leads solution uptake among new buyers because it eliminates capital-intensive server maintenance and accelerates multi-location rollouts. Parent communication modules represent the fastest-expanding solution category as providers recognize messaging tools as retention instruments rather than operational overhead.
The United States Department of Health and Human Services administers Child Care and Development Fund block grants that require detailed attendance verification, directly shaping software feature requirements for subsidy-eligible providers. GDPR and state-level student privacy laws in California and Illinois restrict cross-border data hosting and mandate explicit consent architectures, forcing vendors to reconfigure infrastructure or risk market exclusion. Stakeholders must monitor evolving state reimbursement rules and interoperability mandates to determine whether vertical feature depth or horizontal platform breadth offers superior defensibility.
Market Dynamics
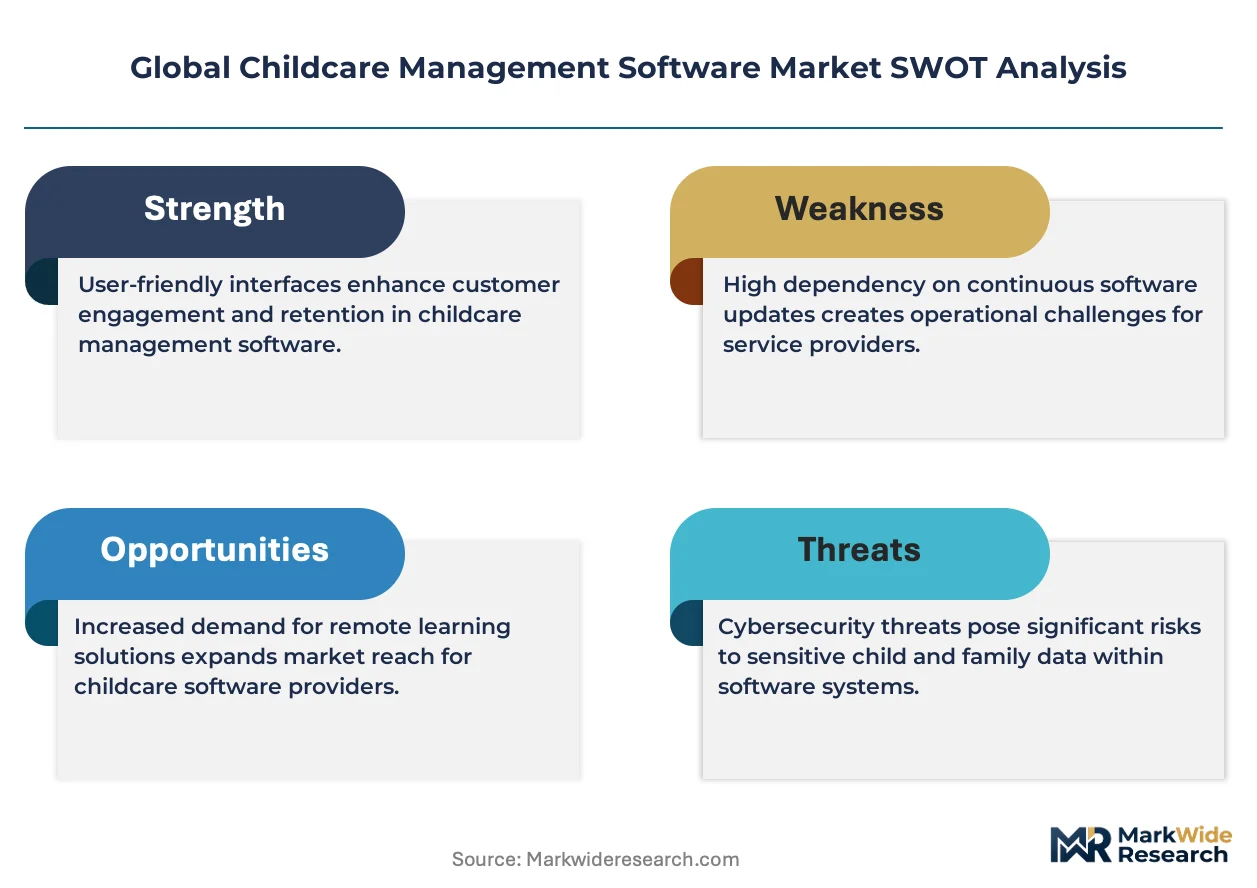
Cloud-native deployment architectures are compressing the traditional on-premise installed base across licensed early-education facilities, forcing incumbent vendors to reconfigure delivery models or cede mid-market share to SaaS-native competitors.
Growth Catalysts
- Child Care and Development Fund mandates:US federal attendance verification requirements for subsidy-eligible providers create non-negotiable software procurement triggers across state-level provider networks.
- Biometric check-in protocols:Fingerprint and facial recognition integrations automate child-staff ratio documentation, reducing manual compliance labor for multi-location daycare chains.
- Parent-engagement module expansion:Real-time notification APIs transform operational overhead into retention instruments, driving renewal premiums among licensed centers in competitive metropolitan markets.
Market Restraints
- GDPR cross-border hosting restrictions:European data localization mandates force vendors to maintain separate infrastructure or exit member-state markets entirely.
- Legacy system integration friction:Proprietary on-premise databases in established centers resist API connectivity, extending sales cycles and implementation costs.
- State subsidy reporting fragmentation:Non-standardized data formats across 50 US state agencies multiply development overhead for compliance modules.
Strategic Opportunities
- Underpenetrated rural provider networks:Federally qualified Head Start centers in non-metropolitan US counties lack digital infrastructure, creating first-mover consolidation potential.
- AI-driven predictive staffing:Machine learning enrollment forecasting converges with automated credential tracking to optimize labor allocation during seasonal demand swings.
- Mobile-first parent portals:Smartphone-native interfaces displace desktop-dependent legacy platforms among millennial parent demographics in urban Canadian markets.
Industry Challenges
- Specialized early-education IT talent scarcity:Hybrid skill sets combining FERPA compliance expertise with cloud architecture deployment command salary premiums that strain vendor margins.
- Multi-state certification timeline compression:Separate approvals for biometric data handling in California, Illinois, and Texas delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Childcare Management Software Market |
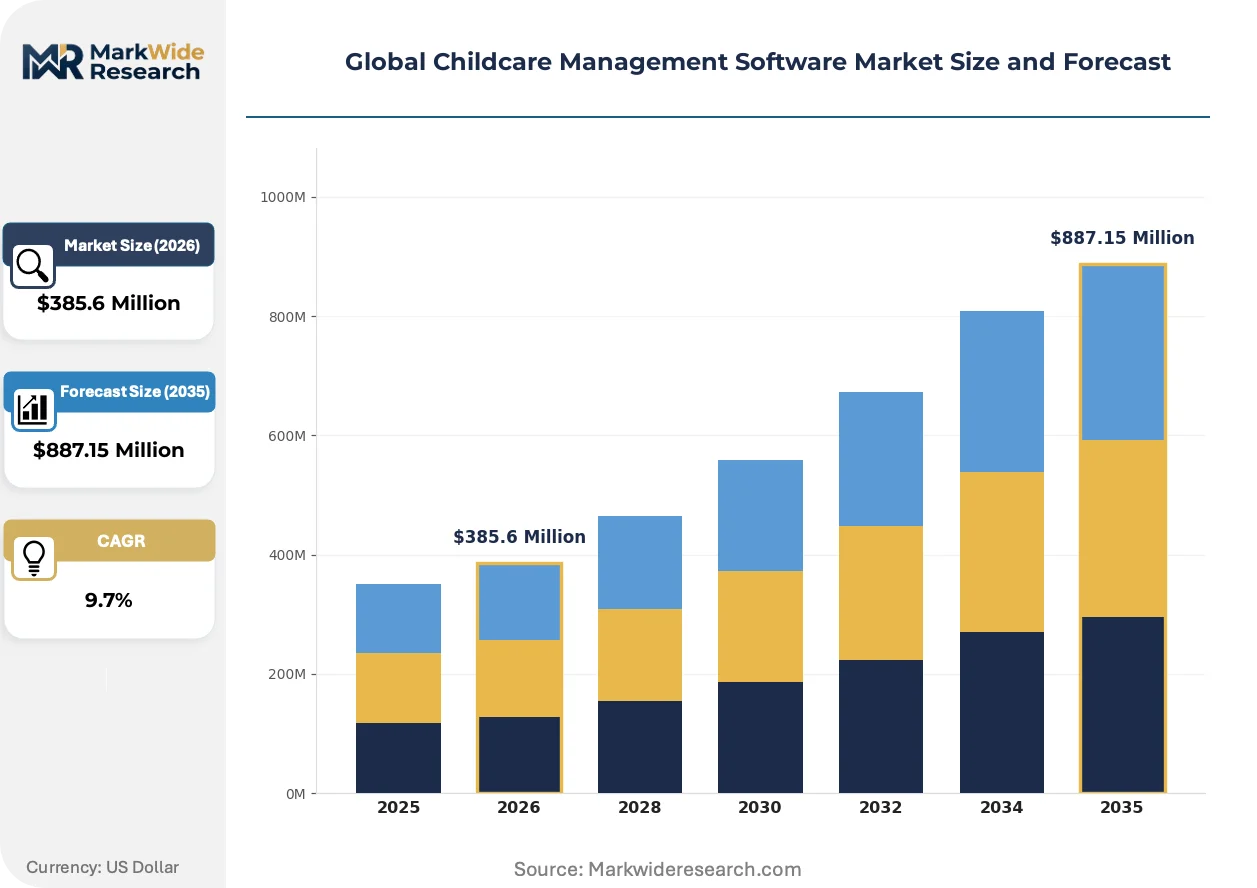
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Web-Based Solution Offering: Attendance Tracking, Billing & Payments, Parent Communication, Staff Management, Scheduling Management Application: Daycare Centers, Early Learning Programs, Preschools, After-School Programs, Nanny Agencies End User: School Administrators, Childcare Providers, Parents, Government Agencies, Non-Profit Organizations |
| Companies Covered | Procare Software LLC, Lifecubby, EZChildTrack, Jackrabbit Technologies Inc., Hi Mama Inc., AIS Software, Bloomz Inc., SofterWare Inc., Orgamation Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Childcare Management Software Market Shifts & Advancements
API-first architectures are dismantling the monolithic platform model that dominated childcare software for two decades, enabling modular procurement and specialized best-of-breed integration.
Serverless computing infrastructure is rewriting cost structures for attendance and billing automation. Mid-sized daycare chains in the United States are migrating check-in and payment processing to consumption-based models that eliminate fixed server licensing. This compression of capital requirements is lowering barriers for multi-location expansion.
GDPR Article 17 right-to-erasure mandates are reshaping data retention architectures across European early-education software deployments. Vendors must engineer automated deletion workflows for student biometric records and parent communication histories. French and German licensed centers now prioritize consent-management modules over feature breadth in procurement evaluations.
Subscription unbundling is fragmenting the traditional all-in-one platform sale. US parent cooperatives and home-based providers are purchasing standalone communication tools from specialized vendors while maintaining basic attendance tracking through free or low-cost alternatives. This behavioral shift concentrates premium spending on engagement features rather than operational modules.
Global Childcare Management Software Market Segmentation
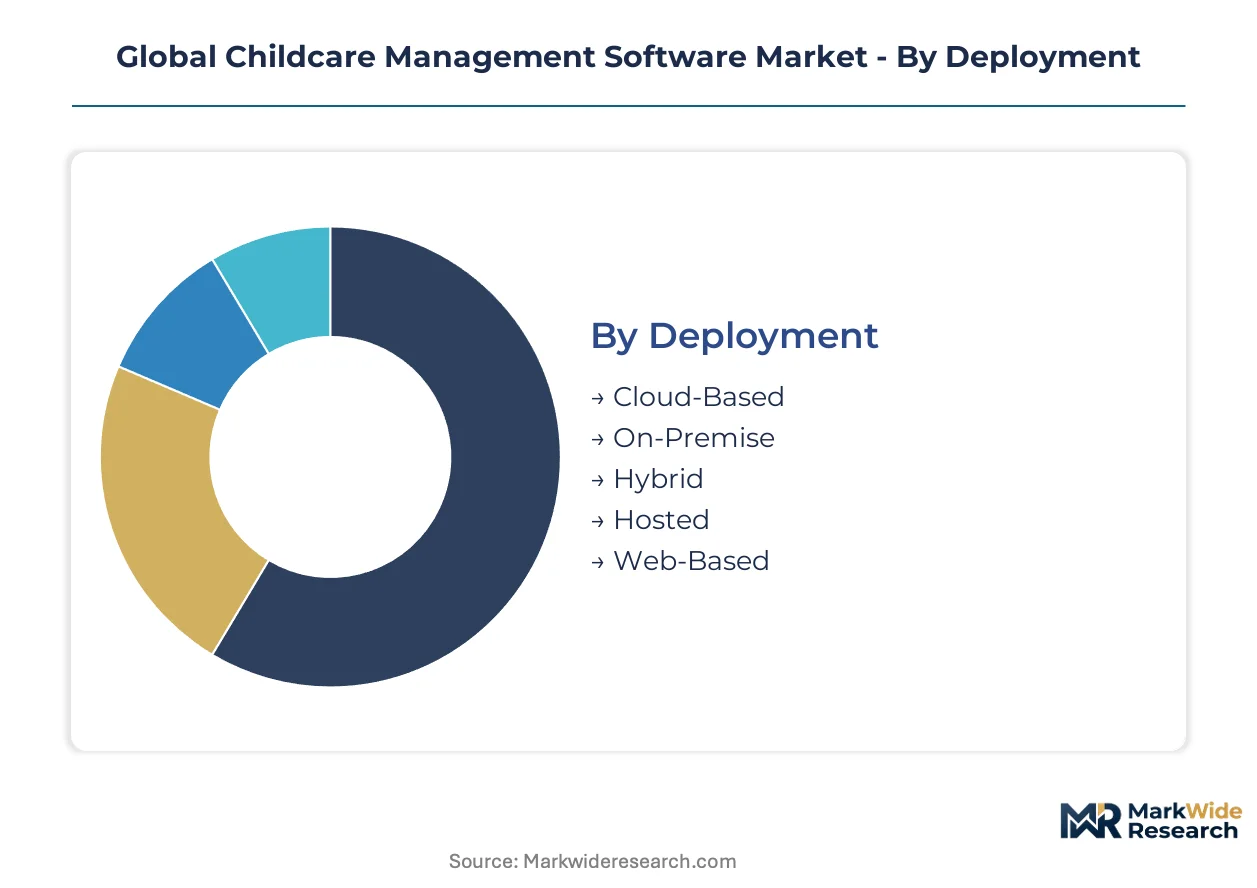
Deployment architecture determines capital requirements and operational scalability for licensed early-education facilities. Solution specialization and end-user workflows shape procurement priorities across fragmented provider networks.
Deployment:
Capital intensity varies sharply across infrastructure models, with perpetual licensing and server hardware demanding the heaviest upfront commitment from established centers.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server procurement and IT staffing overhead. Demand concentrates among mid-sized daycare chains in the United States seeking rapid multi-location rollouts without capital-intensive infrastructure. Federal Child Care and Development Fund reporting requirements accelerate adoption as vendors pre-configure compliance modules.
- On-Premise:Perpetually licensed software running on customer-owned servers demands substantial hardware investment and dedicated IT personnel. Large institutional providers in Germany and France maintain these deployments to satisfy GDPR data localization mandates and internal security protocols.
- Hybrid:Split architectures keep sensitive biometric data on local servers while pushing billing and communication to cloud instances. Canadian provincial regulators in Ontario and British Columbia encourage this model for balancing accessibility with privacy controls.
- Hosted:Single-tenant cloud deployments on dedicated virtual machines reduce capital burden while preserving customization flexibility. Niche appeal among religiously affiliated centers in Texas and Florida with specific theological data governance requirements.
- Web-Based:Browser-accessible platforms without native mobile applications serve budget-constrained home-based providers. Minimal infrastructure needs attract parent cooperatives in rural Australian markets with unreliable connectivity.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as privacy regulations tighten across European member states.
Solution Offering:
Functional modules align with operational pain points, from compliance documentation to revenue collection and family retention.
- Attendance Tracking:Biometric and RFID-based check-in systems automate child-staff ratio verification for state inspectors. Demand clusters in California and Illinois where subsidy reimbursement ties directly to timestamped attendance records.
- Billing & Payments:Automated tuition invoicing with integrated payment processing reduces accounts-receivable overhead. Large licensed chains in metropolitan United States markets prioritize this module for cash-flow predictability.
- Parent Communication:Real-time messaging, photo sharing, and developmental milestone tracking transform operational tools into retention instruments. Fastest-expanding category as millennial parents in urban Canadian markets expect smartphone-native engagement.
- Staff Management:Credential verification, background check tracking, and training compliance dashboards address regulatory audit requirements. Essential procurement trigger for Head Start centers receiving federal funding.
- Scheduling Management:Dynamic room allocation and staff rotation tools optimize capacity utilization during seasonal enrollment swings. Gymnastics and dance academies extending into early childhood programming drive specialized demand.
Procurement concentrates first on Attendance Tracking for compliance. Parent Communication modules are gaining share fastest as retention economics reshape provider priorities.
Application:
Facility type dictates user volume, regulatory scrutiny, and integration complexity for software implementations.
- Daycare Centers:Licensed facilities serving infants through preschoolers with full-day programming. Multi-location chains in the United States represent the core revenue base for established vendors.
- Early Learning Programs:Curriculum-focused initiatives emphasizing school readiness and developmental assessment. State-funded pre-K expansions in New York and New Jersey drive procurement volume.
- Preschools:Part-day educational programs for three- to five-year-olds with lower staff-to-child ratios. Independent operators in the United Kingdom prioritize parent-engagement features for competitive differentiation.
- After-School Programs:School-age care with transportation coordination and homework supervision needs. Fragmented procurement across municipal recreation departments and private providers.
- Nanny Agencies:Placement and payroll management for in-home childcare arrangements. Smaller addressable market with specialized tax reporting requirements.
Largest installed base sits with Daycare Centers. Early Learning Programs are expanding most quickly as public funding commitments deepen.
End User:
Stakeholder workflows determine interface design, permission architectures, and training requirements for platform adoption.
- School Administrators:Executive dashboards for enrollment forecasting, financial reporting, and regulatory compliance. Control procurement decisions at multi-location chains.
- Childcare Providers:Classroom staff requiring intuitive check-in protocols and daily activity logging. Mobile-first design priorities emerge from this user base.
- Parents:Consumer-grade mobile interfaces for payment, communication, and developmental updates. Renewal premiums attach to engagement satisfaction scores.
- Government Agencies:State subsidy administrators and audit inspectors accessing aggregated compliance reports. Data format standardization remains unresolved across United States state boundaries.
- Non-Profit Organizations:Federally qualified Head Start centers with complex funding source tracking and board reporting obligations. Grant compliance modules shape vendor selection.
Administrators control initial procurement. Provider and parent user experience now determines renewal rates and competitive switching.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting vendor development resources toward jurisdictions with clearer compliance pathways, as fragmented subsidy reporting requirements in the United States impose heavier engineering overhead than unified frameworks elsewhere.
United States
State-level Child Care and Development Fund administration creates procurement complexity that favors vendors with pre-built compliance modules. FERPA and state student privacy laws in California and Illinois restrict cross-border data flows. Metropolitan clusters in Texas and Florida drive demand for biometric check-in integrations among multi-location daycare chains.
Germany
GDPR Article 17 right-to-erasure mandates reshape vendor data retention architectures for licensed early-education facilities. The country's federal data protection authority enforces strict localization requirements for student biometric records. Industrial concentration in Bavaria and North Rhine-Westphalia anchors procurement volume for hybrid cloud-on-premise deployments.
United Kingdom
Independent preschool operators prioritize parent-engagement features for competitive differentiation in saturated urban markets. The Information Commissioner's Office applies GDPR-equivalent standards through the UK GDPR framework. Greater London and Southeast England concentrate demand for mobile-first communication platforms among millennial parent demographics.
Canada
Provincial regulators in Ontario and British Columbia encourage hybrid deployment models that balance accessibility with privacy controls. Canadian data residency requirements under PIPEDA influence vendor infrastructure decisions. Urban markets in Toronto and Vancouver drive fastest-expanding adoption of smartphone-native parent portals.
Australia
Budget-constrained home-based providers in rural markets favor web-based platforms with minimal infrastructure requirements. The Office of the Australian Information Commissioner administers privacy safeguards for early-education student data. New South Wales and Victoria anchor demand for cloud-native attendance tracking among federally funded early learning programs.
Global Childcare Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized module integration and API-first architectures to circumvent incumbent platform dominance. The vendor landscape stratifies across three maturity tiers: legacy on-premise providers defending installed bases, SaaS-native challengers capturing mid-market share, and point-solution specialists unbundling communication features. Dominant competitive moves include strategic partnerships with state subsidy reporting systems and portfolio diversification into adjacent early-education verticals.
Within the specialized-module tier, Procare Software LLC and Jackrabbit Technologies Inc. exemplify divergent positioning strategies—Procare anchoring large licensed centers through deep administrative system integration, Jackrabbit occupying niche verticals where class-scheduling complexity extends into early childhood programming. Hi Mama Inc. represents the engagement-focused archetype, where parent-communication feature depth sustains renewal premiums above category benchmarks.
| Leading Market Players |
|---|
| Procare Software LLC |
| Lifecubby |
| EZChildTrack |
| Jackrabbit Technologies Inc. |
| Hi Mama Inc. |
| AIS Software |
| Bloomz Inc. |
| SofterWare Inc. |
| Orgamation Technologies |
| Others |
Supply & Pricing Matrix
Multi-location daycare chains in the United States concentrate procurement power and anchor the dominant subscription-tiered pricing model across the childcare management software market. Their volume purchasing and multi-year contract expectations compress margins for vendors while rewarding modular unbundling strategies.
Pricing Analysis
Distributor margins in the indirect channel typically capture 15-25 percent of end-user subscription value before SaaS-native vendors reach licensed centers. Three-tier pricing structure across premium, standard, and economy levels segments by feature depth, with biometric integrations and state subsidy reporting modules commanding tier premiums. Cost compression in the standard tier is intensifying because SaaS-native challengers eliminate legacy server licensing overhead. Home-based providers and parent cooperatives exhibit highest price sensitivity, while federally funded Head Start centers prioritize compliance certification over cost.
Supply Chain Analysis
Dual-sourcing requirements for biometric hardware components mandate multi-supplier qualification across fingerprint sensor and RFID reader vendors, preventing single-source lock-in for daycare chains. Cloud infrastructure draws from hyperscale data centers concentrated in the United States, Ireland, and Germany to satisfy GDPR data localization mandates. Serverless computing dependencies, API gateway services, and mobile SDK licensing constitute critical software inputs. Single-source vulnerability in biometric algorithm licensing creates supply chain risk for vendors serving European markets. Distribution runs through direct sales teams for enterprise chains and value-added resellers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where procurement priorities have shifted toward FERPA-certified platforms with pre-built state compliance modules. Premium specifications now dominate renewal decisions over baseline operational functionality.
For Market Incumbents: Deepen vertical integration into state subsidy reporting systems to defend against SaaS-native challengers exploiting API-first architectures. Anchor renewal rates by embedding biometric check-in workflows that resist modular replacement. Incumbent vendors must consolidate position through acquisition of specialized parent-engagement modules before point-solution specialists capture communication budgets. For New Entrants and Emerging Players: Begin with underpenetrated rural Head Start networks in non-metropolitan United States counties where legacy on-premise systems dominate and digital infrastructure investment lags. Federally qualified centers in Texas and Florida present the most penetrable segment given fragmented vendor presence and complex multi-source funding requirements. A mobile-first go-to-market angle targeting millennial parent demographics in Canadian urban markets bypasses incumbent desktop-dependent platforms. For Investors and Strategic Acquirers: Private equity firms with vertical software portfolios are the most active acquirer in this space, consolidating point-solution specialists into platform breadth. Long-term viability hinges on regulatory compliance moats deepening across fragmented United States state reporting requirements. Acquisition targets should demonstrate pre-built integrations with three or more state Child Care and Development Fund systems. Deviation in federal subsidy administration centralization would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable modular procurement and best-of-breed unbundling across mid-sized chains. |
| Geographic Expansion | Canadian provincial markets in Ontario and British Columbia reward hybrid deployment expertise with privacy controls. |
| Strategic Partnership | State subsidy reporting system alliances create non-replicable compliance moats for United States vendors. |
| Acquisition of Specialist Firm | Parent-engagement module depth sustains renewal premiums above operational platform benchmarks. |
| Product Launch | AI-driven predictive staffing tools differentiate vendors serving seasonal enrollment swing markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with daycare center administrators, state subsidy program officers, software procurement leads at multi-location chains, and early-education IT directors with secondary validation. Regulatory filings from the United States Department of Health and Human Services, GDPR implementation guidance from European data protection authorities, and vendor SEC disclosures anchored supply-side assessment. Bottom-up enrollment and procurement data triangulated against top-down market sizing from cloud infrastructure spending and SaaS subscription benchmarks.
Historical reference periods spanning pre-pandemic, pandemic-disrupted, and recovery phases anchored the forecast window across the analysis window. Segmentation dimensions modeled include deployment architecture, solution module type, facility category, and end-user stakeholder workflow. CAGRs derived from logistic adoption curves fitted to cloud migration patterns and parent-engagement module penetration rates. Forecast inputs incorporated state-level Child Care and Development Fund allocation trajectories and biometric hardware cost curves.
Caveats apply where federal subsidy administration consolidation or GDPR enforcement escalation could materially shift the outlook. Forecasts reflect assumptions about sustained fragmented state reporting requirements and continued hyperscale cloud infrastructure availability. Deviation in biometric data handling certification timelines across California, Illinois, and Texas would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Germany HR Payroll Software Market
Software & Services
Estate Management Software Market
Software & Services
Global UIUX Software Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Global Application Management Services Market
Software & Services
3D Animation Production Software Market
Software & Services
Broadcast Scheduling Software Market
Software & Services
Live Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Commercial Drone Software Market
Software & Services
Global Automotive Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Global Video Streaming Software Market
Software & Services
Construction Software As A Service Market