
 Global Contract Lifecycle Management Software Market | 2026-2036
Global Contract Lifecycle Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contract Lifecycle Management Software Market Foresight
North American cloud infrastructure expansion is reshaping how contract lifecycle management software reaches enterprise buyers. Icertis leverages deep vertical integration with Microsoft Azure to anchor its position in Fortune 100 procurement deployments. Sirion competes through specialized obligation management and post-signature performance tracking capabilities. Agiloft differentiates via no-code configurability that extends platform utility to mid-market legal operations without dedicated IT support.
Contract lifecycle management software orchestrates the creation, negotiation, execution, and analysis of legal agreements through centralized digital repositories with automated workflow engines, AI extraction engines, and clause libraries that enforce organizational playbooks. Cloud-based deployment dominates new implementations as hybrid work models require remote contract collaboration with enterprise-grade security protocols. Contract analytics represents the fastest-growing solution offering, where natural language processing parses obligation metadata and surfaces revenue leakage risks. Procurement functions generate the largest business function segment, though legal teams increasingly control platform selection as regulatory complexity intensifies across multinational operations.
The EU AI Act imposes transparency requirements on automated contract review tools, compelling vendors to document algorithmic decision pathways for European deployments. HIPAA in the United States and the SEC's cybersecurity disclosure rules shape how healthcare and publicly traded buyers evaluate data residency and access logging capabilities. Stakeholders must monitor how jurisdictional AI governance fragmentation affects product architecture roadmaps and cross-border implementation costs.
Market Dynamics
Generative AI integration into contract analytics engines is compressing negotiation cycles and redistributing procurement authority from legal operations to self-service business units.
Growth Catalysts
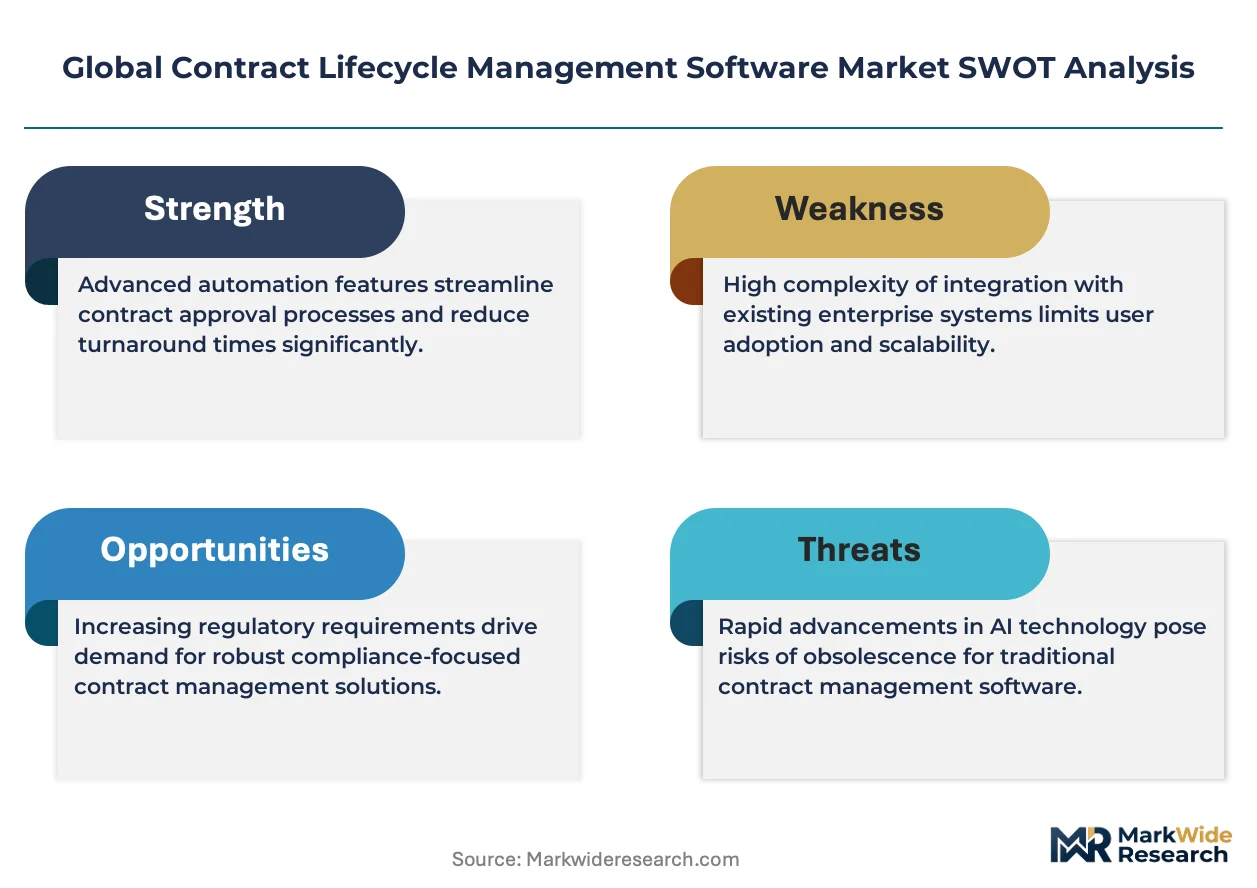
- EU AI Act transparency mandates:Automated contract review tools face algorithmic documentation requirements across European deployments, accelerating vendor investment in explainable NLP pipelines.
- Healthcare procurement digitization:HIPAA-covered entities in the United States require encrypted contract repositories with granular access logging, driving replacement of on-premise legacy systems.
- Natural language processing engines:Clause extraction accuracy improvements enable real-time obligation mapping, reducing manual review hours in high-volume procurement functions.
Market Restraints
- Cloud infrastructure concentration:Dominance of hyperscale providers in the United States and Ireland creates data residency compliance friction for Middle Eastern and Southeast Asian buyers.
- Integration complexity:Enterprise resource planning connectivity requires specialized middleware development, extending implementation timelines for SAP and Oracle environments.
- Substitution by native modules:Salesforce and Microsoft are embedding lightweight contract management into broader platform subscriptions, capturing price-sensitive mid-market demand.
Strategic Opportunities
- India's manufacturing expansion:Production-linked incentive scheme beneficiaries require localized contract governance for supplier qualification and duty drawback documentation.
- Convergence of CLM and ESG reporting:CSRD-aligned buyers in Germany and France seek automated carbon clause tracking and supplier sustainability obligation monitoring.
- Channel innovation via system integrators:Accenture and Deloitte are building vertical-specific implementation practices, opening enterprise access without direct vendor sales investment.
Industry Challenges
- AI governance expertise scarcity:Legal operations teams lack personnel capable of validating machine learning model outputs against organizational risk frameworks.
- Multi-jurisdictional compliance timelines:Simultaneous GDPR, HIPAA, and SEC cybersecurity disclosure requirements create conflicting data architecture specifications.
- Technical debt in legacy repositories:Decades of unstructured contract scans resist automated parsing, requiring expensive manual remediation before AI enablement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contract Lifecycle Management Software Market |
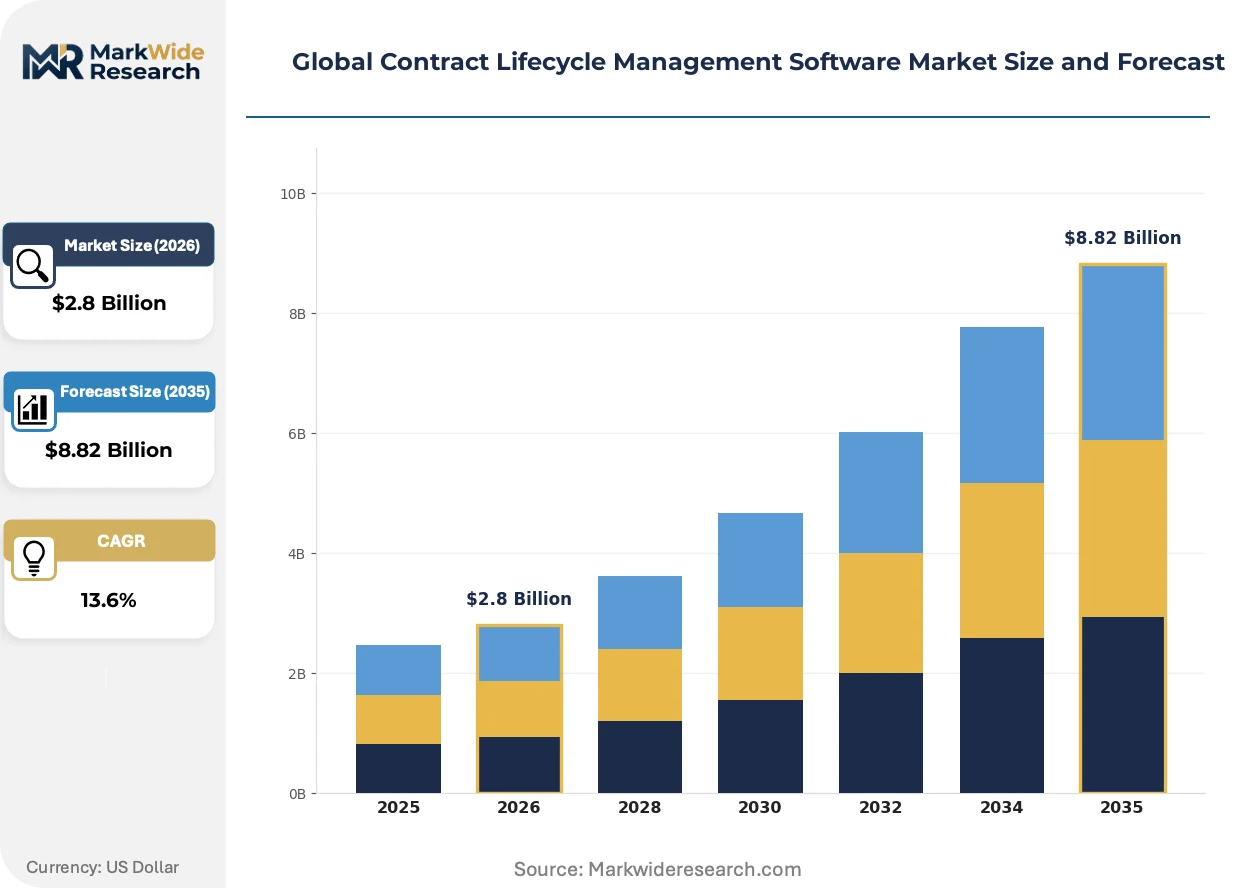
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud, Public Cloud Solution Offering: Contract Authoring, Contract Analytics, Compliance Management, Risk Management, Negotiation Management Business Function: Procurement, Sales, Legal, Finance, Vendor Management End User Industry: Information Technology, Telecommunications, Manufacturing, Transportation, Energy |
| Companies Covered | Ironclad, ContractPodAi, Sirion, Conga CLM, LinkSquares, Icertis, Agiloft, CobbleStone, DocuSign CLM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contract Lifecycle Management Software Market Shifts & Advancements
Foundation model architectures are transforming how contract intelligence systems process unstructured legal text, compressing the gap between raw document ingestion and actionable business insight.
Large language models with retrieval-augmented generation capabilities are rendering obsolete traditional template-based contract assembly workflows. Fortune 500 legal departments in the United States are deploying these systems for first-draft generation and risk-flagging at negotiation onset. The structural consequence is collapsing the traditional law firm markup layer for standard commercial agreements.
The EU AI Act's risk classification framework imposes conformity assessment obligations on high-risk automated decision systems, including certain contract approval workflows. Vendors must maintain technical documentation and human oversight protocols for European deployments. Healthcare and financial services buyers in Germany and the Netherlands are prioritizing vendors with established EU notified body relationships.
Self-service procurement models are displacing centralized legal review for low-risk purchase categories. Business unit leaders in technology and professional services sectors now execute standard NDAs and order forms without legal touch. This pattern is most pronounced in the United States, where procurement technology budgets have shifted from legal operations to revenue-generating functions.
Global Contract Lifecycle Management Software Market Segmentation
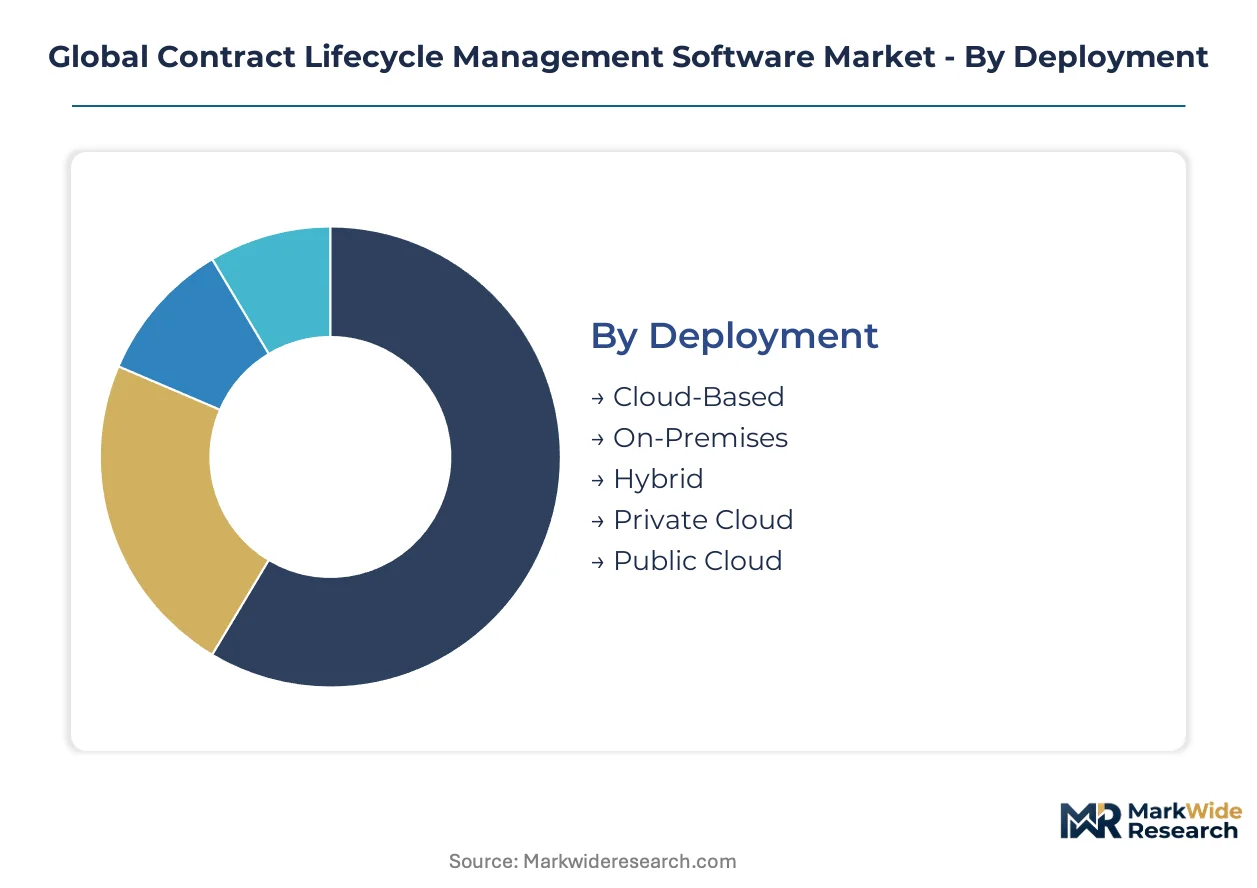
Segmentation in the contract lifecycle management software market reveals distinct procurement rhythms and technology refresh cycles. Deployment models and solution architectures determine implementation timelines, while business function ownership shapes feature prioritization and vendor selection criteria.
Deployment:
Cloud-based implementations compress deployment cycles to weeks, while legacy on-premises installations stretch across quarters. Hybrid architectures split the difference with phased migration timelines.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic feature updates and elastic scaling for seasonal contract volumes. United States-based Fortune 500 procurement teams favor this model for rapid rollout across distributed operations without capital infrastructure commitments.
- On-Premises:Dedicated hardware installations within client data centers satisfy stringent data residency mandates in regulated industries. German automotive manufacturers and French defense contractors maintain these deployments despite higher total cost of ownership.
- Hybrid:Sensitive contract data remains on-premises while collaboration tools leverage cloud connectivity. Japanese trading houses deploy this model to balance confidentiality with supplier accessibility.
- Private Cloud:Single-tenant cloud infrastructure dedicated to one organization with managed service oversight. Australian banking regulators encourage this architecture for financial services contract repositories.
- Public Cloud:Shared infrastructure with standardized security certifications and geographic redundancy. Indian IT services exporters select this option for cost efficiency in high-volume offshore contracting operations.
Cloud-Based deployments dominate installed base. Private Cloud is where expansion concentrates.
Solution Offering:
Feature modules vary dramatically in development maturity and customer willingness to pay, with analytics commanding premium pricing against commoditized authoring tools.
- Contract Authoring:Template libraries and clause assembly engines standardize agreement creation across business units. Mid-market legal operations in Canada leverage these tools to reduce external counsel dependency for routine commercial contracts.
- Contract Analytics:Natural language processing engines extract obligation metadata and surface revenue leakage risks. United Kingdom banking supervisors mandate these capabilities for systemic risk monitoring in derivatives documentation.
- Compliance Management:Automated regulatory tracking ensures contract terms align with evolving jurisdictional requirements. Brazilian healthcare distributors deploy these modules to manage ANVISA pharmaceutical licensing conditions.
- Risk Management:Counterparty exposure scoring and termination clause monitoring protect against financial and operational disruptions. South Korean conglomerates integrate these tools with enterprise risk management frameworks.
- Negotiation Management:Version control and redline automation streamline multi-party agreement refinement. Israeli technology startups utilize these features to accelerate venture financing documentation cycles.
Contract Authoring holds the largest deployment footprint. Contract Analytics is climbing the fastest as AI capabilities mature.
Business Function:
Budget authority and platform selection power shift across functions based on contract type complexity and regulatory exposure.
- Procurement:Source-to-contract workflows manage supplier qualification, RFP generation, and purchase order execution. Mexican manufacturing maquiladoras prioritize these capabilities for NAFTA compliance documentation.
- Sales:Quote-to-cash acceleration through standardized customer agreement templates and approval routing. SaaS vendors in Singapore deploy these tools to compress enterprise subscription closing cycles.
- Legal:Enterprise-wide contract governance with risk playbook enforcement and litigation hold management. Swiss pharmaceutical headquarters mandate legal department control for clinical trial agreements.
- Finance:Revenue recognition alignment and payment term optimization embedded in contract structures. Italian luxury goods houses integrate these modules with ERP for royalty calculation accuracy.
- Vendor Management:Post-execution performance monitoring and relationship scorecarding beyond contractual compliance. UAE sovereign wealth funds utilize these capabilities for portfolio company oversight.
Procurement functions control the majority of existing installations. Legal departments are gaining share fastest in regulated sectors.
End User Industry:
Vertical specialization requirements create divergent implementation priorities and integration complexity.
- Information Technology:Intellectual property licensing and software subscription management with rapid amendment cycles. Cloud-native vendors in Ireland structure deployments around GDPR Article 28 processor agreement automation.
- Telecommunications:Tower leasing and spectrum licensing with long-dated, high-value contractual assets. Saudi operators manage these documents under SFDA-equivalent communications authority oversight.
- Manufacturing:Supply chain contracting with quality specifications and just-in-time delivery terms. Vietnam's electronics assembly sector drives localized deployment growth.
- Transportation:Fleet leasing, logistics service agreements, and regulatory compliance documentation. Dutch port authorities coordinate multimodal contract visibility across North Sea trade corridors.
- Energy:Power purchase agreements and joint operating contracts with decade-plus durations. Norwegian offshore operators require these systems for petroleum taxation audit trails.
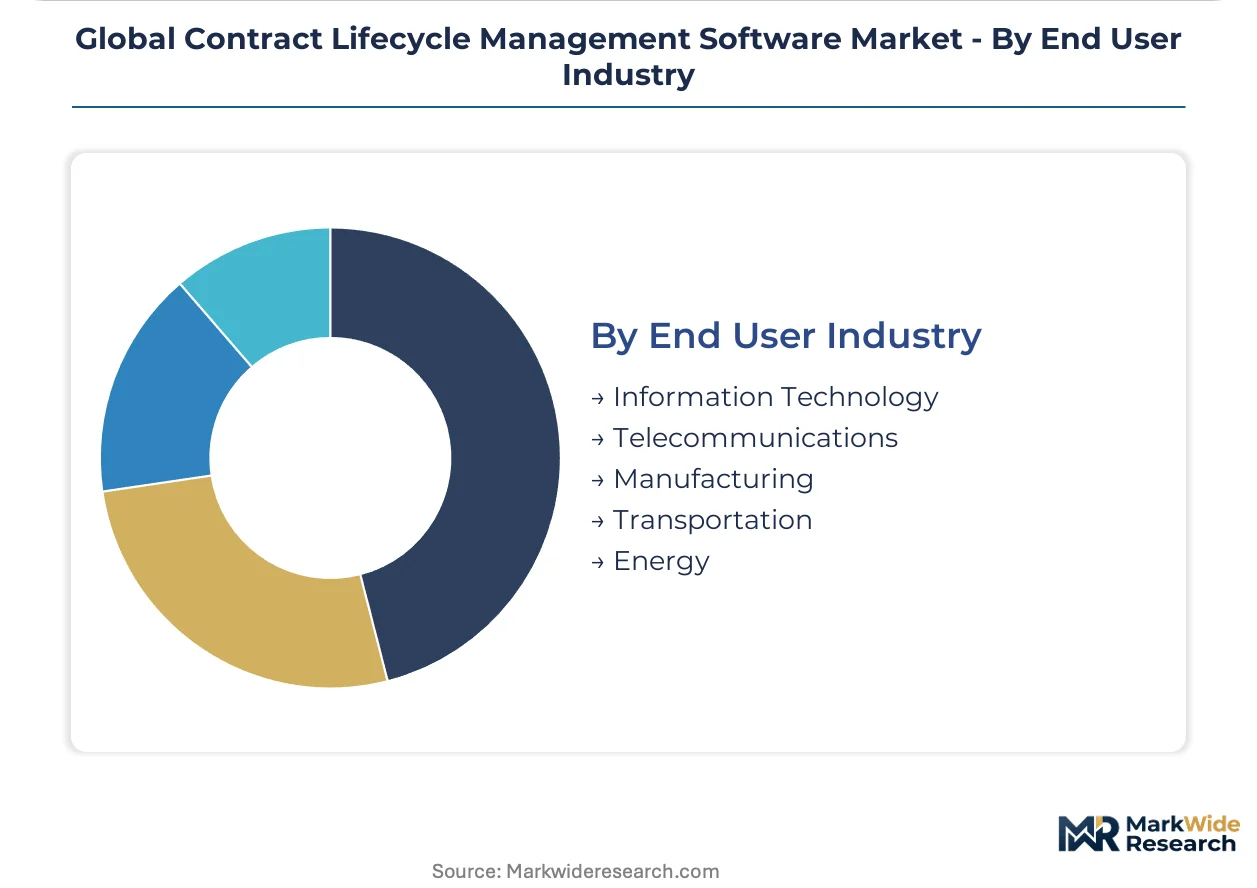
Information Technology accounts for the deepest penetration. Energy sector deployments are expanding most quickly amid contract portfolio consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentration in the United States and Ireland creates data residency friction for multinational buyers, while regulatory divergence across jurisdictions forces vendors to maintain parallel compliance architectures. Enterprise procurement teams in Germany, the United Kingdom, Japan, India, and Brazil drive differentiated deployment patterns based on local digital maturity and sector-specific mandates.
United States
Fortune 500 procurement teams replace legacy document management with integrated CLM suites at accelerating pace. SEC cybersecurity disclosure rules and HIPAA access logging requirements shape vendor selection criteria for healthcare and publicly traded buyers. Silicon Valley technology clusters and New York financial services hubs concentrate early generative AI adoption for contract analytics.
Germany
Automotive manufacturers and industrial conglomerates demand on-premises installations for stringent data sovereignty. CSRD-aligned buyers seek automated carbon clause tracking and supplier sustainability obligation monitoring under EU Green Deal implementation. Bavarian automotive headquarters and Baden-Württemberg industrial zones anchor high-security private cloud deployments.
United Kingdom
Banking supervisors mandate contract analytics capabilities for systemic risk monitoring in derivatives documentation. Post-Brexit regulatory divergence creates parallel compliance tracks for EU-facing and domestic operations. London financial services clusters drive premium-tier demand for real-time obligation extraction and counterparty exposure scoring.
Japan
Trading houses deploy hybrid architectures to balance confidentiality with supplier accessibility across keiretsu networks. METI industrial digitization incentives accelerate mid-market adoption of no-code configurable platforms. Tokyo-Osaka corporate corridors concentrate demand for post-signature performance monitoring and relationship scorecarding.
India
Production-linked incentive scheme beneficiaries require localized contract governance for supplier qualification and duty drawback documentation. IT services exporters select public cloud options for cost efficiency in high-volume offshore contracting. Bengaluru technology corridors and Mumbai financial districts drive SaaS-native deployment growth.
Global Contract Lifecycle Management Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with targeted workflow modules. The vendor base clusters around three strategic archetypes: horizontal enterprise suites with deep ERP connectivity, vertical specialists in obligation management and post-signature tracking, and no-code configurability providers serving mid-market legal operations. Dominant competitive moves include hyperscaler partnership anchoring and system integrator channel development through Accenture and Deloitte vertical practices.
Within the enterprise platform tier, Icertis and Sirion occupy anchor positions representing divergent specialization vectors. Agiloft exemplifies the configurability-focused archetype serving IT-constrained legal departments. Among component specialists, LinkSquares and ContractPodAi sit within the analytics-intensive segment where natural language processing capabilities determine competitive differentiation.
| Leading Market Players |
|---|
| Ironclad |
| ContractPodAi |
| Sirion |
| Conga CLM |
| LinkSquares |
| Icertis |
| Agiloft |
| CobbleStone |
| DocuSign CLM |
| Others |
Supply & Pricing Matrix
United States hyperscaler concentration in cloud infrastructure anchors margin capture downstream, with AWS, Azure, and Google Cloud controlling the substrate upon which CLM vendors build. This upstream consolidation funnels pricing power toward infrastructure providers while compressing software vendor margins.
Pricing Analysis
EU AI Act transparency mandates dictate the pricing tier structure for European deployments, requiring vendors to maintain explainable NLP documentation and human oversight protocols. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade compliance bundles from mid-market SaaS tiers. Cost compression in the mid-market is intensifying because Salesforce and Microsoft embed lightweight contract management into broader platform subscriptions. Procurement functions show highest price sensitivity, while legal departments in regulated healthcare and financial services demonstrate lowest sensitivity due to HIPAA and SEC cybersecurity disclosure requirements.
Supply Chain Analysis
United States export-control restrictions on advanced AI chips limit flows to Chinese CLM developers, constraining their ability to train competitive foundation models. Software supply chains draw from United States, Ireland, and India for cloud infrastructure, NLP engine development, and implementation services respectively. Dependencies include GPU clusters, pre-trained transformer architectures, and specialized legal domain datasets. Single-source vulnerability runs through NVIDIA's dominance in training hardware. Distribution runs through direct enterprise sales teams, system integrator channels, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native platform substitution from Salesforce and Microsoft threatens standalone CLM vendors, forcing incumbents to defend integration depth and vertical specialization.
For Market Incumbents: Entrench through exclusive system integrator relationships with Accenture and Deloitte vertical practices, and deepen API connectivity into SAP and Oracle ERP environments. Salesforce's embedded contract tools threaten mid-market share; counter by emphasizing AI governance documentation for EU AI Act compliance that native modules lack. For New Entrants and Emerging Players: Build out localized contract governance capabilities for India's production-linked incentive scheme beneficiaries, targeting manufacturing supplier qualification workflows. India's manufacturing digitization presents the most penetrable geography. Pursue channel partnerships with Indian system integrators rather than direct sales investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed no-code configurability providers serving IT-constrained mid-market legal operations. Five-to-ten year viability hinges on generative AI integration depth rather than template libraries. Watch for hyperscaler acquisition of obligation management specialists as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Establishes market access for high-risk automated contract approval workflows in Germany and France. |
| Generative AI Integration | Compresses first-draft generation cycles for Fortune 500 legal departments in Silicon Valley. |
| System Integrator Channel Partnership | Opens enterprise access through Accenture and Deloitte vertical-specific implementation practices. |
| Healthcare-Specific Compliance Module | Addresses HIPAA encrypted repositories and granular access logging for United States providers. |
| India Localization Investment | Captures production-linked incentive scheme contract governance demand in Bengaluru and Mumbai corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Interviews with legal operations directors, procurement technology officers, CLM platform engineers, and system integrator partners informed demand-side validation. Bottom-up triangulation across deployment models and solution offerings converged with top-down market sizing.
Forecast inputs span cloud-based, on-premises, hybrid, private cloud, and public cloud deployment architectures alongside contract authoring, analytics, compliance management, risk management, and negotiation management solution modules. CAGRs derive from segment-level growth rate reconciliation against macroeconomic indicators. AI governance fragmentation and generative AI adoption curves shape trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers into native contract management would shift outcomes. Material shifts in EU AI Act enforcement intensity or United States export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
POS Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Construction Suites Software Market
Software & Services
Global Student Information System Market
Software & Services
Global UIUX Software Market
Software & Services
App Building Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
North America Automotive Software Market
Software & Services
Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Procurement Software Market
Software & Services
Global Application Development Software Market
Software & Services
Global Neural Network Software Market