
 User Experience (UX) Research Software Market | 2026-2036
User Experience (UX) Research Software Market Size, Share, and Industry Trends Forecast 2026-2036
User Experience (UX) Research Software Market Analytics
Enterprise-grade functionality is unwinding the historical ceiling on UX research software pricing and capability expectations. Maze leverages its automated participant recruitment engine to dominate mid-market self-serve adoption. Qualtrics anchors enterprise-wide experience management programs that subsume standalone UX tools into broader analytics contracts. UserTesting competes through its integrated panel access and video analytics, sustaining premium positioning against point-solution rivals.
User Experience (UX) Research Software comprises cloud-native and on-premises platforms that capture behavioral signals, task-completion rates, and attitudinal feedback through moderated sessions, unmoderated tests, and survey instruments, with core technical parameters including screen-recording fidelity, sentiment-analysis latency, and API throughput for real-time data pipelines. The primary commercial purpose is reducing product-development risk by validating design decisions with empirical user evidence before engineering commitment. Cloud-based deployment leads in revenue contribution as security certifications mature, while usability testing captures concentrated margin pools due to specialized panel infrastructure requirements. Analytics platforms represent the fastest-expanding segment as product teams demand predictive models that connect UX metrics to business outcomes.
FDA guidelines on human factors engineering for medical-device interfaces shape validation protocols that UX research platforms must support in regulated health-technology deployments. The EU AI Act imposes transparency obligations on automated decision-support features within analytics platforms, directly affecting product roadmaps for vendors serving European enterprises. ISO 9241 ergonomic standards and Section 508 accessibility requirements further constrain interface-design validation workflows, creating compliance-driven demand for auditable research documentation. Stakeholders must monitor how emerging algorithmic-auditing obligations in multiple jurisdictions reshape platform architecture investments and participant-consent workflows.
Market Dynamics
Enterprise product teams now embed continuous UX validation within two-week sprint cycles, collapsing the historical gap between research insight and engineering commitment. This workflow compression forces platforms to deliver same-day recruiting, automated analysis, and direct Jira integration or lose procurement contests.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision-support features in analytics platforms face new disclosure obligations, driving replacement cycles for legacy tools that lack auditable consent chains.
- Agile transformation in financial services:Banks and insurers now staff permanent UX research pods, creating sustained demand for unmoderated testing infrastructure that matches software release velocity.
- Screen-recording fidelity advances:4K capture with sub-100ms latency enables mobile gesture analysis previously requiring lab hardware, expanding addressable use cases.
Market Restraints
- Panel infrastructure concentration:Specialist recruitment networks in the United States and United Kingdom capture 60-70% of qualified B2B participants, creating supply bottlenecks for niche professional segments.
- GDPR consent-chain complexity:Cross-border data transfers require participant re-consent for each jurisdiction, inflating project overhead and extending study timelines.
- Sentiment-analysis API costs:Cloud-native platforms face margin pressure from natural language processing compute charges that scale with video volume.
Strategic Opportunities
- Underpenetrated German Mittelstand:Mid-sized manufacturers lack dedicated UX functions, presenting whitespace for localized self-serve platforms with ISO 9241 compliance templates.
- Biometric-physiological convergence:Integration of eye-tracking hardware with emotion-recognition algorithms enables predictive frustration modeling before verbal feedback.
- FDA human-factors pre-submission pathways:Medical device vendors seek platforms that generate audit-ready documentation packages, commanding premium pricing against generalist competitors.
Industry Challenges
- Research-operations talent scarcity:Hybrid professionals who combine experimental design with data engineering command salaries that strain mid-market vendor economics.
- Legacy on-premises integration friction:Enterprises with air-gapped security requirements demand bespoke deployment architectures that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | User Experience (UX) Research Software Market |
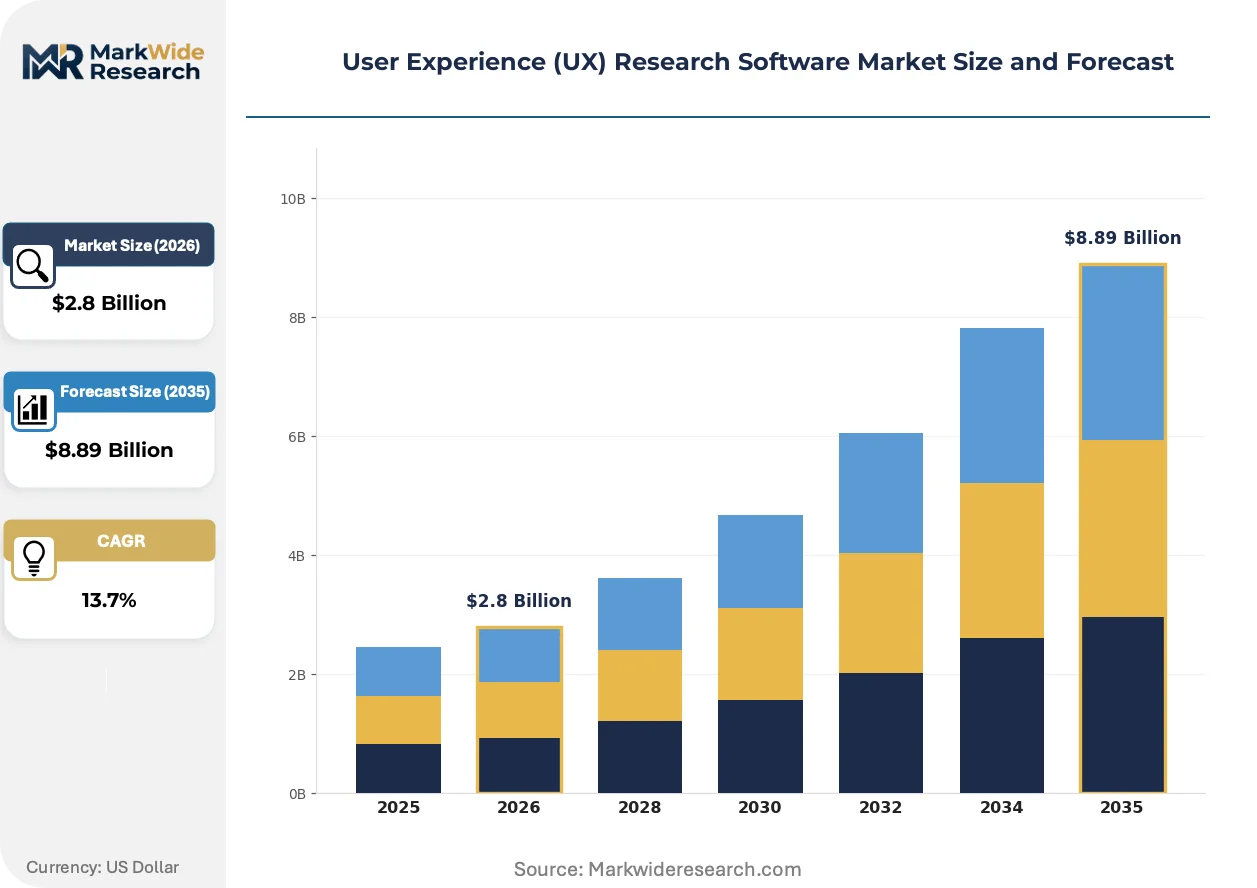
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Survey Tools, Usability Testing, Analytics Platforms, Prototyping Software Deployment: Cloud-based, On-premises, Hybrid Solutions, Open-source End User: Design Agencies, Enterprises, Startups, Academic Institutions Integration Level: API Integrations, Third-party Software, Standalone Applications, Cross-platform |
| Companies Covered | Maze, Hubble, UserTesting, Lookback, UseHubble, Great Question, Userlytics, Validately, Qualtrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
User Experience (UX) Research Software Market Evolving Landscape
Artificial intelligence is compressing the research lifecycle from weeks to hours, forcing incumbents to rebuild core workflows around generative synthesis rather than incremental feature addition.
Generative AI is decomposing traditional video analysis workflows. Product teams at technology firms and design consultancies now receive automated highlight reels and thematic coding within minutes of session completion. This capability collapses the labor cost structure that previously protected full-service agencies, enabling software vendors to capture budget previously allocated to professional services.
The EU AI Act imposes algorithmic transparency obligations on automated insight generation. Platforms serving European enterprises must document training data provenance and decision logic for sentiment classification models. Analytics vendors are responding by building human-in-the-loop validation steps and auditable consent workflows that satisfy CNIL and BfDI enforcement expectations.
Buyer preference is hardening around outcome-linked pricing structures. Enterprise procurement teams now negotiate contracts where fees scale with validated design decisions rather than seat counts or test volumes. This shift is most visible in United States technology firms, where product leadership demands direct attribution between research spend and feature adoption metrics.
User Experience (UX) Research Software Market Segmentation
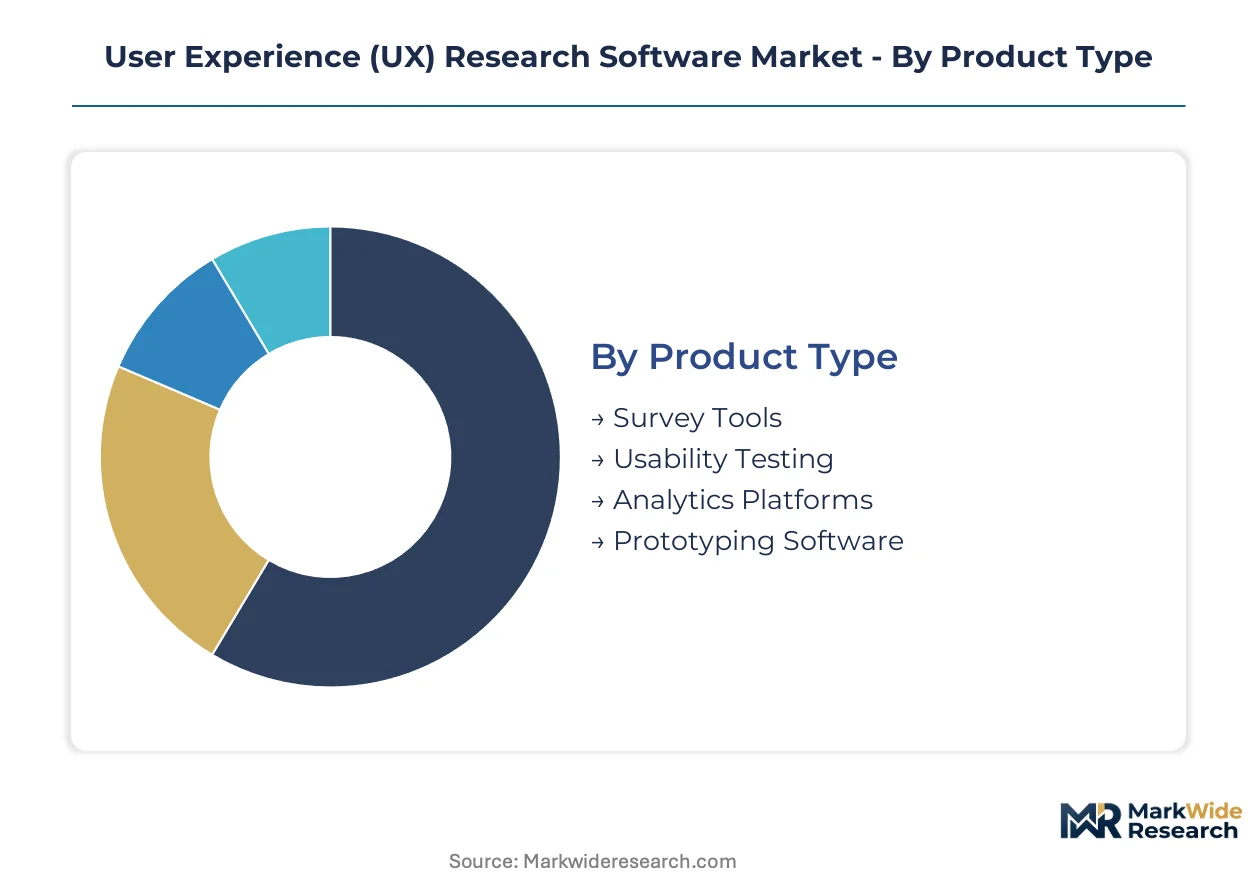
UX research software segments diverge sharply on compliance architecture. Regulated industries impose documentation standards that reshape platform selection across every category.
Product Type:
FDA human-factors validation requirements and EU AI Act algorithmic transparency obligations create divergent capability thresholds across product categories.
- Survey Tools:Web-native instruments capture attitudinal data through branching logic and quota management. GDPR consent-chain automation dominates procurement criteria for European enterprises. Established volume favors survey tools; emerging adoption favors analytics platforms.
- Usability Testing:Platforms combine screen-recording fidelity with participant recruitment infrastructure. Medical device manufacturers in the United States demand audit-ready documentation packages that satisfy FDA pre-submission pathways. Steepest expansion trajectory belongs to usability testing as gesture-analysis capabilities expand mobile validation use cases.
- Analytics Platforms:Predictive models connect behavioral signals to business outcomes through machine-learning pipelines. CNIL and BfDI enforcement expectations force human-in-the-loop validation steps for European deployments.
- Prototyping Software:Design-to-test workflows enable rapid iteration before engineering commitment. Startups and design agencies concentrate demand for browser-based collaboration features.
Margin concentration follows panel infrastructure requirements; self-serve survey tools compete on price while specialized testing platforms command premium positioning.
Deployment:
Security certification maturity determines cloud adoption velocity across enterprise segments.
- Cloud-based:Multi-tenant architectures with SOC 2 Type II and ISO 27001 certifications dominate procurement for technology firms. United States enterprises lead volume as compliance frameworks mature.
- On-premises:Air-gapped installations serve financial services and defense contractors with data sovereignty requirements. Revenue recognition delays from bespoke deployment architectures strain vendor economics.
- Hybrid Solutions:Sensitive participant data remains on-premises while analytics processing leverages cloud elasticity. German Mittelstand manufacturers favor this architecture for ISO 9241 compliance templates.
- Open-source:Self-hosted alternatives attract academic institutions with limited procurement budgets. Community maintenance creates security patch latency that enterprises avoid.
Deployment preference tracks organizational security posture; regulated sectors retain on-premises control while agile teams prioritize cloud velocity.
End User:
Research-operations maturity separates buyer segments on workflow integration depth.
- Design Agencies:Project-based procurement demands rapid study turnaround and client-facing reporting dashboards. United Kingdom consultancies anchor volume for unmoderated testing infrastructure.
- Enterprises:Permanent UX research pods within financial services and technology firms create sustained demand for platform seats. Jira and Slack integration is non-negotiable for procurement approval.
- Startups:Self-serve adoption concentrates in venture-backed technology companies with product-led growth strategies. Maze's automated recruitment engine dominates this segment.
- Academic Institutions:IRB compliance workflows and student licensing programs shape platform requirements. Eye-tracking hardware integration supports experimental psychology departments.
Enterprise contracts anchor vendor revenue stability; startup acquisition costs challenge unit economics without clear expansion pathways.
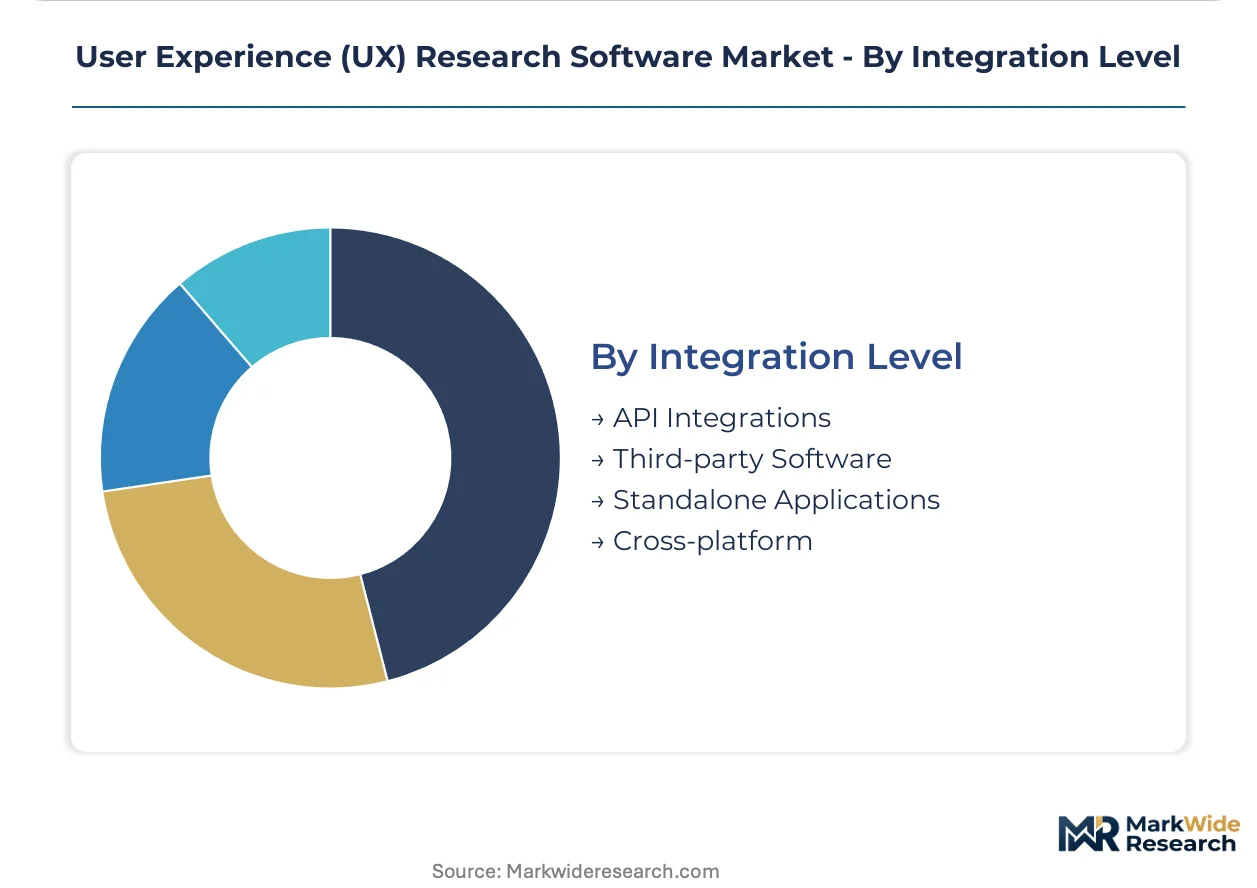
Integration Level:
Workflow compression in agile environments elevates API throughput to critical selection criteria.
- API Integrations:Real-time data pipelines feed product analytics warehouses and activation platforms. Technology firms in the United States demand sub-100ms latency for session event streaming.
- Third-party Software:Pre-built connectors to Figma, Miro, and Notion reduce implementation friction. Design agencies prioritize this category for cross-tool collaboration.
- Standalone Applications:Point solutions without ecosystem connectivity serve occasional researchers with simple study requirements. Price sensitivity concentrates demand at the low end.
- Cross-platform:Native iOS, Android, and desktop capture capabilities support mobile-first product validation. Gesture-analysis accuracy determines competitive positioning.
Integration depth correlates with contract value; standalone tools face displacement as platform consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantial net exports in UX research software while importing specialized analytics capabilities from European vendors. Trade flows concentrate around cloud infrastructure licensing and panel data services rather than packaged software shipments.
United States
Technology firms in Silicon Valley and Seattle sustain procurement volumes for unmoderated testing platforms. FDA human-factors validation requirements shape platform selection for medical-device startups in Boston and Minneapolis. Austin and New York City anchor design consultancy clusters that drive mid-market adoption.
Germany
Automotive manufacturers in Stuttgart and Munich demand ISO 9241-compliant documentation for HMI validation workflows. The BfDI enforces strict consent-chain requirements for biometric data processing in analytics platforms. Berlin and Hamburg host emerging SaaS vendors targeting Mittelstand manufacturers with localized compliance templates.
United Kingdom
Financial services firms in London maintain permanent UX research pods for digital banking validation. The Information Commissioner's Office scrutinizes cross-border data transfers under post-Brexit GDPR arrangements. Manchester and Edinburgh concentrate design agency demand for rapid-turnaround testing infrastructure.
Japan
Consumer electronics manufacturers in Tokyo and Osaka require gesture-analysis capabilities for mobile interface validation. METI guidelines on human-centered design influence enterprise procurement criteria for domestic deployments. Kyoto and Fukuoka host specialized usability labs serving automotive and gaming sectors.
India
IT services firms in Bangalore and Hyderabad build offshore UX capabilities for global technology clients. The Digital Personal Data Protection Act reshapes consent management requirements for multinational platform deployments. Mumbai and Delhi-NCR concentrate startup demand for self-serve research tools with rupee-denominated pricing.
User Experience (UX) Research Software Market Competitive Landscape
Listed leaders compete with private specialists across pricing architecture and deployment flexibility. The vendor base separates into three tiers: enterprise experience management suites, mid-market automated platforms, and specialized panel-access services. Strategic archetypes include vertical-integrated research networks, API-first developer tools, and compliance-focused documentation engines. Consolidation pressures favor acquisition of panel infrastructure and sentiment-analysis capabilities.
Within the mid-market automated tier, Maze and Hubble occupy positions exemplifying self-serve recruitment velocity. UserTesting anchors the premium integrated-panel segment with video analytics infrastructure. These three entities represent divergent bets on workflow compression: Maze emphasizes same-day recruiting automation, Hubble targets continuous discovery integration, and UserTesting sustains premium positioning through specialized participant access.
| Leading Market Players |
|---|
| Maze |
| Hubble |
| UserTesting |
| Lookback |
| UseHubble |
| Great Question |
| Userlytics |
| Validately |
| Qualtrics |
| Others |
Value Network & Pricing Analysis
Automated participant recruitment engines substituting for traditional panel broker networks are redrawing supply geography toward cloud-native platform vendors while collapsing the labor-cost premiums that once sustained full-service agency pricing. This substitution simultaneously concentrates procurement leverage among United States-based recruitment infrastructure providers and compresses margins for European vendors facing GDPR consent-chain complexity.
Pricing Analysis
Enterprise product teams anchor pricing structures around outcome-linked contracts where fees scale with validated design decisions rather than seat counts or test volumes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant documentation packages from self-serve survey instruments. Cost compression in the mid-market tier is intensifying because automated synthesis tools collapse the labor cost structure that previously protected full-service agencies. Startup procurement teams exhibit highest price sensitivity, while medical device manufacturers demonstrate lowest sensitivity due to audit-ready documentation requirements.
Supply Chain Analysis
Just-in-time participant recruitment preferences dominate agile product teams, forcing platforms to maintain elastic panel capacity rather than strategic stockpiles of pre-qualified segments. Supply concentrates in the United States and United Kingdom, where specialist recruitment networks capture qualified B2B participants for technology and financial services verticals. Raw material dependencies include cloud compute infrastructure, natural language processing API access, and video storage bandwidth. Single-source vulnerability in niche professional segments creates supply bottlenecks for specialized B2B panels. Distribution runs through direct SaaS sales motions and self-serve onboarding funnels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
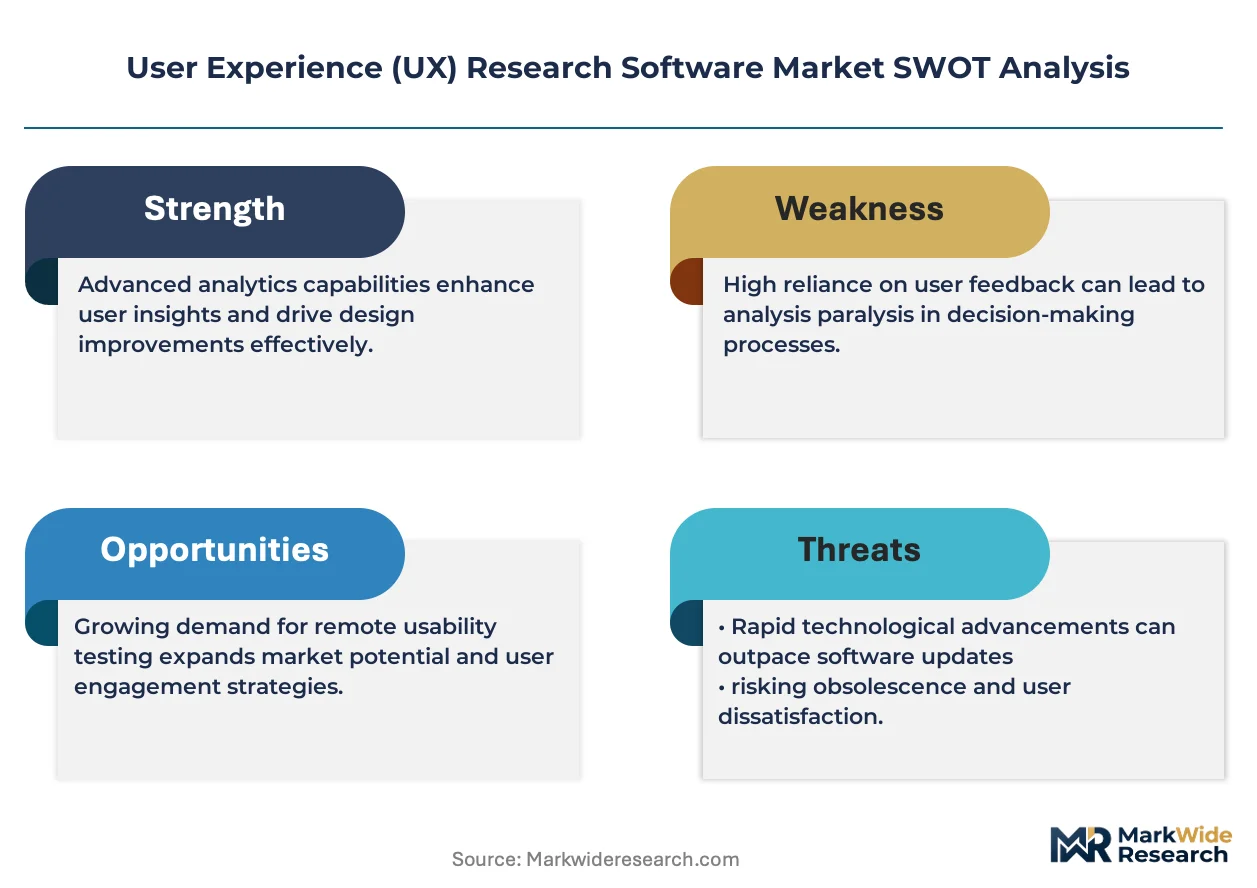
This market sits in early-cycle expansion as enterprise product teams embed continuous UX validation within two-week sprint cycles, creating sustained procurement velocity for platforms that deliver same-day recruiting and automated analysis.
For Market Incumbents: Compound defensive positioning through backward integration into specialized panel infrastructure and certification investment for FDA human-factors validation workflows. Threat from automated synthesis tools collapsing labor cost structures demands preemptive capability acquisition in generative AI. Capacity addition in German-speaking markets addresses BfDI consent-chain requirements before enforcement hardens.
For New Entrants and Emerging Players: Anchor in underpenetrated German Mittelstand manufacturers lacking dedicated UX functions, where localized self-serve platforms with ISO 9241 compliance templates face minimal incumbent saturation. White-space targets include biometric-physiological convergence for predictive frustration modeling and audit-ready documentation packages for medical device pre-submission pathways. Go-to-market motion should emphasize rupee-denominated pricing for Indian IT services firms building offshore UX capabilities.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors acquisition of panel infrastructure and sentiment-analysis capabilities. Long-term viability over the next decade hinges on regulatory compliance architecture as EU AI Act transparency mandates reshape product roadmaps. Acquisition target archetype includes mid-market automated platforms with elastic recruitment engines. Signal to watch is CNIL and BfDI enforcement intensity crossing thresholds that trigger replacement cycles for legacy tools lacking auditable consent chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Direct Jira and Slack connectivity satisfies enterprise procurement non-negotiables for workflow compression. |
| Acquisition of Specialist Firm | Panel infrastructure purchases address supply bottlenecks in niche B2B professional segments. |
| Regulatory Compliance Investment | FDA human-factors documentation capabilities command premium positioning against generalist competitors. |
| Geographic Expansion | Localized compliance templates for German Mittelstand manufacturers capture whitespace in manufacturing verticals. |
| Strategic Partnership | Eye-tracking hardware integration enables predictive frustration modeling before verbal feedback capture. |
Research Methodology
Initial hypotheses were tested against primary input from product operations leads, UX research directors, enterprise procurement officers, and platform engineering managers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of SEC filings, hyperscaler capex disclosures, App Annie mobile analytics data, and FDA human-factors submission databases. Bottom-up sizing of vendor-reported seat counts and top-down triangulation against enterprise software spending patterns ensured cross-verification.
Variance decomposition across deployment models, organization size tiers, vertical industry segments, integration complexity levels, and regional adoption patterns shaped the analytical framework. CAGRs were derived through logistic adoption curve fitting against empirical procurement velocity data across the analysis window. Forecast inputs incorporated panel infrastructure capacity constraints and cloud compute cost trajectories for natural language processing workloads.
Decision-makers should treat outputs as directional under assumptions of sustained agile transformation in financial services and technology sectors; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding EU AI Act enforcement timelines and FDA guidance stability. Revision becomes warranted when sentiment-analysis API cost trajectories cross thresholds that materially alter platform margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Online OCR Software Market
Software & Services
E-Clinical Solution Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Email Applications Market
Software & Services
Time and Attendance Software Market
Software & Services
Web Scraping Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Entity Management Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Mainframe Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Digital Illustration App Market