
 Workflow Automation and Optimization Software Market | 2026-2036
Workflow Automation and Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Workflow Automation and Optimization Software Market Outlook
Subscription-based SaaS financing is rewriting competitive dynamics in workflow automation by lowering capital barriers for mid-market buyers. UiPath leverages its robotic process automation specialization to anchor enterprise accounts across manufacturing verticals. Zapier competes through deep integration libraries that sustain its position among small businesses and marketing teams. ServiceNow dominates IT service management workflows while extending platform capabilities into broader process orchestration.
Workflow automation and optimization software orchestrates rule-based task execution, conditional logic routing, and system-to-system API connectivity to eliminate manual handoffs and reduce process latency. The technology typically deploys through visual drag-and-drop interfaces with pre-built connectors to enterprise applications such as ERP, CRM, and HRIS platforms, serving primarily to compress cycle times and enforce compliance in high-volume operational environments. Cloud-Based and SaaS deployment models are capturing the fastest expansion as IT departments prioritize elastic scaling and reduced infrastructure maintenance overhead. Task Automation solutions lead current revenue pools while Process Optimization segments attract margin-rich consulting and implementation services. Large Enterprises remain the dominant buyer class, though Small Businesses represent the fastest-growing adoption cohort as low-code interfaces democratize access.
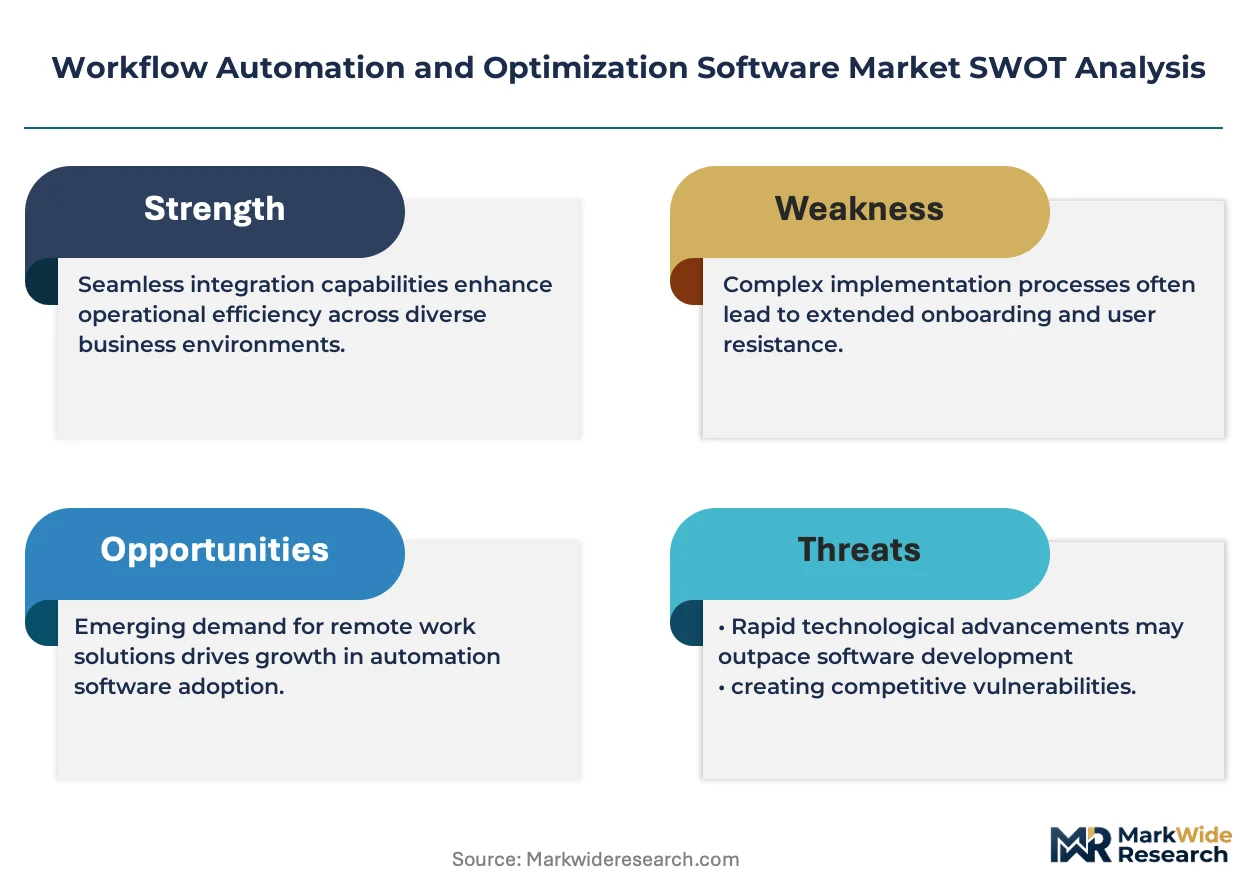
The EU AI Act and GDPR compliance requirements are reshaping product roadmaps for vendors serving European enterprises, particularly around audit trails and automated decision transparency. In the United States, SEC disclosure rules and HIPAA technical safeguards drive demand for governance layers within automation platforms. India's Digital Personal Data Protection Act and BIS cloud standards are accelerating localization investments among multinational software providers. Stakeholders must monitor how divergent regulatory timelines across these jurisdictions fragment platform standardization and inflate compliance engineering costs.
Market Dynamics
Cloud migration mandates under the EU AI Act and comparable data sovereignty frameworks are forcing wholesale replacement of on-premise workflow infrastructure, compressing vendor sales cycles while elevating compliance engineering to a primary procurement criterion.
Growth Catalysts
- Healthcare RPA adoption:Patient scheduling and claims processing automation is accelerating across hospital networks as labor shortages bite into operational capacity.
- EU AI Act transparency requirements:Automated decision audit trails are becoming mandatory for enterprises deploying algorithmic workflows, expanding addressable market for governance-layer vendors.
- India's Digital Personal Data Protection Act:Localization mandates are compelling multinational software providers to establish domestic cloud infrastructure, creating implementation service opportunities.
Market Restraints
- Legacy system integration costs:SAP and Oracle ERP estates require expensive API middleware to connect with modern automation platforms, inflating total cost of ownership.
- Talent concentration in Bangalore and San Francisco:Workflow architects and RPA engineers cluster in narrow geographic corridors, constraining delivery capacity for mid-market implementations.
- GDPR fine exposure:Automated personal data processing carries liability risks up to four percent of global revenue, slowing adoption in privacy-sensitive European healthcare and financial services.
Strategic Opportunities
- Small business low-code penetration:Visual drag-and-drop interfaces are democratizing access beyond enterprise IT departments into founder-led operations.
- Process mining convergence:Discovery-layer analytics layered atop execution engines enables continuous optimization rather than one-time automation.
- US SEC climate disclosure rules:Sustainability reporting automation is emerging as a compliance-driven application segment with premium pricing tolerance.
Industry Challenges
- Workflow architect scarcity:Hybrid skill sets combining business process expertise with API configuration and data modeling command salary premiums that squeeze project margins.
- Multi-cloud orchestration complexity:Enterprises running workloads across AWS, Azure, and GCP require abstraction layers that fragment vendor roadmaps and delay feature releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workflow Automation and Optimization Software Market |
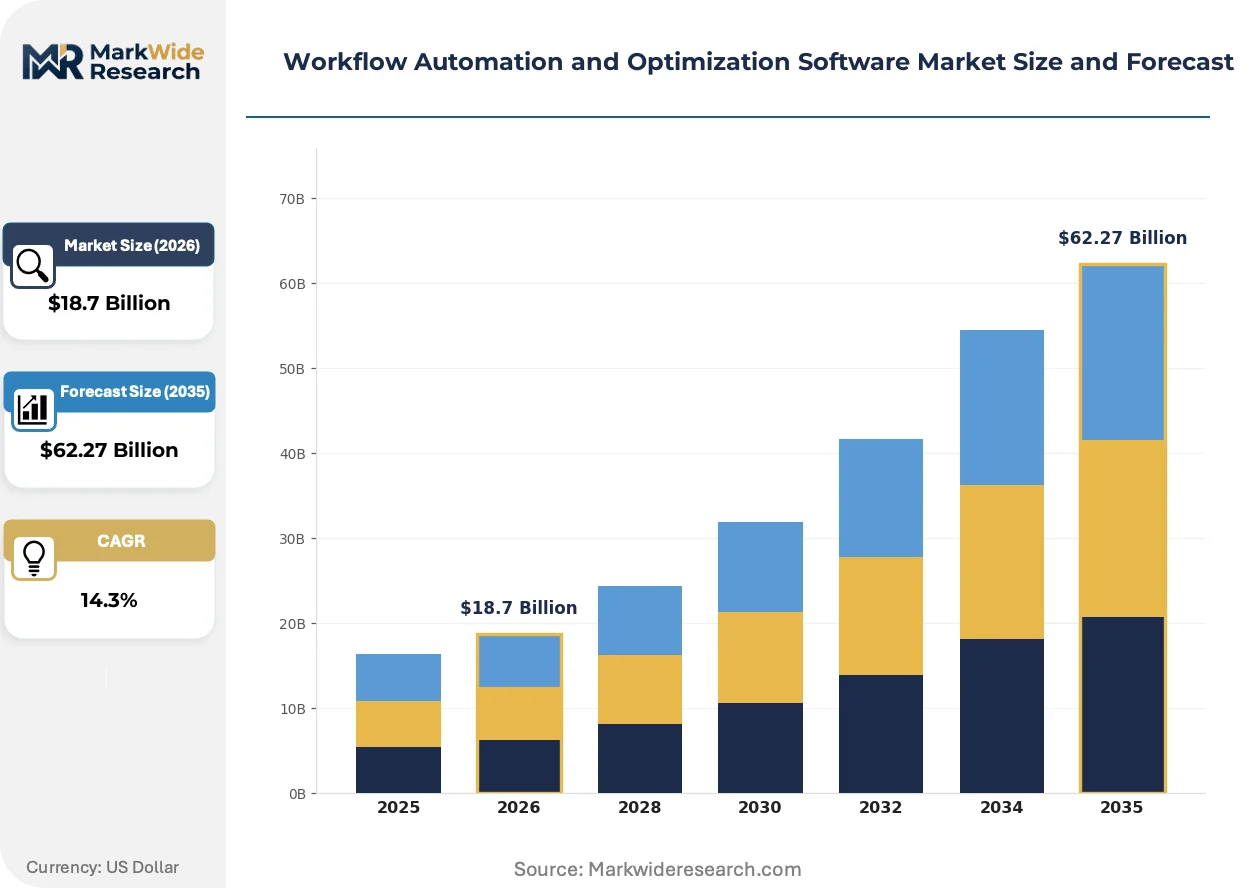
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $62.27 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Task Automation, Process Optimization, Workflow Management, Integration Tools End User: Small Businesses, Large Enterprises, Government Agencies, Non-Profit Organizations Deployment Model: On-Premises, Cloud-Based, Hybrid Solution, SaaS Industry Vertical: Healthcare, Manufacturing, Finance, Education |
| Companies Covered | Zapier, Blue Prism, UiPath, n8n, Make, Automation Anywhere, Workato, ServiceNow, Microsoft Power Automate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workflow Automation and Optimization Software Market Strategic Shifts
Agentic AI architectures are displacing rule-based automation, enabling systems to handle exception-heavy processes without explicit programming. This shift is compressing implementation timelines while expanding the universe of automatable work.
Large language model orchestration is migrating from experimental pilots to production deployments in customer service and document processing. Mid-market enterprises are adopting these capabilities fastest, drawn by reduced training data requirements. The technology is migrating from proof-of-concept budgets into operational expenditure lines, normalizing AI-native workflows as standard infrastructure.
The EU AI Act's risk classification system is forcing vendors to reengineer audit logging and human oversight mechanisms. High-risk automation applications in credit scoring and recruitment now require conformity assessments before deployment. European financial services and HR technology buyers are prioritizing platforms with pre-certified compliance modules.
Subscription financing is displacing perpetual license procurement in enterprise software sales. Finance teams prefer operational expenditure treatment for automation investments, particularly in manufacturing verticals with cyclical capital allocation. Germany and the United States show the fastest rotation toward consumption-based pricing models.
Workflow Automation and Optimization Software Market Segmentation
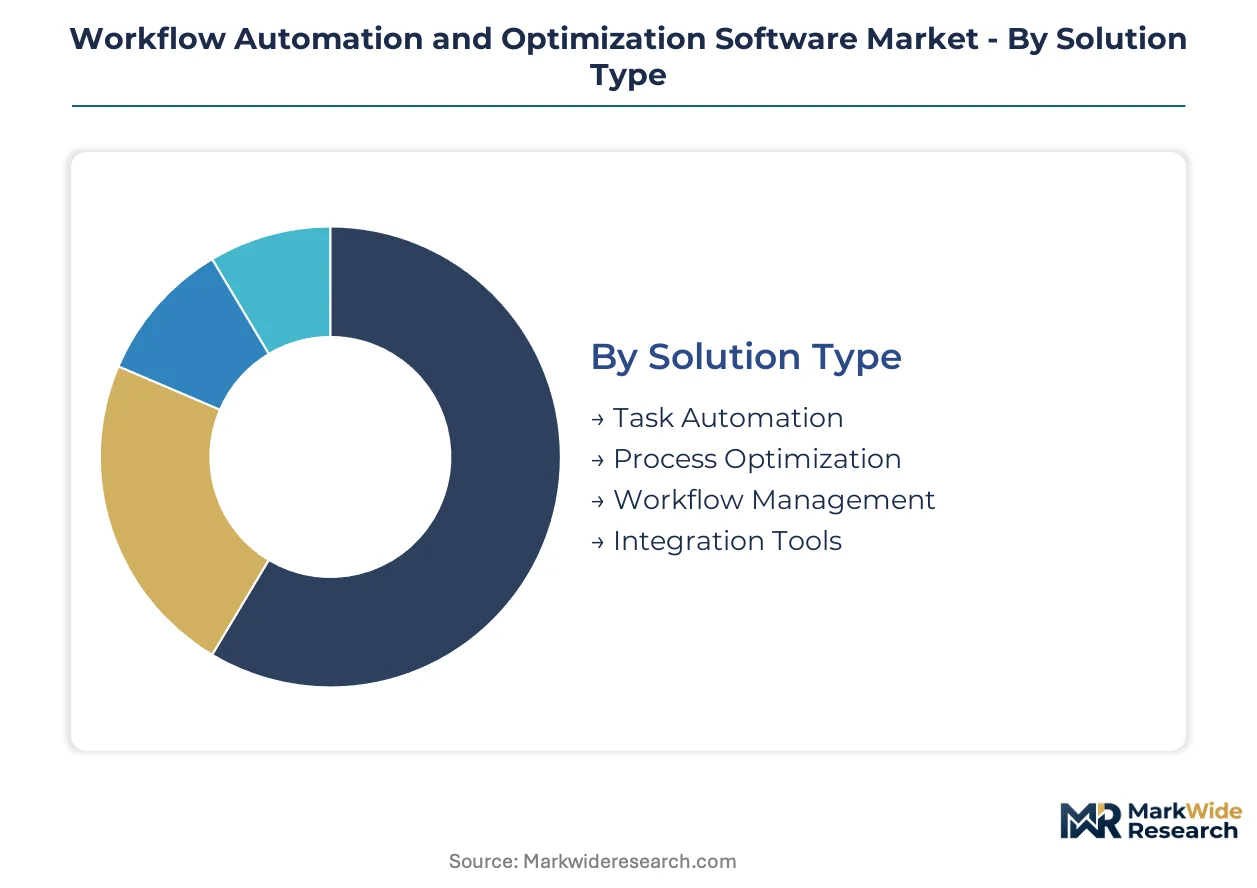
Workflow automation vendors architect product portfolios around distinct operational pain points and buyer maturity levels. Segment boundaries increasingly blur as platforms consolidate task execution, process intelligence, and governance layers into unified stacks.
Solution Type:
Application focus determines pricing architecture and implementation complexity across buyer tiers.
- Task Automation:Rule-based bots execute repetitive data entry, file transfers, and system notifications through scheduled triggers or event-driven logic. Healthcare revenue cycle teams in the United States deploy these tools to accelerate claims status checks while HIPAA audit trails satisfy compliance officers. Task Automation holds installed capacity. Process Optimization is rotating up the share rankings.
- Process Optimization:Discovery engines map actual workflow paths against documented procedures, identifying bottlenecks and compliance deviations through event log analysis. German automotive suppliers leverage these capabilities to compress order-to-delivery cycles under CSRD transparency mandates. Process mining convergence with execution layers is expanding addressable spend beyond IT into operations budgets.
- Workflow Management:Human-in-the-loop orchestration coordinates approvals, escalations, and exception handling across distributed teams.
- Integration Tools:API middleware and pre-built connectors bridge legacy ERP estates with cloud-native applications.
Task Automation commands current revenue pools. Process Optimization is climbing the fastest as continuous improvement methodologies displace one-time automation projects.
End User:
Customer scale dictates sales motion design, from self-service onboarding to enterprise transformation consulting.
- Large Enterprises:Global procurement teams negotiate platform-wide licenses spanning multiple business units and geographies. These buyers demand multi-tenant architectures, granular role-based access controls, and pre-certified compliance modules for EU AI Act and SEC disclosure requirements. Implementation timelines stretch 12-18 months with dedicated customer success resources.
- Small Businesses:Founder-operated companies adopt low-code interfaces through credit-card subscriptions without IT intermediation. India's digitizing services sector represents concentrated demand as UPI-integrated workflows replace manual reconciliation. Visual drag-and-drop configuration compresses time-to-value to days rather than quarters.
- Government Agencies:Public procurement cycles and sovereignty requirements favor vendors with domestic hosting certifications.
- Non-Profit Organizations:Constrained budgets drive preference for freemium tiers and grant-funded implementation support.
Large Enterprises anchor vendor revenue. Small Businesses are gaining share fastest as product-led growth motions mature.
Deployment Model:
Infrastructure location tradeoffs reflect data gravity, regulatory jurisdiction, and capital allocation preferences.
- Cloud-Based:Elastic compute resources scale with transaction volumes without upfront hardware commitments. EU AI Act transparency requirements and GDPR data residency rules are accelerating European enterprise migration from on-premise estates to region-locked cloud instances. Finance teams favor operational expenditure treatment aligned with cyclical manufacturing budgets.
- SaaS:Multi-tenant architectures deliver continuous feature updates without customer-managed maintenance windows. India's Digital Personal Data Protection Act localization mandates are compelling multinational providers to establish domestic cloud regions, creating implementation service opportunities for local systems integrators. Subscription financing is displacing perpetual licenses across buyer tiers.
- On-Premises:Air-gapped installations persist in defense and classified research environments with strict data sovereignty requirements.
- Hybrid Solution:Split architectures process sensitive data locally while leveraging cloud analytics for non-critical workloads.
Cloud-Based carries dominant transaction volume. SaaS is expanding most quickly as consumption-based pricing aligns vendor incentives with customer outcomes.
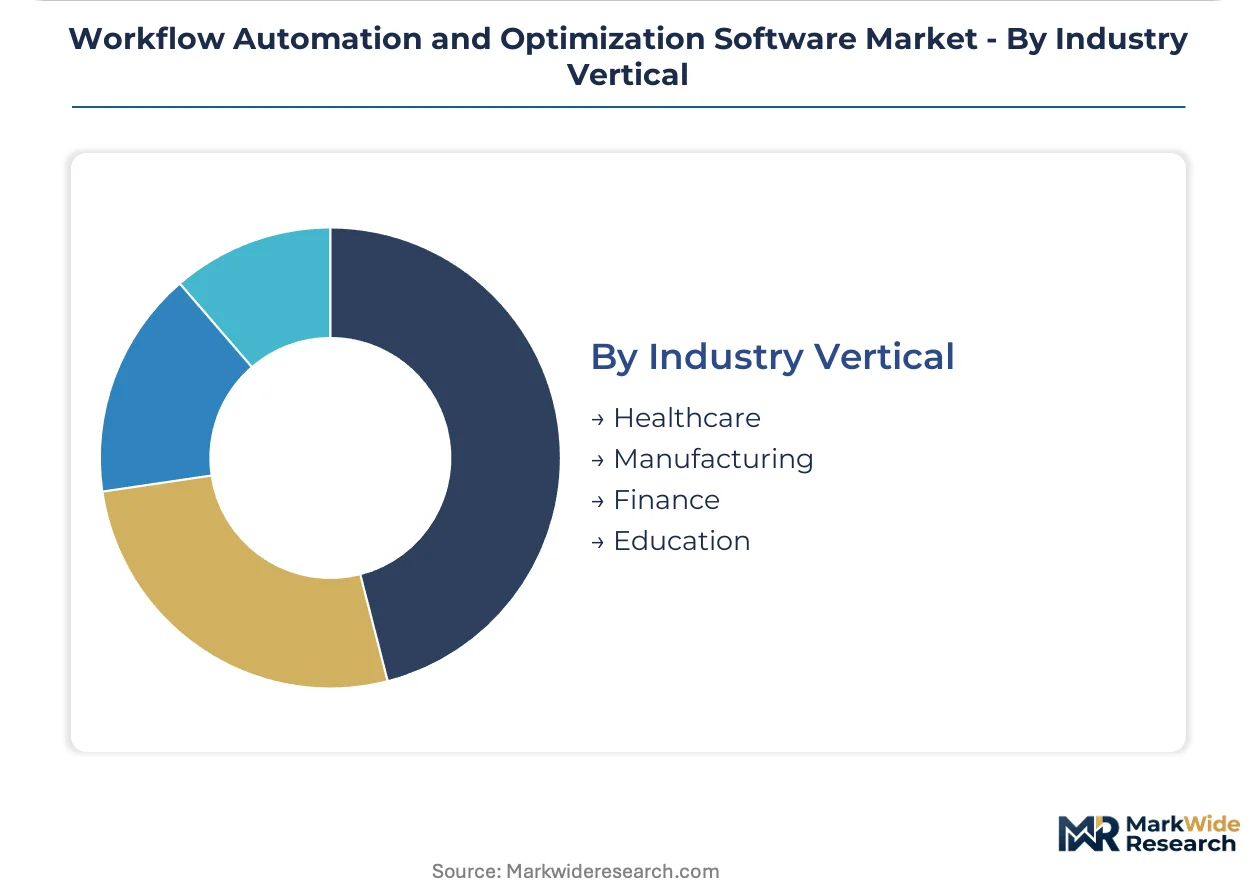
Industry Vertical:
Sector-specific compliance regimes and operational cadences shape feature prioritization and vertical solution packaging.
- Healthcare:Patient scheduling, prior authorization, and claims processing automation address labor shortages biting into hospital network capacity. HIPAA technical safeguards and FDA software validation requirements elevate governance-layer procurement criteria above pure cost reduction. RPA adoption is accelerating across United States health systems.
- Manufacturing:Shop-floor integration with MES and SCADA systems demands real-time data streaming and edge computing compatibility. German industrial clusters under EU Green Deal pressure automate energy monitoring and carbon accounting workflows to satisfy CSRD disclosure timelines. Cyclical capital allocation preferences favor subscription pricing.
- Finance:Algorithmic trading, fraud detection, and regulatory reporting workflows require sub-second latency and immutable audit trails.
- Education:Student lifecycle management and research administration automation serve administrative efficiency mandates.
Healthcare leads vertical revenue concentration. Manufacturing is rotating up the share rankings as sustainability compliance automates carbon-intensive process documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where enterprise procurement teams negotiate multi-year platform commitments, while Indian buyers prioritize consumption-based models that compress vendor margins.
United States
Hospital networks automate patient scheduling and claims processing to offset clinical labor shortages. SEC disclosure rules and HIPAA technical safeguards elevate governance-layer procurement criteria above pure cost reduction. Healthcare RPA adoption accelerates across hospital systems in Texas and Florida.
Germany
Automotive suppliers compress order-to-delivery cycles under CSRD transparency mandates. EU AI Act audit trail requirements force reengineering of automated decision systems. Industrial clusters in Bavaria and Baden-Württemberg automate energy monitoring workflows to satisfy carbon accounting timelines.
India
Digitizing services sector drives UPI-integrated workflow adoption among founder-operated companies. The Digital Personal Data Protection Act compels multinational providers to establish domestic cloud infrastructure. Bengaluru and Hyderabad concentrate workflow architect talent pools for mid-market implementations.
United Kingdom
Financial services firms prioritize pre-certified compliance modules for algorithmic trading and fraud detection workflows. GDPR enforcement exposure slows adoption in privacy-sensitive segments. London anchors demand for IT service management orchestration across banking and insurance verticals.
Japan
Manufacturing enterprises demand real-time data streaming compatibility with MES and SCADA systems. METI standards guide edge computing deployment for shop-floor automation. Industrial corridors around Nagoya and Osaka integrate sustainability reporting into operational workflows.
Workflow Automation and Optimization Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the integration layer. The vendor base organizes around three strategic archetypes: horizontal automation platforms, vertical workflow suites, and API-centric integration specialists. Consolidation pressure intensifies as horizontal platforms acquire process mining and governance capabilities to defend account expansion rates. Strategic partnerships between cloud hyperscalers and workflow vendors accelerate co-selling motions into enterprise accounts.
Among horizontal automation platforms, UiPath and Automation Anywhere occupy positions anchored in robotic process automation specialization. Zapier sits within the self-service tier serving founder-led operations through deep integration libraries. ServiceNow exemplifies the vertical expansion archetype, migrating from IT service management roots into broader process orchestration domains.
| Leading Market Players |
|---|
| Zapier |
| Blue Prism |
| UiPath |
| n8n |
| Make |
| Automation Anywhere |
| Workato |
| ServiceNow |
| Microsoft Power Automate |
| Others |
Value Chain & Pricing Dynamics
EU AI Act compliance chokepoints determine both tiered SaaS pricing spreads and supply chain localization decisions as vendors reroute cloud infrastructure through region-locked data centers to satisfy audit trail mandates.
Pricing Analysis
Industrial OEM buyers anchor three-tier subscription pricing across premium enterprise suites, standard mid-market packages, and economy self-service tiers. Certification against EU AI Act high-risk system requirements and HIPAA technical safeguards commands 40-60% premiums over uncertified alternatives. Pricing pressure stems from low-code platform proliferation compressing entry-level margins. Small businesses exhibit highest price sensitivity, while healthcare systems under labor shortage pressure show lowest elasticity.
Supply Chain Analysis
Upstream compute infrastructure feeds from concentrated hyperscaler capacity in the United States, Ireland, and Singapore. Proprietary AI model weights, API middleware libraries, and compliance certification frameworks constitute critical intangible inputs. Single-source vulnerability runs through NVIDIA GPU supply for training workloads. Distribution runs through direct enterprise sales teams for large accounts and self-service digital channels for founder-led buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capital expenditure cycles signal recovery as deferred automation projects reactivate under CSRD disclosure deadlines.
For Market Incumbents: Pre-empt agentic AI displacement by acquiring process mining specialists before horizontal platforms consolidate discovery-layer capabilities. Anchor enterprise accounts through vertical integration into implementation services. Defend against Zapier's self-service expansion by embedding governance layers that mid-market buyers cannot replicate. For New Entrants and Emerging Players: Build out India-focused localization stacks before multinational incumbents establish domestic cloud regions under Digital Personal Data Protection Act mandates. Target founder-operated services companies in Bengaluru and Hyderabad through UPI-integrated workflow templates. Lead with consumption-based pricing that aligns vendor incentives with customer transaction volumes. For Investors and Strategic Acquirers: EU AI Act high-risk system certification deadlines reshape the acquisition landscape toward pre-certified compliance module vendors. Five-to-ten year viability favors platforms with embedded governance layers rather than pure execution engines. Watch for SEC climate disclosure rule enforcement as inflection signal for sustainability reporting automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Pre-Certification | EU AI Act high-risk system assessments accelerate procurement cycles for certified vendors. |
| Process Mining Acquisition | Discovery-layer analytics expand addressable spend from IT into operations budgets. |
| Domestic Cloud Region Establishment | India's Digital Personal Data Protection Act creates implementation service opportunities. |
| Low-Code Interface Expansion | Visual drag-and-drop configuration compresses time-to-value for founder-led operations. |
| Sustainability Reporting Automation | CSRD disclosure timelines automate carbon-intensive process documentation for German manufacturers. |
Study Parameters
A standing panel of workflow architects, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary interview programs. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and hospital procurement databases. Bottom-up deployment estimates triangulated against top-down enterprise software spend analysis.
Scenario-bracketing around regulatory enforcement intensity and manufacturing capital cycle timing bounded projections across the analysis window. Segmentation dimensions modeled deployment model, organization size, vertical application, integration complexity, and regional adoption pattern. CAGRs derived from elasticity-adjusted price-volume relationships with agentic AI adoption curves as primary demand shifter.
Stress conditions across EU AI Act implementation timelines, GPU supply constraints, and manufacturing recession depth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and cloud infrastructure buildout rates. Cross-checking against hyperscaler revenue disclosures and enterprise SaaS billing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Meditation Management Apps Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Mind Mapping Software Market
Software & Services
Global Electronic Dictionary Market
Software & Services
Optical Design Software Market
Software & Services
Patent Management Software Market
Software & Services
Job Description Management Software Market
Software & Services
Yacht Management Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Global Intranet Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Content Curation Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
Embroidery Design Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market