
 Enterprise Performance Management (EPM) Software Market | 2026-2036
Enterprise Performance Management (EPM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Performance Management (EPM) Software Market Foresight
Multi-source vendor strategies is realigning how enterprises procure planning and consolidation tools. Oracle Fusion Cloud EPM anchors the high-end segment with deep financial close integration. Workday Adaptive Planning leverages its HCM heritage to dominate workforce planning adjacencies. SAP Analytics Cloud competes through native connectivity to S/4HANA operational data.
Enterprise Performance Management software encompasses integrated applications for budgeting, forecasting, financial consolidation, and performance reporting, typically deployed via cloud, on-premises, or hybrid architectures with sub-second calculation engines supporting driver-based models. Its primary purpose is to replace spreadsheet-dependent processes with auditable, collaborative planning workflows that align operational tactics with financial targets. Cloud deployment now captures the fastest expansion as finance teams abandon server maintenance overhead, while on-premises installations persist in banking and defense sectors with stringent data residency requirements. The manufacturing vertical generates disproportionate margin pools due to complex supply chain planning needs that demand specialized scenario modeling capabilities.
Sarbanes-Oxley compliance requirements enforced by the SEC shape demand for audit trails and version control in North American deployments, while GDPR constraints in Europe limit cross-border data flows within cloud-hosted EPM instances. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating SaaS planning vendors. Finance leaders must weigh the trade-off between vendor consolidation benefits and the flexibility of maintaining specialized point solutions for niche planning domains.
Market Dynamics
Cloud migration mandates from finance leadership are compressing replacement cycles for on-premises planning systems, forcing vendors to rearchitect calculation engines for elastic scalability and real-time collaboration.
Growth Catalysts
- SEC Climate Disclosure Rules:Mandates for scope 3 emissions reporting in the United States are forcing CFOs to adopt integrated planning platforms with carbon accounting modules.
- AI-Augmented Forecasting:Machine learning algorithms trained on operational telemetry are reducing variance in demand predictions for manufacturing supply chains.
- German Mittelstand Consolidation:Mid-sized industrial exporters in Baden-Württemberg and Bavaria are unifying fragmented Excel processes to meet CSRD assurance requirements.
Market Restraints
- Data Residency Compliance:GDPR constraints on cross-border data flows create architectural friction for US-headquartered SaaS vendors serving European banking clients.
- Specialized Talent Scarcity:Shortage of FP&A professionals fluent in both driver-based modeling and Python-based data pipelines limits implementation velocity.
- Legacy System Entrenchment:COBOL-based general ledger systems in Japanese insurance sector create integration barriers requiring expensive middleware layers.
Strategic Opportunities
- India Manufacturing Scale-Up:PLI scheme beneficiaries in electronics and pharmaceuticals are building planning capabilities to manage multi-entity consolidation across SEZ and domestic units.
- ESG-Linked Scenario Modeling:EU Taxonomy alignment requirements are creating demand for carbon price stress testing and transition pathway analysis modules.
- Edge-to-Cloud Synchronization:Convergence of IoT shop-floor sensors with centralized planning engines enables real-time production rebalancing for automotive tier-1 suppliers.
Industry Challenges
- Multi-Vendor Integration Complexity:Enterprises stitching together specialized tools for workforce, supply chain, and financial planning face API versioning conflicts and data lineage gaps.
- ISO 27001 Certification Timelines:Six-to-nine month audit cycles delay go-live dates for SaaS procurement in defense and healthcare verticals with classified data handling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Performance Management (EPM) Software Market |
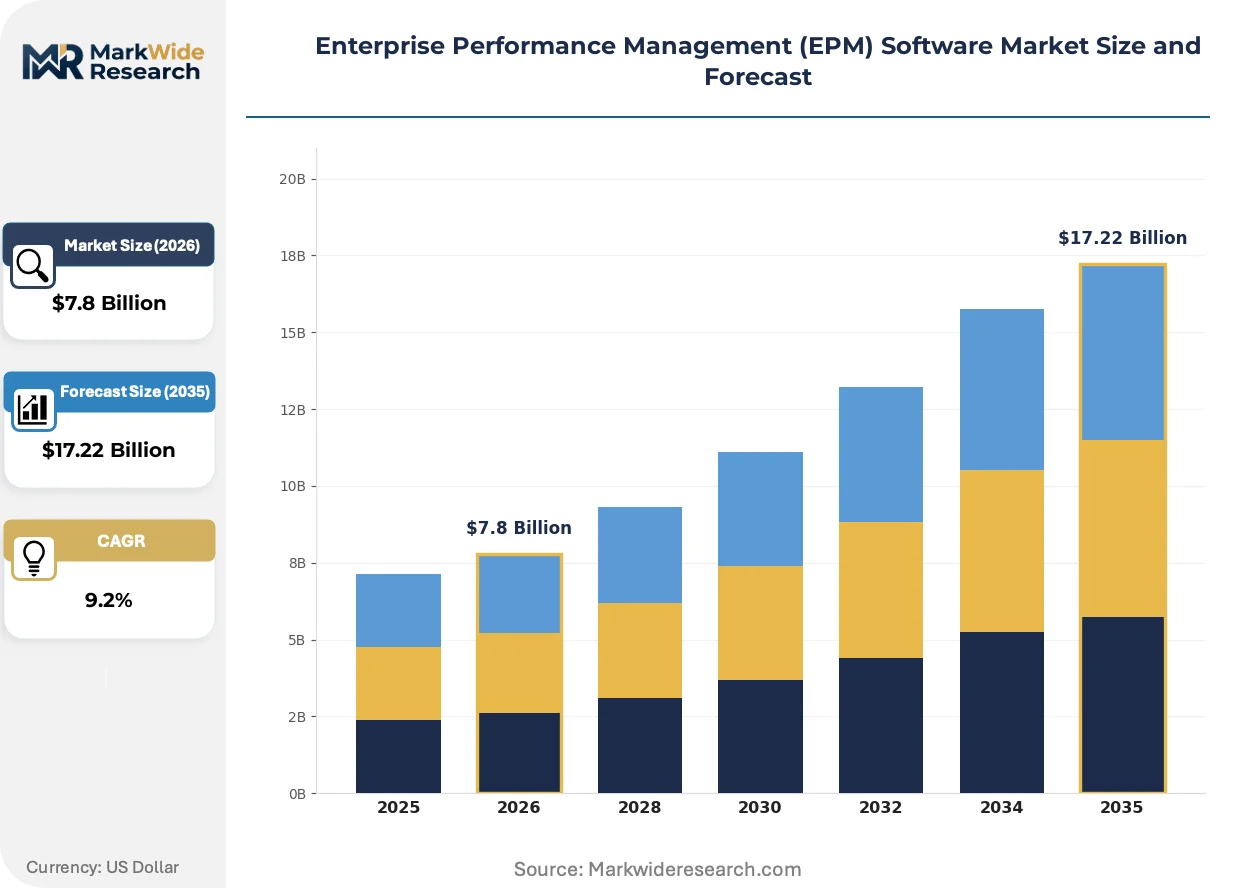
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.22 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, SaaS End User: Finance, Human Resources, IT, Operations Solution: Budgeting, Forecasting, Reporting, Analytics Industry Vertical: Manufacturing, Retail, Healthcare, Telecommunications |
| Companies Covered | Anaplan, CCH Tagetik, Oracle Fusion Cloud EPM, Jedox, Workday Adaptive Planning, OneStream, IBM Planning Analytics, Prophix, SAP Analytics Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Performance Management (EPM) Software Market Shifts & Advancements
Generative AI capabilities are embedding directly into planning interfaces, compressing the cycle time between data discovery and executive presentation while raising new governance questions about model explainability.
Natural language query interfaces are automating the translation of CFO questions into multidimensional calculations. Finance teams at industrial conglomerates in Germany and Japan are piloting these tools for ad-hoc variance analysis. The technology is automating report generation workflows that previously consumed 40% of FP&A staff hours.
CSRD implementation deadlines in the European Union are mandating double materiality assessments that fuse financial and sustainability planning. Industrial manufacturers with complex supply chains face the steepest compliance burden. French and Italian CFOs are prioritizing vendors with pre-built ESG metric libraries and assurance-ready audit trails.
Subscription pricing for planning modules is displacing perpetual license models among mid-market buyers in the United States. Value-added resellers and systems integrators are capturing recurring revenue through managed planning services. This shift is most visible in healthcare and professional services verticals where IT capital budgets remain constrained.
Enterprise Performance Management (EPM) Software Market Segmentation
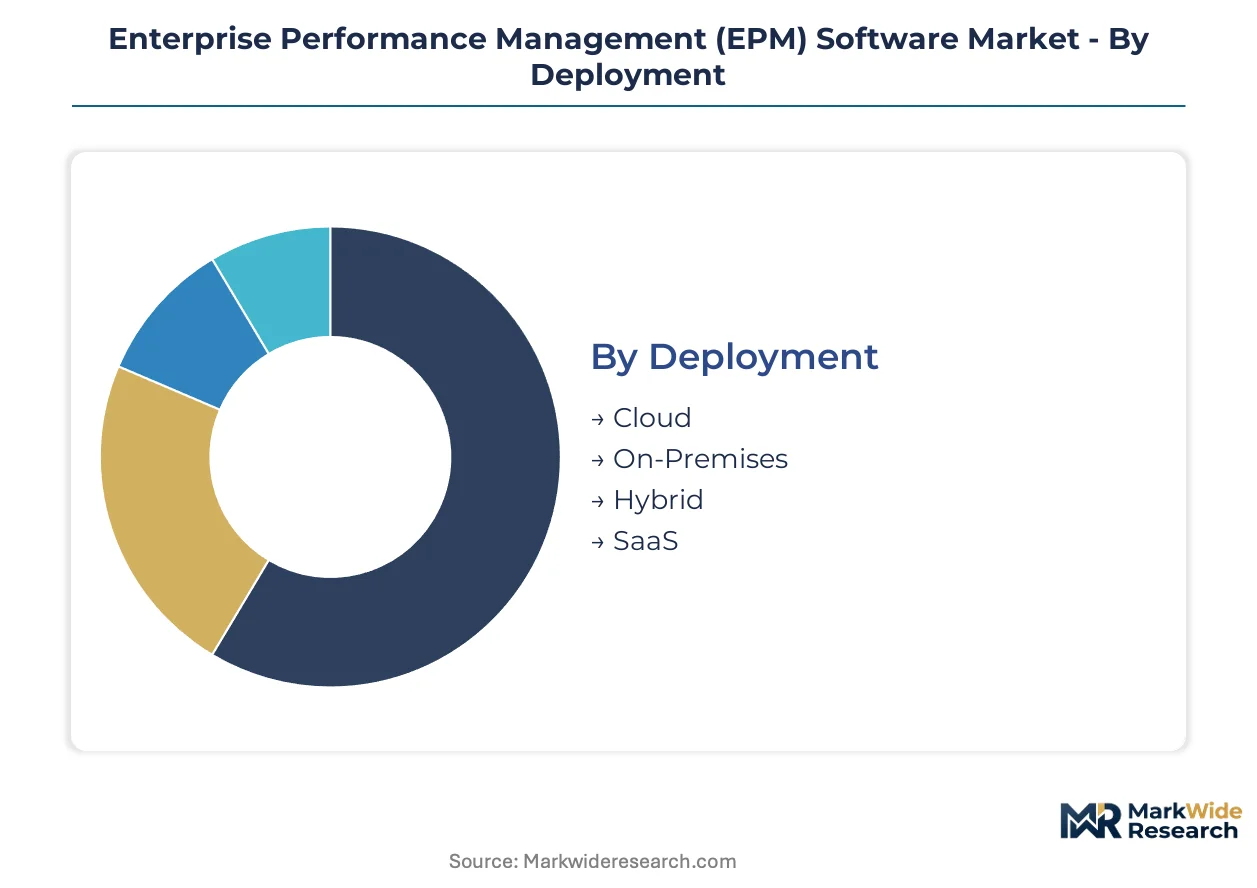
EPM procurement patterns diverge sharply across deployment architectures, functional domains, and vertical compliance requirements. Finance leaders evaluate segments through the lens of auditability, calculation latency, and integration depth with operational source systems.
Deployment:
Cloud-native architectures dominate new procurement decisions as elastic scalability replaces fixed-capacity planning.
- Cloud:Multi-tenant SaaS platforms with sub-second consolidation engines serve CFOs eliminating server maintenance overhead. Demand concentrates among mid-market manufacturers in Baden-Württemberg seeking CSRD-compliant audit trails without capital expenditure.
- On-Premises:Single-tenant installations with localized calculation grids persist where data residency mandates override cost efficiency. Japanese insurance carriers with COBOL-era general ledger dependencies maintain these deployments for regulatory continuity.
- Hybrid:Split architectures anchor sensitive consolidation data on-premises while pushing collaborative budgeting workflows to cloud edge nodes.
- SaaS:Subscription-priced modules with pre-configured planning templates accelerate time-to-value for healthcare systems with constrained IT capital budgets.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud.
End User:
Functional ownership determines workflow design priorities and interface complexity requirements.
- Finance:Treasury controllers and FP&A directors demand driver-based modeling with version-controlled scenario hierarchies and automated intercompany eliminations. German Mittelstand exporters in Bavaria prioritize these capabilities for multi-entity consolidation across SEZ and domestic units.
- Human Resources:Workforce planners integrate headcount forecasting with compensation modeling and skills-based scenario testing. US healthcare systems leverage these tools for nursing labor optimization amid regulatory staffing mandates.
- IT:Technical architects evaluate API governance, data lineage tools, and identity federation protocols for enterprise planning ecosystems.
- Operations:Supply chain planners synchronize demand signals with production capacity models and supplier risk scoring.
Finance commands the deepest feature penetration. Operations shows the steepest expansion trajectory as IoT sensor integration matures.
Solution:
Capability modules align with discrete phases of the performance management cycle from target-setting to variance analysis.
- Budgeting:Bottom-up and top-down target allocation workflows with workflow approvals and commentary threads. Retail conglomerates in Japan deploy these for store-level P&L planning with real-time currency conversion.
- Forecasting:Rolling projection engines with statistical baseline generation and management override tracking. Automotive tier-1 suppliers in Germany adopt AI-augmented demand prediction to reduce inventory carrying costs.
- Reporting:Structured output generation with XBRL tagging, board-ready visualizations, and multi-format distribution.
- Analytics:Ad-hoc multidimensional exploration with natural language query interfaces and predictive scenario simulation.
Reporting exhibits the highest deployment maturity. Analytics is gaining share fastest as generative AI compresses insight-to-presentation cycles.
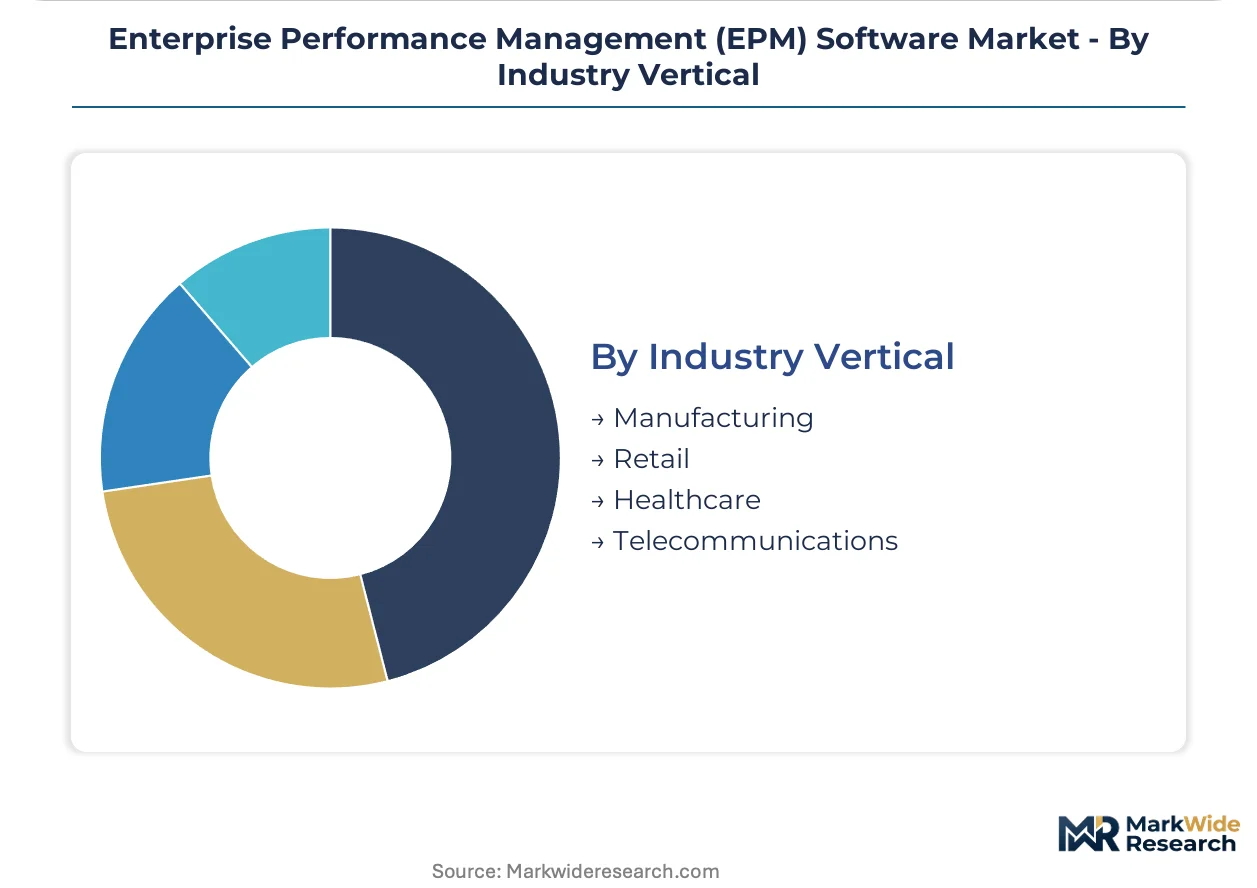
Industry Vertical:
Sector-specific compliance regimes and operational complexity shape solution configuration requirements.
- Manufacturing:Complex bill-of-materials planning with supply chain stress testing and carbon accounting integration. French industrial exporters prioritize these capabilities for EU Taxonomy alignment and scope 3 emissions disclosure.
- Retail:Omnichannel demand forecasting with promotional lift modeling and markdown optimization. US specialty retailers deploy these tools for SKU-level profitability analysis across digital and physical footprints.
- Healthcare:Patient volume planning with DRG-based revenue projection and labor cost optimization under HIPAA constraints.
- Telecommunications:Network capacity planning with subscriber churn modeling and 5G deployment capital allocation.
Manufacturing retains the deepest functional penetration. Healthcare is expanding most quickly as reimbursement complexity and labor shortages intensify planning automation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finance leadership in the United States, Germany, and Japan commands the highest EPM procurement velocity, with CFOs in these markets replacing spreadsheet-dependent workflows at accelerated cadences.
United States
SEC climate disclosure mandates and Sarbanes-Oxley compliance requirements drive demand for audit-ready consolidation platforms. Healthcare systems in the Southeast and Pacific Northwest prioritize subscription-priced SaaS modules to bypass capital expenditure constraints. New York Metro financial services firms deploy scenario modeling tools for regulatory stress testing under SEC supervision.
Germany
CSRD implementation deadlines and EU Taxonomy alignment requirements force Mittelstand exporters toward unified planning platforms. Baden-Württemberg industrial manufacturers integrate carbon accounting modules for scope 3 emissions disclosure. Bavarian automotive suppliers adopt AI-augmented demand forecasting to optimize inventory carrying costs across multi-entity structures.
Japan
METI digital transformation incentives accelerate cloud migration for COBOL-era general ledger systems in insurance and banking. Tokyo-based conglomerates pilot natural language query interfaces for ad-hoc variance analysis. Osaka manufacturing clusters deploy edge-to-cloud synchronization for real-time production rebalancing.
India
PLI scheme beneficiaries in electronics and pharmaceuticals build planning capabilities for multi-entity consolidation across SEZ and domestic units. RBI regulatory reporting requirements shape vendor selection for banking sector deployments. Karnataka and Maharashtra technology corridors attract SaaS vendors establishing localized data residency infrastructure.
United Kingdom
GDPR constraints on cross-border data flows create procurement friction for US-headquartered SaaS vendors serving London financial services clients. NHS reimbursement complexity drives healthcare systems toward patient volume planning with DRG-based revenue projection. Scottish and Northern Irish manufacturing units adopt hybrid architectures for sensitive consolidation data.
Enterprise Performance Management (EPM) Software Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent enterprise software vendors expand planning module coverage through organic development and targeted acquisitions. The vendor base stratifies into three tiers: cloud-native specialists with elastic calculation engines, legacy ERP extenders leveraging installed base relationships, and vertical-focused boutiques serving niche compliance requirements. Two strategic archetypes occupy distinct positions: horizontal platform consolidators pursuing unified data models across finance, HR, and operations; and domain purists maintaining specialized depth in single planning disciplines. M&A activity and API ecosystem expansion represent the dominant competitive vectors.
Within the cloud-native specialist tier, Anaplan and OneStream exemplify architecture-first approaches with sub-second consolidation engines. Oracle Fusion Cloud EPM anchors the high-end segment through deep financial close integration, while Workday Adaptive Planning leverages its HCM heritage to dominate workforce planning adjacencies. SAP Analytics Cloud occupies a position among ERP extenders competing through native S/4HANA connectivity.
| Leading Market Players |
|---|
| Anaplan |
| CCH Tagetik |
| Oracle Fusion Cloud EPM |
| Jedox |
| Workday Adaptive Planning |
| OneStream |
| IBM Planning Analytics |
| Prophix |
| SAP Analytics Cloud |
| Others |
Supply & Pricing Matrix
Cloud-native architecture migration simultaneously compresses infrastructure cost economics and concentrates supply leverage among hyperscaler-aligned vendors. Elastic scalability investments by SaaS platforms in the United States and Germany are reshaping total cost of ownership calculations while narrowing the vendor pool capable of meeting enterprise-grade ISO 27001 certification requirements.
Pricing Analysis
Service bundling separates implementation support from base platform licensing across vendor tiers. Subscription pricing dominates mid-market procurement, with premium differentiation anchored in AI-augmented forecasting modules and dedicated customer success management. Price erosion runs through standard-tier offerings as Workday and Oracle escalate feature parity investments. Healthcare systems in the United States exhibit highest price sensitivity due to capital budget constraints, while German Mittelstand manufacturers prioritize compliance-ready audit trails over cost minimization.
Supply Chain Analysis
ISO 27001 certification gating restricts viable infrastructure partners to established hyperscaler ecosystems in the United States, Germany, and Ireland. Cloud-native EPM platforms draw from Amazon Web Services, Microsoft Azure, and Google Cloud compute fabrics, with specialized calculation engine development concentrated in Silicon Valley and Bangalore technology corridors. Single-source vulnerability in AI training data pipelines poses structural risk as vendors compete for proprietary operational telemetry access. Distribution runs through direct enterprise sales organizations and systems integrator partnerships, with Accenture and Deloitte capturing substantial implementation revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as AI-augmented forecasting capabilities raise R&D barriers beyond mid-cap vendor reach. Cloud hyperscalers and ERP incumbents absorb specialized planning boutiques to complete unified platform architectures.
For Market Incumbents: Anchor platform stickiness through native integration with S/4HANA and Fusion Cloud ERP ecosystems. Deepen vertical-specific scenario modeling for CSRD-compliant carbon accounting to defend against Workday's workforce planning expansion. Prioritize ISO 27701 privacy certification to maintain German banking procurement eligibility amid GDPR enforcement tightening.
For New Entrants and Emerging Players: Capture white-space in India PLI scheme manufacturing verticals where multi-entity consolidation across SEZ boundaries remains underserved. Target pharmaceutical and electronics contract manufacturers in Karnataka and Maharashtra with pre-configured planning templates. Pursue channel partnerships with Tata Consultancy Services and Infosys to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ERP extenders seeking calculation engine talent and installed base access. Long-term viability favors vendors with demonstrated S/4HANA or Fusion Cloud integration depth and recurring revenue above seventy percent. Watch for CSRD implementation deadline acceleration as inflection signal for ESG-linked scenario modeling demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native S/4HANA connectivity enables real-time operational data ingestion for Bavarian automotive suppliers. |
| Acquisition of Specialist Firm | Carbon accounting boutiques add EU Taxonomy compliance modules for French industrial exporters. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure elastic scalability for sub-second consolidation engines. |
| Geographic Expansion | Localized data residency infrastructure in Karnataka addresses RBI requirements for Indian banking clients. |
| Product Launch | Natural language query interfaces reduce FP&A report generation workload at Tokyo-based conglomerates. |
Research Methodology
Independent corroboration across CFO interviews, IT procurement officer surveys, and vendor product documentation underwrites the qualitative findings. Primary fieldwork engaged finance transformation leads, FP&A directors, cloud architecture specialists, and systems integrator delivery heads across the United States, Germany, Japan, and India. Secondary validation drew from SEC climate disclosure filings, EU CSRD implementation guidance, METI digital transformation white papers, and RBI regulatory technology circulars. Bottom-up deployment estimates triangulated against top-down software spending benchmarks.
Comparable-period anchoring utilized historical cloud migration velocity and AI capability adoption curves to calibrate projection assumptions across the modeling period. Segmentation dimensions modeled include deployment architecture, functional solution module, end-user department, and industry vertical with regional adoption pattern overlays. CAGRs derived from exponential smoothing of vendor-reported booking trends and enterprise software spending surveys. Forecast inputs incorporated CSRD compliance deadline schedules and PLI scheme beneficiary expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI regulatory frameworks and cross-border data flow restrictions. Assumptions reflect current SEC, EBA, and METI policy trajectories without anticipating disruptive enforcement shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Channel Management Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Content Creation Software Market
Software & Services
Deck Design Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Forestry Software Market
Software & Services
Software As a Service (Saas) Market
Software & Services
Global Intranet Software Market
Software & Services
Employee Referral Software Market
Software & Services
School Timetable Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Camp Management Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Global Digital Signage Software Market