
 Procure to Pay Software Market | 2026-2036
Procure to Pay Software Market Size, Share, and Industry Trends Forecast 2026-2036
Procure to Pay Software Market Insights
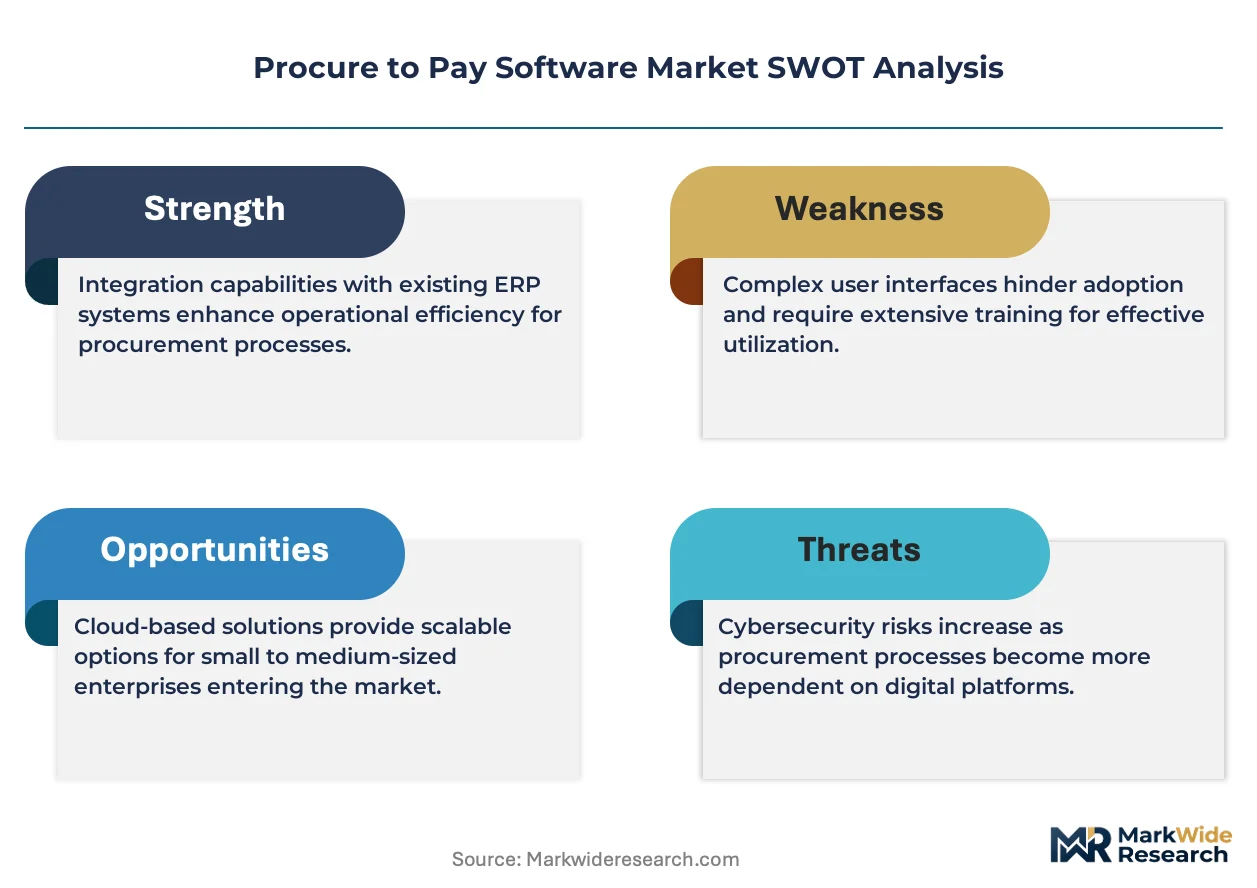
EU CSRD disclosure requirements for supply chain transparency is expanding the addressable market for audit-ready procurement platforms. SAP SE leverages its embedded ERP footprint to anchor enterprise deployments across European manufacturing hubs. Oracle Corporation sustains competitive pressure through database-to-cloud integration that unifies financial and procurement workflows. Coupa Software differentiates via community intelligence networks that benchmark supplier pricing across peer organizations.
Procure to Pay Software automates the complete sourcing-to-settlement workflow, encompassing requisitioning, purchase order management, invoice matching, and payment execution through configurable rule engines and API-driven integrations. The primary commercial purpose is to eliminate maverick spending, reduce processing costs, and enforce compliance through three-way matching protocols. Cloud-Based deployment leads solution adoption as enterprises prioritize scalable infrastructure over capital-intensive on-premise installations. Procurement Management captures the deepest functionality investment, while Spend Analysis represents the fastest-growing solution type as organizations demand predictive visibility into category expenditure.
FDA supply chain traceability mandates for pharmaceutical procurement, EU GDPR requirements for vendor data handling, and India's GST e-invoicing regulations through the GST Network collectively shape platform architecture and market access conditions. The central bank of India's digital payment push and Germany's Supply Chain Due Diligence Act further tighten compliance thresholds for cross-border supplier management. Stakeholders must evaluate whether their current systems can absorb emerging AI-driven anomaly detection and real-time carbon accounting modules before regulatory deadlines harden.
Market Dynamics
Cloud migration mandates from finance executives are compressing procurement cycle times while forcing legacy ERP replacements across mid-market enterprises. Artificial intelligence integration in invoice matching and anomaly detection is redrawing competitive boundaries between incumbent platforms and specialized challengers.
Growth Catalysts
- EU CSRD disclosure requirements:Supply chain transparency mandates are expanding the addressable market for audit-ready procurement platforms across European manufacturing and healthcare systems.
- Healthcare automation:North American hospital networks are accelerating procure-to-pay deployments to streamline supplier payments and achieve regulatory compliance with FDA supply chain traceability rules.
- GST e-invoicing:India's mandatory digital invoice reporting through the GST Network is forcing legacy system replacements and creating immediate demand for compliant cloud platforms.
Market Restraints
- Data localization costs:EU GDPR requirements for vendor data handling impose infrastructure duplication expenses that deter single-tenant cloud architectures.
- Technical debt:Deep on-premise ERP customizations in German manufacturing create integration friction that extends implementation timelines.
- Substitution pressure:Embedded procurement modules within major ERP suites threaten standalone platform margins in enterprise accounts.
Strategic Opportunities
- Carbon accounting convergence:Real-time emissions tracking integration with procurement workflows represents unmet demand in European industrial sectors.
- Mid-market penetration:United States-based regional healthcare systems remain underpenetrated relative to integrated delivery networks.
- API ecosystem expansion:Open banking protocols in India's digital payment infrastructure enable embedded finance features that differentiate platform offerings.
Industry Challenges
- Specialized talent scarcity:Shortage of procurement technologists capable of configuring three-way matching protocols and API integrations delays enterprise go-lives.
- Legacy system coexistence:Hybrid environments requiring real-time synchronization between cloud platforms and on-premise financial systems multiply integration complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Procure to Pay Software Market |
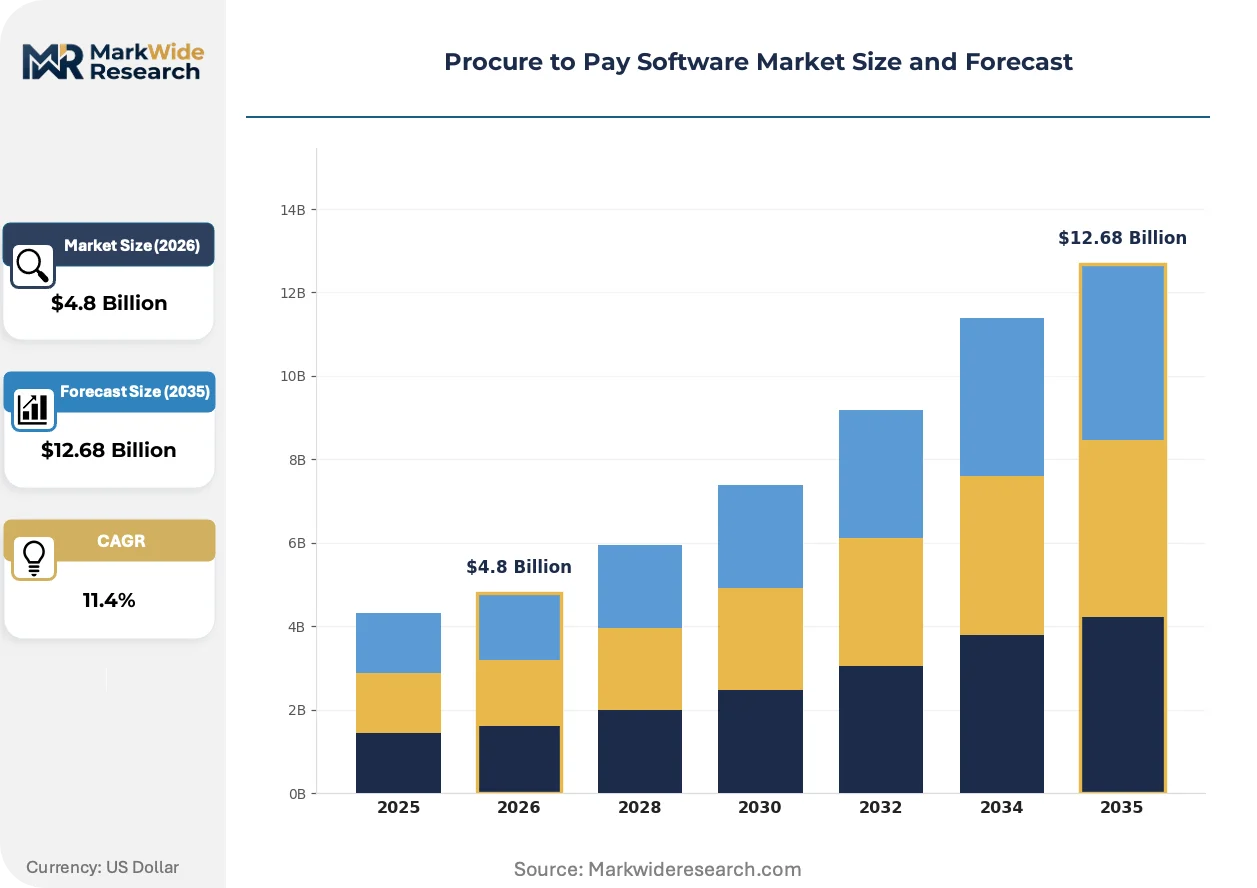
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Manufacturers, Retailers, Government Agencies, Educational Institutions Solution Type: Spend Analysis, Supplier Management, Invoicing, Procurement Management Industry Vertical: Healthcare, Construction, Transportation, Energy |
| Companies Covered | SAP SE, Oracle Corporation, Coupa Software, Basware, Jaggaer, GEP, Workday, Ivalua, Zycus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Procure to Pay Software Market Trends and Innovations
Machine learning is penetrating invoice processing workflows at an accelerating pace, compressing exception-handling costs while raising the bar for platform differentiation. Three interconnected developments are reshaping competitive positioning.
Intelligent document processing is expanding into accounts payable automation by extracting unstructured data from supplier invoices without template configuration. Mid-market enterprises in the United States are adopting these tools fastest, driven by CFO mandates to reduce manual touchpoints. The technology is expanding into supplier onboarding and contract analytics, collapsing multiple procurement subprocesses into unified workflows.
Germany's Supply Chain Due Diligence Act imposes liability for supplier human rights violations, forcing procurement platforms to embed audit trail capabilities. Industrial manufacturers face the steepest compliance burden, requiring granular visibility into tier-two and tier-three supplier networks. German automotive and electronics clusters are responding by demanding pre-certified compliance modules from platform vendors.
Self-service requisitioning is displacing centralized purchasing departments in professional services and technology sectors. Business unit leaders now expect consumer-grade mobile interfaces for catalog browsing and approval routing, bypassing traditional procurement gatekeepers. This pattern is most visible in India and the United States, where distributed workforce models have normalized remote purchasing authority.
Procure to Pay Software Market Segmentation
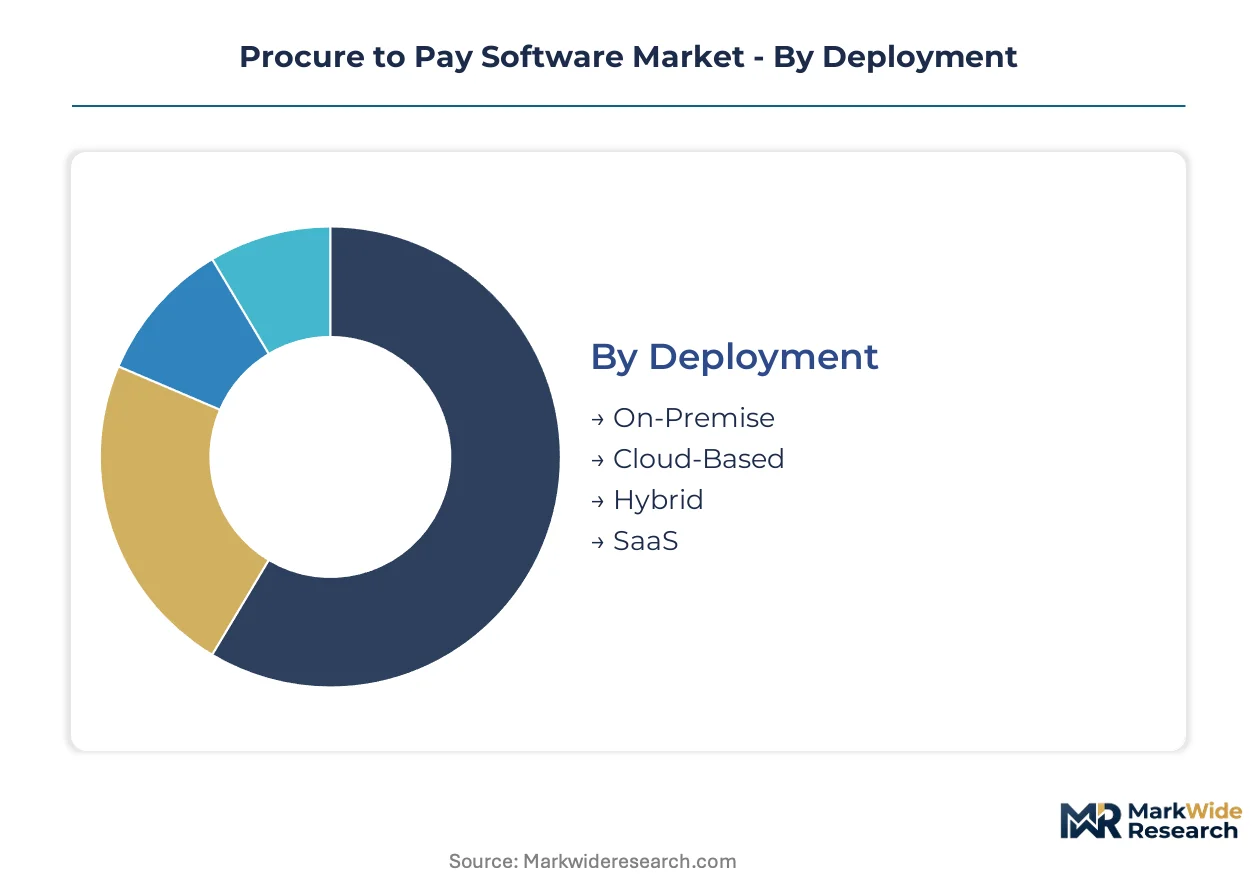
Procure to Pay Software vendors architect their roadmaps around distinct deployment preferences, end-user complexity, and vertical compliance burdens. Segmentation reveals where upgrade cycles concentrate and which solution types command premium pricing.
Deployment:
Cloud migration mandates from finance executives are compressing procurement cycle times while forcing legacy ERP replacements across mid-market enterprises.
- Cloud-Based:Multi-tenant architectures with elastic compute resources eliminate capital expenditure barriers. United States healthcare networks and German automotive suppliers prioritize these platforms for rapid supplier onboarding without infrastructure buildout.
- SaaS:Subscription licensing with embedded API marketplaces enables real-time integration with banking networks. India's GST e-invoicing compliance requirements accelerate adoption among mid-market manufacturers replacing legacy on-premise installations.
- On-Premise:Single-tenant installations with deep customization layers persist in defense contracting and regulated utilities.
- Hybrid:Split architectures maintaining sensitive spend data on-premise while routing transactional workflows through cloud gateways.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to SaaS delivery models.
End User:
Procurement complexity and supplier base scale determine solution sophistication requirements across customer categories.
- Manufacturers:Tiered supplier networks with three-way matching protocols and quality gate integration. German industrial clusters and United States aerospace suppliers drive demand for embedded compliance modules under supply chain due diligence regulations.
- Government Agencies:Public procurement frameworks with sealed bidding workflows and audit trail preservation. India's state-level digital transformation mandates and United States federal acquisition regulations shape platform certification requirements.
- Retailers:High-velocity catalog management with seasonal demand forecasting and dropship coordination.
- Educational Institutions:Grant-funded purchasing with restricted fund accounting and donor compliance tracking.
Manufacturers dominate current installations; government agencies are climbing the fastest as digital procurement mandates harden.
Solution Type:
Functional depth correlates with procurement maturity and available implementation resources.
- Procurement Management:Core requisition-to-purchase order workflows with approval hierarchies and catalog management. Healthcare systems across the United States and Germany anchor investment here as they consolidate purchasing authority across dispersed facilities.
- Spend Analysis:Predictive category intelligence with supplier consolidation recommendations and price benchmarking. India's manufacturing exporters and United States mid-market distributors adopt these tools fastest for margin protection.
- Supplier Management:Qualification workflows, performance scorecards, and risk monitoring across tiered supply networks.
- Invoicing:Automated matching engines with exception routing and early payment discount capture.
Procurement Management captures the deepest investment; Spend Analysis is gaining share fastest as predictive visibility becomes a board-level priority.
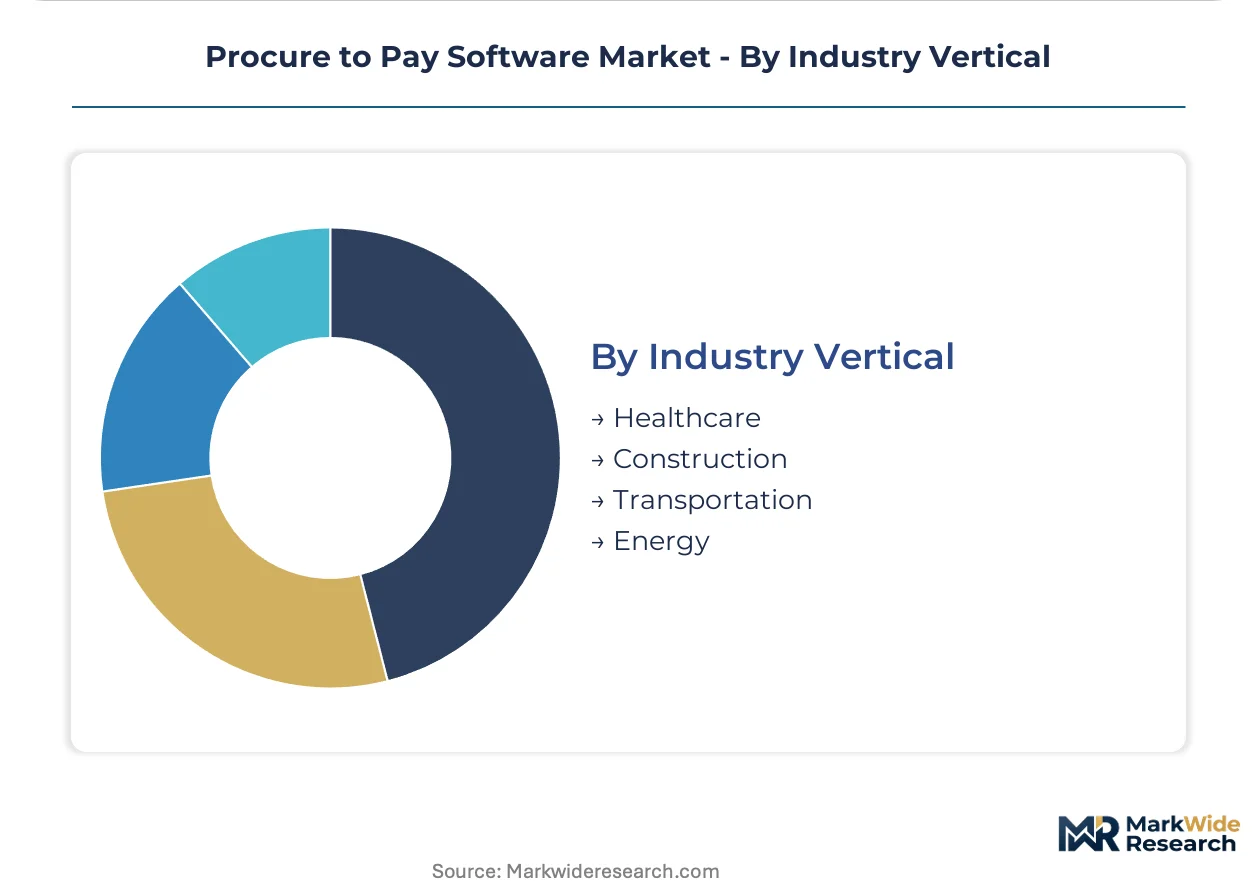
Industry Vertical:
Regulatory density and supplier fragmentation dictate platform configuration requirements.
- Healthcare:FDA supply chain traceability mandates and EU MDR requirements drive audit-ready procurement with lot-level tracking. United States hospital networks and German medical device manufacturers lead deployment velocity.
- Energy:Capital project procurement with long-lead equipment sourcing and contractor management under environmental compliance.
- Construction:Subcontractor qualification with lien waiver management and progress payment workflows.
- Transportation:Fleet procurement with fuel hedging integration and maintenance contract lifecycle management.
Healthcare anchors vertical revenue; energy sector deployments are expanding most quickly under infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area technology corridors anchor software development velocity for procurement automation, while Frankfurt's financial services cluster drives enterprise SaaS adoption across continental Europe. Regulatory divergence between jurisdictions is fragmenting platform architecture requirements.
United States
Hospital networks in Texas and California are consolidating supplier databases under FDA supply chain traceability mandates. The Department of Health and Human Services is tightening pharmaceutical procurement audit standards. Boston's biotechnology corridor demands lot-level tracking integration from platform vendors.
Germany
Automotive suppliers in Baden-Württemberg face liability exposure under the Supply Chain Due Diligence Act for tier-two vendor violations. Berlin's federal procurement office is mandating electronic invoicing compliance for public contracts. Munich's industrial manufacturing belt requires embedded carbon accounting modules.
India
GST Network e-invoicing requirements are forcing legacy ERP replacements among Maharashtra textile exporters and Karnataka automotive component manufacturers. The Reserve Bank of India's digital payment infrastructure push enables real-time supplier settlement. Hyderabad's pharmaceutical formulation cluster is adopting cloud-based procurement for export documentation.
United Kingdom
NHS procurement consolidation across England is standardizing requisition-to-payment workflows for medical device suppliers. The Cabinet Office is mandating open contracting data standards for public sector spend transparency. London's professional services firms are displacing centralized purchasing with self-service catalog interfaces.
France
Île-de-France healthcare systems are deploying three-way matching protocols under EU MDR device tracking requirements. The national procurement agency is requiring API interoperability for supplier onboarding. Lyon's chemical manufacturing basin demands REACH-compliant vendor qualification workflows.
Procure to Pay Software Market Competitive Landscape
The competitive structure tilts toward ERP-embedded platforms with deep financial system integration. Consolidation pressure from database-to-cloud migration strategies is compressing standalone vendor margins. Two archetypes dominate: enterprise suites leveraging existing ERP footprints, and specialized challengers with community intelligence networks. M&A activity concentrates on API infrastructure and anomaly detection capabilities.
Within the enterprise suite tier, SAP SE and Oracle Corporation exemplify database-anchored positioning, while Coupa Software occupies the community intelligence specialist position. These three entities represent divergent strategic bets on procurement workflow unification versus peer benchmarking differentiation.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Coupa Software |
| Basware |
| Jaggaer |
| GEP |
| Workday |
| Ivalua |
| Zycus |
| Others |
Pricing and Supply Chain Analysis
Procurement technologists concentrated in Bengaluru and Hyderabad command wage premiums that widen spreads between economy-tier SaaS subscriptions and enterprise-grade cloud deployments. Labor-cost differentials in implementation and configuration services cascade into pricing-tier stratification across mid-market and large-enterprise segments.
Pricing Analysis
Value-based pricing anchored to invoice throughput volumes dominates SaaS delivery models, with platforms charging per-transaction fees scaled to document processing loads. Price differentiation stems from AI-powered anomaly detection certification tiers and embedded compliance module depth. Cost compression in mid-market cloud tiers is intensifying because hyperscaler infrastructure commoditization erodes hosting margins. Regional healthcare systems in the United States exhibit highest price sensitivity due to constrained IT budgets, while German automotive suppliers prioritize compliance-grade configurations with lower elasticity.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center networks concentrated in the United States, Ireland, and Singapore. Software development draws from Indian engineering talent pools and Eastern European QA specialists. Single-source vulnerability in AI model training data licensing poses structural risk to specialized invoice processing vendors. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for complex ERP migrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Procure to Pay Software Market sits in a technology-transition phase as machine learning inference replaces rule-based matching engines in accounts payable workflows. Legacy on-premise ERP integrations are giving way to API-native cloud architectures.
For Market Incumbents: To counter embedded procurement modules within SAP and Oracle ERP suites, deepen vertical integration into healthcare compliance data networks and accelerate carbon accounting module certification under EU CSRD timelines. Prioritize talent retention in Bengaluru-based AI engineering centers to defend configuration service margins.
For New Entrants and Emerging Players: Enter via mid-market healthcare networks in Texas and Florida where legacy system replacement cycles lag integrated delivery networks. Target white-space demand for GST-compliant SaaS among Maharashtra textile exporters. Pursue open banking API partnerships with Indian fintech infrastructure providers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized anomaly detection vendors given FDA supply chain traceability mandate acceleration. Long-term viability favors platforms with embedded compliance modules spanning EU, US, and Indian regulatory frameworks. Monitor Reserve Bank of India real-time payment protocol adoption as the inflection signal for embedded finance integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Anomaly Detection Launch | FDA traceability mandates compress exception-handling costs for pharmaceutical procurement networks. |
| Carbon Accounting Module Integration | Germany's Supply Chain Due Diligence Act forces emissions tracking into supplier qualification workflows. |
| API Ecosystem Expansion | India's open banking protocols enable real-time supplier settlement features that differentiate SaaS tiers. |
| Healthcare Compliance Certification | EU MDR requirements drive audit-ready procurement with lot-level tracking for device manufacturers. |
| Mid-Market SaaS Geographic Expansion | United States regional hospital networks remain underpenetrated relative to consolidated IDN procurement platforms. |
Research Methodology
Document review covered SEC 10-K filings, EU regulatory disclosure databases, and GST Network implementation reports, complemented by interviews with procurement software executives, healthcare IT directors, and systems integration specialists. Primary fieldwork engaged CFOs at mid-market manufacturers, GPO contracts managers at United States hospital networks, and platform engineers at Indian SaaS providers. Secondary validation drew from customs data on enterprise software imports, hyperscaler capex disclosures, and FDA guidance document repositories. Bottom-up deployment counts and top-down IT spending estimates were triangulated to anchor market sizing.
Segmentation outputs reflect deployment model, end-user complexity, solution type depth, and vertical regulatory density across the projection horizon. CAGRs were derived from logistic adoption curves fitted to cloud migration penetration data and AI feature deployment timelines. Modeled inputs included GST e-invoicing compliance deadlines, EU CSRD disclosure phase-in schedules, and healthcare system consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under central bank digital currency acceleration or abrupt ERP vendor consolidation. Projections reflect assumptions on regulatory deadline adherence and mid-market cloud adoption elasticity. A small set of named triggers—RBI real-time payment protocol expansion, FDA traceability enforcement intensity, and EU carbon border adjustment implementation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Engineering Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Webcasting Software Market
Software & Services
Global AI Writing Assistant Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Grant Management Software Market
Software & Services
Video Server Software Market
Software & Services
Global Application Performance Monitoring (APM) Market
Software & Services
Combat Management Systems Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Mobile Application Development Market
Software & Services
Inventory Management Software Market
Software & Services
Global Business Card Software Market
Software & Services
Global User Interface Service Market