
 Electronic Beam Machining Market | 2026-2036
Electronic Beam Machining Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Beam Machining Market Foresight
High-vacuum precision specifications are rotating toward the center of procurement criteria for advanced electron beam systems. Mitsubishi Electric Corporation leverages its vacuum technology heritage to anchor Japanese supply chains for semiconductor fabrication tools. Sciaky Inc. specializes in large-chamber electron beam welding systems for aerospace structural components. Global Beam Technologies AG competes on European defense and space qualification programs.
Electronic beam machining employs focused streams of electrons accelerated through high-voltage potentials, typically operating in vacuum environments at beam powers ranging from kilowatts to hundreds of kilowatts for material removal, welding, or surface modification. The process achieves energy densities exceeding conventional thermal methods, enabling precision work on refractory metals and heat-sensitive alloys without atmospheric contamination. Welding applications dominate value capture given the technology's penetration in aerospace engine manufacturing and medical implant fabrication. Surface treatment represents the fastest-expanding category as turbine blade coating and biomedical texturing requirements intensify. Metals processing remains the most mature material segment, while ceramics and composites present emerging margin pools for specialized system configurations.
FDA quality system regulations and EU Machinery Directive safety standards shape equipment certification pathways and customer qualification timelines for electron beam system vendors. ISO 9001 and aerospace-specific NADCAP accreditation function as baseline market access requirements across major buyer segments. Stakeholders must monitor evolving vacuum chamber size standards and automation integration protocols as production lot sizes shrink and flexibility requirements tighten across end-user industries.
Market Dynamics
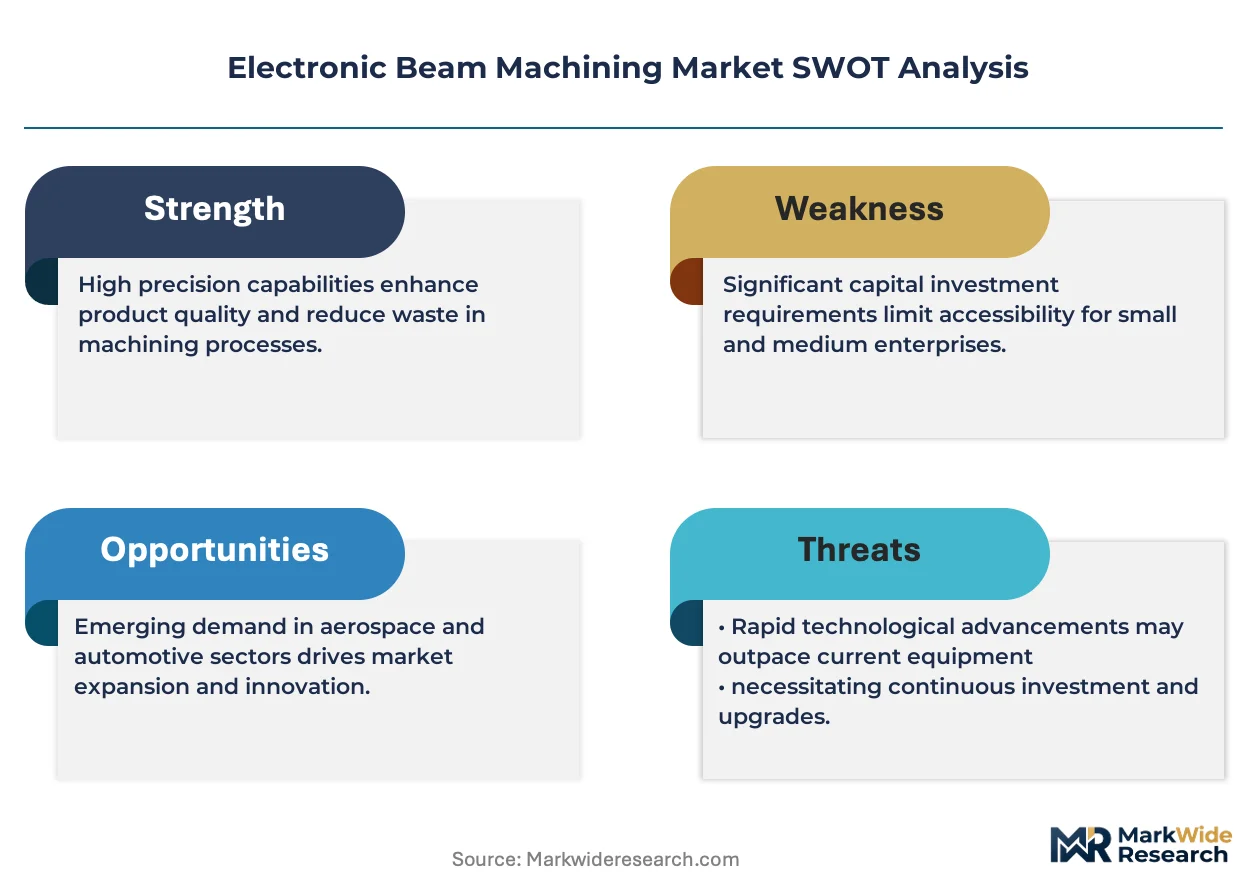
The Electronic Beam Machining Market is undergoing structural reconfiguration as aerospace manufacturers consolidate their supplier base around vacuum-welding specialists capable of NADCAP-accredited production. This buyer-side concentration is compressing qualification timelines and raising technical barriers for new equipment vendors.
Growth Catalysts
- Aerospace structural welding:Titanium airframe programs at Boeing and Airbus are mandating electron beam welding for critical joints, creating sustained equipment demand from tier-one suppliers.
- FDA device manufacturing standards:Implantable medical device producers must achieve validated electron beam surface finishes, driving system upgrades across orthopedic and cardiovascular manufacturing lines.
- German precision engineering corridor:Munich-Stuttgart manufacturing clusters are absorbing specialized large-chamber systems for defense and space qualification programs.
Market Restraints
- High-vacuum pump supply concentration:German and Japanese cryogenic pump manufacturers control critical subcomponent supply, creating procurement bottlenecks during capacity expansions.
- Refractory metal input volatility:Tungsten filament and tantalum chamber liner costs fluctuate with mining output from Central African and Russian sources.
- Laser welding substitution:Fiber laser systems with atmospheric shielding are capturing lower-tolerance aerospace and automotive applications below 50mm penetration depth.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme for capital goods is creating localized assembly opportunities for electron beam welding platforms serving missile and satellite programs.
- Ceramic matrix composite processing:Silicon carbide and carbon-carbon composite machining for hypersonic thermal protection systems remains underpenetrated by existing equipment configurations.
- EU Green Deal industrial decarbonization:Electron beam surface hardening offers energy-efficient alternatives to thermal spray coating for heavy machinery remanufacturing.
Industry Challenges
- Vacuum technician scarcity:Specialized electron optics alignment and high-voltage maintenance skills are concentrated among retiring European and North American workforce cohorts.
- NADCAP accreditation timelines:Aerospace supplier qualification for electron beam welding processes extends 18-24 months, freezing capital deployment until certification completion.
- Legacy CNC integration:Retrofitting 1990s-era five-axis positioning tables with modern beam deflection controllers requires custom mechanical-electrical engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Beam Machining Market |
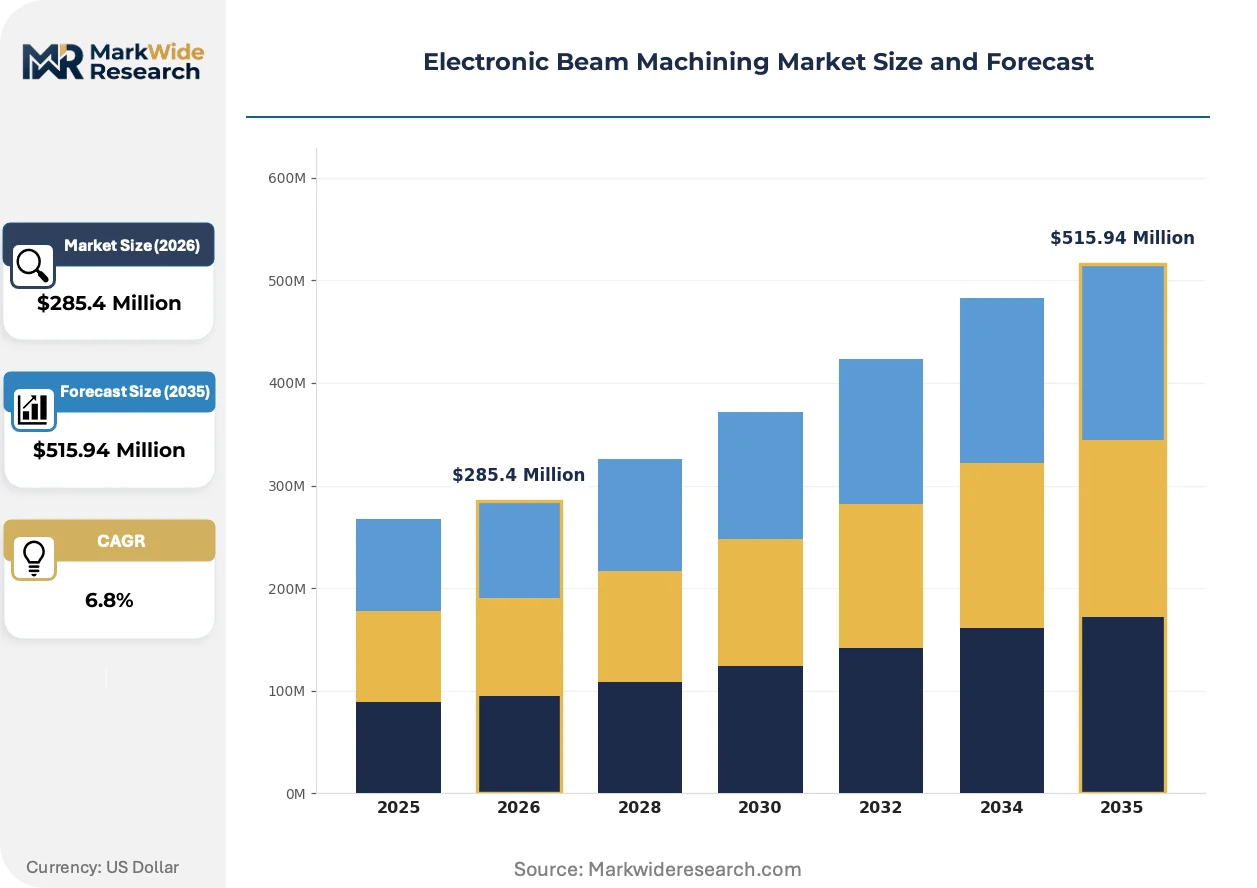
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microwave, Laser, Water Jet, Plasma End User: Aerospace, Automotive, Electronics, Medical Material: Metals, Alloys, Ceramics, Composites Application: Drilling, Cutting, Welding, Surface Treatment |
| Companies Covered | Global Beam Technologies AG, Mitsubishi Electric Corporation, pro-beam, Sciaky Inc., Cambridge Vacuum Engineering, EB Industries, Evobeam GmbH, Sodick, FOCUS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Beam Machining Market Shifts & Advancements
Electron beam system architecture is pivoting toward modular vacuum chamber designs and real-time beam diagnostics. Equipment vendors are embedding machine vision and predictive maintenance capabilities to compress downtime and extend service intervals.
Non-thermal electron beam surface modification is displacing conventional plasma spray and chemical vapor deposition for turbine blade coating applications. Rolls-Royce and Siemens Energy are qualifying these processes for next-generation gas turbine hot-section components. The shift is compressing coating cycle times from hours to minutes while eliminating hazardous precursor chemicals.
EU Machinery Directive 2006/42/EC amendments are mandating integrated safety controllers and emergency vacuum venting systems for industrial electron beam installations. Equipment manufacturers must redesign chamber interlocks and radiation shielding to achieve CE marking under tightened conformity assessment procedures. German system integrators are absorbing the highest compliance costs due to their defense and medical device customer concentration.
After-sales service unbundling is fragmenting the traditional bundled maintenance model across Japanese and European installed bases. End-users are purchasing spare electron gun assemblies and vacuum pumps through third-party distributors rather than OEM service contracts. This pattern is most pronounced in South Korean semiconductor fabrication facilities, where in-house vacuum engineering teams perform routine cathode replacements.
Electronic Beam Machining Market Segmentation
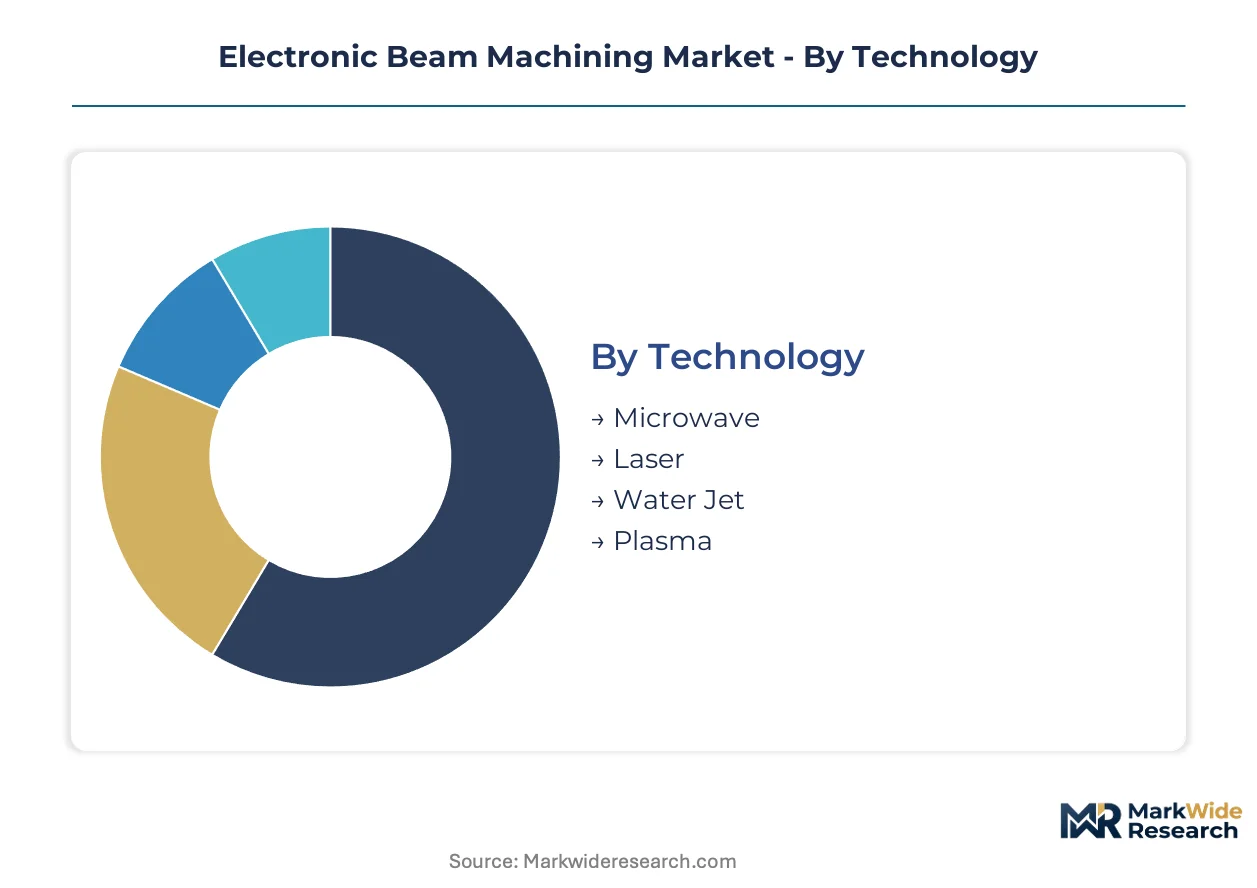
Electronic beam machining systems command price premiums through application-specific configurations. Segment boundaries align with certification requirements and vacuum chamber specifications rather than generic power ratings.
Technology:
Microwave and laser platforms capture the highest margin pools through semiconductor fabrication tool integration.
- Microwave:Generates electron beam excitation through resonant cavity oscillation at gigahertz frequencies. Demand concentrates in Japanese semiconductor fabrication facilities where METI-supported equipment modernization programs prioritize energy efficiency.
- Laser:Employs photonic pre-ionization to stabilize electron beam generation. German precision engineering clusters around Munich absorb specialized laser-electron hybrid systems for defense qualification programs.
- Water Jet:Hybrid systems combining electron beam precision with abrasive water cooling for thick-section cutting.
- Plasma:Atmospheric-pressure electron beam variants using plasma channel confinement.
Microwave holds installed capacity. Laser is rotating up the share rankings.
End User:
Aerospace and medical segments drive qualification-intensive procurement with extended vendor certification timelines.
- Aerospace:Titanium airframe welding and engine component fabrication dominate equipment utilization. Boeing and Airbus tier-one suppliers in Germany's Stuttgart corridor mandate NADCAP-accredited electron beam systems for structural joints.
- Medical:Implantable device manufacturers require validated surface finishes for orthopedic and cardiovascular applications. FDA quality system regulations drive system upgrades across US and European manufacturing lines.
- Automotive:Powertrain component welding and transmission gear surface hardening.
- Electronics:Semiconductor mask repair and microelectromechanical system fabrication.
Aerospace holds installed capacity. Medical is climbing the fastest.
Material:
Metals and alloys anchor revenue concentration through mature welding applications.
- Metals:Refractory metal processing including tungsten, molybdenum, and tantalum. Aerospace engine manufacturers in the US and Germany consume high-power systems for turbine blade fabrication.
- Alloys:Nickel-based superalloys and titanium aluminides for hot-section components. Rolls-Royce and Siemens Energy qualification programs are expanding coating cycle demand.
- Ceramics:Silicon carbide machining for hypersonic thermal protection systems.
- Composites:Carbon-carbon and ceramic matrix composite drilling and cutting.
Metals holds installed capacity. Alloys is gaining share fastest.
Application:
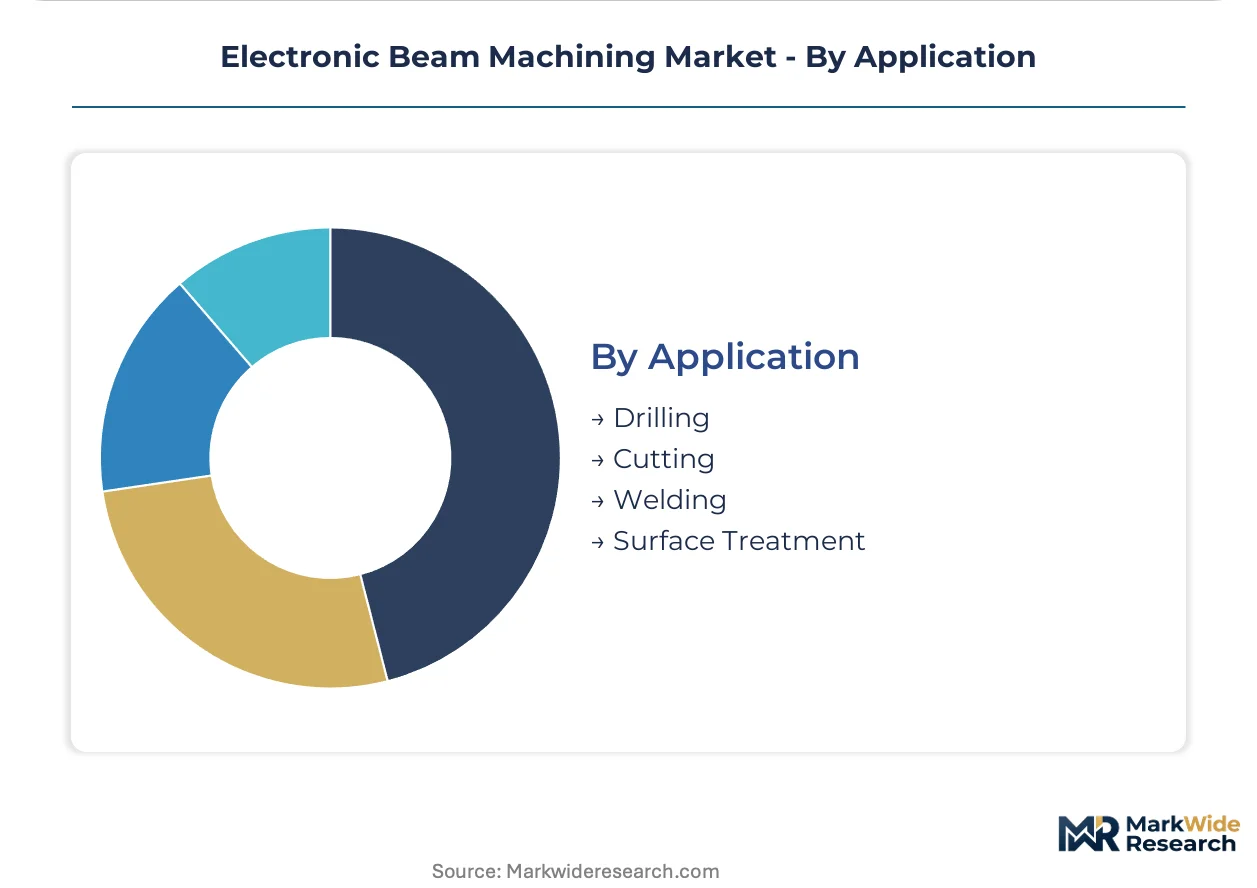
Welding and surface treatment split margin pools between volume equipment and specialized coating systems.
- Welding:Deep-penetration vacuum welding achieves single-pass joints exceeding 100mm in titanium and steel. German defense and space programs absorb large-chamber systems through Global Beam Technologies AG supply chains.
- Surface Treatment:Non-thermal electron beam modification displaces plasma spray for turbine blade coating. Cycle time compression from hours to minutes drives qualification at Siemens Energy and Rolls-Royce.
- Drilling:High-aspect-ratio hole generation for aerospace cooling channels.
- Cutting:Refractory metal sectioning for medical implant blanks.
Welding holds installed capacity. Surface Treatment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing economies with vacuum technology heritage. Germany and Japan maintain trade surpluses in high-vacuum electron beam systems. Emerging markets in India and South Korea are accelerating localized assembly to reduce import dependency.
United States
Aerospace engine manufacturers at Boeing and Lockheed Martin drive demand for NADCAP-accredited welding systems. FDA quality system regulations mandate validated surface finishes for implantable device production. The Pacific Northwest aerospace corridor around Seattle absorbs specialized large-chamber equipment for titanium airframe programs.
Germany
Defense and space qualification programs through Global Beam Technologies AG anchor equipment procurement. EU Machinery Directive amendments tighten CE marking requirements for integrated safety controllers. The Munich-Stuttgart precision engineering corridor concentrates demand for semiconductor fabrication tools and medical device manufacturing lines.
Japan
METI-supported equipment modernization programs prioritize energy-efficient microwave excitation systems. JIS standards govern vacuum chamber specifications for domestic semiconductor fabrication facilities. The Chubu region around Nagoya hosts integrated supply chains linking Mitsubishi Electric Corporation to electronics manufacturers.
India
PLI scheme incentives for capital goods are creating localized assembly opportunities for missile and satellite programs. The country's national aerospace regulator mandates indigenization timelines for defense procurement. Karnataka's aerospace cluster in Bangalore is absorbing electron beam welding platforms for space launch vehicle fabrication.
South Korea
Semiconductor fabrication facilities with in-house vacuum engineering teams drive aftermarket component demand. MFDS medical device regulations align with international standards for orthopedic implant surface finishing. The Seoul Capital Area concentrates electronics manufacturing lines requiring precision beam systems for mask repair applications.
Electronic Beam Machining Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth. The vendor base stratifies into three tiers: diversified industrial conglomerates with vacuum heritage, dedicated electron beam system fabricators, and regional assembly specialists serving national defense programs. Two dominant competitive moves are reshaping positioning: strategic partnerships to secure cryogenic pump supply chains, and geographic licensing agreements to bypass NADCAP accreditation timelines in new markets.
Among European-based fabricators, Global Beam Technologies AG and Evobeam GmbH exemplify the defense-specialist archetype, occupying positions within EU space qualification programs. Mitsubishi Electric Corporation represents the diversified conglomerate model, anchoring Japanese supply chains through captive vacuum technology capabilities. These three companies illustrate how competitive positioning depends on certification depth rather than scale alone.
| Leading Market Players |
|---|
| Global Beam Technologies AG |
| Mitsubishi Electric Corporation |
| pro-beam |
| Sciaky Inc. |
| Cambridge Vacuum Engineering |
| EB Industries |
| Evobeam GmbH |
| Sodick |
| FOCUS GmbH |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with cryogenic pump manufacturers lock in supply access and price visibility for German and Japanese system integrators serving NADCAP-accredited aerospace programs. These arrangements insulate tier-one equipment vendors from tungsten filament cost spikes while freezing out smaller competitors unable to secure comparable terms.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across electron beam system procurement. Three-tier pricing stratifies across NADCAP-certified premium configurations, standard ISO 9001 systems, and economy-grade refurbished platforms. Pricing pressure stems from fiber laser substitution in sub-50mm penetration applications. Medical device manufacturers exhibit lowest price sensitivity given FDA validation requirements, while automotive powertrain buyers drive hardest bargains on surface hardening equipment.
Supply Chain Analysis
German and Japanese cryogenic pump manufacturing underwrites vacuum system reliability for high-value electron beam installations. Tungsten filament supply draws from Central African mining operations, while tantalum chamber liners source primarily from Russian extraction. Single-source vulnerability concentrates in cryogenic pump subcomponent supply. Distribution runs through direct OEM sales channels for large-chamber aerospace systems and third-party distributors for aftermarket electron gun assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace manufacturer consolidation around NADCAP-accredited welding specialists has shifted bargaining power decisively toward qualified tier-one suppliers, compressing margins for uncertified equipment vendors.
For Market Incumbents: Consolidate cryogenic pump supply relationships through backward integration or exclusive offtake agreements to defend against procurement bottlenecks during capacity expansions. Lock in vacuum technician training pipelines with Munich-Stuttgart technical institutes to preempt workforce scarcity. Prioritize CE marking pre-compliance for EU Machinery Directive amendments affecting integrated safety controllers. For New Entrants and Emerging Players: NADCAP fast-track partnerships with established aerospace tier-one suppliers offer the most viable entry path around 18-24 month qualification timelines. Ceramic matrix composite processing for hypersonic thermal protection systems remains underpenetrated by incumbent configurations. License technology from Japanese microwave excitation patent holders to bypass METI-supported domestic supply chain barriers. For Investors and Strategic Acquirers: Specialized large-chamber system fabricators with existing defense qualification credentials present asymmetric upside as India and South Korea accelerate localized assembly mandates. Long-term viability hinges on automation integration capabilities for shrinking production lot sizes. Monitor EU Green Deal industrial decarbonization funding allocations as inflection indicator for surface hardening equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Pump Supply Agreement | Secures vacuum subcomponent access for NADCAP-accredited production lines at Boeing tier-one suppliers. |
| CE Marking Pre-Compliance Investment | Anticipates EU Machinery Directive amendments mandating integrated safety controllers and emergency venting systems. |
| Ceramic Matrix Composite R&D Partnership | Opens silicon carbide machining applications for hypersonic thermal protection systems at defense programs. |
| Localized Assembly Licensing | Navigates India's PLI scheme capital goods incentives for missile and satellite fabrication platforms. |
| Predictive Maintenance Platform Launch | Embeds machine vision capabilities to compress downtime for Rolls-Royce turbine blade coating operations. |
Research Methodology
A standing panel of vacuum system engineers, aerospace procurement directors, FDA regulatory consultants, and aftermarket service managers provided ongoing calibration across primary interview rounds. Secondary validation incorporated EU Machinery Directive amendment drafts, NADCAP accreditation timelines, METI equipment modernization disclosures, and customs data on cryogenic pump trade flows. Bottom-up equipment shipment tallies triangulated against top-down aerospace and medical device capital expenditure patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology type, end-user industry, material processed, and application function. CAGRs derived from equipment replacement cycles, qualification timeline compression, and emerging ceramic matrix composite adoption curves. Industry-specific forecast inputs encompassed tungsten filament price volatility indices and defense procurement indigenization policy trajectories.
Underlying assumptions cover sustained NADCAP accreditation requirements, with deviation risk concentrated in fiber laser substitution rates and cryogenic pump supply disruptions. Practitioners should keep alternative scenarios live as EU Green Deal industrial decarbonization funding allocations and India PLI scheme implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Global Fans and Blowers Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Seal Inspection Equipment Market