
 Global Esports Market | 2026-2036
Global Esports Market Size, Share, and Industry Trends Forecast 2026-2036
Global Esports Market Intelligence
The professional player talent pipeline is collapsing across multiple tiers as burnout rates escalate and career longevity contracts. Team Liquid sustains its competitive edge through deep investment in player wellness infrastructure and coaching systems. FaZe Clan leverages its lifestyle brand architecture to control merchandise and content monetization beyond tournament winnings. G2 Esports differentiates through regional league dominance in Europe and cross-platform audience development.
Esports denotes organized, multiplayer video game competitions conducted between professional players, teams, or organizations, typically streamed via digital platforms with real-time audience interaction and integrated betting or fantasy mechanics. The competitive ecosystem relies on low-latency broadcast infrastructure, standardized tournament formats, and anti-cheat software protocols to ensure competitive integrity across geographically distributed participants. Sponsorship and advertisement revenue models currently anchor the value chain, though merchandise sales and subscription platforms represent the fastest-expanding margin pools as fan direct-relationship tools mature. Mobile and cloud gaming platforms are displacing traditional PC-centric tournament formats in emerging markets where hardware accessibility constraints persist.
FCC broadcast standards in the United States, GDPR data frameworks across Europe, and China's SAMR content approval processes collectively shape how tournament operators collect viewer data, structure cross-border streaming rights, and monetize youth audiences. South Korea's Game Rating and Administration Committee and the Korea Esports Association impose age-participation rules and licensing requirements that influence player contract structures and international team composition. Stakeholders must monitor evolving gambling regulation harmonization between jurisdictions as betting integration becomes central to broadcast revenue strategies and fan engagement architectures.
Market Dynamics
The convergence of 5G infrastructure deployment and cloud gaming architecture is fundamentally restructuring competitive formats and audience access models across professional and collegiate tiers.
Growth Catalysts
- GDPR data frameworks:European tournament operators now monetize viewer analytics through compliant first-party data architectures, opening direct-to-fan revenue streams previously blocked by third-party cookie deprecation.
- Franchise league expansion:City-based team permanence in South Korea, China, and the United States builds predictable sponsorship inventory and long-term media rights valuations.
- Mobile-first tournament formats:Cloud gaming platforms bypass hardware accessibility constraints in emerging markets, converting smartphone-native audiences into viewership and betting participation.
Market Restraints
- Player burnout and talent attrition:Career longevity averages under four years across tier-one rosters, forcing continuous recruitment costs and competitive instability.
- Broadcast rights fragmentation:Exclusive streaming deals across Twitch, YouTube Gaming, and regional platforms splinter audience measurement and ad inventory standardization.
- SAMR content approval timelines:China's State Administration for Market Regulation review processes delay international tournament licensing and cross-border team participation.
Strategic Opportunities
- Brazil and Southeast Asia penetration:Mobile esports tournaments exploit smartphone density and underdeveloped PC gaming infrastructure to build first-mover audience lock-in.
- Betting integration architectures:Real-time fantasy and wagering mechanics embedded in broadcast overlays capture engagement minutes and recurring transaction revenue.
- Collegiate scholarship formalization:NCAA-adjacent athletic department budgets in the United States create institutional funding pipelines for amateur-to-pro talent development.
Industry Challenges
- Anti-cheat software arms race:Kernel-level detection systems require continuous R&D investment as cheat developers exploit hardware-level vulnerabilities.
- Cross-border tax treaty complexity:Player contract structures face withholding disputes when international rosters compete in multi-jurisdiction tournament circuits.
- Intellectual property licensing fragmentation:Game publishers retain termination rights over tournament usage, creating revenue uncertainty for league operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Esports Market |
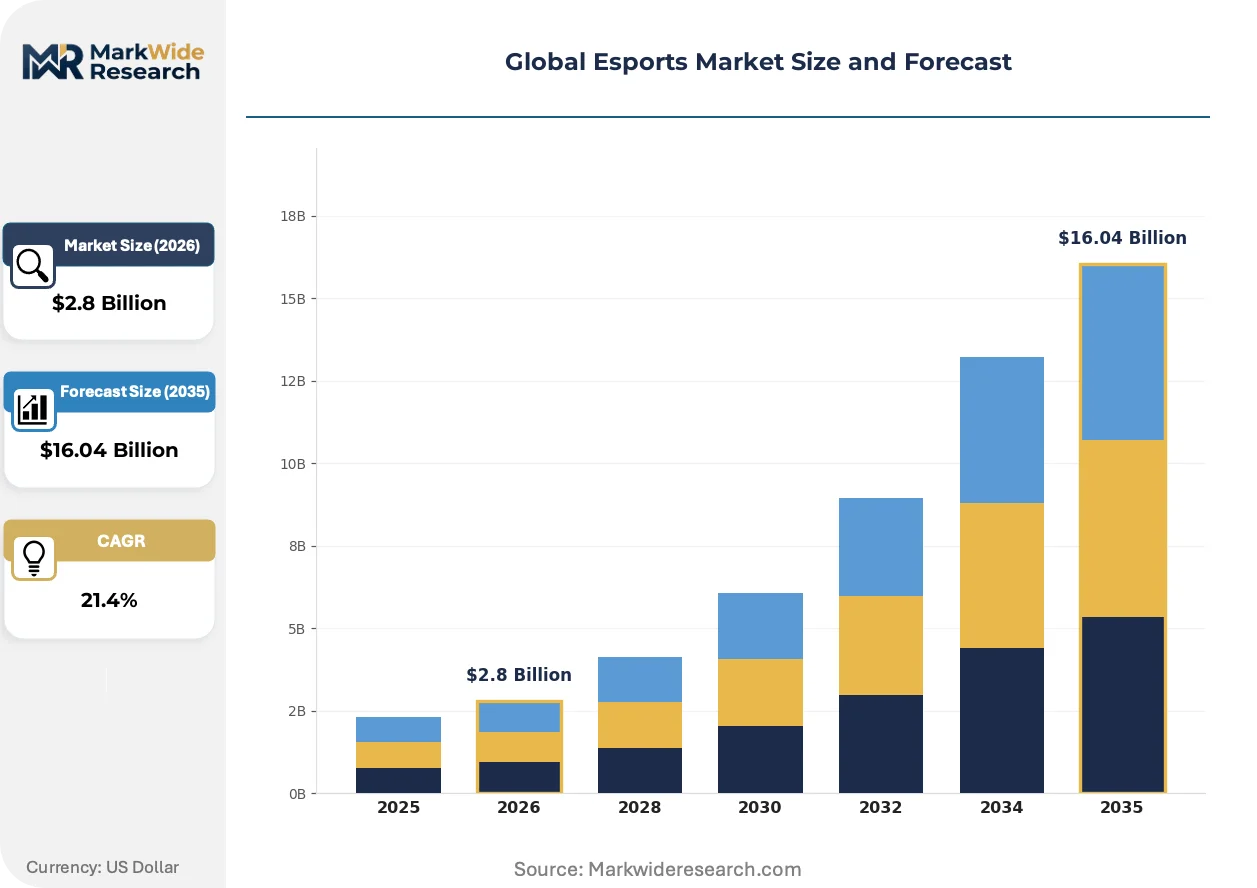
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Genre: First-Person Shooter, Multiplayer Online Battle Arena, Fighting, Real-Time Strategy, Sports Simulation, Battle Royale Platform: PC, Console, Mobile, Cloud Gaming, VR, Arcade Revenue Model: Sponsorship, Advertisement, Merchandise Sales, Ticketing, Subscriptions, Licensing Audience Segment: Casual Gamers, Professional Players, Stream Viewers, Event Attendees, Brand Followers, Content Creators |
| Companies Covered | FaZe Clan, G2 Esports, Team Liquid, Na'Vi, Fnatic, T1, Team Spirit, Gen.G Esports, Team Falcons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Esports Market Strategic Shifts & Innovations
Cloud-native broadcast infrastructure and AI-generated content tools are compressing production costs while fragmenting distribution control across platform-native ecosystems.
Edge computing nodes co-located with 5G base stations are displacing centralized server architectures for tournament hosting. Tier-two league operators in Southeast Asia and Latin America adopt these distributed systems to eliminate latency penalties without capital-intensive data center builds. This topology is displacing traditional CDN-reliant streaming models and enabling real-time betting synchronization previously impossible across geographic dispersion.
FCC broadcast standards in the United States now mandate closed captioning and accessibility overlays for digital-first sports content. Tournament operators must retrofit live production pipelines with automated speech-to-text and audio description layers, adding 12-18% to per-event technical budgets. North American franchise leagues absorb these costs through sponsor packaging while independent circuits in Europe and Asia delay compliance pending regulatory harmonization.
Subscription-based fan clubs with tiered perks and exclusive Discord access replace ad-supported viewership as the primary monetization path for mid-tier influencers and semi-pro teams. Younger demographics in South Korea and Brazil demonstrate higher willingness-to-pay for direct creator relationships than for platform memberships. This behavioral pivot forces legacy sponsorship models to reallocate budget toward individual talent contracts rather than league-wide inventory.
Global Esports Market Segmentation
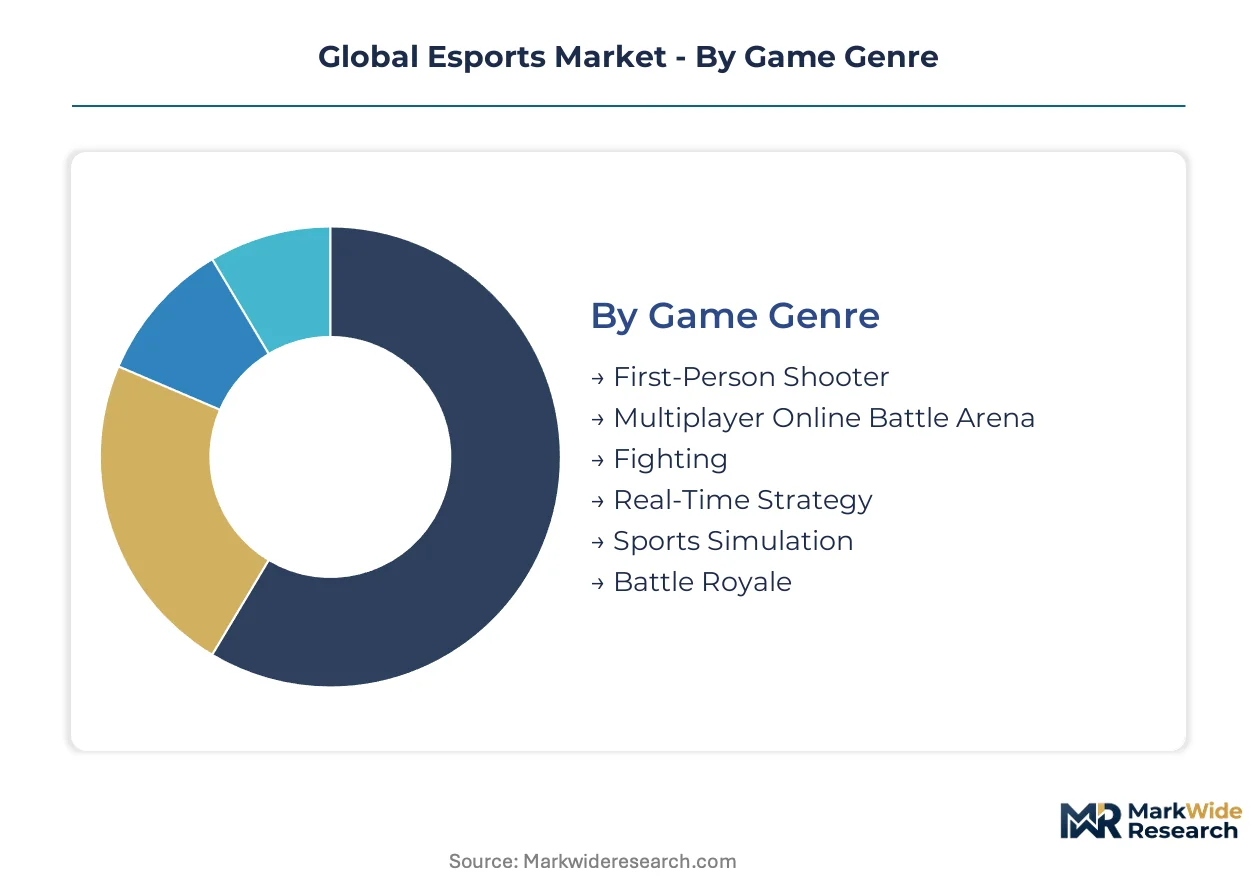
Esports market segmentation reveals divergent monetization mechanics across game genres, hardware platforms, and audience psychographics. Publishers and tournament operators calibrate investment priorities based on where engagement minutes convert to recurring revenue streams.
Game Genre:
Margin pools concentrate in genres with established franchise leagues and multi-year media rights contracts.
- Multiplayer Online Battle Arena:League of Legends and Dota 2 anchor professional circuits with standardized five-versus-five formats and deep strategic complexity. Riot Games and Valve Corporation control tournament licensing, extracting revenue share from regional league operators in China, South Korea, and Europe.
- First-Person Shooter:Counter-Strike and Call of Duty sustain the highest per-viewer betting volumes through round-based structures that enable granular live wagering. Tournament operators in the United States and Denmark optimize broadcast overlays for real-time odds synchronization.
- Battle Royale:Fortnite and PUBG Mobile convert smartphone-native audiences in Brazil and Southeast Asia through accessible drop-in formats.
- Sports Simulation:FIFA and NBA 2K leverage existing athletic brand equity to secure endemic sponsorships from equipment manufacturers.
- Fighting:Street Fighter and Tekken maintain niche but high-loyalty viewer bases through one-versus-one formats that minimize team infrastructure costs.
- Real-Time Strategy:StarCraft II retains concentrated demand in South Korea despite contracting global tournament circuits.
Multiplayer Online Battle Arena holds installed capacity. Battle Royale is rotating up the share rankings.
Platform:
Cost tier stratification separates capital-intensive PC infrastructure from low-barrier mobile penetration.
- PC:Desktop rigs with discrete GPUs deliver the lowest input latency and highest frame rates required for tier-one professional competition. Tournament operators in South Korea and Germany mandate standardized hardware specifications to ensure competitive parity across LAN events.
- Mobile:Smartphone-native platforms bypass hardware accessibility constraints in India, Indonesia, and Nigeria, converting billions of device owners into viewership and microtransaction participation. PUBG Mobile and Mobile Legends dominate esports viewership hours in these markets.
- Console:PlayStation and Xbox ecosystems anchor sports simulation and fighting game circuits through controller-standardized competition.
- Cloud Gaming:Microsoft xCloud and NVIDIA GeForce NOW reduce latency penalties through edge computing deployment, enabling competitive play on low-specification hardware.
- VR:Meta Quest and HTC Vive host experimental tournament formats in beat-saber and tactical shooter categories with limited commercial scale.
- Arcade:Japan and South Korea retain location-based fighting game competition through dedicated cabinet infrastructure.
PC retains the premium revenue tier. Mobile is climbing the fastest as smartphone density expands across emerging markets.
Revenue Model:
Customer type determines contract structure, from brand sponsorship commitments to individual fan subscriptions.
- Sponsorship:Non-endemic brands including automobile manufacturers and financial services firms commit multi-year franchise league partnerships for predictable inventory access. Team Liquid and G2 Esports package jersey placement, stream overlay integration, and player appearance rights into unified deals.
- Subscriptions:Twitch Prime and YouTube Memberships convert casual viewers into recurring revenue through exclusive emotes, ad-free viewing, and subscriber-only chat modes. South Korean and Brazilian demographics demonstrate higher willingness-to-pay for direct creator relationships than platform memberships.
- Advertisement:Pre-roll and mid-roll inventory on streaming platforms competes with traditional sports for brand budget allocation.
- Merchandise Sales:Limited-edition team apparel and peripheral collaborations capture margin from identity-driven fan segments.
- Ticketing:Arena events in Los Angeles, Berlin, and Shanghai generate per-attendee revenue through premium seating tiers and on-site merchandise.
- Licensing:Game publishers extract fees from tournament operators for commercial usage rights, creating revenue uncertainty for league sustainability.
Sponsorship holds installed capacity. Subscriptions are gaining share fastest as fan direct-relationship tools mature.
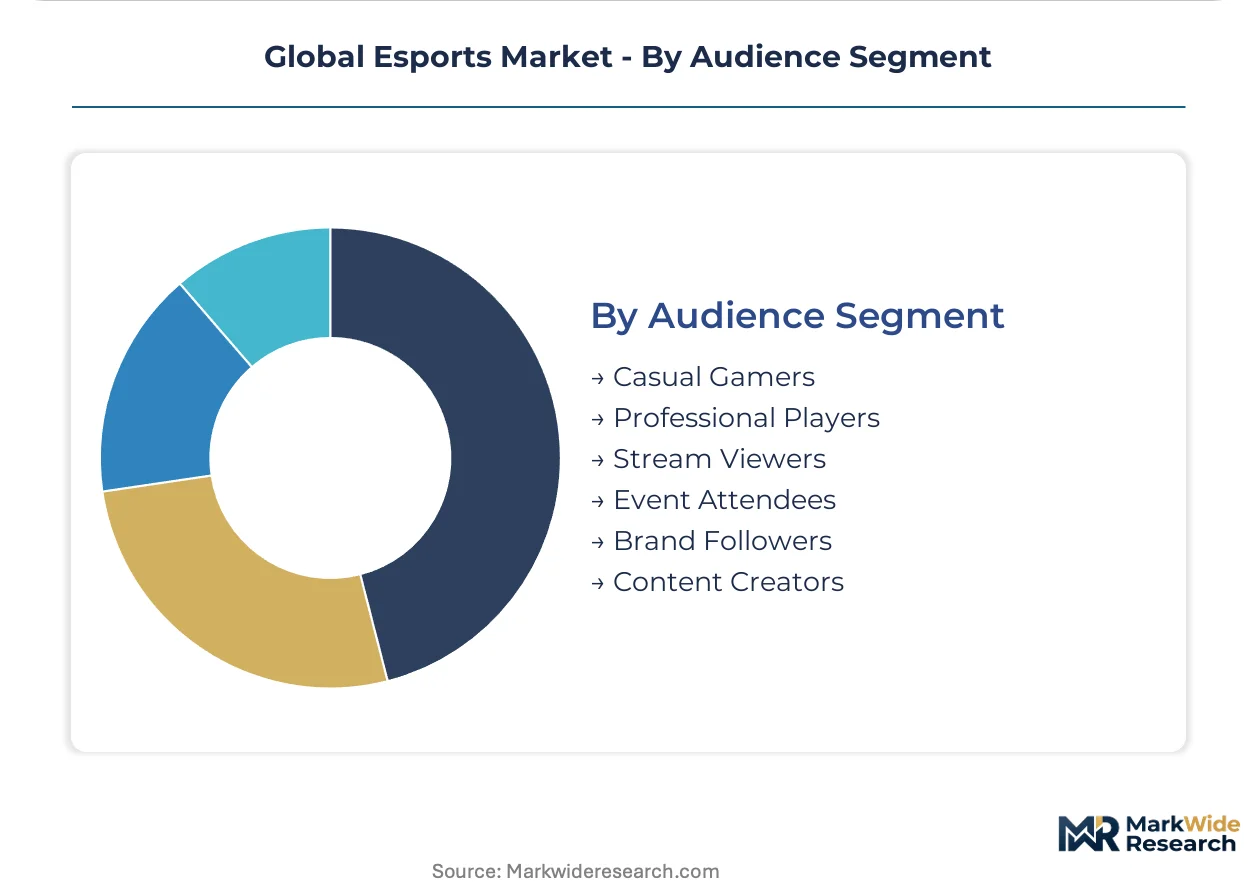
Audience Segment:
Application focus distinguishes passive consumption from active participation and content production.
- Stream Viewers:Twitch and YouTube Gaming audiences generate advertising and subscription revenue through engagement minutes, with peak concurrency during major tournament finals. FCC accessibility mandates in the United States now require closed captioning overlays, adding production cost burdens.
- Professional Players:Tier-one rosters command salary and prize pools through team contracts, though career longevity averages under four years due to burnout and mechanical skill degradation. Team Liquid invests in player wellness infrastructure to extend competitive tenure.
- Content Creators:Influencers and semi-pro streamers build direct fan relationships through Discord communities and tiered subscription perks, displacing league-wide sponsorship models.
- Casual Gamers:Ranked ladder participants convert to esports viewership through game client integration and battle pass progression systems.
- Event Attendees:Live arena audiences in Seoul, Los Angeles, and Stockholm drive merchandise velocity and local hospitality revenue.
- Brand Followers:Lifestyle-oriented fans engage with team social media and apparel without active game participation.
Stream Viewers hold installed capacity. Content Creators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes esports through institutionalized career pipelines and broadcast infrastructure, while Brazil and Indonesia access competitive gaming primarily through smartphone-native platforms without PC hardware investment.
United States
Franchise league permanence in city-based teams generates predictable sponsorship inventory and long-term media rights valuations. FCC broadcast standards mandate closed captioning and accessibility overlays for digital-first sports content, adding production cost burdens to tournament operators. Los Angeles anchors North American competitive infrastructure through arena events and premium seating tiers.
South Korea
Professional player development flows through institutionalized team houses and coaching academies with standardized training regimens. The Game Rating and Administration Committee and Korea Esports Association impose age-participation rules and licensing requirements that shape player contract structures. Seoul concentrates tier-one organization headquarters and broadcast production facilities.
China
Mobile tournament formats dominate viewership through smartphone density and cloud gaming platform penetration. SAMR content approval timelines delay international tournament licensing and cross-border team participation. Shanghai hosts major arena finals and publisher-operated league headquarters.
Brazil
Smartphone-native audiences convert to esports viewership through accessible drop-in tournament formats without hardware constraints. The country's national communications regulator oversees streaming platform compliance and youth audience protections. São Paulo anchors Latin American competitive circuits and influencer talent development.
Germany
GDPR data frameworks enable compliant first-party data architectures for direct-to-fan revenue streams previously blocked by third-party cookie deprecation. ECHA and national data protection authorities shape how tournament operators collect viewer analytics and structure cross-border streaming rights. Berlin hosts European league operations and production facilities.
Global Esports Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the esports organizational hierarchy. Tier-one organizations command franchise league slots and multi-year sponsorship commitments through diversified revenue portfolios spanning merchandise, content, and media rights. Three archetypes dominate: lifestyle brand builders, competitive excellence optimizers, and regional market consolidators. M&A activity concentrates on talent roster acquisitions and content creator network integration.
Within the lifestyle brand tier, FaZe Clan exemplifies merchandise and content monetization architectures that transcend tournament winnings. Team Liquid occupies a position emphasizing player wellness infrastructure and coaching systems to extend competitive tenure. G2 Esports anchors European regional league dominance with cross-platform audience development strategies. These three organizations represent divergent strategic postures for organizational sustainability beyond prize pool dependency.
| Leading Market Players |
|---|
| FaZe Clan |
| G2 Esports |
| Team Liquid |
| Na'Vi |
| Fnatic |
| T1 |
| Team Spirit |
| Gen.G Esports |
| Team Falcons |
| Others |
Cost & Logistics Intelligence
Franchise league scale economies in South Korea, China, and the United States compress per-event production costs while establishing price floors for media rights and sponsorship inventory. Tournament operators with locked city-based slots command premium valuations, while independent circuits without franchise permanence face margin compression from fragmented broadcast deals and rising FCC compliance burdens.
Pricing Analysis
Long-term franchise league contracts anchor media rights valuations across city-based permanence structures, while spot tournament participation fees and project-based event production contracts fill gaps for independent operators. Price differentiation rests on viewership scale and betting integration depth, with tier-one leagues in Los Angeles and Seoul commanding premiums over emerging market circuits. Pricing pressure stems from platform exclusivity fragmentation splintering audience measurement and ad inventory standardization. Collegiate athletic departments show highest price sensitivity due to NCAA-adjacent budget constraints, while endemic gaming peripheral brands demonstrate lowest sensitivity through multi-year jersey placement commitments.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for standardized PC hardware shipments to tournament venues in Germany and the United States. Supply concentrates in Taiwan for GPU components, South Korea for display panels, and China for peripheral manufacturing. Raw material dependencies span semiconductor wafers, rare earth magnets in precision controllers, and lithium-ion cells for mobile competition devices. Single-source vulnerability runs through TSMC's advanced node capacity for broadcast encoding hardware. Distribution runs through publisher-controlled licensing networks that extract revenue share from regional league operators before prize pool disbursement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in mobile-first tournament formats and cloud gaming infrastructure creates penetration tailwinds across Brazil, Indonesia, and Nigeria where smartphone density outpaces PC accessibility.
For Market Incumbents: Shield franchise league slots through exclusive streaming platform partnerships that lock in multi-year media rights valuations. Deepen vertical integration into player wellness infrastructure to extend competitive tenure and reduce continuous recruitment costs from burnout-driven talent attrition. Absorb FCC accessibility compliance costs through sponsor packaging rather than margin erosion. For New Entrants and Emerging Players: Differentiate on mobile-native tournament formats targeting Southeast Asian and Latin American markets where PC hardware constraints persist. Exploit underdeveloped collegiate scholarship formalization in NCAA-adjacent athletic departments to build first-mover talent pipelines. Deploy cloud gaming platform partnerships as the primary go-to-market angle to bypass capital-intensive data center builds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lifestyle brand builders with merchandise and content monetization architectures that transcend prize pool dependency. Long-term viability hinges on diversified revenue portfolios spanning media rights, direct-to-fan subscriptions, and betting integration overlays. Watch for SAMR content approval timeline harmonization as the signal for cross-border tournament licensing inflection in China.| Strategic Initiative | Industry Significance |
|---|---|
| Player Wellness Infrastructure Investment | Team Liquid extends competitive tenure through coaching systems and burnout prevention protocols. |
| Mobile-First Tournament Format Expansion | PUBG Mobile and Mobile Legends capture smartphone-native audiences in Brazil and Indonesia. |
| Betting Integration Architecture Development | Real-time wagering overlays in Counter-Strike broadcasts capture engagement minutes and recurring transaction revenue. |
| Cloud Gaming Platform Partnership | Microsoft xCloud and NVIDIA GeForce NOW reduce latency penalties through edge computing deployment. |
| Collegiate Scholarship Formalization | NCAA-adjacent athletic department budgets create institutional funding pipelines for amateur-to-pro talent development. |
Research Approach
The analysis maps game genre segments, platform tiers, and revenue model categories, each validated through tournament operators, team executives, streaming platform partnerships managers, and betting integration specialists. Primary interviews with esports organization CFOs and league commissioners combined with secondary validation through publisher licensing disclosures, SEC filings from publicly traded teams, Twitch viewership analytics, and regional telecommunications regulator reports. Bottom-up tournament revenue modeling and top-down media rights valuation triangulation anchor quantitative outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include game genre competitive formats, hardware platform accessibility tiers, and audience psychographic participation depth. CAGRs derived from sponsor commitment renewal rates, subscription platform growth curves, and mobile esports viewership expansion patterns. Forecast inputs incorporate 5G infrastructure deployment timelines and cloud gaming platform penetration assumptions.
The analysis sits within stated boundaries; outcomes outside franchise league permanence expansion and regulatory harmonization on betting integration would require recalibration. Forecasts reflect assumptions on player career longevity stabilization and publisher licensing fee structures. SAMR content approval delays, anti-cheat software arms race R&D burdens, and cross-border tax treaty complexity pose revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game API Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
United States Gaming Market
Gaming
Australia Gaming Accessories Market
Gaming
Puzzle Video Game Market
Gaming
H5 Games Market
Gaming
China in-Game Advertising Market
Gaming
Gaming Gadgets Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Galgames Market
Gaming
Africa Gaming Market
Gaming
RPG Games Market
Gaming
Social Gaming Market
Gaming
VR Gaming Accessories Market
Gaming
GCC Gaming Headsets Market
Gaming
Russia in-Game Advertising Market