
 Australia Gaming Accessories Market | 2026-2036
Australia Gaming Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Gaming Accessories Market Insights
High-refresh-rate mechanical keyboard specifications is rotating through the mid-premium tier as Australian consumers replace membrane-based peripherals. Razer Inc. leverages its Sydney-based distribution hub to sustain same-day fulfillment across southeastern states. Corsair Gaming Inc. anchors its position through in-house production of proprietary mechanical switches, reducing reliance on third-party Cherry MX supply chains.
Gaming accessories encompass input peripherals, audio equipment, and display-adjacent hardware engineered for sub-20ms latency, 1000Hz polling rates, and mechanical actuation forces between 45-60g for competitive use. The category serves commercial purposes spanning professional esports training, content creation workflows, and immersive single-player experiences. Headsets with wireless low-latency codecs capture expanding margin pools as streamers prioritize broadcast-quality audio fidelity. Mechanical switch keyboards outpace membrane alternatives in replacement velocity among esports participants. Controllers face pressure from cross-platform standardization as console-PC hybrid play expands.
ACMA enforces RCM compliance and electromagnetic compatibility standards for all wireless gaming peripherals sold in Australia, elevating certification costs for new market entrants. TGA oversight applies to extended-wear gaming headsets with active noise cancellation marketed with health claims. Energy rating requirements under the GEMS Act shape power adapter specifications for charging docks and wireless charging mats. Stakeholders must monitor how ACMA's evolving spectrum allocation for low-latency wireless protocols reshapes product development roadmaps for next-generation peripherals.
Market Dynamics
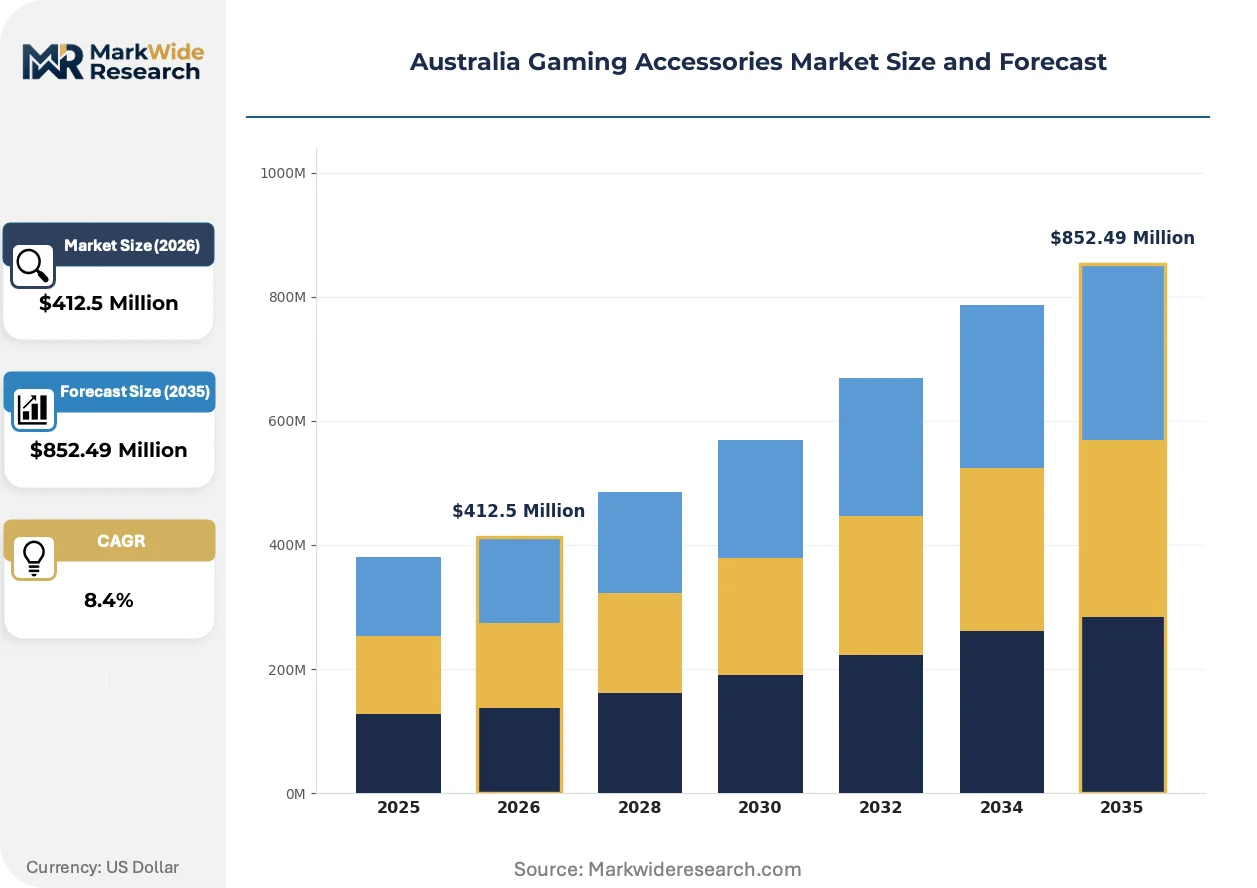
ACMA's tightening electromagnetic compatibility certification for wireless peripherals is compressing product development timelines and elevating compliance costs for new entrants, while professional esports participants accelerate hardware refresh cycles across New South Wales and Victoria.
Growth Catalysts
- Professional esports training infrastructure:Gaming cafes and dedicated esports venues clustering around Sydney and Melbourne are driving institutional procurement of low-latency peripherals. Tournament-grade specifications are filtering into consumer purchase criteria.
- ACMA spectrum allocation for low-latency wireless protocols:Regulatory support for dedicated wireless bands is enabling peripheral manufacturers to develop next-generation products with sub-20ms latency performance.
- Content creator economy expansion:Australian streamers and broadcast-quality audio workflows are capturing expanding margin pools for wireless low-latency codec headsets.
Market Restraints
- Cherry MX supply chain concentration:Proprietary mechanical switch production remains concentrated among limited third-party suppliers, creating input cost volatility for keyboard manufacturers without in-house capabilities.
- RCM certification cost structure:ACMA electromagnetic compatibility testing and documentation requirements impose fixed cost barriers that disproportionately constrain smaller peripheral vendors.
- Cross-platform controller standardization:Console-PC hybrid play expansion is eroding differentiation for proprietary controller ecosystems, compressing margin pools in the gamepad segment.
Strategic Opportunities
- Queensland and Western Australia venue penetration:Underdeveloped gaming cafe density in Brisbane and Perth relative to Sydney-Melbourne corridors offers whitespace for peripheral distribution expansion.
- GEMS Act energy rating optimization:Power adapter efficiency requirements are creating regulatory tailwinds for charging dock manufacturers that engineer ahead of minimum thresholds.
- Mechanical-membrane hybrid switch convergence:Development of actuation technologies blending tactile response with cost efficiency could capture price-sensitive segments without full premium positioning.
Industry Challenges
- TGA extended-wear certification timelines:Active noise cancellation headsets marketed with health claims face prolonged approval cycles that delay product launches and compress revenue recognition windows.
- Wireless protocol integration complexity:Legacy peripheral architectures require substantial re-engineering to support ACMA-allocated low-latency spectrum standards, elevating R&D capex intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Gaming Accessories Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Keyboards, Headsets, Mice Technology: Wireless, Wired, Optical, Mechanical End User: Casual Gamers, Professional Gamers, Streamers, Esports Participants Distribution Channel: Online Retailers, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | Dell Australia Pty Limited, Logitech International S.A., Voyetra Turtle Beach, Inc., HP Inc., NZXT Australia Pty Ltd, Razer Inc., Corsair Gaming Inc., SteelSeries, Cooler Master Technology Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Gaming Accessories Market Trends and Innovations
Hardware specifications are rotating through the mid-premium tier as Australian consumers replace membrane-based peripherals, while regulatory compliance and wireless protocol evolution reshape competitive positioning.
Magnetic switch technology is fragmenting actuation customization in mechanical keyboards. Esports participants and competitive gamers are adopting Hall-effect and adjustable actuation point switches at accelerating velocity. This technology is fragmenting the traditional Cherry MX-dominated landscape by enabling per-key customization without physical switch replacement.
ACMA's electromagnetic compatibility enforcement under RCM standards is elevating product development rigor. Wireless peripheral manufacturers must now embed certification testing earlier in design cycles, extending time-to-market. The headset and wireless controller segments are responding by consolidating certification expertise in-house or partnering with Sydney-based testing facilities.
Consumer replacement cycles for input peripherals are compressing as streaming and content creation workflows professionalize. Mid-premium mechanical keyboards are displacing membrane alternatives in volume terms among Australian buyers. This behavioral shift is most visible in New South Wales and Victoria, where gaming cafe density correlates with accelerated upgrade frequency among adjacent consumer segments.
Australia Gaming Accessories Market Segmentation
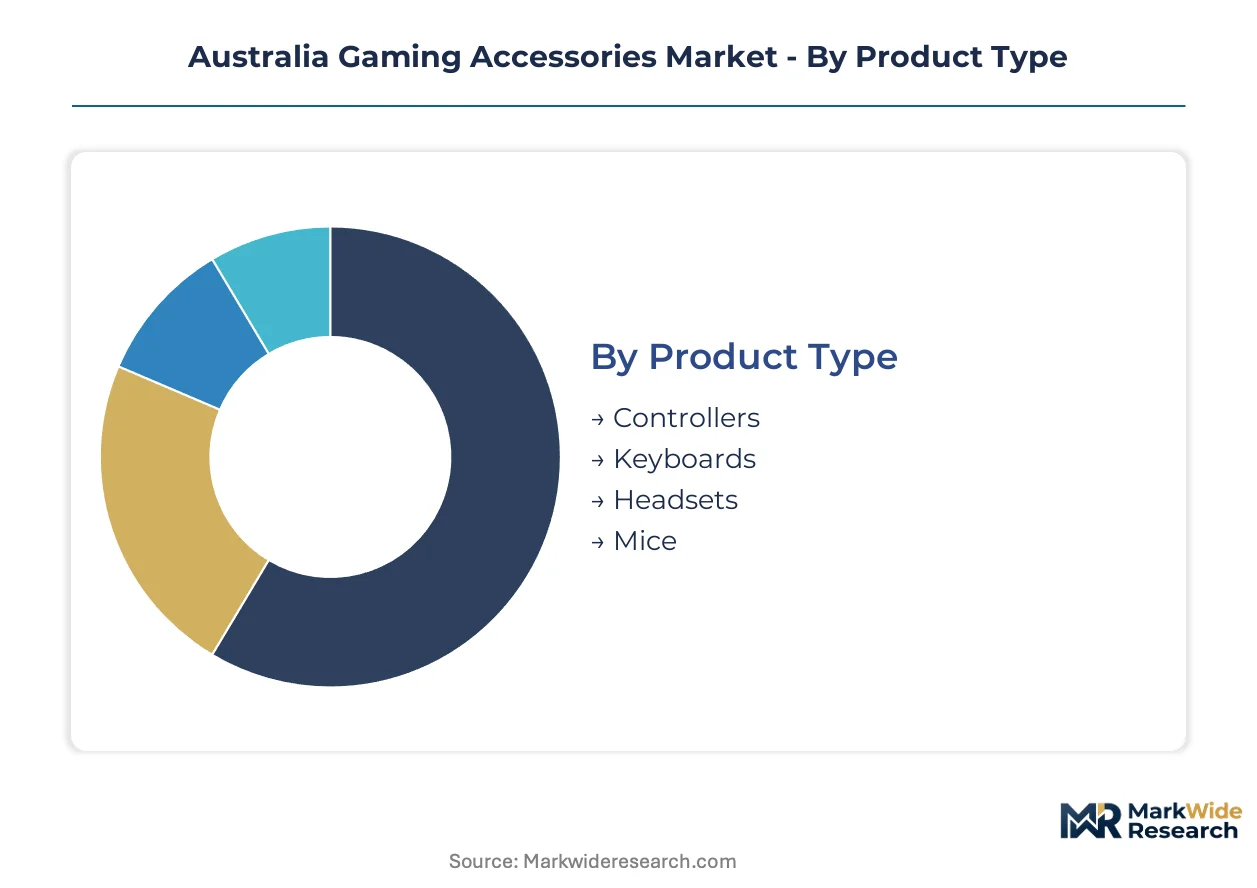
Segmentation in the Australian gaming accessories market reveals how procurement patterns diverge across professional versus casual use cases, with regulatory compliance and latency specifications creating distinct margin tiers. Understanding these divisions enables targeted positioning against ACMA certification requirements and state-level demand concentration.
Product Type:
Margin pools concentrate in peripherals where technical differentiation commands pricing power against membrane alternatives and cross-platform standardization pressures.
- Controllers:Gamepads engineered for console-PC hybrid play face margin compression from cross-platform standardization. Queensland and Western Australia retail channels show underpenetration relative to New South Wales and Victoria, where gaming cafe density sustains institutional procurement.
- Keyboards:Mechanical switch configurations with Hall-effect actuation and customizable actuation points are displacing membrane alternatives in volume terms. New South Wales and Victoria consumers upgrade most frequently, driven by adjacent gaming cafe culture and esports venue clustering around Sydney and Melbourne.
- Headsets:Wireless low-latency codecs with broadcast-quality audio fidelity capture expanding margins among Australian streamers. TGA extended-wear certification applies to active noise cancellation models marketed with health claims.
- Mice:Optical and wireless variants with sub-20ms latency and 1000Hz polling rates serve competitive gaming requirements. ACMA electromagnetic compatibility standards elevate certification costs for wireless entrants.
The dominant share belongs to Keyboards, while Headsets are closing the gap fastest as content creator workflows professionalize audio requirements.
Technology:
Cost tier stratification separates premium wireless implementations from value-positioned wired alternatives, with mechanical actuation commanding sustained price premiums.
- Wireless:Low-latency protocols operating on ACMA-allocated spectrum enable sub-20ms performance critical for esports. RCM certification requirements under electromagnetic compatibility standards extend development timelines and elevate fixed costs for new market entrants.
- Wired:USB-C and legacy USB-A connections retain volume share among price-sensitive segments and tournament environments where interference elimination outweighs convenience. Mass merchant channels in Perth and Brisbane distribute these configurations most heavily.
- Optical:Sensor technologies in mice deliver precision tracking without mechanical wear, appealing to professional gamers with compressed refresh cycles. In-house production capabilities reduce supply chain volatility for manufacturers.
- Mechanical:Proprietary switch production and magnetic Hall-effect technologies fragment the traditional third-party supplier landscape. Australian consumers in southeastern states rotate through mid-premium tiers most rapidly.
Wireless configurations hold the dominant revenue position, though Mechanical switch technologies are expanding share fastest through actuation customization demand.
End User:
Customer type determines specification intensity, with professional use cases demanding tournament-grade latency and durability standards that casual segments bypass.
- Casual Gamers:Price-sensitive buyers prioritizing single-player immersion and basic multiplayer functionality. Membrane keyboards and standard headsets satisfy requirements without premium positioning.
- Professional Gamers:Esports participants with compressed hardware refresh cycles and institutional procurement through gaming cafes. Tournament-grade specifications filter into purchase criteria most visibly in Sydney and Melbourne corridors.
- Streamers:Content creators demanding broadcast-quality audio fidelity and peripheral aesthetics for on-camera presentation. Wireless low-latency codec headsets capture this segment's margin concentration.
- Esports Participants:Organized competitors with standardized equipment requirements from venue operators and tournament organizers. ACMA-compliant wireless peripherals face mandatory adoption as venue infrastructure upgrades.
Professional Gamers command the dominant share by value, with Streamers climbing fastest as the Australian content creator economy expands.
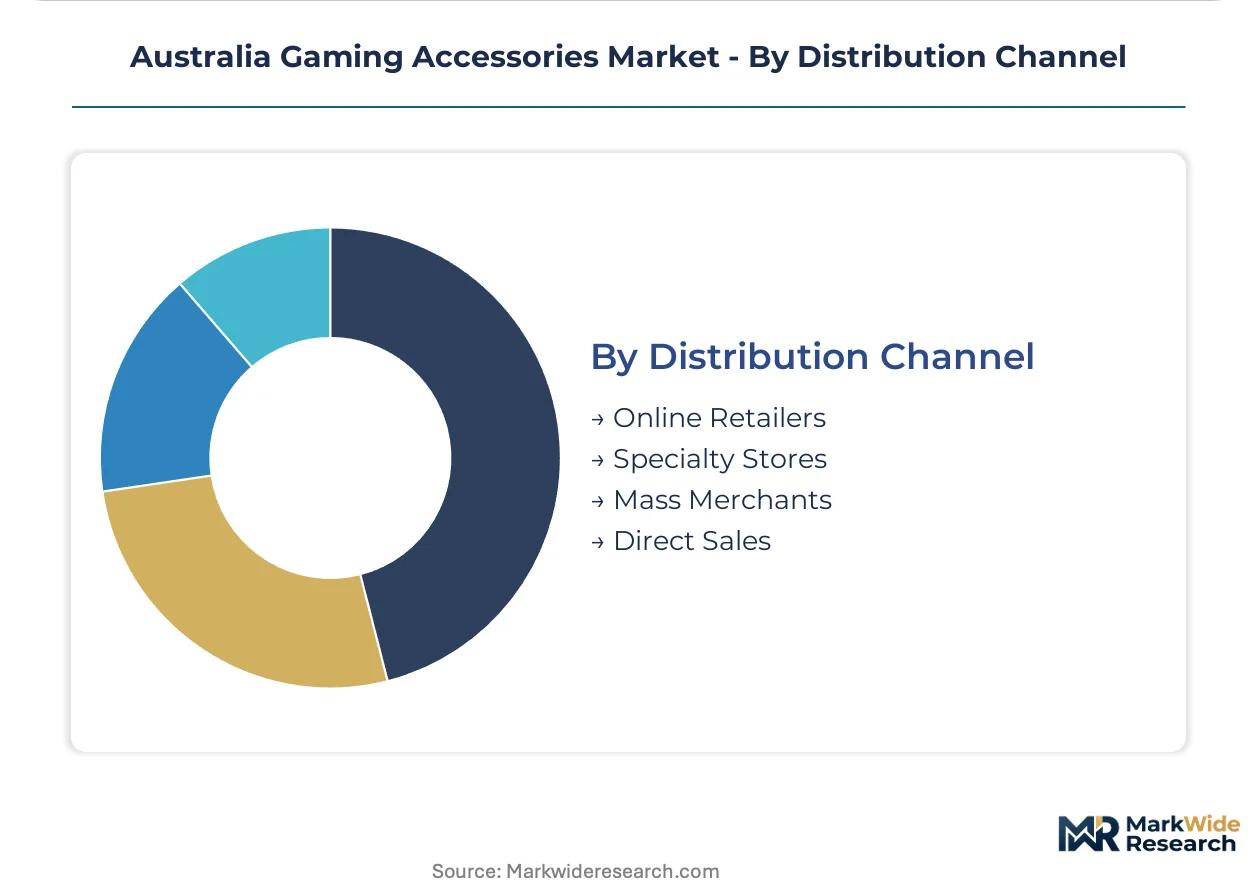
Distribution Channel:
Geography shapes channel effectiveness, with southeastern state density favoring same-day fulfillment networks and specialty retail expertise.
- Online Retailers:E-commerce platforms enabling national reach beyond Sydney-Melbourne concentration, with same-day fulfillment capabilities anchored by southeastern distribution hubs.
- Specialty Stores:Focused gaming retailers providing technical consultation and hands-on peripheral testing. These channels cluster in New South Wales and Victoria where consumer knowledge and upgrade frequency run highest.
- Mass Merchants:Broad retail networks serving price-sensitive segments and gift purchase occasions. Brisbane and Perth show relative overrepresentation as gaming cafe density lags southeastern states.
- Direct Sales:Manufacturer-owned channels capturing full margin and enabling subscription-style refresh programs for institutional esports venues.
Online Retailers maintain the dominant position, while Direct Sales are expanding most quickly through institutional esports venue procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia runs a substantial trade deficit in gaming peripherals, with domestic consumption outpacing local assembly capacity. Import flows concentrate through Port Botany and Port of Melbourne, where ACMA pre-certification documentation accelerates customs clearance for RCM-compliant wireless devices.
New South Wales
Sydney anchors the nation's highest gaming cafe density, with institutional procurement from esports venues driving tournament-grade peripheral demand. ACMA's Sydney-based electromagnetic compatibility testing facilities compress certification timelines for wireless headset manufacturers. Parramatta and Macquarie Park host distribution hubs enabling same-day fulfillment across southeastern corridors.
Victoria
Melbourne's esports venue clustering around the CBD and inner suburbs sustains compressed hardware refresh cycles among adjacent consumer segments. The state's Consumer Affairs Victoria enforces product safety standards for extended-wear peripherals marketed with ergonomic claims. Docklands and Dandenong South concentrate specialty retail channels and third-party logistics operations.
Queensland
Brisbane exhibits underdeveloped gaming cafe density relative to southeastern states, creating whitespace for peripheral distribution expansion. The Queensland Office of Fair Trading administers warranty and consumer protection frameworks affecting retail channel operations. Fortitude Valley and South Bank host emerging esports venue developments with nascent institutional procurement relationships.
Western Australia
Perth's geographic isolation elevates inventory carrying costs for peripheral distributors serving remote mining communities and regional centers. The state's Department of Energy, Mines, Industry Regulation and Safety oversees electrical safety standards for gaming peripheral power adapters. Canning Vale and Welshpool industrial zones concentrate mass merchant distribution infrastructure.
South Australia
Adelaide's lower population density supports price-sensitive peripheral consumption through mass merchant channels rather than specialty retail. Consumer and Business Services South Australia regulates product labeling and warranty disclosure requirements. The Tonsley Innovation District hosts limited gaming hardware assembly operations with primarily domestic market focus.
Australia Gaming Accessories Market Competitive Landscape
Listed leaders compete with private specialists across certification bandwidth and distribution reach. The vendor base fragments between multinational peripheral conglomerates with in-house switch production and regional distributors reliant on third-party supply chains. Three archetypes dominate: vertically integrated manufacturers with captive component supply, brand licensors leveraging OEM partnerships, and specialty retailers with technical consultation capabilities. Competitive moves concentrate on geographic expansion into underpenetrated state markets and portfolio diversification into wireless low-latency codecs.
Within the multinational tier, Razer Inc. and Corsair Gaming Inc. exemplify divergent supply chain strategies. Razer anchors its position through a Sydney-based distribution hub sustaining same-day fulfillment across New South Wales and Victoria. Corsair occupies a position emphasizing in-house mechanical switch production, reducing exposure to Cherry MX supply concentration. Logitech International S.A. sits within the scale-driven archetype, leveraging broad portfolio breadth across input peripherals and audio equipment.
| Leading Market Players |
|---|
| Dell Australia Pty Limited |
| Logitech International S.A. |
| Voyetra Turtle Beach, Inc. |
| HP Inc. |
| NZXT Australia Pty Ltd |
| Razer Inc. |
| Corsair Gaming Inc. |
| SteelSeries |
| Cooler Master Technology Inc. |
| Others |
Pricing and Supply Chain Analysis
Scale economies in Cherry MX-compatible switch manufacturing concentrate component supply among East Asian foundries, compressing margin floors for keyboard assemblers without captive production while elevating pricing power for vertically integrated manufacturers with in-house mechanical switch capabilities.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels in the Australian gaming accessories market. Price differentiation rests on ACMA RCM certification grade and Hall-effect actuation customization depth, with certified wireless peripherals commanding sustained premiums over wired alternatives. Cost compression in the mid-premium tier is intensifying because magnetic switch technologies fragment traditional Cherry MX dominance. Casual gamers in Queensland and Western Australia exhibit highest price sensitivity, while professional esports venues in Sydney and Melbourne demonstrate lowest sensitivity to tournament-grade specifications.
Supply Chain Analysis
China and Taiwan anchor mechanical switch fabrication and printed circuit board assembly for wireless gaming peripherals. Component sourcing draws from Japanese optical sensor foundries and South Korean low-latency codec semiconductor suppliers. Single-source vulnerability concentrates in proprietary Hall-effect magnetic switch suppliers, where limited qualified vendors create qualification bottlenecks. Distribution runs through Sydney and Melbourne-based third-party logistics hubs enabling same-day fulfillment across southeastern states, with Port Botany and Port of Melbourne handling ACMA pre-certified import clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as professional esports training infrastructure professionalizes procurement standards, creating niche specifications that bypass mass-market commoditization.
For Market Incumbents: Fortify certification bandwidth through Sydney-based electromagnetic compatibility testing partnerships, compressing ACMA RCM approval timelines against emerging entrants with limited regulatory expertise. Deepen in-house mechanical switch production to reduce Cherry MX supply concentration exposure. Prioritize direct sales channel development for institutional esports venue procurement relationships.
For New Entrants and Emerging Players: Lead with Queensland and Western Australia geographic whitespace, where gaming cafe density lags New South Wales and Victoria corridors and mass merchant channels dominate price-sensitive segments. Target Brisbane and Perth specialty retail development with technical consultation capabilities. Deploy subscription-style refresh programs for emerging esports venues seeking standardized equipment procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among peripheral manufacturers with institutional esports venue direct sales relationships and proprietary mechanical switch production capabilities. Long-term viability favors vertically integrated specialists with certification expertise and southeastern distribution infrastructure. Monitor ACMA spectrum allocation announcements for low-latency wireless protocols as inflection indicator for next-generation peripheral R&D capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| ACMA Certification Investment | RCM electromagnetic compliance compresses time-to-market for wireless headset launches. |
| In-House Switch Production | Captive mechanical switch manufacturing reduces Cherry MX supply chain volatility exposure. |
| Queensland Distribution Expansion | Brisbane gaming cafe whitespace offers first-mover advantage in institutional procurement. |
| Magnetic Switch Technology Integration | Hall-effect actuation customization captures mid-premium tier replacement velocity. |
| Direct Sales Channel Development | Manufacturer-owned subscription programs secure recurring esports venue revenue. |
Research Methodology
Initial hypotheses were tested against primary input from esports venue procurement managers, peripheral distribution channel heads, ACMA compliance consultants, and gaming cafe operators and refined through secondary validation against customs import records, ACMA RCM certification databases, Australian Bureau of Statistics retail trade data, and esports tournament infrastructure investment disclosures. Bottom-up segment sizing triangulated with top-down market reconstruction across product type, technology configuration, end-user archetype, and distribution channel dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning mechanical versus membrane switch technologies, wireless versus wired connectivity, professional versus casual end-user specifications, and online versus specialty versus mass merchant channel flows. CAGRs were derived from fitted growth curves incorporating hardware refresh cycle compression rates, gaming cafe venue expansion trajectories, and ACMA regulatory compliance cost escalation assumptions.
Forecasts assume regulatory continuity in ACMA electromagnetic compatibility and TGA extended-wear headset certification regimes; material policy shifts would require re-modeling. Specific risks include ACMA spectrum reallocation disrupting low-latency wireless protocol roadmaps, Cherry MX supply concentration shocks elevating input costs, and cross-platform controller standardization eroding gamepad margin pools. Recalibration cycles align with material shifts in esports venue infrastructure investment and ACMA regulatory guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game Applications Market
Gaming
Europe Video Game Software Market
Gaming
Arcade Cabinet Market
Gaming
SLG Game Market
Gaming
Australia Casino Tourism Market
Gaming
North America Gaming Market
Gaming
Online Casual Games Market
Gaming
China Subscription-Based Gaming Market
Gaming
Mobile Shooter Market
Gaming
Social Gaming Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Southeast Asia Gaming Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Latin America Mobile Gaming Market
Gaming
North America Casino Gambling Market
Gaming
Mobile Game Software Market