
 Middle East and Africa Gaming Headsets Market | 2026-2036
Middle East and Africa Gaming Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Gaming Headsets Market Insights
Wireless audio latency is narrowing the performance gap between RF and analog connections across competitive gaming environments. Razer Inc leverages its esports sponsorship network to sustain brand visibility in Saudi Arabian tournament circuits. SteelSeries anchors its regional position through specialized distribution partnerships with Middle Eastern gaming retailers. Corsair Gaming Inc competes on RGB customization and firmware ecosystem control to differentiate its headset portfolio from commodity alternatives.
Gaming headsets are over-ear audio peripherals engineered with 20 Hz–20 kHz frequency response, directional microphone arrays, and cushioned ear cups designed for extended wear during competitive or immersive gameplay. Their primary commercial purpose is to deliver spatial audio positioning and voice communication clarity in multiplayer environments. Wireless headsets incorporating Bluetooth and RF technology are capturing disproportionate growth as 5G rollouts reduce latency concerns across the Middle East and Africa. The professional gamers and esports athletes end-user segment commands premium pricing due to tournament-grade certification requirements and sponsor-driven equipment standards. Wired USB-C configurations retain volume dominance in price-sensitive North African markets where import duties inflate wireless product costs.
Saudi Arabia's Communications and Information Technology Commission and South Africa's Independent Communications Authority regulate wireless spectrum allocation for gaming peripherals, directly shaping which RF technologies manufacturers can deploy. South African National Standards and SASO certification requirements in Saudi Arabia mandate electromagnetic compatibility testing that filters lower-cost uncertified imports from regional distribution channels. Stakeholders must monitor evolving spectrum harmonization agreements between Gulf Cooperation Council regulators and sub-Saharan African authorities to anticipate which wireless protocols will achieve cross-border approval.
Market Dynamics
5G infrastructure deployment across Gulf Cooperation Council states is compressing wireless audio latency to competitive parity with wired connections, fundamentally altering headset procurement criteria for esports venues and professional gaming circuits.
Growth Catalysts
- Saudi Vision 2030 esports investments:Government-funded gaming arenas in Riyadh and Jeddah mandate tournament-grade peripheral procurement, creating certified demand pipelines for RF-enabled headsets.
- ICASA spectrum harmonization:South Africa's regulator has allocated dedicated 2.4 GHz and 5 GHz bands for low-latency wireless audio, removing RF interference barriers that previously constrained competitive adoption.
- Cloud gaming infrastructure:Microsoft Azure and Amazon Web Services data centers in UAE and South Africa reduce round-trip latency for streamed titles, amplifying headset dependency for spatial audio positioning in browser-based competitive play.
Market Restraints
- SASO certification costs:Saudi Arabia's electromagnetic compatibility testing requirements add 15-20% to landed costs for uncertified manufacturers, filtering budget-tier imports from distribution channels.
- Import duty stacking:North African markets including Egypt and Morocco impose cumulative tariffs on Bluetooth chipsets and lithium battery cells, inflating wireless headset retail prices versus wired USB-C alternatives.
- Sub-Saharan logistics fragmentation:Last-mile distribution across Kenya, Nigeria, and Ghana relies on informal retail networks that lack technical support infrastructure for firmware-dependent wireless products.
Strategic Opportunities
- Ethiopia and Kenya gaming café expansion:Nairobi and Addis Ababa host underpenetrated PC gaming venue networks where entry-level wired headsets face minimal wireless competition due to price sensitivity.
- TRAI-equivalent spectrum convergence:Gulf Cooperation Council regulators are negotiating unified RF certification standards that would enable single-approval headset distribution across UAE, Qatar, Bahrain, and Oman.
- Mobile esports tournament circuits:PUBG Mobile and Free Fire competitions across North Africa create demand for lightweight 3.5mm headsets compatible with smartphone audio jacks, a category neglected by premium wireless-focused vendors.
Industry Challenges
- Firmware localization timelines:Arabic-language voice prompt integration and right-to-left UI adaptation delay product launches by 4-6 months versus English-first markets.
- Heat management in desert climates:Extended wear sessions in Saudi and UAE gaming venues expose closed-back headset designs to thermal discomfort, requiring material engineering iterations that extend R&D cycles.
- Counterfeit certification documentation:Unauthorized SASO and ICASA markings on gray-market imports from Southeast Asia complicate brand protection enforcement for legitimate distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Gaming Headsets Market |
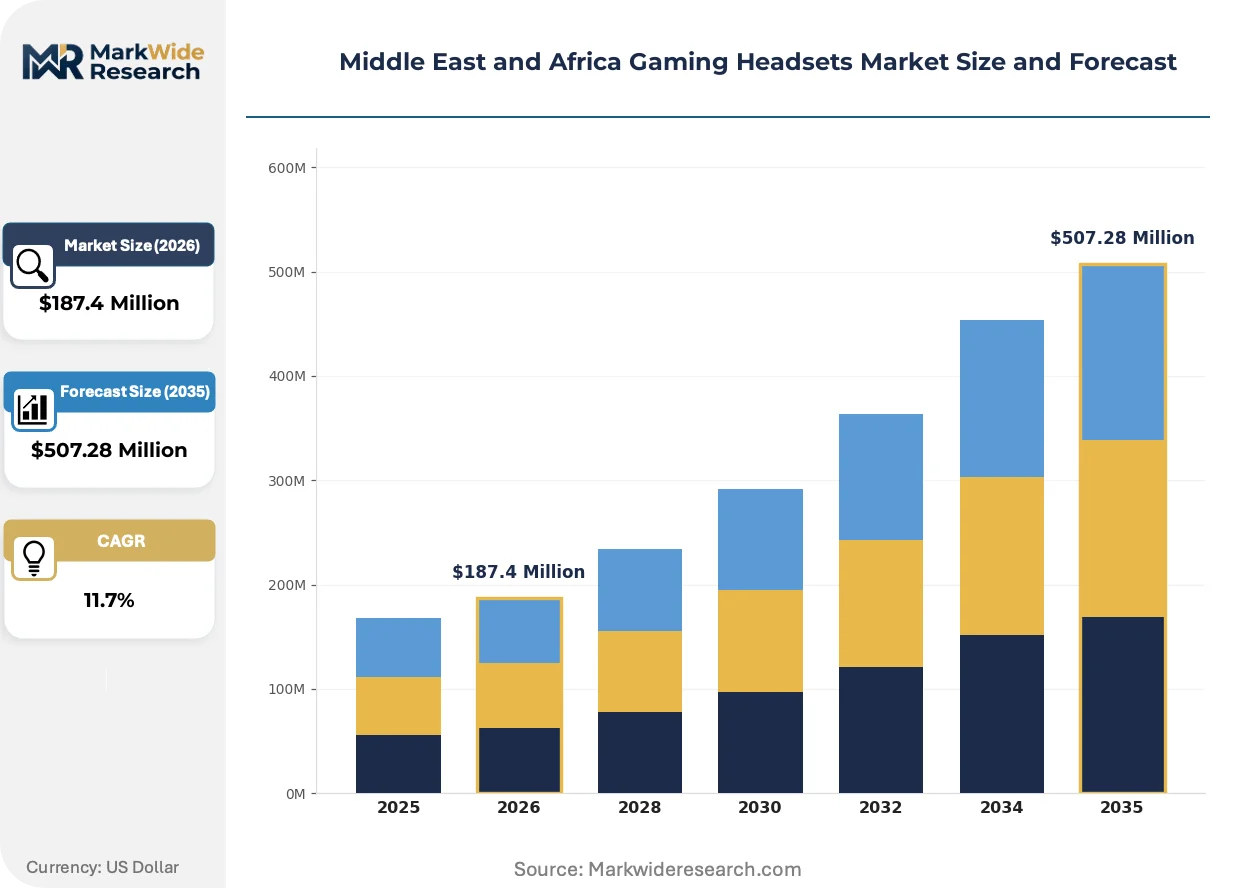
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Noise-Canceling, Surround Sound Technology: Bluetooth, USB-C, RF, Analog End User: Professional Gamers, Casual Gamers, Streamers, Esports Athletes Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Razer Inc, SteelSeries, Corsair Gaming Inc, Logitech International SA, Sony Interactive Entertainment Inc, HyperX, Turtle Beach Corporation, Cooler Master Technology Inc, ASTRO Gaming, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Gaming Headsets Market Trends and Innovations
Audio peripheral architecture is converging with mobile connectivity standards, compressing development cycles and forcing vendors to synchronize headset firmware with smartphone OS release schedules rather than console hardware generations.
Low-latency wireless protocols are hybridizing proprietary RF stacks with Bluetooth LE Audio to serve dual-use scenarios. Saudi esports venues deploy tournament-grade RF base stations for competitive play while casual users toggle to Bluetooth for mobile companion apps. This convergence is collapsing the premium-tier SKU count vendors must maintain, reducing inventory carrying costs for regional distributors.
SASO technical regulations for electromagnetic compatibility are tightening testing protocols for 2.4 GHz band congestion management. Manufacturers must now demonstrate coexistence performance with Wi-Fi 6E routers and microwave appliances. Headset vendors targeting Saudi retail channels are redesigning antenna architectures to pass revised interference benchmarks ahead of enforcement deadlines.
Esports team sponsorship contracts are displacing traditional retail marketing as the primary demand generation channel. South African and UAE-based professional rosters specify equipment partners in streaming disclosures, directing fan purchases through team-affiliate links rather than brick-and-mortar shelf placement. Peripheral vendors are reallocating trade marketing budgets to player endorsement retainers and tournament title sponsorships.
Middle East and Africa Gaming Headsets Market Segmentation
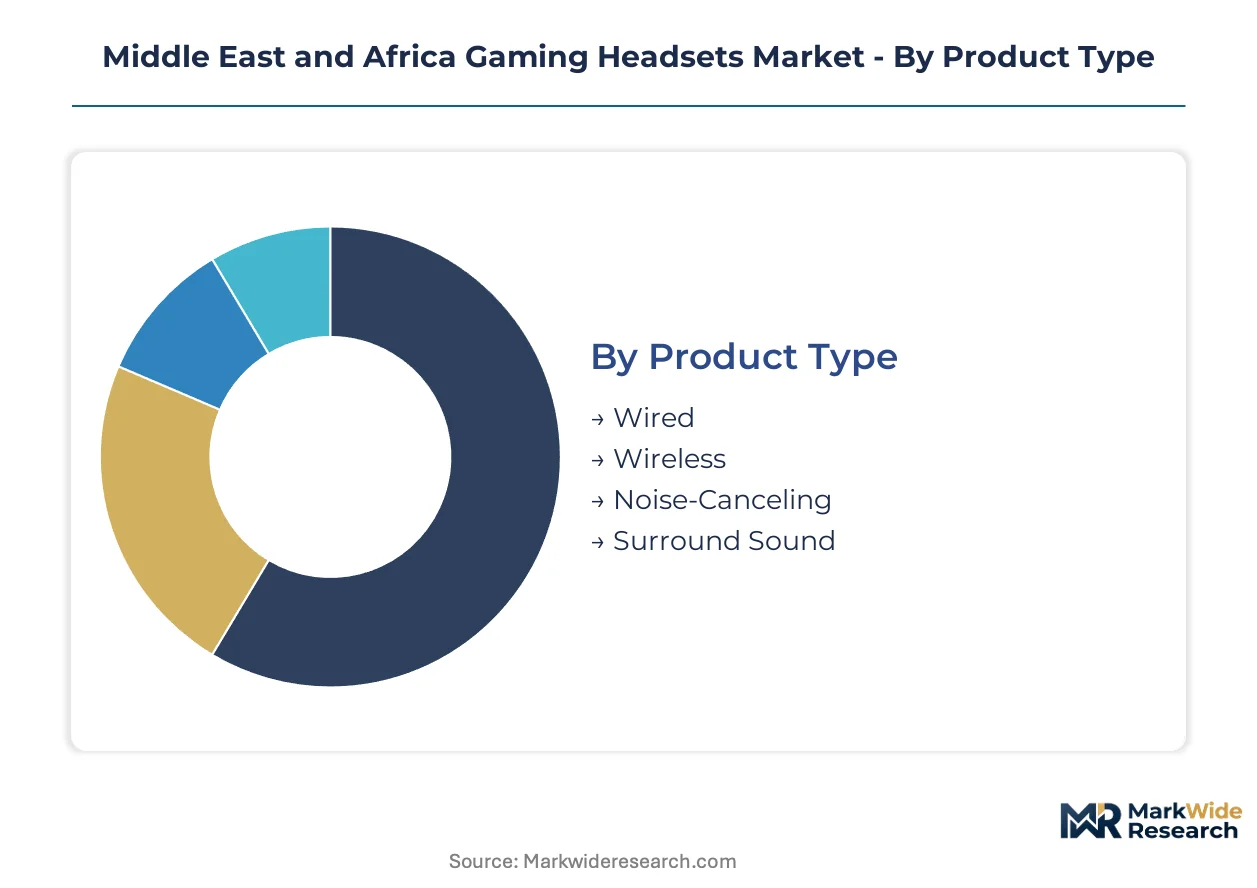
Segmentation in the Middle East and Africa gaming headsets market reveals divergent procurement patterns across connectivity standards, user certification requirements, and retail infrastructure maturity. Understanding these fault lines enables vendors to align SKU portfolios with Saudi Arabia's tournament-grade mandates versus North Africa's price-sensitive volume channels.
Product Type:
Cost tier differentiation separates entry-level peripherals from esports-certified equipment, with connectivity architecture driving the primary price wedge.
- Wireless:RF and Bluetooth-enabled headsets with sub-20ms latency specifications dominate Saudi and UAE esports venue procurement. Government-backed arena investments in Riyadh and Jeddah mandate untethered peripherals for tournament play. The steepest expansion runs through this segment as 5G infrastructure compresses latency gaps with wired alternatives.
- Wired:USB-C and 3.5mm configurations retain volume leadership in Egyptian and Moroccan retail channels where cumulative import duties on lithium cells and Bluetooth chipsets inflate wireless pricing. North African gaming cafés favor these units for their zero-latency reliability and lower replacement costs.
- Surround Sound:7.1-channel virtualized audio headsets with positional mapping algorithms serve competitive FPS players in South African tournament circuits.
- Noise-Canceling:Active noise cancellation variants with environmental sound filtering target streamers in Dubai and Johannesburg content production studios.
Wireless commands the established base. The steepest expansion runs through Surround Sound as spatial audio becomes mandatory for tournament certification.
Technology:
Application context determines protocol selection, with competitive environments demanding dedicated RF stacks while casual mobile play tolerates Bluetooth LE Audio tradeoffs.
- RF:Proprietary radio frequency protocols operating in ICASA-allocated 2.4 GHz and 5 GHz bands deliver sub-15ms latency for South African and Saudi professional circuits. Spectrum harmonization negotiations across Gulf Cooperation Council regulators are streamlining cross-border certification for single-SKU regional distribution.
- Bluetooth:LE Audio and Auracast-enabled configurations serve dual-use scenarios in UAE gaming lounges where casual users toggle between tournament RF base stations and smartphone companion apps. Firmware synchronization with Android and iOS release schedules compresses vendor development cycles.
- USB-C:Digital audio interfaces with integrated DACs dominate Kenyan and Ethiopian PC gaming café procurement due to power delivery consolidation and reduced cable clutter.
- Analog:3.5mm TRRS connectors persist in North African mobile esports where PUBG Mobile and Free Fire tournaments require smartphone audio jack compatibility.
RF anchors competitive procurement. Bluetooth is climbing the fastest as hybrid-use venues proliferate across Gulf urban centers.
End User:
Customer type stratification reflects equipment certification tiers, with sponsor-driven standardization creating divergent margin profiles across professional and casual segments.
- Esports Athletes:Tournament-grade peripherals with SASO electromagnetic compatibility certification and team sponsorship alignment command premium positioning in Saudi Vision 2030-funded arenas. Riyadh and Jeddah training facilities mandate specific RF headset models through equipment partner contracts.
- Professional Gamers:Streaming disclosure requirements and affiliate link monetization drive equipment standardization among South African and UAE-based rosters, directing fan purchases through team channels rather than traditional retail.
- Streamers:Content creators in Dubai and Johannesburg prioritize noise-canceling variants with broadcast-quality microphone arrays for multi-platform output.
- Casual Gamers:Price-sensitive consumers across Egyptian and Moroccan markets favor entry-level wired configurations with basic stereo positioning.
Esports Athletes concentrate the highest per-unit margins. Casual Gamers deliver the volume base.
Distribution Channel:
Supply concentration patterns mirror retail infrastructure maturity, with formal channels dominating Gulf markets while informal networks persist in sub-Saharan Africa.
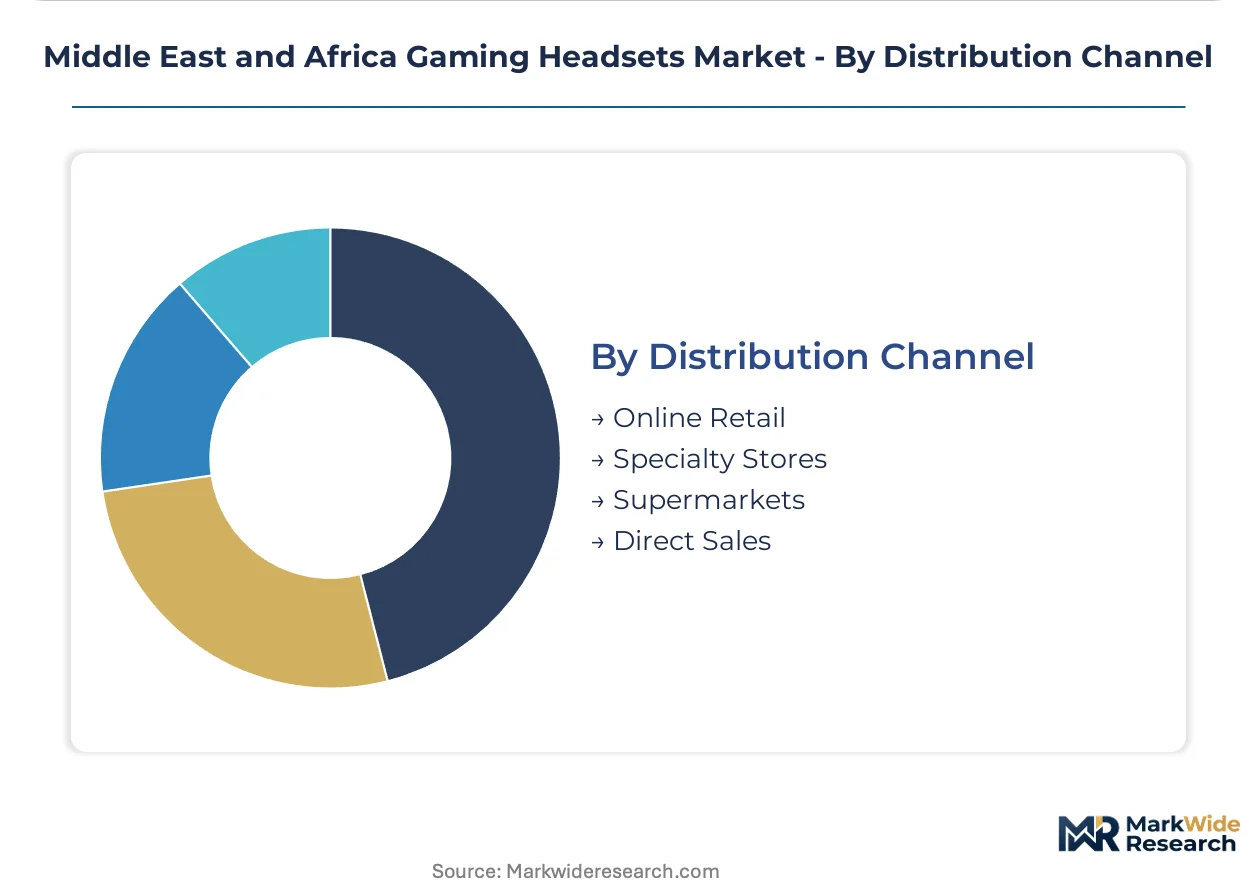
- Online Retail:Amazon.ae, Noon, and Takealot capture disproportionate share in UAE and South African metropolitan markets where esports team affiliate links and tournament sponsorship disclosures direct purchase behavior. Firmware-dependent wireless products require post-sale support infrastructure that pure-play e-commerce struggles to provide.
- Specialty Stores:Gaming-focused retailers in Riyadh's Boulevard and Dubai's Mall of the Emirates offer hands-on latency testing and certification verification for SASO-compliant tournament peripherals.
- Direct Sales:B2B procurement pipelines into Saudi government-funded esports venues and South African tournament organizers bypass retail markup for volume headset deployments.
- Supermarkets:Mass-market electronics sections in Carrefour and Lulu hypermarkets serve entry-level wired demand across North African price-sensitive segments.
Online Retail commands the established base. Direct Sales is expanding most quickly as venue-scale procurement accelerates under Saudi Vision 2030.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export gaming headsets through Dubai's Jebel Ali Free Zone into Saudi Arabia and South Africa, leveraging the UAE's duty-free warehousing to bypass direct shipment tariffs.
Saudi Arabia
Riyadh and Jeddah gaming hubs drive procurement volume under Vision 2030 arena construction. The Communications and Information Technology Commission allocates 2.4 GHz and 5 GHz spectrum for low-latency RF peripherals. King Abdullah Financial District venues mandate SASO-certified tournament-grade headsets through equipment partner contracts.
United Arab Emirates
Dubai Mall of the Emirates and Abu Dhabi Yas Island gaming lounges anchor premium wireless demand. MOHAP regulates electromagnetic compatibility standards for imported peripherals. Jebel Ali Free Zone distributors consolidate shipments for re-export across Gulf Cooperation Council markets.
South Africa
Johannesburg and Cape Town esports circuits generate professional-grade headset procurement. ICASA spectrum harmonization in 2.4 GHz and 5 GHz bands removes RF interference barriers. Sandton tournament venues deploy ICASA-certified RF base stations for competitive play.
Egypt
Cairo and Alexandria gaming cafés favor wired USB-C configurations due to cumulative import duties on Bluetooth chipsets. The National Telecom Regulatory Authority oversees wireless device certification. Nasr City electronics markets distribute entry-level peripherals through informal retail networks.
Nigeria
Lagos and Abuja mobile esports tournaments create demand for 3.5mm smartphone-compatible headsets. The Nigerian Communications Commission regulates wireless spectrum allocation. Computer Village Ikeja retailers source gray-market imports from Southeast Asian suppliers.
Middle East and Africa Gaming Headsets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented distribution networks. The vendor base stratifies into three tiers: esports sponsorship-driven brands, retail distribution anchors, and component-integrated manufacturers. Strategic moves concentrate on tournament partnership retainers and SASO certification pre-approval to secure Saudi venue procurement pipelines.
Within the esports sponsorship tier, Razer Inc and SteelSeries exemplify brand-visibility strategies through Middle Eastern tournament circuit presence. Corsair Gaming Inc occupies a position emphasizing ecosystem integration and firmware control differentiation. These three companies anchor the premium procurement segment that Saudi Vision 2030-funded venues favor through mandated equipment standards.
| Leading Market Players |
|---|
| Razer Inc |
| SteelSeries |
| Corsair Gaming Inc |
| Logitech International SA |
| Sony Interactive Entertainment Inc |
| HyperX |
| Turtle Beach Corporation |
| Cooler Master Technology Inc |
| ASTRO Gaming |
| Others |
Pricing and Supply Chain Analysis
SASO certification chokepoints determine both pricing tier spreads and supply chain shape across Middle Eastern distribution channels. Saudi Arabia's electromagnetic compatibility testing mandates filter uncertified manufacturers from premium procurement pipelines while concentrating certified volume through Jebel Ali Free Zone re-export hubs.
Pricing Analysis
RF-to-Bluetooth generational pricing gaps separate tournament-grade peripherals from casual-use alternatives across Saudi and UAE venues. Three-tier pricing structure across premium, standard, and economy levels reflects SASO certification status, wireless protocol latency specifications, and bundled firmware support. Cost compression in entry-tier wired configurations is intensifying because Egyptian and Moroccan import duties on lithium cells inflate wireless alternatives. Casual gamers in North African markets exhibit highest price sensitivity, while esports athletes in Riyadh venues demonstrate lowest sensitivity due to sponsor-mandated equipment standards.
Supply Chain Analysis
Export-control scrutiny on RF chipset technologies limits flows from US and Taiwanese semiconductor suppliers into Middle Eastern assembly operations. Chinese, Vietnamese, and Malaysian manufacturing hubs anchor final headset assembly, drawing from South Korean lithium cell suppliers and Japanese acoustic driver specialists. Single-source vulnerability concentrates in proprietary RF protocol licensing from Nordic Semiconductor and Texas Instruments. Distribution runs through Dubai's Jebel Ali Free Zone for duty-free consolidation before Saudi and South African retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning. SASO and ICASA certification requirements generate switching costs that protect incumbent vendor relationships with Saudi government-funded venues.
For Market Incumbents: Insulate Saudi venue procurement pipelines through preemptive SASO certification renewals and firmware localization investments ahead of 2.4 GHz band congestion rule changes. Deepen backward integration into RF chipset sourcing to reduce exposure to Nordic Semiconductor allocation constraints. Anchor exclusive equipment partner contracts with Riyadh and Jeddah arena operators to block challenger brand shelf placement. For New Entrants and Emerging Players: Build out Ethiopian and Kenyan gaming café networks where entry-level wired demand faces minimal wireless competition due to price sensitivity and sub-Saharan logistics fragmentation. Target Nairobi PC gaming venues with USB-C configurations bundled with local technical support partnerships. Pursue white-label manufacturing relationships with Dubai-based distributors to bypass direct SASO certification timelines. For Investors and Strategic Acquirers: The market sits at a venue-infrastructure buildout phase that favors certification-embedded peripheral vendors over pure-brand marketing plays. Long-term viability rests on regulatory relationship depth rather than transient esports sponsorship visibility. Monitor Gulf Cooperation Council spectrum harmonization negotiations as inflection indicator for single-approval cross-border distribution economics.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Pre-Approval Investment | Secures pipeline access to Saudi Vision 2030-funded esports venues before competitors complete testing cycles. |
| Arabic Firmware Localization | Reduces 4-6 month launch delays versus English-first markets and satisfies CITC interface requirements. |
| RF Base Station Tournament Deployment | Creates venue-level switching costs through proprietary ecosystem lock-in with Saudi professional circuits. |
| Jebel Ali Free Zone Distribution Consolidation | Enables duty-efficient re-export across GCC markets while minimizing direct shipment tariff exposure. |
| Esports Team Sponsorship Retainers | Displaces traditional retail marketing through streaming disclosure requirements that direct fan purchases. |
Research Methodology
A standing panel of esports venue procurement managers, gaming peripheral distributors, CITC regulatory affairs specialists, and ICASA certification consultants provided ongoing calibration throughout the analysis. Primary interviews with Riyadh arena operators, Dubai Mall of the Emirates retailers, and Johannesburg tournament organizers combined with secondary validation from SASO technical regulations, ICASA spectrum allocation notices, and hyperscaler cloud gaming infrastructure disclosures. Bottom-up headset shipment data from Kenyan and Nigerian retail channels triangulated against top-down gaming venue construction pipelines across the analysis window.
Scenario-bracketing anchored the analytical framework around low, base, and high cases for 5G infrastructure deployment pace and Gulf Cooperation Council spectrum harmonization timelines. Segmentation dimensions modeled include connectivity protocol, certification tier, end-user archetype, and regional retail infrastructure maturity. CAGRs derived from logistic diffusion curves fitted to wireless adoption patterns in Saudi professional circuits, cross-referenced with lithium cell import duty trajectories in North African markets.
Practitioners should monitor ICASA enforcement intensity and GCC unified RF certification negotiations for early signals of competitive access shifts. Forecasts reflect documented assumptions regarding Saudi arena construction schedules and Egyptian tariff stability. Material shifts in SASO electromagnetic compatibility testing protocols or sub-Saharan logistics consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Galgames Market
Gaming
Germany Gaming Headset Market
Gaming
MMORPG Gaming Market
Gaming
Shooter Game Market
Gaming
Global Tarot Cards Market
Gaming
Mobile Shooter Market
Gaming
India Gaming Market
Gaming
RPG Games Market
Gaming
LAMEA in-Game Advertising Market
Gaming
North America Casino Gambling Market
Gaming
Global Casino and Gaming Market
Gaming
Video Game Software Market
Gaming
Online Strategy Games Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
VR Gaming Accessories Market
Gaming
Europe Video Game Software Market