
 Virtual Influencer Market | 2026-2036
Virtual Influencer Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Influencer Market Analytics
Buyer concentration across brand marketing departments is rebalancing as mid-sized consumer goods firms join luxury houses in commissioning synthetic talent. Epic Games leverages its Unreal Engine rendering pipeline to anchor high-fidelity avatar production for enterprise clients. Soul Machines differentiates through emotionally responsive AI faces that sustain longer viewer engagement metrics. Superplastic dominates collectible merchandise tie-ins, extending its virtual characters into physical product drops with tight channel control.
A virtual influencer denotes a computer-generated persona rendered through real-time graphics engines or neural synthesis pipelines, typically operating at 60 frames per second for livestream deployment and designed to perform brand advocacy without human talent dependency. Fashion and gaming verticals currently lead monetization, with photorealistic models capturing premium sponsorship rates while 2D characters occupy lower-budget affiliate tiers across Southeast Asian mobile platforms. Social media distribution still commands the largest audience reach, though augmented reality integrations on messaging apps represent the fastest-growing engagement surface.
The US FTC requires clear synthetic media disclosure in sponsored content, while China's SAMR mandates watermarking for AI-generated commercial faces and South Korea's KFTC monitors virtual idol advertising claims under standard endorsement rules. The EU AI Act's transparency obligations for manipulative media will reshape how European-deployed avatars label themselves in brand collaborations. Stakeholders must track which jurisdiction's disclosure standard becomes the de facto global compliance floor.
Market Dynamics
Real-time neural rendering pipelines are compressing production timelines for photorealistic avatars, collapsing the cost barrier between 2D anime-style characters and cinematic-grade synthetic talent. This technology inflection is redistributing commissioning power from entertainment conglomerates toward mid-sized brand marketing departments.
Growth Catalysts
- SAMR watermarking mandates:China's synthetic media disclosure rules for commercial faces are legitimizing virtual influencers as a regulated advertising channel, accelerating enterprise adoption by risk-averse brand legal teams.
- Unreal Engine 5 nanite geometry:Epic Games' micro-polygon rendering stack enables film-quality facial capture at broadcast frame rates, collapsing the fidelity gap between pre-rendered campaign assets and livestreamed synthetic hosts.
- Seoul idol-industry infrastructure:South Korea's entertainment agencies already operate casting, training, and fan-management systems that translate directly to rendered persona operations, creating concentrated expertise clusters.
Market Restraints
- GPU compute cost volatility:Real-time ray-traced avatar rendering depends on NVIDIA H100 and AMD MI300X allocation, with cloud instance pricing fluctuating 40-60% based on semiconductor foundry output constraints.
- Deepfake detection arms race:Platform content moderation systems flag high-fidelity synthetic faces as manipulated media, triggering account suspensions that disrupt campaign continuity for unverified avatar operators.
- FTC disclosure friction:The US regulator's evolving synthetic media labeling requirements create interpretive uncertainty, forcing legal review cycles that extend campaign launch timelines by 3-4 weeks.
Strategic Opportunities
- EU AI Act transparency tailwinds:The regulation's manipulative media labeling obligations will standardize disclosure formats across France, Germany, and Italy, reducing jurisdictional compliance fragmentation for multi-market avatar deployments.
- AR messaging app surfaces:Snapchat and Instagram camera integrations represent underexploited distribution channels where synthetic characters can occupy persistent spatial anchors rather than ephemeral feed posts.
- Emotional AI convergence:Soul Machines' affective computing stack merging with neural synthesis pipelines enables real-time viewer sentiment response, opening premium subscription tiers for interactive synthetic companions.
Industry Challenges
- Performance capture talent scarcity:Motion actors capable of conveying micro-expression nuance for neural training datasets command rates exceeding traditional voiceover work, constraining avatar emotional range for budget-constrained productions.
- Cross-border IP licensing complexity:Synthetic faces trained on composite biometric data face unresolved personality rights claims across German and French jurisdictions, exposing campaigns to retroactive injunctive relief.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Influencer Market |
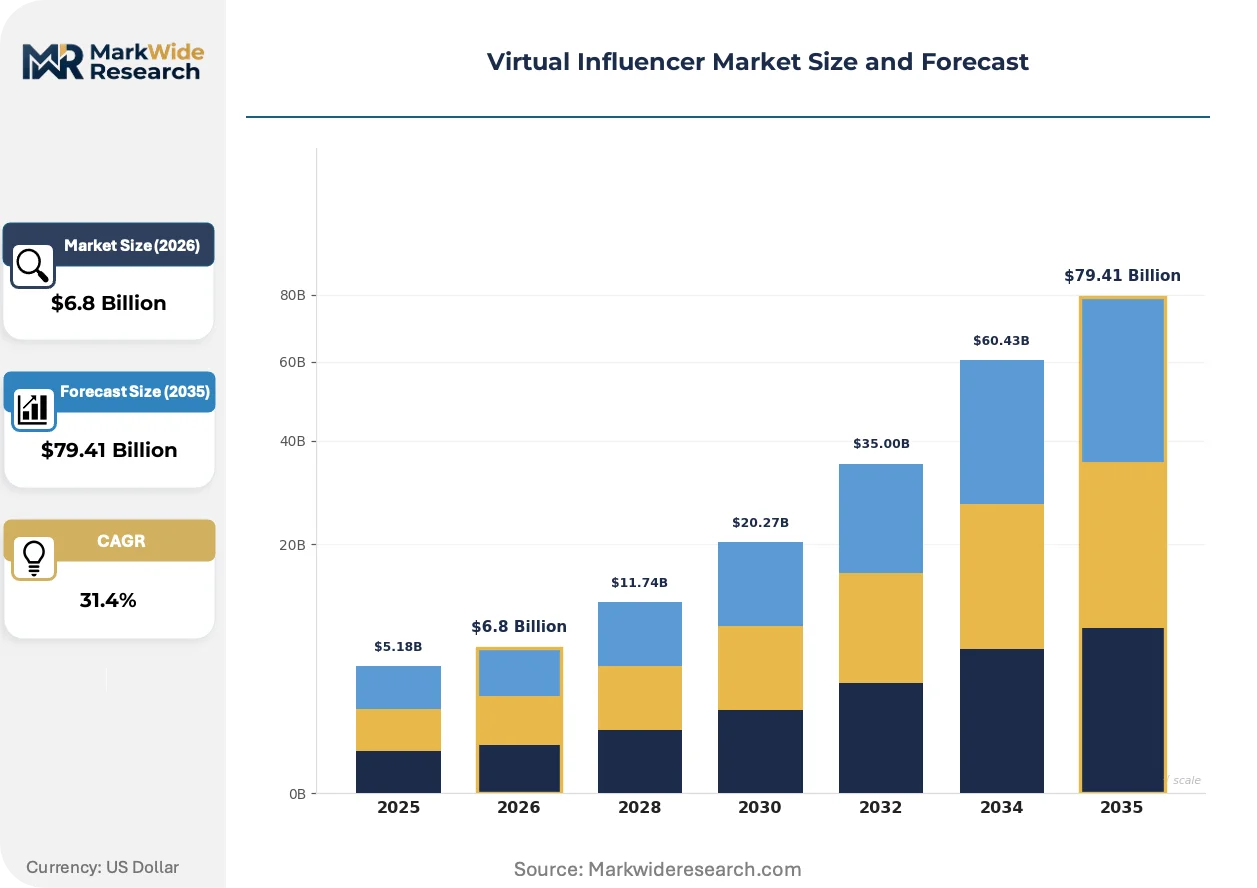
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $79.41 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: 3D Characters, 2D Characters, Animated Avatars, Photorealistic Models Industry Vertical: Fashion, Beauty, Gaming, Automotive Platform: Social Media, Gaming Platforms, Virtual Reality, Augmented Reality Monetization Strategy: Sponsored Content, Affiliate Marketing, Merchandise Sales, Brand Collaborations |
| Companies Covered | Epic Games, Inc., Soul Machines, Superplastic, Pinscreen Inc., NEON, Dapper Labs, Inc., UneeQ Limited, Didimo Inc., Spatial Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Influencer Market Evolving Landscape
Neural synthesis pipelines are fragmenting the production stack into specialized, interoperable components. This modularization is enabling new competitive entry points and compressing the traditional studio monopoly over high-fidelity avatar creation.
Generative adversarial networks for facial texture synthesis are modularizing the traditional 3D modeling pipeline. Mid-sized fashion brands now commission photorealistic skin and hair assets from distributed specialist shops rather than captive studio teams. This componentization is collapsing the minimum viable budget for cinematic-grade avatar launches from seven-figure to low six-figure investments.
The EU AI Act's transparency obligations for manipulative media are forcing disclosure standardization across member states. Brand legal departments must now embed synthetic origin labels into avatar content metadata rather than relying on platform-native tagging. French and German luxury houses are responding by building compliance-native avatar architectures where provenance verification is baked into render pipelines.
Brand procurement departments are unbundling talent representation from content production, treating synthetic influencers as licensable software assets rather than managed celebrity relationships. This contractual shift is displacing traditional talent agency retainers with usage-based API licensing models. South Korean entertainment conglomerates are most aggressively restructuring their commercial terms to capture this recurring-revenue transition.
Virtual Influencer Market Segmentation
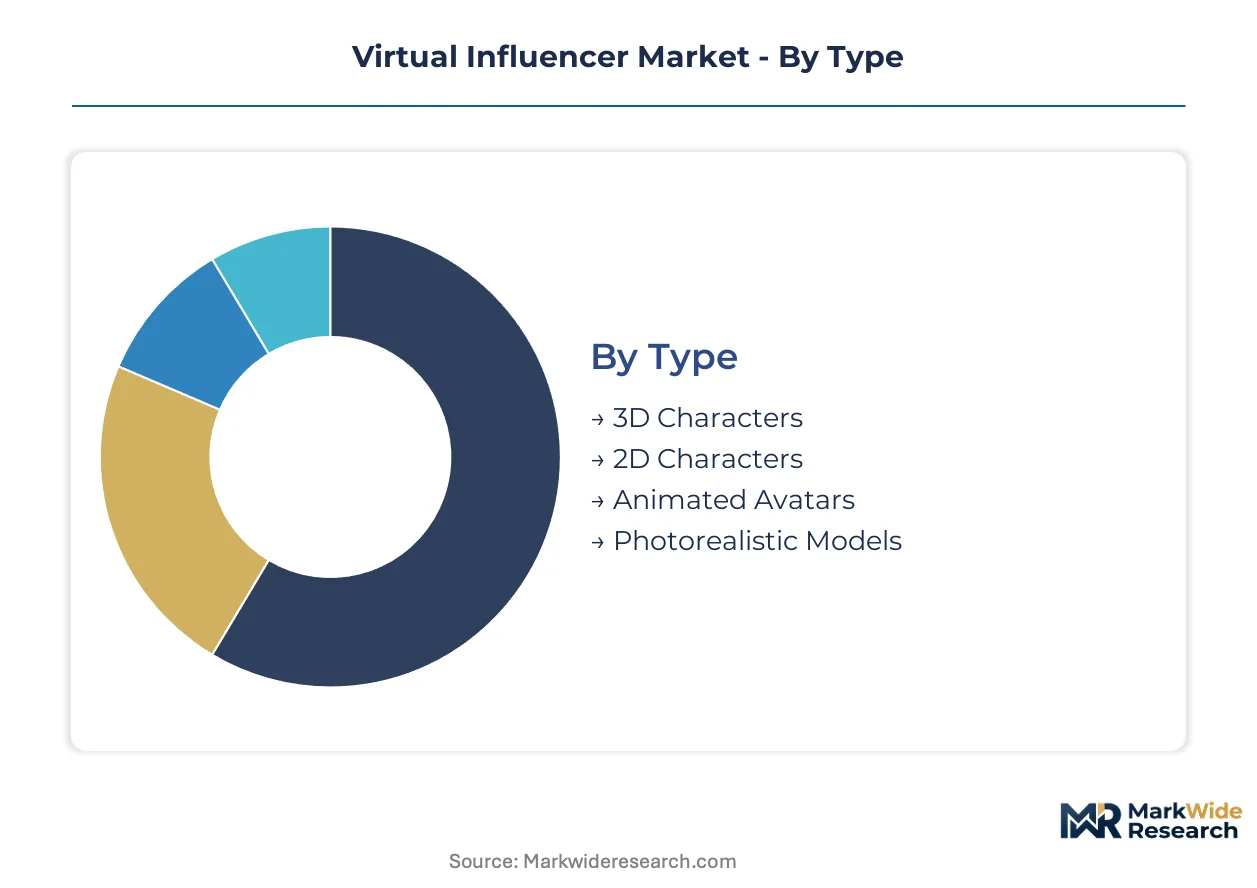
Segmentation in the virtual influencer market reveals divergent production economics and platform strategies across fidelity tiers. Brand procurement teams calibrate commissioning budgets against audience engagement depth, with photorealistic deployments commanding premium sponsorship rates while 2D anime-style characters saturate mobile-first Southeast Asian markets.
Type:
Volume concentrates in stylized character formats where rendering pipelines minimize GPU compute overhead, while premium deployment gravitates toward cinematic-grade synthetic talent requiring dedicated motion capture stages.
- Photorealistic Models:Neural synthesis pipelines generate skin microgeometry and subsurface scattering at broadcast frame rates. Luxury fashion houses in France and Italy commission these assets for runway campaigns where indistinguishability from human talent justifies seven-figure production budgets.
- 3D Characters:Real-time engines render stylized geometry optimized for livestream deployment. Gaming platform integrations in South Korea drive concentrated demand where 60 frames per second interaction sustains viewer retention metrics.
- 2D Characters:Vector-based animation dominates mobile-first Southeast Asian markets with minimal GPU requirements.
- Animated Avatars:Simplified rigging enables rapid content iteration for affiliate marketing tiers.
Mature deployment sits with 3D Characters. Newer deployment is concentrated in Photorealistic Models.
Industry Vertical:
Margin structures diverge sharply between physical product endorsement and digital-native engagement where synthetic talent requires no logistics coordination.
- Fashion:Photorealistic avatars execute seasonal campaign cycles without human talent scheduling constraints. European luxury houses deploy synthetic models across Paris, Milan, and London fashion weeks simultaneously, collapsing traditional casting timeline dependencies.
- Gaming:Native integration with Unreal Engine and Unity pipelines enables real-time character operation within playable environments. South Korean entertainment agencies structure entire idol rosters from rendered personas purpose-built for cross-platform IP extension.
- Beauty:Skincare and cosmetics brands leverage consistent facial geometry for product demonstration repeatability.
- Automotive:Synthetic hosts occupy virtual showroom environments where configurability exceeds human presenter adaptability.
Revenue concentration favors Fashion. Steepest expansion trajectory belongs to Gaming.
Platform:
Distribution economics favor ephemeral feed content against persistent spatial anchors where technical integration costs currently suppress adoption velocity.
- Social Media:Instagram, TikTok, and YouTube command dominant audience reach through algorithmic distribution. FTC disclosure mandates for sponsored synthetic content create compliance overhead that legal departments embed into campaign metadata rather than platform-native tagging.
- Augmented Reality:Snapchat and Instagram camera integrations enable persistent spatial anchoring where synthetic characters occupy physical environments through smartphone lenses. Technical implementation lags behind social feed ubiquity but shows strongest engagement depth metrics.
- Gaming Platforms:Native engine compatibility enables real-time avatar operation within interactive environments.
- Virtual Reality:Headset penetration constraints limit addressable audience despite immersive engagement potential.
Scale advantages accrue to Social Media. Technical differentiation concentrates in Augmented Reality.
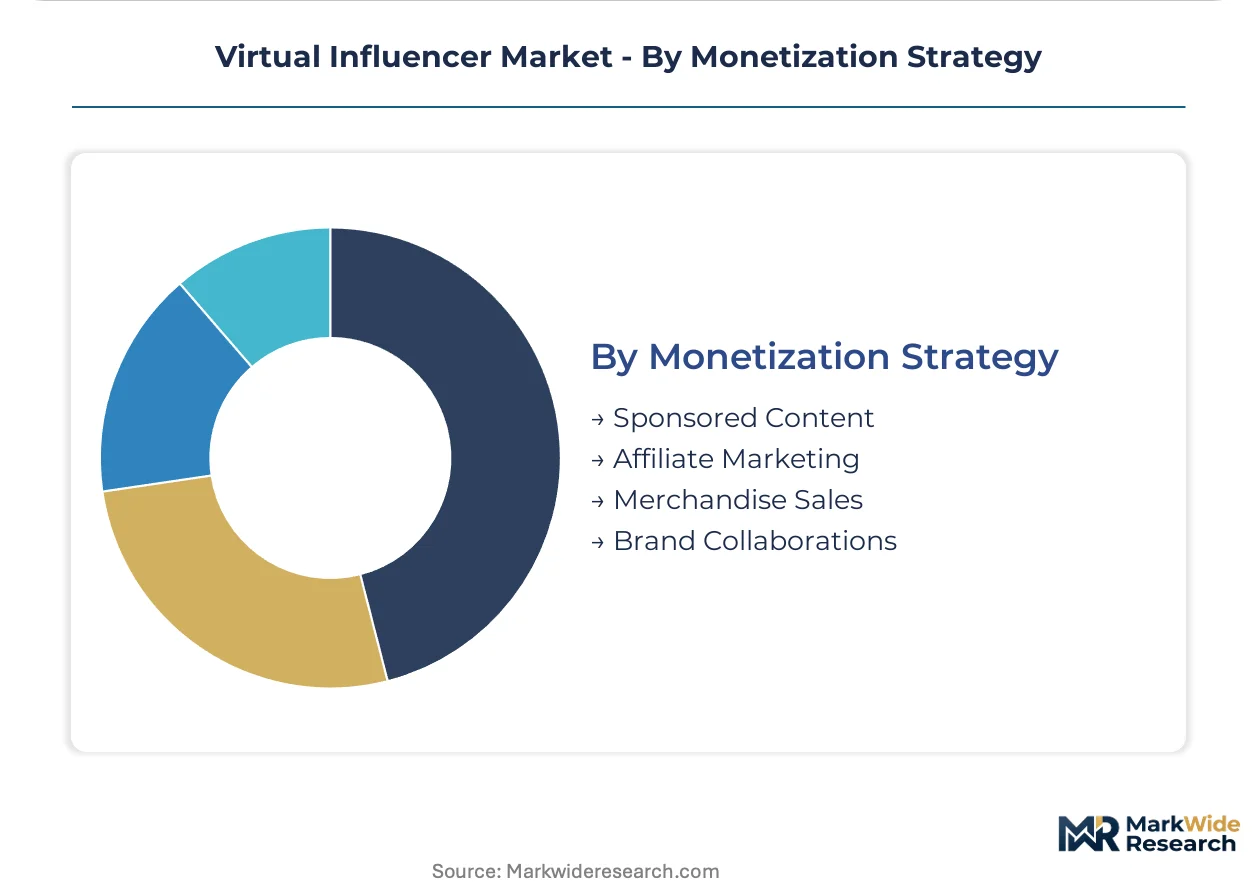
Monetization Strategy:
Contractual structures are displacing traditional talent agency retainers with usage-based licensing models that treat synthetic influencers as software assets.
- Brand Collaborations:Long-term ambassador contracts replicate celebrity endorsement frameworks with perpetual availability guarantees. South Korean entertainment conglomerates restructure commercial terms to capture recurring-revenue transitions from traditional idol management.
- Merchandise Sales:Synthetic characters extend into physical product drops with tight channel control, exemplified by collectible figurine and apparel tie-ins where IP ownership faces no personality rights fragmentation.
- Sponsored Content:Single-post campaigns dominate mid-market brand testing of synthetic talent efficacy.
- Affiliate Marketing:Performance-based commissions align low-budget avatar operations with conversion metrics.
Contract maturity centers on Brand Collaborations. Operational experimentation clusters in Merchandise Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brand procurement departments concentrate commissioning authority in South Korea, China, and France, where entertainment infrastructure and regulatory clarity accelerate synthetic talent deployment. National disclosure frameworks diverge sharply, fragmenting compliance architectures for cross-border campaigns.
South Korea
Seoul-based entertainment agencies operate casting and fan-management systems that translate directly to rendered persona operations. The KFTC monitors virtual idol advertising claims under standard endorsement rules, treating synthetic talent identically to human celebrities. Busan-Ulsan clusters host motion capture stages serving both gaming and fashion verticals.
China
Domestic platforms drive volume demand for 2D and 3D avatars across livestreaming commerce. SAMR mandates watermarking for AI-generated commercial faces, legitimizing virtual influencers as a regulated channel. Beijing and Shanghai concentrate avatar production studios serving consumer goods brands.
United States
Mid-sized consumer goods firms in Los Angeles and New York join luxury houses in commissioning photorealistic synthetic talent. The FTC requires clear synthetic media disclosure in sponsored content, creating interpretive uncertainty that extends campaign launch timelines. Epic Games anchors high-fidelity production through its Unreal Engine rendering pipeline.
France
Paris-based luxury fashion houses deploy synthetic models across Milan and London fashion weeks simultaneously. The EU AI Act's transparency obligations for manipulative media force disclosure standardization, prompting compliance-native avatar architectures. Île-de-France clusters integrate provenance verification into render pipelines.
Japan
Tokyo entertainment conglomerates structure idol rosters blending human and rendered performers for cross-platform IP extension. METI guidelines on synthetic media in advertising remain less prescriptive than Chinese or American frameworks. Kansai region studios specialize in emotionally responsive AI face development.
Virtual Influencer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue emotionally responsive AI and spatial computing integrations. The market fragments across rendering engine licensors, AI face specialists, and collectible merchandise operators. Three archetypes dominate: graphics engine providers, affective computing developers, and IP-centric character studios. Competitive moves center on technology licensing partnerships and recurring-revenue contract restructuring.
Within the graphics engine tier, Epic Games, Inc. anchors high-fidelity avatar production for enterprise clients. Soul Machines exemplifies the affective computing archetype through emotionally responsive AI faces. Superplastic occupies the IP-centric position, extending virtual characters into physical merchandise with tight channel control. These three represent divergent bets on where value accumulates in synthetic talent value chains.
| Leading Market Players |
|---|
| Epic Games, Inc. |
| Soul Machines |
| Superplastic |
| Pinscreen Inc. |
| NEON |
| Dapper Labs, Inc. |
| UneeQ Limited |
| Didimo Inc. |
| Spatial Systems, Inc. |
| Others |
Value Network & Pricing Analysis
GPU cloud instance pricing indices cascade through virtual influencer production economics, compressing margins for real-time ray-traced avatar operators while rewarding stylized 2D pipelines with minimal compute overhead. This input-cost volatility stratifies commissioning budgets across photorealistic, 3D, and 2D fidelity tiers.
Pricing Analysis
Volume concentrates in low-margin 2D character deployments across Southeast Asian mobile platforms, while premium margin capture sits with photorealistic synthetic talent commanding seven-figure production budgets from European luxury houses. Three-tier pricing structure across premium photorealistic, standard 3D real-time, and economy 2D vector tiers reflects GPU compute intensity and motion capture stage requirements. Cost compression in the mid-tier 3D segment is intensifying as Unreal Engine 5 nanite geometry democratizes broadcast-quality rendering. Brand marketing departments exhibit highest price sensitivity, whereas gaming platform operators prioritize frame-rate performance over per-asset cost.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA H100 and AMD MI300X allocation for real-time neural rendering, exposing production timelines to semiconductor foundry output constraints. Geographic supply concentration centers on the United States for graphics engine development, South Korea for motion capture infrastructure and idol-industry expertise, and China for 2D animation labor pools. Raw material dependencies encompass cloud GPU instances, performance capture talent for neural training datasets, and composite biometric data licensing for photorealistic facial synthesis. Tariff exposure on semiconductor equipment imports threatens cost predictability for avatar production studios. Distribution runs through direct enterprise licensing contracts with brand procurement departments rather than traditional talent agency representation models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual influencer market constitutes a vertical-integration race where control over rendering pipelines and emotional AI capabilities determines margin capture. Players are aggressively pursuing upstream control over motion capture talent and neural training datasets to defend pricing power.
For Market Incumbents: Extend proprietary rendering engine partnerships into exclusive motion capture stage networks, locking out mid-tier competitors from performance capture talent pools. Deepen in-house production of emotionally responsive AI face modules to offset Soul Machines' affective computing differentiation. The threat of modular GAN-based facial texture shops collapsing production budgets demands defensive certification investments in provenance-verified avatar architectures compliant with EU AI Act transparency mandates. For New Entrants and Emerging Players: Enter via AR messaging app integrations where Snapchat and Instagram camera surfaces remain underexploited relative to saturated social feed distribution. The most penetrable segment is mid-sized consumer goods firms in the United States seeking lower-risk synthetic talent testing grounds outside luxury house dominance. A go-to-market angle emphasizing FTC-compliant disclosure-native avatar metadata will accelerate legal department approvals. For Investors and Strategic Acquirers: Distressed-cycle entries favor affective computing specialists in New Zealand and Japan where emotional AI development clusters face funding pressure from GPU cost volatility. Long-term viability over the next decade hinges on recurring-revenue contract restructuring displacing traditional talent agency retainers. The signal to watch is South Korean entertainment conglomerate M&A activity indicating consolidation timing for rendered persona IP portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Rendering Pipeline Integration | Epic Games' Unreal Engine 5 nanite geometry enables film-quality facial capture at broadcast frame rates for enterprise clients. |
| Emotional AI Acquisition | Soul Machines' affective computing stack sustains longer viewer engagement metrics through real-time sentiment response. |
| Merchandise Channel Control | Superplastic's tight physical product drop coordination extends virtual characters into collectible figurine and apparel markets. |
| Compliance-Native Architecture | French and German luxury houses embed EU AI Act provenance verification directly into avatar render pipelines. |
| Motion Capture Stage Network | Busan-Ulsan clusters in South Korea concentrate expertise serving both gaming and fashion verticals simultaneously. |
Research Methodology
Independent corroboration across brand marketing executives, entertainment agency commercial directors, platform content policy leads, and regulatory affairs specialists underwrites the qualitative findings in this study. Primary interviews with avatar production studio heads and GPU cloud procurement officers combined with secondary validation from SAMR disclosure filings, FTC enforcement guidance documents, and EU AI Act legislative texts establish demand-side and supply-side triangulation. Bottom-up segmentation modeling and top-down market sizing approaches converge on volume and value estimates.
Rate-of-change decomposition across the analysis window separates technology adoption velocity from regulatory compliance lag effects in forecast construction. Segmentation dimensions modeled encompass avatar fidelity tier, industry vertical, distribution platform, and monetization strategy, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derive from installed base growth curves for rendering engine licenses and brand commissioning contract velocity. Forecast inputs include GPU cloud pricing volatility indices and entertainment agency restructuring announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR watermarking mandate enforcement intensity and deepfake detection platform algorithm shifts. Forecasts reflect assumptions regarding neural rendering pipeline cost compression trajectories and cross-border IP licensing resolution timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Photo Sharing Market