
 Argentina Satellite Imagery Services Market | 2026-2036
Argentina Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Satellite Imagery Services Market Insights
Multi-source procurement among Argentine agribusiness and energy operators is rebalancing toward hybrid domestic-foreign satellite constellations. Satellogic anchors commercial Earth observation capacity from Buenos Aires with a dedicated smallsat manufacturing base. Maxar Technologies competes through high-resolution archive depth and direct government relationships. INVAP S.E. sustains sovereign payload engineering for CONAE missions, reducing import dependency for critical infrastructure monitoring.
Argentina satellite imagery services encompass the acquisition, processing, and analytical exploitation of remotely sensed Earth observation data, typically spanning spatial resolutions from 30-meter multispectral to sub-meter panchromatic, delivered through cloud-based platforms or on-premise geospatial information systems. These services enable decision support across agriculture, environmental compliance, and extractive industries by transforming raw sensor data into classified land-cover maps, change-detection layers, and predictive terrain models. End-user segmentation reveals agriculture as the dominant demand pool, where optical systems and radar technology converge to solve cloud-cover limitations during critical growing-season windows. Technology segmentation shows hyperspectral imaging advancing fastest in mineral exploration and soil chemistry applications, while 3D mapping services command premium pricing from urban planning and infrastructure engineering clients.
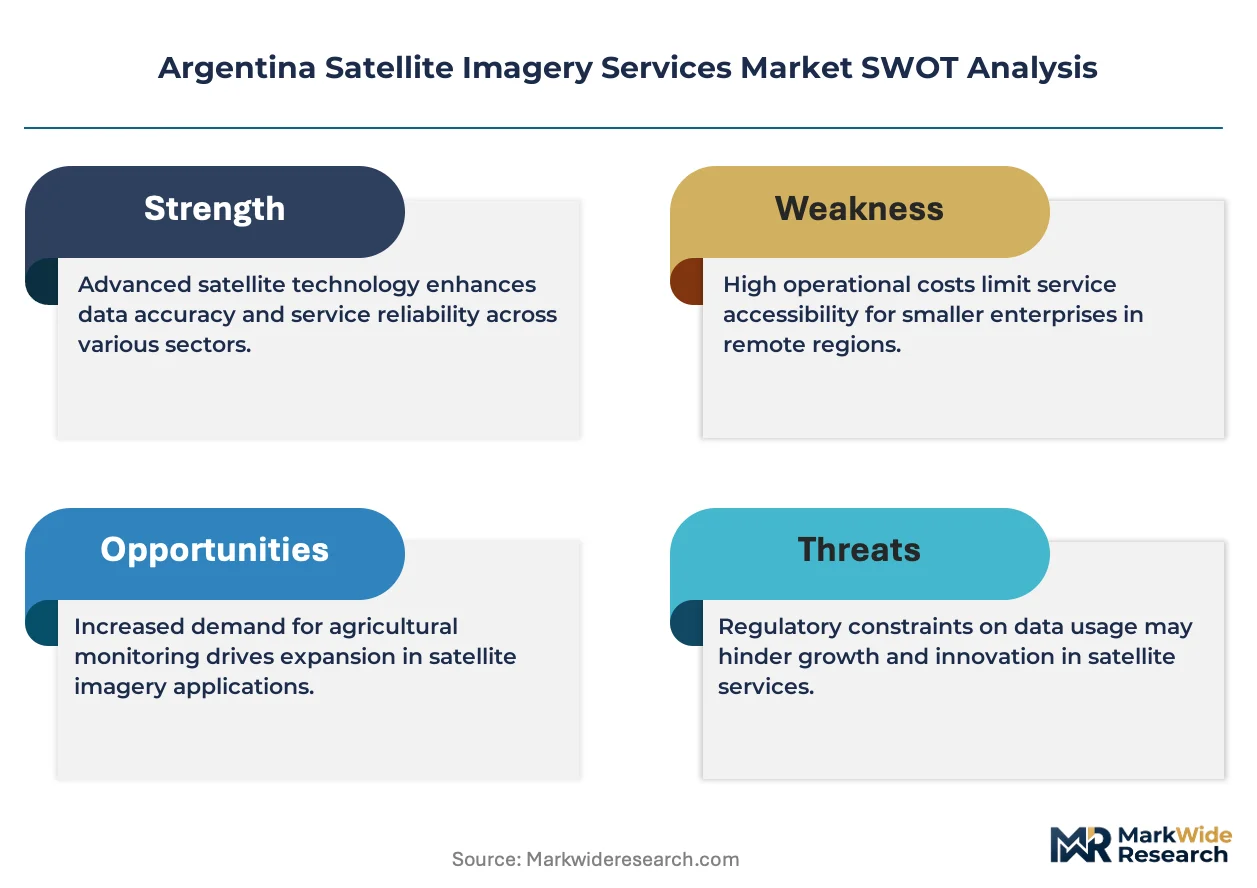
CONAE operates under Argentina's national space plan, coordinating orbital assets with regulatory oversight from the country's telecommunications and broadcasting authority for spectrum allocation and downlink licensing. The national geospatial data infrastructure law imposes public-sector data-sharing obligations that expand downstream analytics markets while restricting certain foreign-platform access for sensitive border and defense zones. Stakeholders must monitor forthcoming spectrum auction rules and sovereign cloud mandates that will determine whether domestic processing clusters or international platform partnerships capture the value chain's analytical layer.
Market Dynamics
Argentina's sovereign data mandates are restructuring procurement flows, forcing foreign platform operators to localize processing infrastructure while domestic manufacturers capture payload integration contracts for CONAE's expanding orbital constellation.
Growth Catalysts
- CONAE National Space Plan:Sovereign launch capacity and orbital asset expansion reduce dependency on foreign data streams for critical infrastructure monitoring.
- Precision Agriculture:Sub-meter resolution demand from Buenos Aires Province grain operators drives subscription growth for crop health analytics platforms.
- Cloud-Processing Localization:Domestic data center investments satisfy geospatial data infrastructure law requirements for sensitive border zone analytics.
Market Restraints
- Foreign Exchange Volatility:Dollar-denominated sensor procurement and launch service contracts expose operators to peso depreciation risk.
- Spectrum Licensing Bottlenecks:Telecommunications and broadcasting authority backlogs delay downlink authorization for commercial smallsat operators.
- Optical Cloud-Cover Dependency:Persistent cloud interference during Pampas growing seasons limits reliable optical acquisition windows.
Strategic Opportunities
- Synthetic Aperture Radar Convergence:All-weather imaging capability opens mineral exploration contracts in cloud-prone Andean zones.
- Córdoba Technology Cluster:Underpenetrated precision agriculture demand in secondary grain belts offers first-mover platform deployment.
- Hyperspectral Soil Chemistry:Emerging lithium brine and rare earth exploration applications command premium per-kilometer pricing.
Industry Challenges
- Geospatial Data Scientist Scarcity:Limited domestic training programs in remote sensing analytics constrain platform scaling for downstream value-added services.
- Legacy System Integration:Provincial agricultural agencies operate fragmented GIS databases that resist standardized API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Satellite Imagery Services Market |
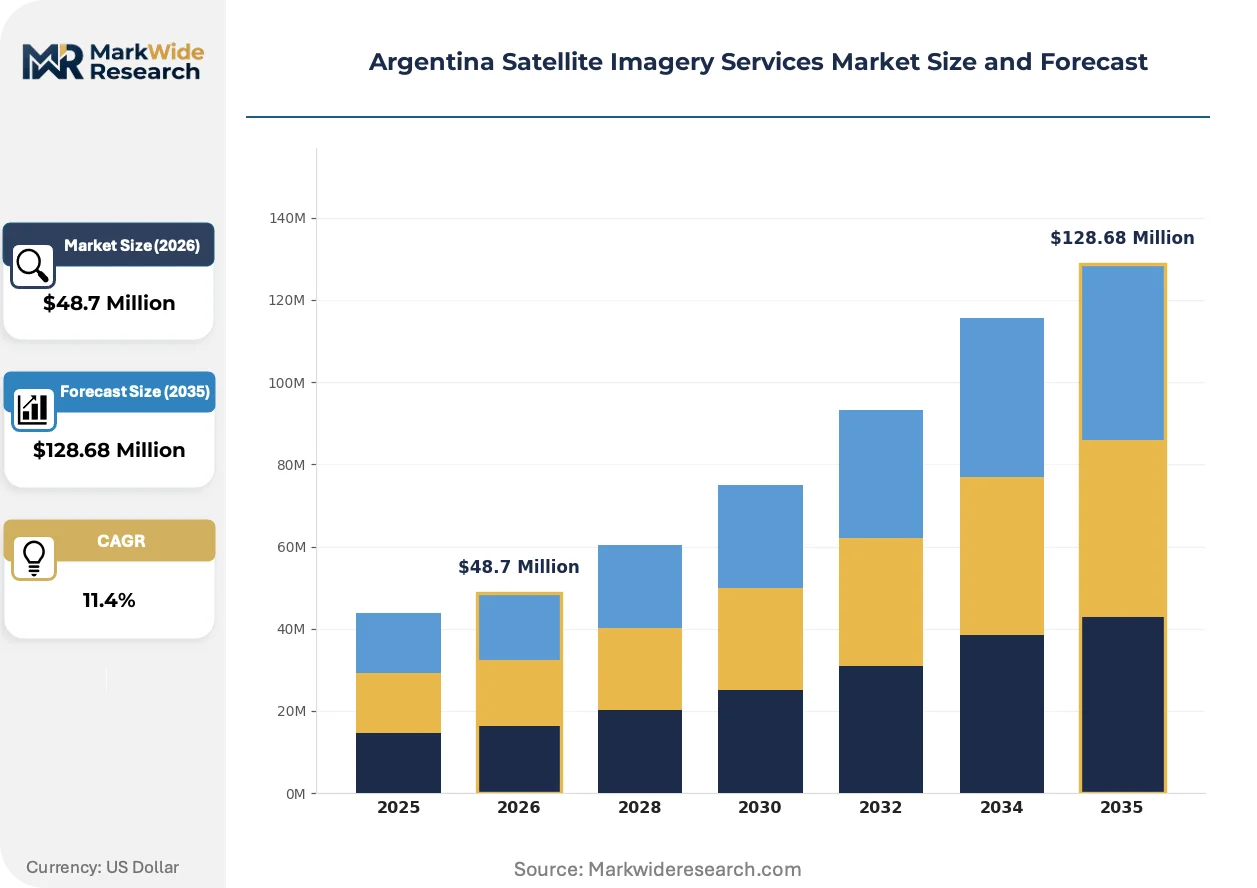
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analytics, Image Processing, Custom Solutions, Mapping Services End User: Agriculture, Environmental Monitoring, Urban Planning, Oil & Gas Application: Disaster Management, Land Use Planning, Forestry, Climate Research Technology: Optical Systems, Radar Technology, Hyperspectral Imaging, 3D Mapping |
| Companies Covered | Satellogic, CONAE (National Commission for Space Activities), Airbus, Maxar Technologies, Planet Labs, SI Imaging Services, ImageSat International, L3Harris Technologies, INVAP S.E., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Satellite Imagery Services Market Trends and Innovations
Sensor fusion architectures and sovereign processing mandates are compressing value chain margins for pure-play foreign operators while rewarding hybrid domestic-foreign platform partnerships with regulatory preference.
Smallsat synthetic aperture radar constellations is overtaking optical-only systems for agricultural monitoring contracts. Pampas grain cooperatives now specify all-weather acquisition guarantees in procurement tenders. This capability compression is eliminating seasonal revenue volatility for operators while raising capital requirements for radar payload manufacturing.
Argentina's geospatial data infrastructure law imposes public-sector sharing obligations that expand downstream analytics markets. Commercial platform operators must architect sovereign cloud instances to access defense and border zone contracts. Domestic processing clusters in Buenos Aires Province capture the highest-margin analytical layer under this framework.
Cooperative buying consortia among medium-scale agricultural operators are consolidating subscription purchasing power. Traditional direct-to-farmer platform sales face displacement from provincial grain elevator aggregators bundling imagery with input financing. This channel restructuring concentrates most visible in Santa Fe and Entre Ríos provinces where cooperative density exceeds national averages.
Argentina Satellite Imagery Services Market Segmentation
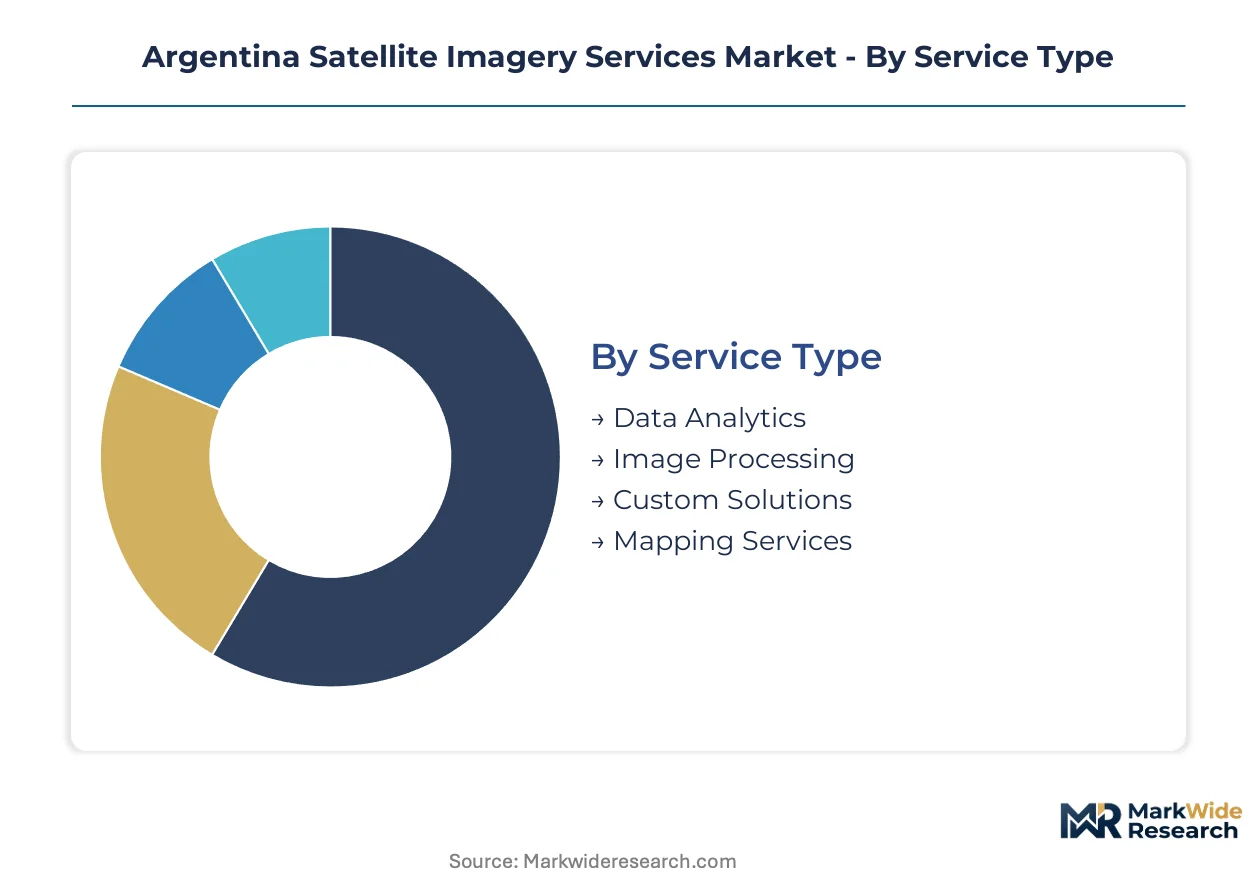
Argentina's satellite imagery market fragments across four functional dimensions that determine procurement patterns and margin capture. Service delivery models, end-user concentration, application workflows, and sensor technologies each create distinct competitive arenas where domestic platform operators and foreign providers vie for contract flow.
Service Type:
Supply concentration clusters around high-value analytical layers rather than raw data distribution, with domestic operators capturing sovereign processing mandates while foreign platforms retain archive depth advantages.
- Data Analytics:Transformation of raw sensor feeds into predictive crop models, mineral prospectivity indices, and infrastructure degradation forecasts. Buenos Aires Province grain cooperatives drive subscription volume for yield prediction algorithms that integrate soil chemistry with spectral signatures.
- Image Processing:Atmospheric correction, orthorectification, and pan-sharpening workflows that prepare raw acquisitions for downstream exploitation. CONAE's sovereign data infrastructure requirements favor domestic processing clusters for sensitive border zone contracts.
- Custom Solutions:Bespoke algorithm development for lithium brine exploration and rare earth prospectivity mapping in Andean salars.
- Mapping Services:Large-scale topographic and cadastral deliverables for provincial land registry modernization programs.
Data Analytics absorbs the bulk of installed capacity; Custom Solutions is expanding most quickly.
End User:
Cost tier stratification separates commodity subscription buyers from premium contract purchasers, with agricultural cooperatives anchoring volume and extractive operators commanding per-kilometer premiums.
- Agriculture:Precision agriculture operators across the Pampas grain belt purchase sub-meter resolution coverage for crop health monitoring and input optimization. Cooperative buying consortia in Santa Fe and Entre Ríos provinces consolidate subscription purchasing power.
- Oil & Gas:Pipeline corridor monitoring and exploration site screening in Neuquén Basin shale plays. All-weather SAR acquisition guarantees command premium pricing from operators facing cloud-cover constraints.
- Environmental Monitoring:CONAE-mandated deforestation tracking and wetland conservation compliance for provincial environmental agencies.
- Urban Planning:Municipal governments in Córdoba and Rosario deploy 3D mapping for infrastructure engineering and flood risk assessment.
Agriculture captures the dominant revenue share; Oil & Gas delivers the steepest margin expansion.
Application:
Volume concentration aligns with sovereign funding priorities and climate adaptation mandates, with disaster response workflows driving episodic procurement spikes.
- Disaster Management:Flood extent mapping and wildfire perimeter tracking for national emergency response coordination. CONAE orbital assets provide rapid-tasking capacity during critical event windows.
- Land Use Planning:Agricultural frontier expansion monitoring and urban growth boundary enforcement for provincial planning departments.
- Forestry:Plantation inventory and illegal logging detection in Misiones Province subtropical forests.
- Climate Research:Glacier mass balance tracking and precipitation pattern analysis for national meteorological services.
Land Use Planning sustains the most consistent contract flow; Disaster Management shows the highest episodic revenue volatility.
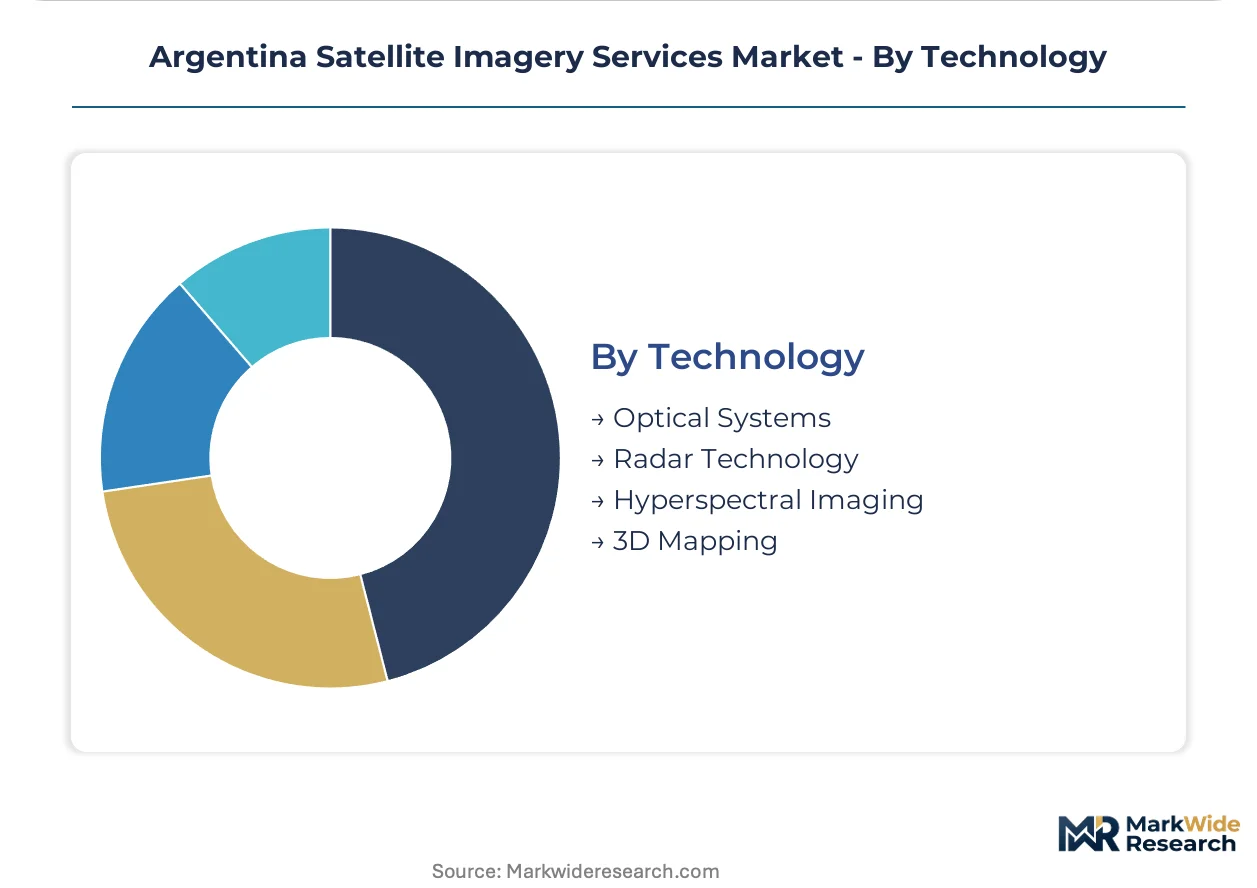
Technology:
Margin distribution favors all-weather and high-dimensional sensing modalities over conventional optical platforms, with technology selection driven by geographic cloud-cover patterns and application precision requirements.
- Radar Technology:Synthetic Aperture Radar systems penetrate cloud cover and darkness to deliver reliable acquisition in Andean zones and during Pampas growing seasons. Mineral exploration contracts in lithium-rich salars specify SAR guarantees.
- Hyperspectral Imaging:Narrow-band spectral sampling enables soil chemistry quantification and mineral species identification. Rare earth and lithium brine exploration applications command premium per-kilometer pricing.
- Optical Systems:Panchromatic and multispectral platforms dominate agricultural monitoring where cloud-free windows permit reliable scheduling.
- 3D Mapping:Stereo photogrammetry and interferometric SAR generate digital elevation models for infrastructure engineering and hydrological modeling.
Optical Systems retain the largest installed base; Hyperspectral Imaging is climbing the fastest on exploration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pampas grain belt anchors Argentina's satellite imagery demand, with sub-meter resolution procurement concentrated where soy and wheat production density meets precision agriculture adoption.
Buenos Aires Province
Grain cooperatives in the northwest Pampas drive subscription volume for crop health analytics platforms. The provincial agricultural agency mandates standardized API connectivity for federal subsidy eligibility. The Bahía Blanca corridor hosts domestic processing clusters serving sovereign cloud requirements.
Córdoba Province
Secondary grain belt operators in the central sierras underpenetrate precision agriculture platforms relative to Pampas density. CONAE orbital asset tasking prioritizes this zone for sovereign data infrastructure compliance. The Córdoba technology cluster attracts first-mover SAR constellation deployment for all-weather monitoring.
Santa Fe Province
Cooperative buying consortia consolidate subscription purchasing power among medium-scale operators. The national geospatial data infrastructure law expands downstream analytics markets through public-sector sharing obligations. The Rosario agro-industrial hub channels bundled imagery with input financing.
Entre Ríos Province
Wetland conservation compliance and rice paddy monitoring create dual-use demand for environmental and agricultural applications. Provincial environmental agencies contract deforestation tracking under CONAE-mandated programs. The Paraná River corridor concentrates infrastructure engineering demand for 3D mapping services.
Neuquén Basin
Shale play operators in the Vaca Muerta formation specify all-weather SAR acquisition guarantees for pipeline corridor monitoring. The national space plan's sovereign launch capacity reduces dependency on foreign data streams for critical energy infrastructure. Domestic payload integration contracts flow to INVAP S.E. for orbital asset support.
Argentina Satellite Imagery Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as foreign platform operators localize processing infrastructure to satisfy sovereign data mandates. The vendor base splits between domestic manufacturers with CONAE relationships and international providers with archive depth advantages. Three archetypes occupy distinct positions: sovereign-anchored domestic builders, high-resolution foreign incumbents, and smallsat constellation specialists. Technology licensing and geographic expansion represent the prevailing competitive vectors as operators seek regulatory preference through hybrid partnership structures.
Within the sovereign-anchored tier, Satellogic and INVAP S.E. occupy positions tied to national space policy execution. Satellogic exemplifies the smallsat manufacturing archetype with its Buenos Aires-based production base. INVAP S.E. represents the payload engineering specialist archetype serving CONAE mission requirements. Among foreign providers, Maxar Technologies anchors the high-resolution archive segment competing through direct government relationships.
| Leading Market Players |
|---|
| Satellogic |
| CONAE (National Commission for Space Activities) |
| Airbus |
| Maxar Technologies |
| Planet Labs |
| SI Imaging Services |
| ImageSat International |
| L3Harris Technologies |
| INVAP S.E. |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed manufacturers anchored by CONAE procurement mandates and Satellogic's Buenos Aires production base impose pricing discipline through captive domestic capacity, while foreign platform operators absorb localization costs to retain defense and border zone contract access.
Pricing Analysis
Warranty and service bundling separates premium SAR constellation operators from unbundled optical data resellers. Three-tier pricing structure across premium, standard, and economy levels stratifies by resolution grade and all-weather acquisition guarantees. Pricing pressure stems from cooperative buying consortia consolidating subscription purchasing power among Pampas grain cooperatives. Small-scale agricultural operators in secondary grain belts exhibit highest price sensitivity, while lithium exploration contractors in Andean salars accept premium per-kilometer hyperspectral pricing.
Supply Chain Analysis
Argentina's geospatial data infrastructure law and sovereign cloud mandates reshape sourcing toward domestic payload integration and Buenos Aires Province processing clusters. Sensor manufacturing draws from the United States, France, and China for critical optical and radar components. Supply chain risk centers on dollar-denominated procurement exposure under peso volatility. Distribution runs through provincial grain elevator aggregators bundling imagery with input financing in Santa Fe and Entre Ríos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Argentina satellite imagery market sits in a capability-transition phase where synthetic aperture radar constellations displace optical-only platforms for agricultural monitoring contracts.
For Market Incumbents: Extend sovereign processing infrastructure to capture defense and border zone contracts under geospatial data infrastructure law requirements. Deepen CONAE partnership structures to secure orbital asset tasking priority. Counter emerging hyperspectral specialists by integrating soil chemistry analytics into existing crop health platforms. For New Entrants and Emerging Players: Enter via Córdoba Province's underpenetrated precision agriculture segment where cooperative density lags Pampas benchmarks. Target medium-scale grain operators outside Buenos Aires Province core markets. Deploy go-to-market partnerships with provincial agricultural agencies mandating standardized API connectivity for subsidy eligibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic payload engineering specialists with CONAE mission heritage in Buenos Aires technology corridors. Long-term viability hinges on sovereign data mandate durability and lithium exploration demand expansion. Monitor spectrum auction rulemaking as inflection signal for domestic versus international platform value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Deployment | Domestic processing clusters in Buenos Aires Province satisfy CONAE data localization requirements for sensitive contracts. |
| SAR Constellation Manufacturing Scale-Up | All-weather acquisition guarantees command premium pricing from Pampas grain cooperatives facing cloud-cover constraints. |
| Hyperspectral Payload Integration Partnership | Soil chemistry quantification capabilities capture lithium brine exploration contracts in Andean salars. |
| Cooperative Buying Consortium Channel Development | Provincial grain elevator aggregators in Santa Fe consolidate subscription purchasing power beyond direct-to-farmer sales. |
| Spectrum Licensing Pre-Positioning | Early telecommunications and broadcasting authority engagement secures downlink authorization for commercial smallsat operators. |
Research Methodology
CONAE mission documentation, Argentina's national geospatial data infrastructure law filings, and provincial agricultural agency procurement records formed the secondary backbone for supply-side validation. Primary interviews with precision agriculture platform engineers, CONAE payload integration specialists, grain cooperative procurement managers, and lithium exploration geophysicists informed demand-side calibration. Bottom-up and top-down triangulation cross-validated segment-level assumptions against sovereign budget allocations and foreign trade data.
Bottom-up modeling anchored volume projections to individual provincial agricultural agency subscription patterns and extractive industry contract flows. Top-down constraints incorporated national space plan expenditure frameworks and spectrum licensing pipeline visibility. Segmentation dimensions spanned service delivery model, end-user concentration, application workflow, and sensor technology modality. CAGRs derived from fitted growth curves applied to disclosed CONAE orbital asset expansion timelines and cooperative buying consortium formation rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under peso depreciation acceleration or telecommunications authority spectrum auction delays. Projections reflect assumptions around sovereign data mandate enforcement continuity and lithium exploration permit issuance velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Small Satellite Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Global Enterprise VSAT System Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Germany Satellite Communications Market
Satellite
Satellite Communication Subsystem Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
India Satellite Communication Market
Satellite
UAE Satellite Communication Market
Satellite
Satellite Communication System Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Europe Satellite IoT Market