
 North America Automotive Lubricants Market | 2026-2036
North America Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Lubricants Market Analytics
Aftermarket service revenue is reshaping margin distribution across the North America automotive lubricants value chain. ExxonMobil Corporation leverages its integrated refining base to secure feedstock cost advantages across the region. Valvoline Inc. specializes in quick-lube channel control, sustaining high-margin recurring revenue streams. Shell plc anchors its position through backward integration into Group III+ base oil production.
Automotive lubricants are formulated blends of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with SAE viscosity grades and API service categories defining operational compatibility. Engine oil dominates product type value pools due to high consumption frequency and OEM specification complexity, while synthetic transmission fluid is expanding fastest as automakers adopt multi-speed automatic and dual-clutch architectures. Among end users, fleet operators are consolidating procurement through maintenance service providers, compressing aftermarket retailer margins in commercial vehicle segments.
The U.S. EPA and NHTSA coordinate fuel economy and emissions rules that directly determine engine oil viscosity trends and drain interval requirements. California's Air Resources Board enforces supplemental standards that frequently preempt federal timelines, forcing lubricant formulators to qualify products earlier for that state's vehicle population. Stakeholders must monitor how electrification shifts thermal management fluid demand versus traditional powertrain lubricant volumes.
Market Dynamics
Fleet operators across the United States and Canada are consolidating procurement through maintenance service providers, compressing aftermarket retailer margins and forcing lubricant suppliers to restructure channel economics around volume contracts rather than individual transactions.
Growth Catalysts
- U.S. EPA Emissions Standards:Tightened fuel economy rules are forcing reformulation of engine oils toward lower viscosity grades, creating mandatory product refresh cycles across the installed vehicle base.
- Synthetic Lubricant Chemistry:Advanced Group III+ and PAO base stocks are extending drain intervals, allowing fleet operators to reduce maintenance downtime and total cost of ownership.
- Great Lakes Manufacturing Corridor:Dense automotive production clusters in Michigan, Ohio, and Ontario sustain concentrated demand for OEM-fill and service-fill lubricants.
Market Restraints
- API Certification Costs:Extended engine test protocols and licensing fees for new service categories create fixed cost barriers for smaller formulators.
- Base Oil Supply Concentration:Gulf Coast refinery complexes control the majority of North American Group II/III capacity, exposing buyers to hurricane-related disruption risk.
- Electric Powertrain Substitution:Battery electric vehicles eliminate engine oil demand entirely, reducing addressable market volume in passenger car segments.
Strategic Opportunities
- Canadian Heavy-Duty Fleet Expansion:Cross-border trucking corridors and mining operations in Alberta and British Columbia present underpenetrated demand for extended-drain commercial lubricants.
- California CARB Preemption:The state's accelerated emissions timelines force early product qualification, creating first-mover advantage for formulators meeting supplemental standards.
- Quick-Lube Channel Integration:Direct relationships with high-throughput service networks enable captive lubricant placement and recurring revenue streams.
Industry Challenges
- Formulation Chemist Shortage:Specialized expertise in friction modifier and antioxidant blending is concentrating at major suppliers, constraining mid-tier R&D capacity.
- Legacy ERP Integration:Fleet management software systems require API connectivity for automated lubricant reordering, forcing distributors into expensive platform upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Lubricants Market |
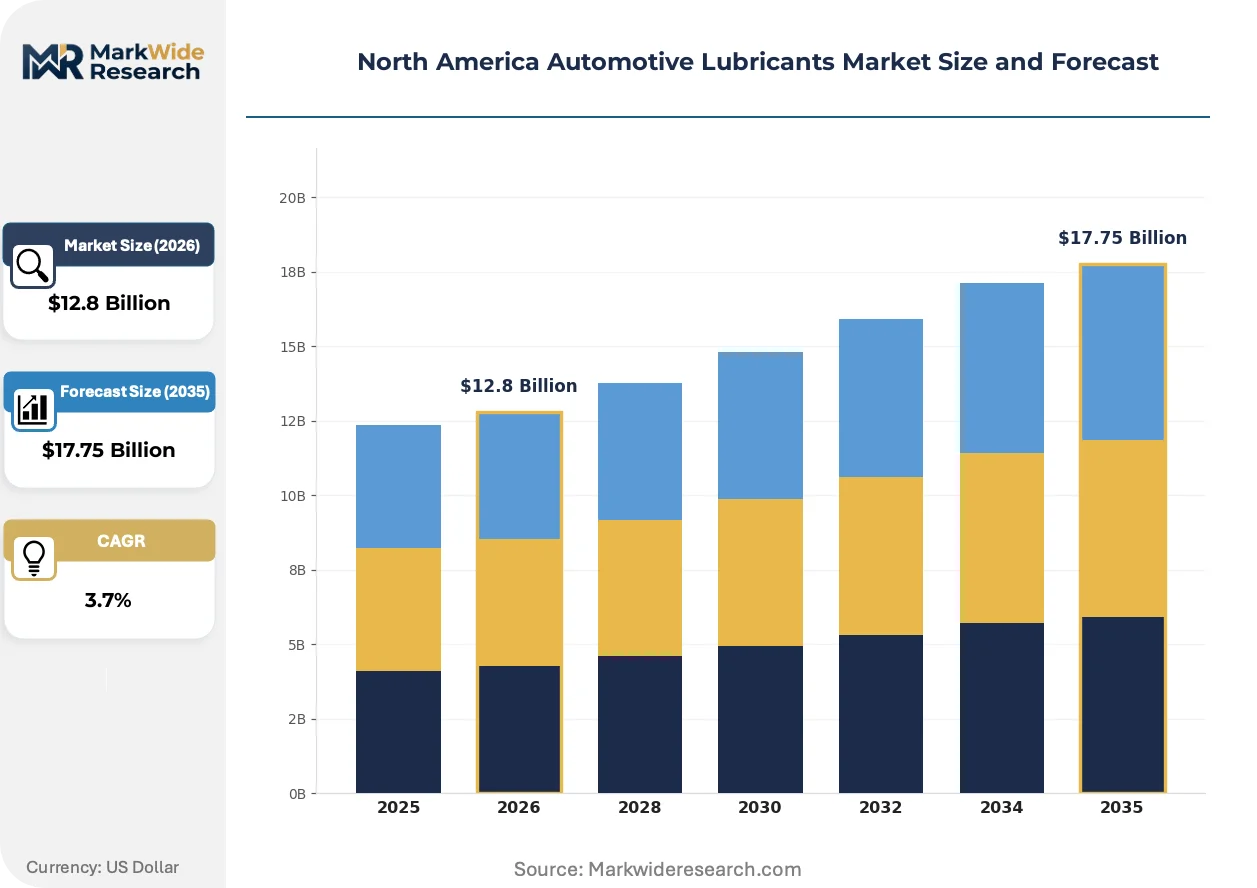
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.75 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles End User: Automotive OEMs, Aftermarket Retailers, Fleet Operators, Maintenance Service Providers Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Direct Sales |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell plc, Valvoline Inc., BP plc, Phillips 66, TotalEnergies SE, Castrol Limited, Petro-Canada Lubricants, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Lubricants Market Evolving Landscape
Automotive lubricant technology is converging with powertrain electrification and digital fleet management, creating new product categories while compressing traditional volume pools. Formulators must now engineer for thermal management and electrical compatibility alongside friction reduction.
Advanced thermal management fluids are hybridizing the functional boundaries between engine coolants and powertrain lubricants. Electric vehicle manufacturers are adopting these dielectric formulations for battery pack and inverter cooling. Tier-1 suppliers are compressing their fluid supplier base to vendors capable of dual-chemistry certification.
The U.S. EPA and NHTSA coordinated rulemaking on fuel economy standards is accelerating SAE 0W-16 and 0W-8 viscosity grade adoption. Lubricant formulators must revalidate additive packages for thinner oil films and higher thermal stress. Passenger car motor oil certifications are shifting faster than historical API service category cycles.
Fleet procurement departments are consolidating spend through maintenance service providers rather than purchasing lubricants directly. Quick-lube chains and mobile service operators are displacing traditional jobber distribution in commercial vehicle segments. This concentration is most visible in long-haul trucking corridors linking Texas, Illinois, and California distribution hubs.
North America Automotive Lubricants Market Segmentation
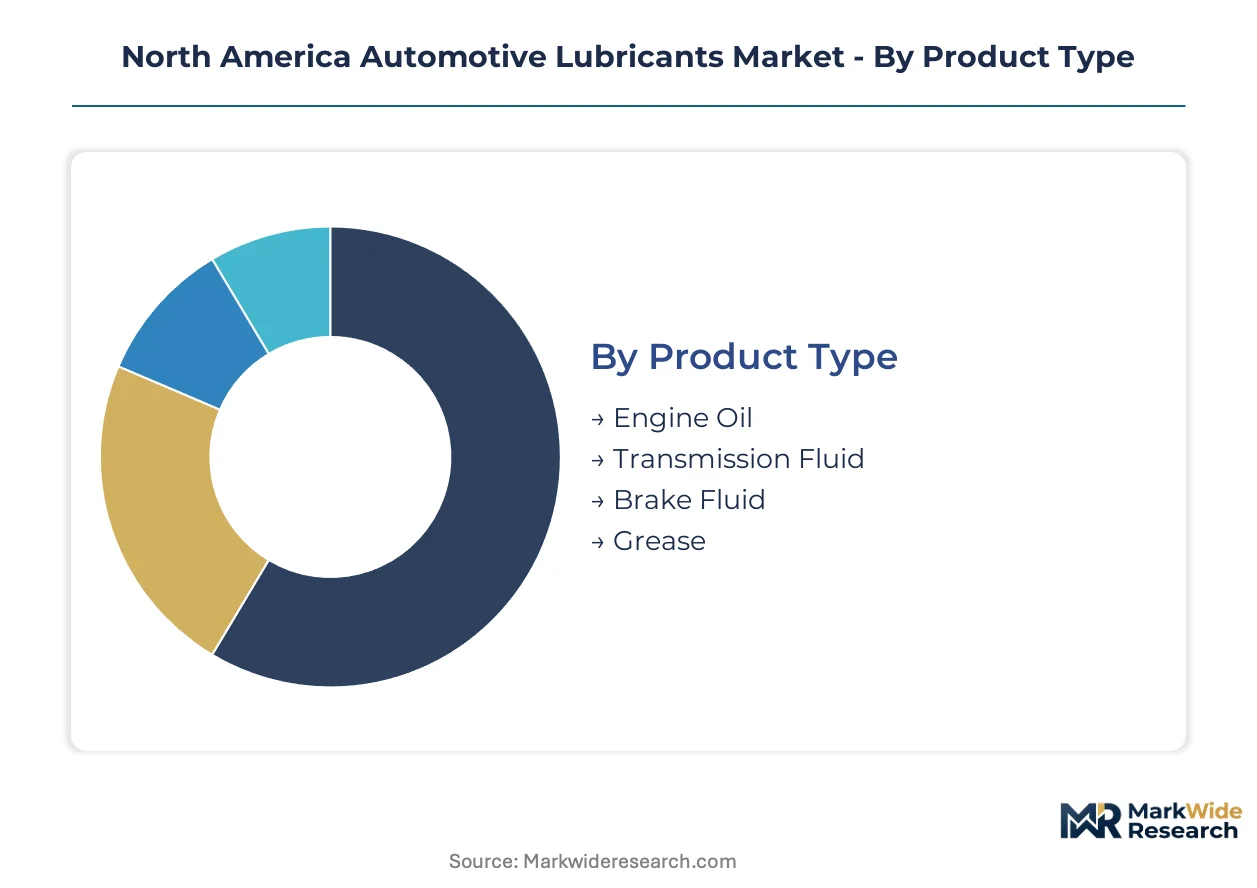
Segmentation in the North America automotive lubricants market reveals how after-sales service intensity varies dramatically across product categories and customer types. Understanding these patterns allows suppliers to align formulation investments with channel economics and drain-interval economics.
Product Type:
After-sales service intensity peaks with products requiring frequent monitoring and replacement, creating divergent margin structures across the lubricant portfolio.
- Engine Oil:Formulated from Group II, III, or synthetic base stocks with detergent-dispersant and anti-wear additive packages meeting API SP or ILSAC GF-6 specifications. Demand concentrates in the U.S. Great Lakes corridor where Michigan and Ohio automotive production clusters sustain high OEM-fill and service-fill volumes, though EPA-mandated lower viscosity grades are shortening formulation lifecycles.
- Transmission Fluid:Synthetic ATF and dual-clutch formulations engineered for multi-speed automatic architectures with friction stability requirements. Fleet operators in long-haul trucking corridors across Texas, Illinois, and California are consolidating procurement through maintenance service providers, compressing traditional jobber margins while extending drain intervals.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 3, DOT 4, or DOT 5.1 specifications for corrosion protection and high-temperature stability.
- Grease:Thickened lubricants combining base oil with lithium, calcium, or polyurea soap structures for chassis and bearing applications in off-road equipment.
Engine Oil holds the largest share; momentum sits with Transmission Fluid.
Application:
Volume scale and specification complexity diverge sharply between light-duty consumer segments and commercial duty cycles.
- Passenger Vehicles:Light-duty automobiles and SUVs requiring SAE 0W-20, 5W-30, and emerging 0W-16 viscosity grades under EPA fuel economy mandates. California CARB's accelerated emissions timelines are forcing earlier product qualification for this vehicle population than federal schedules require.
- Commercial Vehicles:Class 3-6 trucks and vans operating on regional delivery cycles with moderate load factors. Maintenance service providers are displacing direct fleet procurement, restructuring channel economics toward volume contracts.
- Heavy-Duty Trucks:Class 7-8 long-haul tractors with extended drain interval requirements driving synthetic and Group III+ adoption. Cross-border trucking corridors linking U.S. distribution hubs to Canadian freight networks present concentrated demand for high-performance formulations.
- Off-Road Vehicles:Construction, agriculture, and mining equipment operating in severe contamination and temperature environments across Alberta oil sands and British Columbia mining districts.
Passenger Vehicles generates the highest absolute volume; Heavy-Duty Trucks delivers the steepest expansion trajectory in per-unit value.
End User:
Procurement consolidation is reshaping which intermediaries capture margin between formulator and vehicle.
- Automotive OEMs:Vehicle manufacturers specifying factory-fill lubricants for new production, with qualification protocols tied to powertrain warranty coverage.
- Aftermarket Retailers:Auto parts chains and independent jobbers serving DIY consumers and small independent repair shops.
- Fleet Operators:Commercial vehicle owners managing total cost of ownership through extended drain intervals and bulk purchasing. These stakeholders are consolidating spend through maintenance service providers rather than direct lubricant acquisition.
- Maintenance Service Providers:Quick-lube chains and mobile service operators capturing fleet procurement consolidation. Direct relationships with high-throughput networks enable captive lubricant placement and recurring revenue streams for suppliers.
Fleet Operators historically dominated commercial volume; Maintenance Service Providers are gaining share fastest through procurement consolidation.
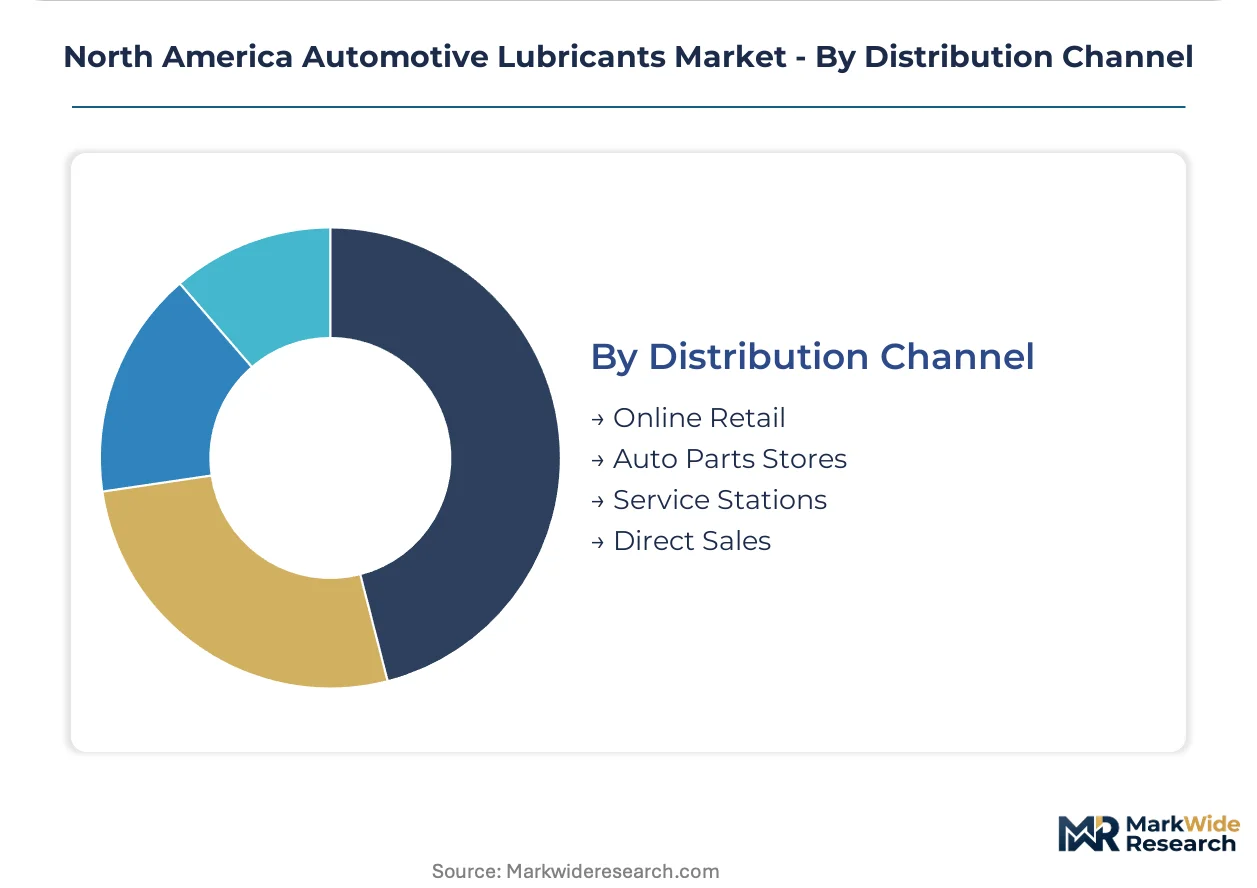
Distribution Channel:
Channel selection determines margin capture and customer relationship depth in a market shifting toward subscription-like service models.
- Online Retail:E-commerce platforms serving DIY consumers and small repair shops with convenience-driven purchasing.
- Auto Parts Stores:Brick-and-mortar retailers with counter staff technical support and immediate availability for emergency repairs.
- Service Stations:Co-located quick-lube operations and fuel retail sites capturing drive-by maintenance demand.
- Direct Sales:Formulator-to-fleet or formulator-to-OEM relationships eliminating distributor margin layers. Fleet management software systems require API connectivity for automated reordering, forcing distributors into expensive platform upgrades to compete.
Auto Parts Stores retains the broadest geographic footprint; Direct Sales is climbing the fastest as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast refinery complexes dominate North American Group II and Group III base oil production, concentrating feedstock supply in Texas and Louisiana. Hurricane exposure and logistics constraints create periodic supply volatility that ripples through lubricant formulation networks across the continent.
United States
The Great Lakes manufacturing corridor in Michigan and Ohio sustains dense automotive production clusters driving OEM-fill and service-fill lubricant demand. The EPA coordinates with NHTSA on fuel economy standards that mandate lower viscosity engine oil grades. Detroit-area assembly plants and tier-1 supplier parks concentrate factory-fill procurement volumes.
Canada
Cross-border trucking corridors linking Ontario to U.S. distribution hubs generate concentrated demand for extended-drain commercial lubricants. Health Canada enforces environmental regulations affecting lubricant disposal and recycling protocols. Alberta oil sands and British Columbia mining districts sustain severe-duty off-road equipment lubricant consumption.
Mexico
Expanding automotive assembly capacity in Nuevo León and the Bajío Region drives factory-fill lubricant qualification programs. The country's national environmental regulator enforces emissions standards that increasingly align with U.S. EPA timelines. Querétaro and Guanajuato supplier parks concentrate tier-1 manufacturing requiring process lubricants.
North America Automotive Lubricants Market Competitive Landscape
Integrated petroleum majors and specialty lubricant formulators split the market between feedstock-integrated scale and channel-specific service models. The competitive structure tiers around backward integration depth, with Gulf Coast refining assets providing cost-position advantages for base oil supply. Three archetypes dominate: integrated oil companies with captive base oil production, quick-lube channel specialists with recurring revenue platforms, and regional blenders serving niche industrial segments. Capacity expansion and channel integration represent the dominant competitive moves as suppliers reposition for fleet procurement consolidation.
Among integrated petroleum majors, ExxonMobil Corporation anchors the feedstock-integrated archetype through its Gulf Coast refining base. Shell plc occupies a comparable position with upstream control over Group III+ base oil production. Valvoline Inc. exemplifies the channel-specialist model, with its quick-lube network generating high-margin recurring revenue streams distinct from commodity lubricant sales.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell plc |
| Valvoline Inc. |
| BP plc |
| Phillips 66 |
| TotalEnergies SE |
| Castrol Limited |
| Petro-Canada Lubricants |
| Others |
Value Network & Pricing Analysis
Hurricane exposure across Gulf Coast refinery complexes determines both the premium-to-economy pricing spread for Group II/III base oils and the geographic configuration of backup supply networks. Buyers absorb volatility through long-term offtake contracts that embed force majeure clauses, compressing margins for distributors lacking captive production.
Pricing Analysis
The U.S. EPA's coordinated fuel economy mandates with NHTSA dictate the pricing tier structure across SAE viscosity grades, with 0W-16 and 0W-8 formulations commanding certification premiums over legacy 5W-30 products. Three-tier pricing structure across premium synthetic, standard synthetic-blend, and economy mineral-based levels separates fleet operators with extended-drain requirements from price-sensitive DIY consumers. Cost compression in the economy tier is intensifying because quick-lube chains consolidate procurement through direct formulator relationships. Fleet operators exhibit the lowest price sensitivity due to total cost of ownership calculations, while independent repair shops face acute margin pressure from bulk-buying competitors.
Supply Chain Analysis
Export-control regimes on advanced additive chemistries limit flows of friction-modifier packages containing restricted rare-earth compounds, constraining formulation flexibility for non-integrated blenders. Base oil supply concentrates in the United States Gulf Coast, Canada, and select European export hubs, with Group III+ capacity expansion lagging synthetic lubricant demand growth. Raw material dependencies include PAO base stocks, detergent-dispersant additives, and viscosity-index improvers sourced from specialty chemical manufacturers. Single-source vulnerability persists for hurricane-prone Texas and Louisiana refinery clusters, where logistics chokepoints amplify disruption risk. Distribution runs through a hybrid model: direct sales to fleet operators and OEMs, with jobber networks serving fragmented aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as electrification tailwinds create parallel thermal-management fluid categories alongside traditional powertrain lubricants. Synthetic lubricant penetration in commercial fleets remains below saturation, extending the runway for premium formulation growth.
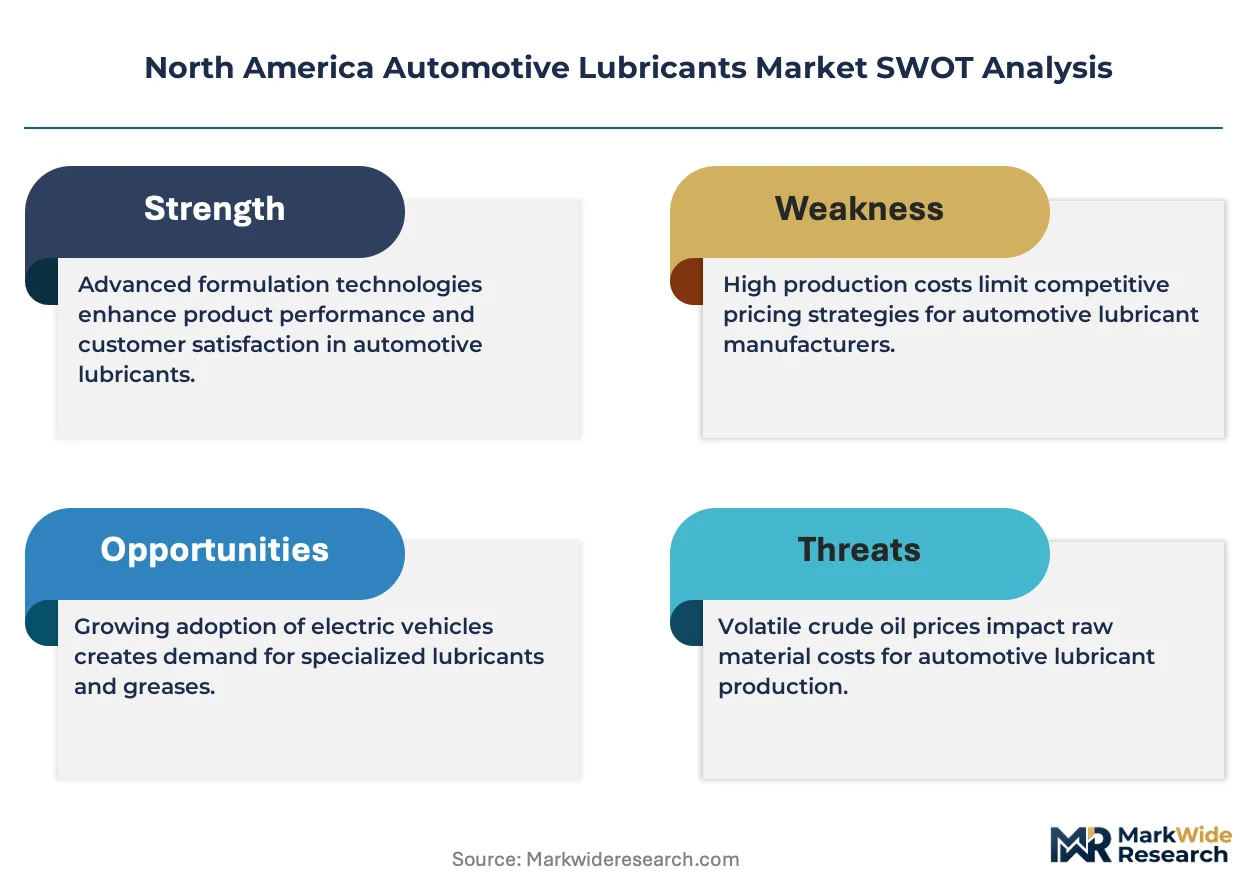
For Market Incumbents: Harden feedstock security through backward integration into Group III+ base oil production or long-term supply agreements with Gulf Coast refiners. Electric powertrain substitution threatens engine oil volumes, making thermal management fluid R&D investment the critical defensive lever. Channel control through quick-lube network expansion preserves margin capture against fleet procurement consolidation.
For New Entrants and Emerging Players: Canadian heavy-duty trucking corridors and Alberta mining districts represent the most penetrable entry point for extended-drain commercial lubricants underserved by incumbent distribution density. Cross-border fleet operators seeking alternatives to established suppliers present receptive buyers for qualification-flexible formulators. A go-to-market angle anchored in API certification speed—beating incumbents to California CARB preemption timelines—creates differentiation.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors formulators with dual-chemistry capability spanning traditional lubricants and dielectric thermal fluids. Long-term viability over the next decade hinges on positioning for electric vehicle thermal management alongside legacy powertrain service. The acquisition target archetype: regional blenders with established fleet relationships and flexible formulation infrastructure. The signal to watch is OEM thermal management fluid qualification announcements, indicating inflection in addressable market composition.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Base Oil Production | Captive supply from Gulf Coast refining assets insulates margin pressure from feedstock volatility. |
| Quick-Lube Channel Acquisition or Partnership | Direct placement with Valvoline-type networks secures recurring revenue streams independent of commodity pricing. |
| California CARB Preemptive Product Qualification | Early certification for supplemental emissions standards builds first-mover positioning in the largest state vehicle population. |
| Thermal Management Fluid R&D Expansion | Dielectric formulation capability addresses electric vehicle battery and inverter cooling demand growth. |
| Fleet Management Software API Integration | Automated reordering connectivity captures procurement consolidation through maintenance service provider platforms. |
Research Methodology
A standing panel of lubricant formulators, fleet procurement directors, quick-lube operations managers, and aftermarket distributors provided ongoing calibration across primary data collection. Secondary validation drew from API certification databases, EPA regulatory filings, U.S. EIA refinery utilization reports, and vehicle production statistics from IHS Markit. Bottom-up volume modeling triangulated against top-down value estimates from petroleum major segment disclosures.
Scenario-bracketing across electrification penetration rates and synthetic lubricant adoption curves anchored the analytical framework throughout the projection horizon. Segmentation dimensions spanned product type, vehicle class, propulsion architecture, OEM versus aftermarket channel, and regional production cluster. CAGRs were derived from installed vehicle base projections and drain-interval elasticity modeling. Industry-specific inputs included EPA fuel economy rulemaking timelines and fleet telematics adoption rates affecting automated reordering.
Stress conditions across hurricane disruption frequency, base oil capacity expansion delays, and electric vehicle sales penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory coordination between EPA and NHTSA, CARB preemption patterns, and fleet consolidation trajectories. Material shifts in federal emissions enforcement intensity or Gulf Coast refinery investment cycles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
Hydropower Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Lubricity Improvers Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Global Grease Cartridges Market