
 Cerebrospinal Fluid (CSF) Testing Market | 2026-2036
Cerebrospinal Fluid (CSF) Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebrospinal Fluid (CSF) Testing Market Outlook
Software-defined assay analytics is realigning what laboratories purchase, shifting capital from standalone instruments to cloud-connected diagnostic platforms. Medtronic leverages its neurosurgical device installed base to cross-sell CSF collection and monitoring systems. Natus Medical anchors its position through electrodiagnostic and neurocritical care product integration. Sophysa specializes in intracranial pressure management devices that interface directly with CSF sampling workflows.
Cerebrospinal fluid testing analyzes the clear, protein-rich fluid surrounding the brain and spinal cord for protein concentration, cell count, glucose levels, and pathogen detection to diagnose infections, hemorrhages, multiple sclerosis, and Alzheimer's disease biomarkers. Reagents and consumables command recurring revenue streams as laboratories process high-throughput panels, while instrumentation faces longer replacement cycles and capital budget competition. Mass spectrometry and immunoassays dominate technology deployment for protein biomarker quantification, with PCR gaining share in infectious disease CSF panels.
FDA oversight of laboratory-developed tests and CLIA quality standards shape assay commercialization pathways and clinical adoption timelines. The EU MDR and IVDR frameworks impose stricter conformity requirements on CSF diagnostic kits entering European markets. Stakeholders must monitor regulatory convergence between US and European in vitro diagnostic frameworks to anticipate compliance costs and market access timelines.
Market Dynamics
Software-defined assay analytics is compressing instrument replacement cycles as laboratories redirect capital toward cloud-connected diagnostic platforms and subscription-based reagent panels.
Growth Catalysts
- FDA's evolving LDT oversight:The FDA's framework for laboratory-developed tests is accelerating clinical validation standards, pushing diagnostic developers toward higher-throughput, automated CSF platforms that reduce manual processing variability.
- Neurodegenerative screening expansion:Diagnostic laboratories in the United States are scaling Alzheimer's biomarker panels, driving recurring reagent consumption for amyloid-beta and tau protein quantification.
- Mass spectrometry adoption:Clinical laboratories are deploying LC-MS/MS systems for CSF metabolite profiling, enabling simultaneous quantification of multiple neurological biomarkers in a single analytical run.
Market Restraints
- Capital equipment intensity:Mass spectrometry and automated immunoassay platforms require substantial upfront investment, constraining adoption among mid-sized hospital laboratories with limited capital budgets.
- Reagent supply concentration:Specialty antibodies and isotopically labeled standards for CSF biomarker assays concentrate among a limited supplier base, creating vulnerability to batch-to-batch variability and lead time extensions.
- EU IVDR compliance burden:The European Union's In Vitro Diagnostic Regulation imposes stricter conformity assessment requirements, extending market access timelines for novel CSF assay kits.
Strategic Opportunities
- Point-of-care neurology:Emergency departments in Germany and France are piloting rapid CSF analysis devices for suspected subarachnoid hemorrhage, bypassing centralized laboratory bottlenecks.
- AI-assisted interpretation:Machine learning algorithms are integrating with flow cytometry data to automate cell count differentiation in CSF, reducing pathologist review time.
- Biobank network expansion:National brain banks in Sweden and the Netherlands are standardizing pre-analytical CSF collection protocols, creating longitudinal sample repositories for biomarker discovery.
Industry Challenges
- Pre-analytical standardization:Variability in CSF collection tubes, centrifugation protocols, and storage temperatures degrades biomarker stability, complicating multi-site clinical trial data harmonization.
- Cross-platform assay correlation:Discrepancies between immunoassay and mass spectrometry results for identical CSF biomarkers create diagnostic uncertainty and require dual-method validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebrospinal Fluid (CSF) Testing Market |
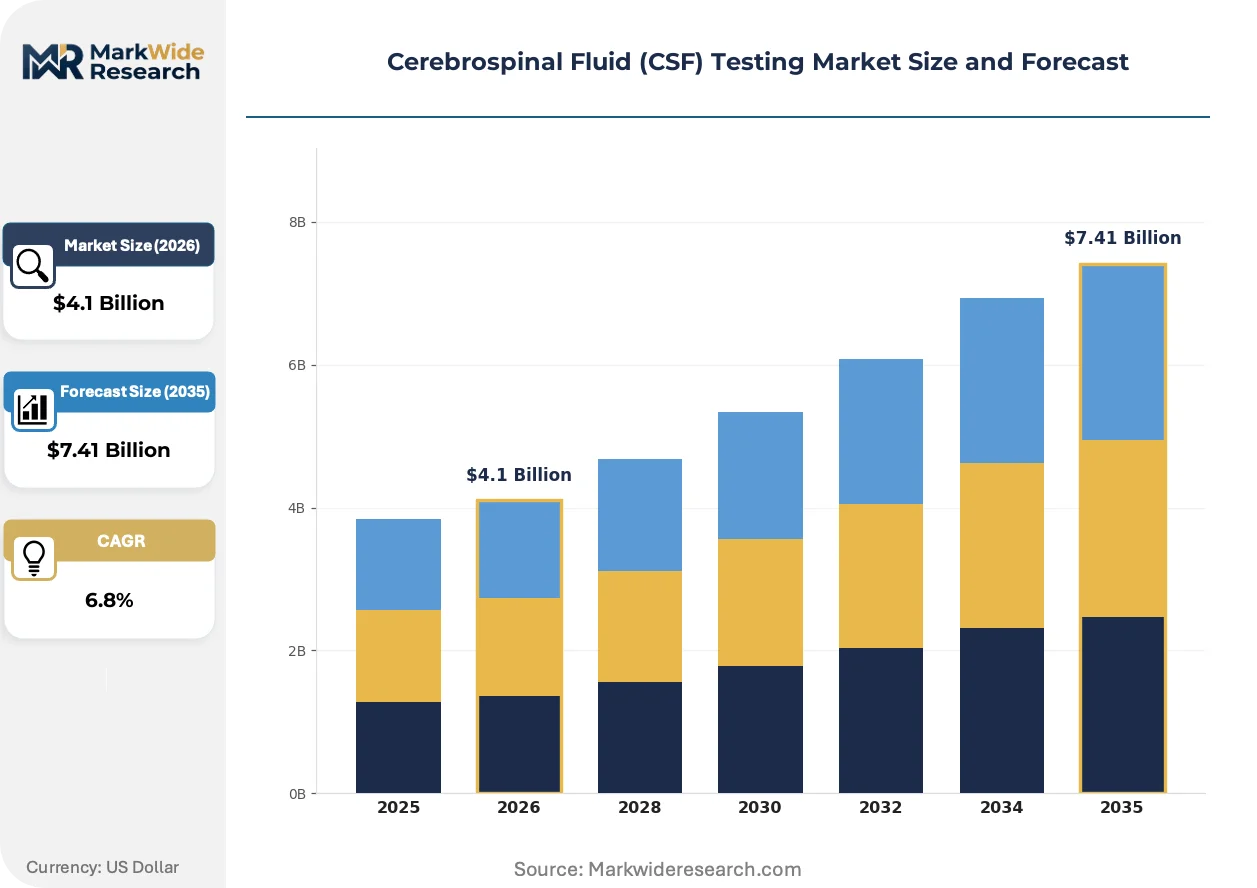
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instrumentation, Reagents, Consumables, Kits Application: Diagnostic Testing, Research,Clinical Trials, Biomarker Discovery End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Centers Technology: Mass Spectrometry, Immunoassays, PCR, Microscopy |
| Companies Covered | Sophysa, DePuy Synthes, Medtronic, Belay Diagnostics, Moller Medical, B. Braun, Natus Medical, Spiegelberg, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebrospinal Fluid (CSF) Testing Market Strategic Shifts
Digital pathology workflows and multiplex biomarker panels are converging to reshape how neurological diagnoses are confirmed, shifting value capture from hardware toward data analytics and interpretive software.
Mass spectrometry-based proteomics is integrating with automated sample preparation robotics to enable high-throughput CSF biomarker quantification. Academic medical centers in the United States are adopting these platforms for research-to-clinic translation. The technology is compressing turnaround times from days to hours while reducing manual pipetting errors.
The EU MDR and IVDR frameworks are tightening post-market surveillance requirements for CSF diagnostic devices. Manufacturers must now maintain clinical evidence registries and periodic safety updates. Smaller assay developers are responding by partnering with notified bodies early in the design phase to preempt conformity gaps.
Hospital procurement departments are consolidating CSF testing contracts under integrated laboratory service agreements. Health systems in the United Kingdom are replacing instrument-specific purchasing with multi-year managed service contracts spanning reagents, maintenance, and software updates. This restructuring concentrates vendor selection authority within centralized supply chain functions.
Cerebrospinal Fluid (CSF) Testing Market Segmentation
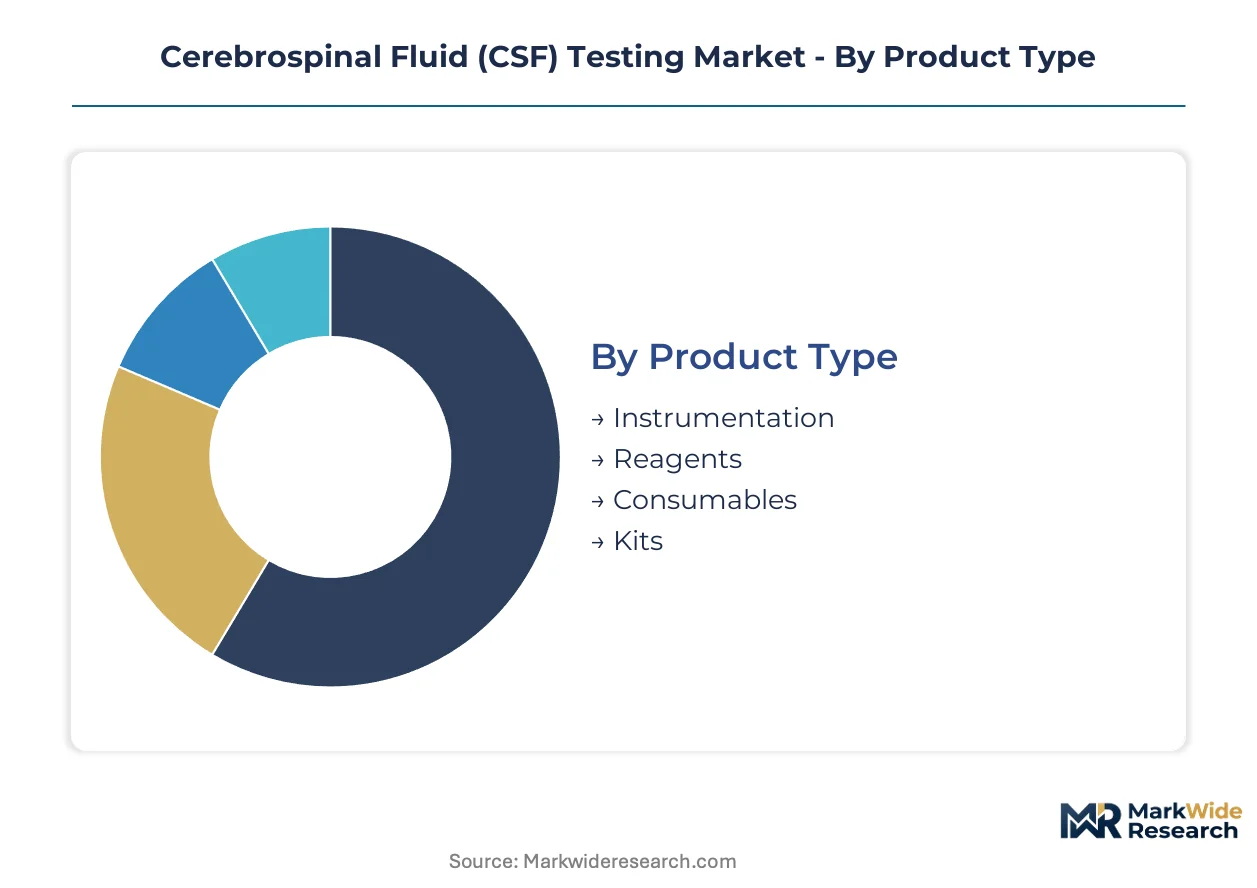
CSF testing procurement patterns diverge sharply between capital-intensive instrumentation and recurring reagent consumption, with upgrade cycles and replacement timelines driving vendor selection criteria across hospital and laboratory settings.
Product Type:
Replacement cycles compress as laboratories redirect capital from standalone analyzers toward integrated platform ecosystems with embedded software subscriptions.
- Instrumentation:Automated immunoassay analyzers and mass spectrometry platforms require 5-7 year capital planning horizons. Academic medical centers in the United States prioritize systems with open-architecture software that accommodates multiplex panel expansion without hardware replacement.
- Reagents:Antibody conjugates, calibrators, and isotopically labeled internal standards generate recurring revenue streams tied to test volume. Supply contracts increasingly bundle reagent consumption with instrument placement to lock in multi-year purchasing commitments.
- Consumables:Collection tubes, pipette tips, and sample preparation cartridges face price pressure from consolidated laboratory procurement functions.
- Kits:Pre-packaged assay panels for Alzheimer's biomarker quantification reduce lot-to-lot variability but constrain customization flexibility.
Reagents sit at the top of the volume ranking, with kits climbing the fastest as standardized neurodegenerative panels displace in-house assay development.
Application:
Cost tier separation emerges between reimbursed clinical diagnostics and grant-funded research applications, with biomarker discovery commanding premium pricing for specialized reagent formulations.
- Diagnostic Testing:Reimbursed panels for infection, hemorrhage, and demyelinating disease detection dominate hospital laboratory throughput. CLIA-certified laboratories in the United States drive volume for routine CSF glucose, protein, and cell count analysis.
- Research:Academic investigators prioritize assay flexibility over regulatory certification, purchasing research-use-only antibodies and custom mass spectrometry methods. Funding volatility from NIH and European Research Council grants creates irregular purchasing patterns distinct from clinical revenue stability.
- Clinical Trials:Central laboratories managing multi-site neurodegenerative studies demand pre-analytical standardization across collection sites. Biomarker qualification requirements from FDA and EMA impose additional validation costs on assay developers serving this segment.
- Biomarker Discovery:Untargeted proteomics and metabolomics screening generates low-volume, high-complexity demand for specialized chromatography columns and mass spectrometry consumables.
Diagnostic testing captures the highest absolute spending, with clinical trials expanding most quickly as pharmaceutical sponsors accelerate Alzheimer's therapeutic development programs.
End User:
Customer type determines procurement authority concentration, with health system centralization reshaping how diagnostic laboratories negotiate reagent and service contracts.
- Hospitals:Inpatient neurology services and emergency departments require rapid turnaround for suspected meningitis and subarachnoid hemorrhage. Mid-sized community hospitals face capital constraints that limit mass spectrometry adoption to send-out reference laboratory arrangements.
- Diagnostic Laboratories:National reference chains and regional independent laboratories achieve scale economies in high-throughput biomarker quantification. Quest Diagnostics and LabCorp consolidation in the United States concentrates purchasing power for reagent sourcing negotiations.
- Academic Institutions:Medical school-affiliated hospitals blend clinical service requirements with research mission flexibility, maintaining dual inventory streams for CLIA-certified and research-use-only assays.
- Research Centers:Standalone neuroscience institutes and brain bank networks prioritize sample biorepository compatibility over analytical throughput, investing in standardized pre-analytical processing equipment.
Diagnostic laboratories lead in procurement volume, with academic institutions gaining share fastest as research-to-clinic translation funding expands.
Technology:
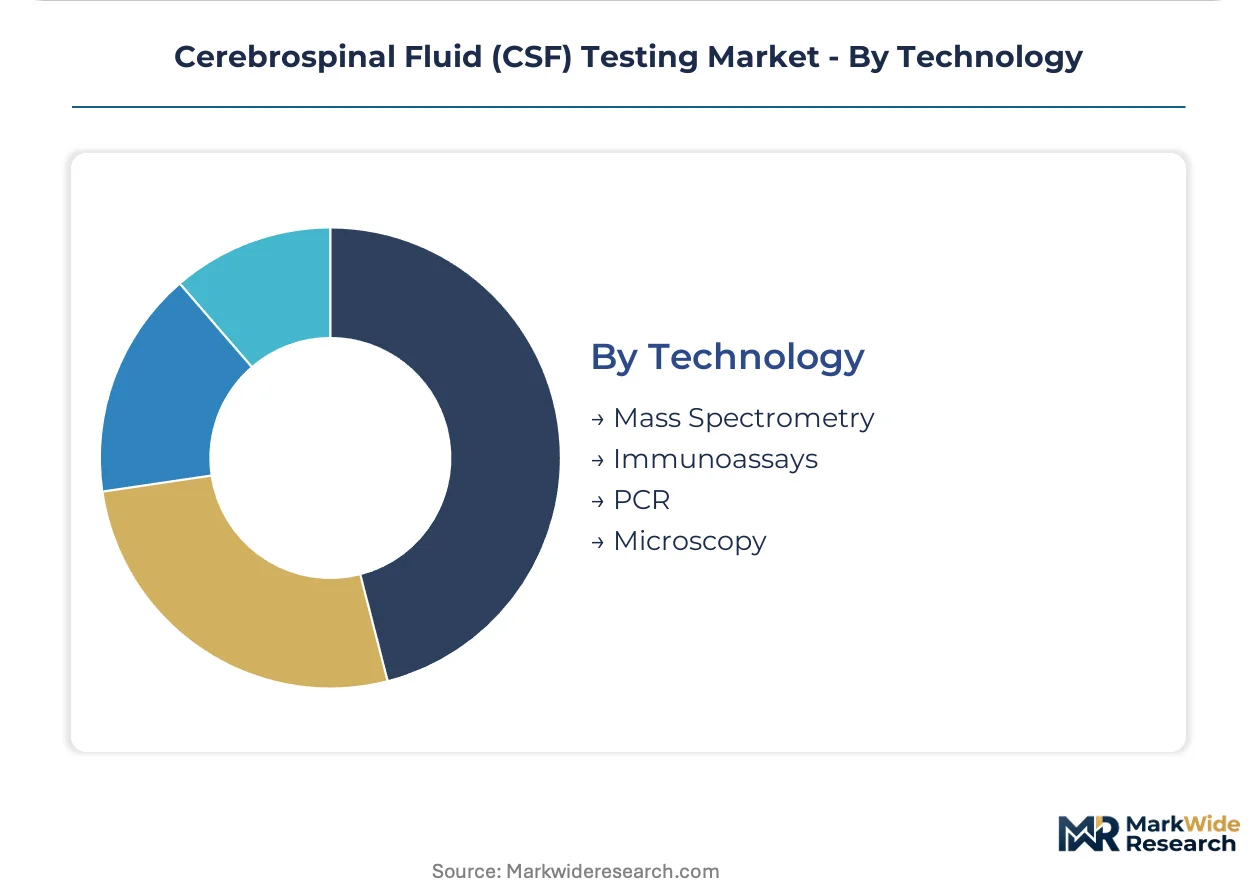
Technology maturity curves separate established immunoassay platforms from emerging mass spectrometry adoption, with PCR gaining infectious disease panel share through syndromic testing integration.
- Mass Spectrometry:LC-MS/MS systems enable simultaneous quantification of amyloid-beta, tau, and neurofilament light chain without antibody cross-reactivity interference. Installation growth concentrates in academic medical centers with neurochemistry core facilities.
- Immunoassays:Chemiluminescence and ELISA platforms dominate routine CSF protein analysis through established reimbursement pathways and regulatory clearance breadth. Beckman Coulter and Roche maintain installed base advantages in hospital core laboratories.
- PCR:Syndromic meningitis/encephalitis panels from BioFire and FilmArray compress pathogen detection turnaround from days to hours.
- Microscopy:Manual cell count and Gram stain procedures persist in resource-constrained settings despite flow cytometry automation availability.
Immunoassays retain the highest test volume position, with mass spectrometry following the steepest expansion trajectory as protein biomarker multiplexing requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's diagnostic laboratory networks process higher CSF biomarker volumes per capita than France, reflecting deeper integration of neurodegenerative screening into standard neurological care protocols across Central Europe.
United States
Academic medical centers in Boston and Baltimore drive adoption of mass spectrometry-based CSF panels for Alzheimer's biomarker quantification. FDA oversight of laboratory-developed tests shapes validation requirements for novel assays. The Research Triangle in North Carolina anchors clinical trial central laboratory services for multi-site neurodegenerative studies.
Germany
Emergency departments in Munich and Hamburg pilot rapid CSF analysis devices for suspected subarachnoid hemorrhage. EU IVDR compliance requirements extend market access timelines for novel assay kits. The Heidelberg-Mannheim corridor concentrates biobank networks standardizing pre-analytical CSF collection protocols.
Sweden
National brain banks in Stockholm and Gothenburg maintain longitudinal CSF sample repositories for biomarker discovery research. The country's national pharmaceutical regulator enforces strict post-market surveillance for diagnostic devices. The Uppsala region hosts core facilities translating proteomics methods into clinical workflows.
Netherlands
Academic hospitals in Amsterdam and Rotterdam integrate AI-assisted flow cytometry for automated CSF cell count differentiation. GDPR compliance requirements shape data handling for cloud-connected diagnostic platforms. The Leiden-Utrecht corridor concentrates electrodiagnostic device manufacturers expanding into CSF sampling workflows.
Japan
PMDA regulatory pathways prioritize clinical validation for companion diagnostic CSF assays supporting therapeutic development. METI funding programs accelerate translation of mass spectrometry methods from research to hospital laboratories. The Tokyo-Osaka corridor dominates procurement of automated immunoassay analyzers for routine CSF protein analysis.
Cerebrospinal Fluid (CSF) Testing Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated device-and-consumable vendors commanding premium positions in hospital procurement while component suppliers capture volume through reference laboratory chains. The vendor base concentrates around three strategic archetypes: neurosurgical device incumbents cross-selling into CSF collection workflows, standalone diagnostic platform developers, and consumables-focused reagent houses. Consolidation pressures intensify as health systems bundle instrument placement with multi-year reagent supply agreements, while technology licensing partnerships accelerate assay menu expansion without internal R&D investment.
Among neurosurgical-device-anchored competitors, Medtronic, Sophysa, and Natus Medical exemplify the cross-selling archetype, each occupying positions that leverage installed base relationships in neurocritical care to expand into CSF sampling and monitoring workflows. These entities sit within a tier where hardware placement drives recurring consumable attachment, contrasting with pure-play diagnostic developers competing on assay breadth and regulatory clearance velocity.
| Leading Market Players |
|---|
| Sophysa |
| DePuy Synthes |
| Medtronic |
| Belay Diagnostics |
| Moller Medical |
| B. Braun |
| Natus Medical |
| Spiegelberg |
| Integra LifeSciences |
| Others |
Value Chain & Pricing Dynamics
Performance-grade bifurcation between mass spectrometry platforms and routine immunoassay systems manifests in divergent supply chain configurations and procurement authority concentration. Premium-tier LC-MS/MS installations anchor long-term reagent lock-in contracts through bundled consumable commitments, while standardized ELISA workflows face procurement centralization that compresses margin structures across both pricing and supplier selection dimensions.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for isotopically labeled internal standards and specialty antibody conjugates. The market operates on a hybrid structure combining capital equipment placement with subscription-based reagent panels. Price differentiation rests on CLIA certification tier and biomarker panel complexity, with FDA-cleared Alzheimer's assays commanding substantial premia over research-use-only alternatives. Cost compression in routine protein quantification intensifies as hospital procurement departments consolidate contracts under multi-year managed service agreements. Mid-sized community hospitals exhibit highest price sensitivity due to capital budget constraints, while academic medical centers prioritize assay menu breadth over per-test economics.
Supply Chain Analysis
Regional distribution centers in Massachusetts, North Rhine-Westphalia, and Tokyo prefecture anchor hub-and-spoke patterns for temperature-sensitive reagent logistics. Manufacturing concentration spans the United States, Germany, and Japan for mass spectrometry platforms, with antibody production drawing from facilities in the United States and Switzerland. Specialty isotopes and chromatography consumables hinge on suppliers in Germany and the United States. Single-source vulnerability concentrates in isotopically labeled tau protein standards, where batch-to-batch variability creates qualification delays. Distribution runs through health system central warehouses for hospital laboratories, while national reference chains maintain direct vendor relationships for high-throughput reagent sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CSF testing market compounds steadily as neurodegenerative disease prevalence climbs in aging populations across developed economies, anchoring recurring reagent demand irrespective of macroeconomic cycles.
For Market Incumbents: Acquire pre-analytical standardization protocols and biobank network relationships to defend installed base positions against mass spectrometry platform entrants. Consolidate reagent supply contracts under multi-year managed service agreements that embed software analytics subscriptions, raising switching costs for hospital laboratory customers. Invest in backward integration into isotopically labeled internal standard production to reduce batch variability exposure from concentrated supplier tiers. For New Entrants and Emerging Players: Reference laboratory partnerships offer the most penetrable channel for novel assay commercialization without direct hospital capital sales cycles. Target emergency department rapid testing workflows in France and Germany, where centralized laboratory bottlenecks create white-space for point-of-care CSF analysis devices. Pursue biobank network integration as a go-to-market angle, leveraging standardized pre-analytical protocols to accelerate clinical validation timelines for novel biomarker panels. For Investors and Strategic Acquirers: Consolidation pressure builds where reagent supply concentration intersects with health system procurement centralization, favoring platform vendors with bundled instrument-consumable-service offerings. The market supports 5-10 year compound growth trajectories anchored by Alzheimer's therapeutic development pipelines and reimbursement expansion for predictive biomarker testing. Acquisition target archetypes include mass spectrometry assay developers with FDA-cleared neurodegenerative panels and biobank-linked sample processing technology providers. Monitor FDA laboratory-developed test guidance evolution as the critical inflection signal for platform standardization versus fragmentation outcomes.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR compliance unlocks European market access for novel CSF assay kits. |
| Hospital System Partnership | Integrated laboratory service agreements concentrate procurement authority with platform vendors. |
| Software Companion Development | AI-assisted flow cytometry interpretation reduces pathologist review time and differentiates platform offerings. |
| Reimbursement Strategy | CPT code acquisition for Alzheimer's biomarker panels drives clinical adoption and reagent volume. |
| Biobank Network Integration | Standardized pre-analytical protocols accelerate biomarker discovery translation into cleared assays. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with laboratory directors, neurochemistry core facility managers, hospital procurement officers, and diagnostic platform product managers with secondary validation. Primary fieldwork drew from FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov biomarker qualification studies, and CMS Medicare reimbursement databases. SEC 10-K disclosures from publicly traded diagnostic manufacturers provided financial segmentation anchors. Bottom-up test volume modeling and top-down market sizing triangulated across reagent consumption estimates and instrument placement tracking.
Historical reference periods anchored the forecast window to pre-pandemic baseline utilization patterns and post-2023 reimbursement expansion trajectories. The analytical framework modeled segmentation dimensions spanning technology platform, application purpose, end-user facility type, and regional regulatory cluster. CAGRs derived from instrument replacement cycle compression rates and reagent panel expansion trajectories. Neurodegenerative screening reimbursement decisions and FDA LDT oversight evolution served as primary forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biomarker qualification timelines and health system procurement centralization velocity. Outputs reflect documented assumptions regarding Alzheimer's therapeutic development success rates and EU IVDR notified body capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Specific Protein Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Special Coagulation Tests Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Global Laboratory Proficiency Testing Market