
 Large Molecule Bioanalytical Testing Services Market | 2026-2036
Large Molecule Bioanalytical Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Large Molecule Bioanalytical Testing Services Market Intelligence
The capital-intensity divergence between fully integrated testing platforms and modular service offerings is bifurcating competitive tiers in large molecule bioanalytical testing. Laboratory Corporation of America Holdings leverages its central laboratory network to sustain high-throughput clinical trial support across multiple therapeutic areas. Charles River Laboratories anchors its position through specialized biologics safety testing capabilities that extend into complex cell and gene therapy analytical programs. WuXi AppTec competes aggressively on geographic coverage, operating substantial GLP-compliant facilities that serve both domestic Chinese and international sponsor demand.
Large molecule bioanalytical testing services encompass the quantitative and qualitative measurement of biologics—monoclonal antibodies, recombinant proteins, gene therapies, and oligonucleotides—in biological matrices using ligand-binding assays, mass spectrometry, and cell-based methods, with sensitivity requirements typically reaching pg/mL levels for pharmacokinetic characterization. These services enable regulatory submission packages for biologic drug candidates by demonstrating bioequivalence, immunogenicity profiles, and exposure-response relationships to health authorities. Mass spectrometry platforms are capturing expanding method development work as biosimilar comparability studies intensify, while immunoassay technologies dominate routine clinical sample analysis where throughput and cost efficiency determine contract awards. Bioassay segments command premium pricing due to cell line maintenance complexity and the specialized scientific talent required for potency determination.
FDA immunogenicity guidance and EMA bioanalytical method validation standards shape method development protocols, driving sponsors toward providers with established regulatory inspection histories and documented assay reproducibility. The EU AI Act and evolving FDA expectations for algorithm-enabled data analysis are beginning to influence how chromatography and next-generation sequencing workflows incorporate artificial intelligence for peak integration and variant detection. Stakeholders must evaluate whether their testing partners maintain concurrent compliance across multiple regulatory jurisdictions or risk program delays from redundant method transfers.
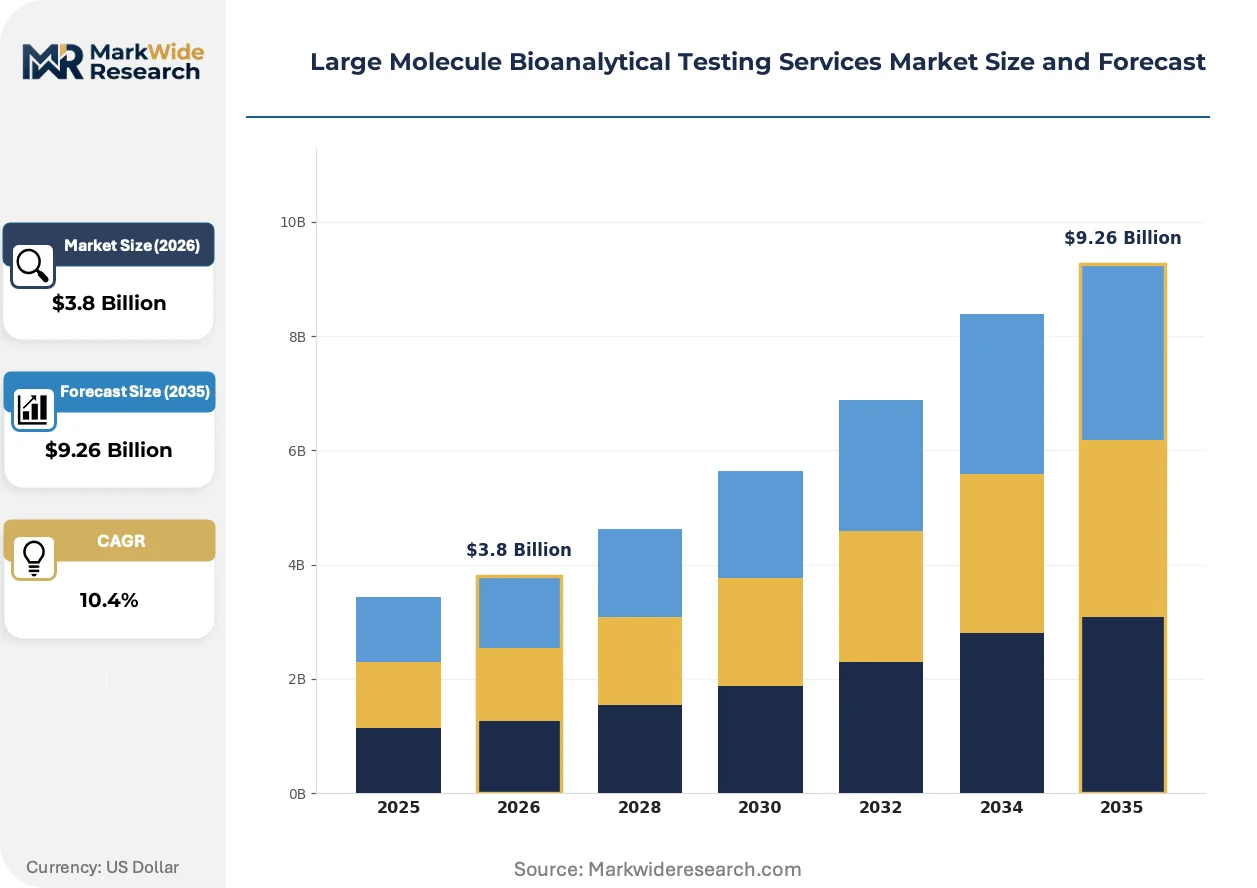
Market Dynamics
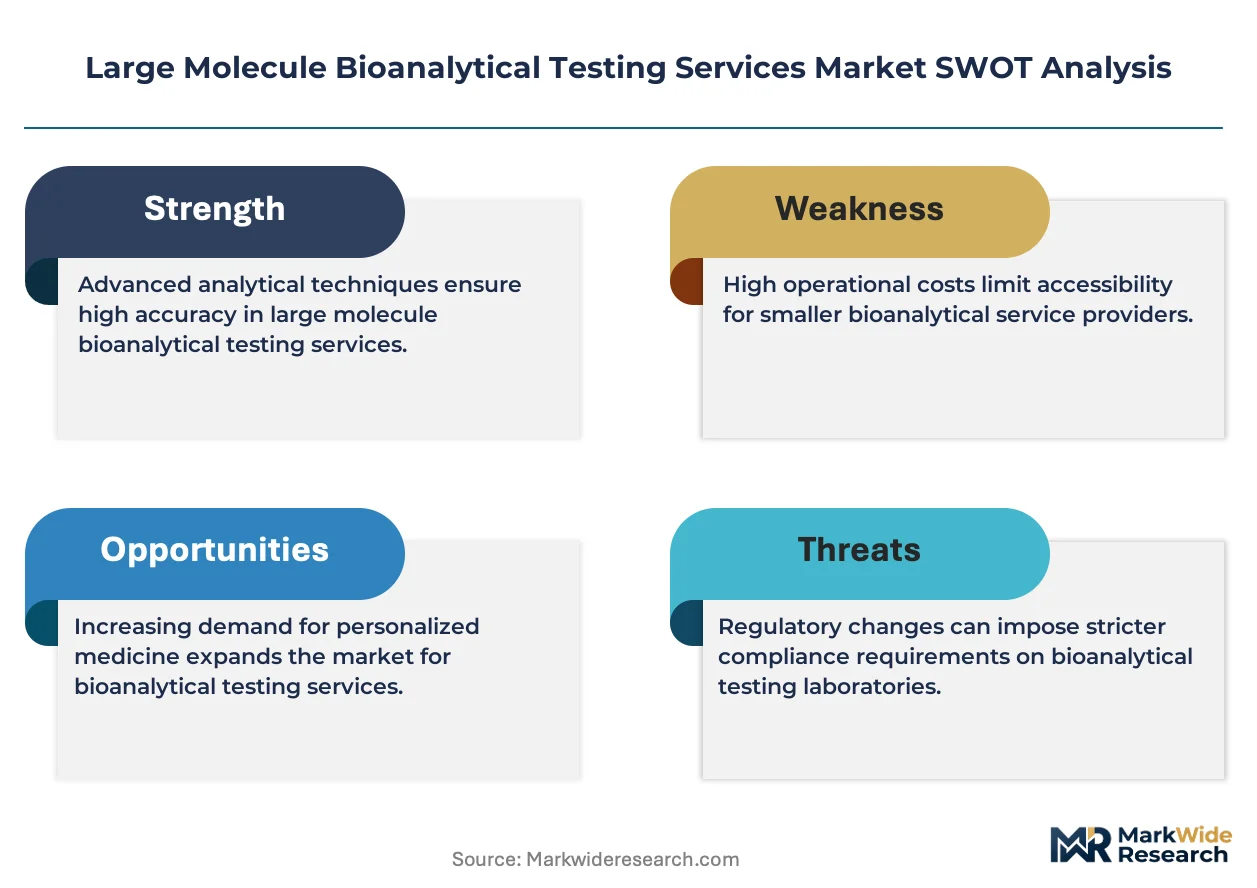
Mass spectrometry platforms are supplanting legacy ligand-binding assays for biosimilar comparability studies, compressing method development timelines while elevating the technical bar for contract providers. This instrumentation shift coincides with tightening FDA immunogenicity guidance and EMA bioanalytical method validation standards that favor laboratories with documented regulatory inspection histories.
Growth Catalysts
- EMA Bioanalytical Method Validation Standards:Sponsors outsource complex immunogenicity assay development to CROs with established European regulatory track records, accelerating demand for GLP-compliant facilities.
- Cell and Gene Therapy Pipelines:Viral vector potency assays and CAR-T pharmacokinetic characterization require specialized bioanalytical capabilities that biopharmaceutical developers lack in-house.
- Boston and San Diego Biotech Clusters:Concentrated R&D investment in these metropolitan hubs generates sustained contract volumes for local and national testing service providers.
Market Restraints
- High-Purity Reagent Costs:Certified reference materials and critical assay components face supply concentration among limited qualified vendors, inflating per-test material expenditures.
- Specialized Scientific Talent Scarcity:Cell-based assay scientists and mass spectrometry method developers command premium compensation, constraining laboratory expansion velocity.
- Multi-Jurisdictional Compliance Burden:Concurrent FDA, EMA, and NMPA method validation requirements force redundant documentation and extended transfer timelines.
Strategic Opportunities
- China Domestic Biopharma Expansion:NMPA regulatory reforms and indigenous innovation policies are cultivating sponsor demand for locally operated GLP-compliant bioanalytical facilities.
- AI-Enabled Peak Integration:Machine learning algorithms applied to chromatography data processing reduce analyst time per sample while improving reproducibility metrics.
- Companion Diagnostic Co-Development:Pharmacokinetic testing bundled with biomarker assay development creates stickier sponsor relationships and higher contract values.
Industry Challenges
- Cell Line Maintenance Complexity:Bioassay segments require continuous culture infrastructure and specialized personnel that strain operational bandwidth and capital deployment.
- Assay Transfer Standardization:Method migration between sponsor laboratories and CROs encounters protocol drift, demanding extensive bridging studies that delay study initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Molecule Bioanalytical Testing Services Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.26 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Western Blot, Bioassay, Mass Spectrometry Technology: Chromatography, Immunoassays, NGS, PCR End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Contract Laboratories Application: Clinical Trials, Preclinical Studies, Quality Control, Regulatory Compliance |
| Companies Covered | Laboratory Corporation of America Holdings, Charles River Laboratories, IQVIA, Syneos Health, ICON plc, SGS SA, WuXi AppTec, Intertek Group plc, Pace Analytical Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Molecule Bioanalytical Testing Services Market Strategic Shifts & Innovations
Next-generation analytical platforms are compressing detection limits while expanding the molecular classes amenable to quantitative bioanalysis. Regulatory authorities are incorporating algorithmic data integrity requirements into inspection protocols.
Hybrid mass spectrometry workflows combining high-resolution accurate mass with automated sample preparation are supplanting traditional ELISA formats for monoclonal antibody pharmacokinetic studies. Large pharmaceutical sponsors and biosimilar developers are adopting these platforms for NDA-enabling studies. The shift is compressing method development cycles from months to weeks while demanding capital-intensive instrumentation investments that favor scaled providers.
The EU AI Act and evolving FDA guidance on computerized systems are mandating algorithm validation for peak integration and data analysis software. Chromatography data systems must now demonstrate audit trail integrity and model interpretability. Bioanalytical CROs serving European and American markets are restructuring quality assurance frameworks to document AI decision pathways.
Consolidated procurement arrangements are displacing project-by-project contracting as mid-cap biopharmaceutical sponsors seek preferred provider relationships. Master service agreements with volume commitments and dedicated capacity allocation are replacing transactional RFP processes. This pattern concentrates contract awards among laboratories with established regulatory inspection histories and multi-site geographic coverage.
Large Molecule Bioanalytical Testing Services Market Segmentation
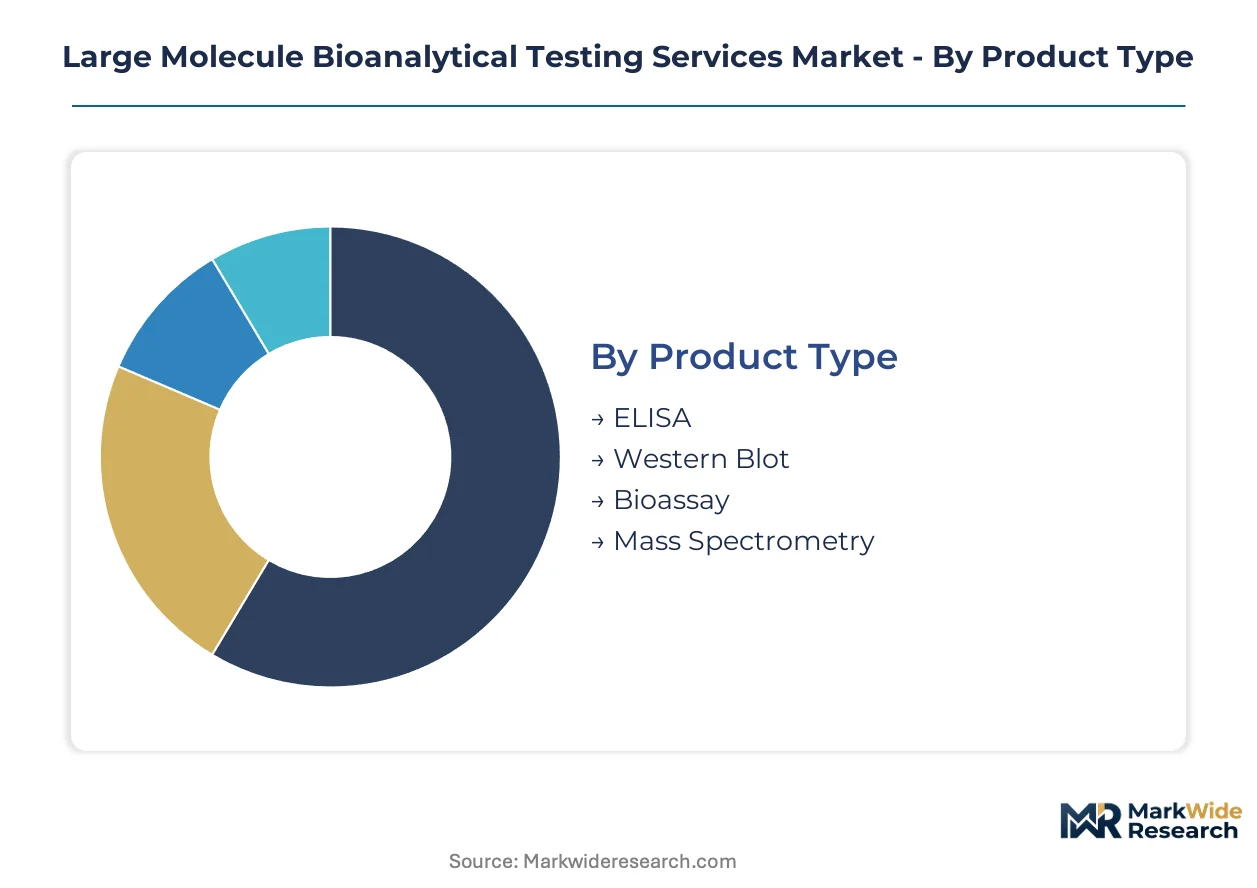
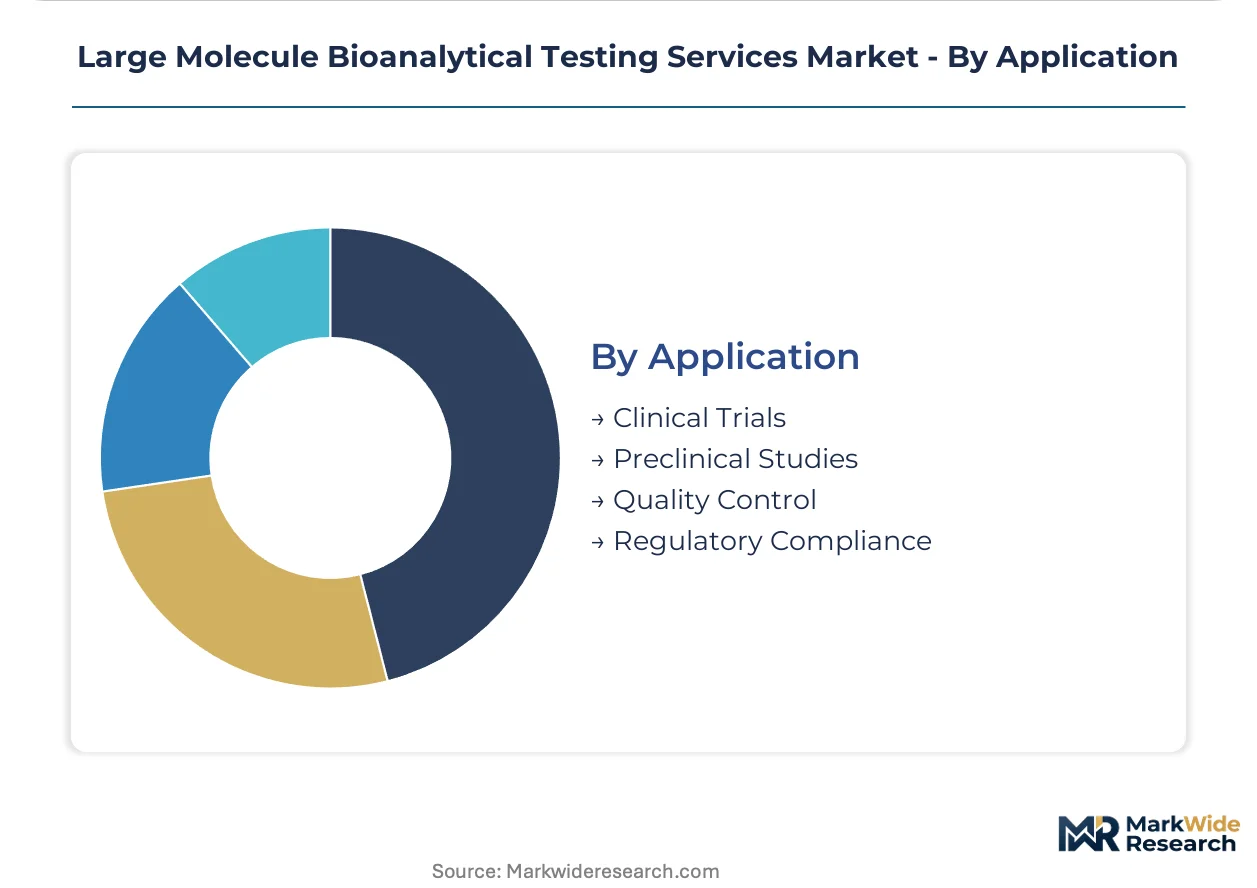
Segmentation in large molecule bioanalytical testing reveals distinct margin architectures across technologies, end-users, and applications. Contract providers optimize platform investments by targeting segments where regulatory complexity and scientific specialization create pricing power.
Product Type:
Margin pools concentrate in platforms requiring specialized instrumentation and scientific talent, with bioassay and mass spectrometry commanding premium positioning.
- ELISA:Enzyme-linked immunosorbent assays deliver standardized quantification of monoclonal antibodies and recombinant proteins with established regulatory acceptance. Pharmaceutical sponsors in the United States route routine clinical sample volumes through high-throughput ELISA platforms to balance cost efficiency with FDA submission requirements.
- Mass Spectrometry:Hybrid high-resolution accurate mass systems enable biosimilar comparability studies with superior specificity over ligand-binding methods. Boston and San Diego biotech clusters are shifting pharmacokinetic method development toward mass spectrometry to compress timelines for NDA-enabling studies.
- Bioassay:Cell-based potency assays require continuous culture infrastructure and specialized personnel for viral vector and CAR-T characterization.
- Western Blot:Semi-quantitative protein detection serves confirmatory immunogenicity testing and antibody specificity verification.
The dominant share belongs to ELISA, while mass spectrometry is closing the gap fastest.
Technology:
Technology selection tracks the molecular complexity of therapeutic pipelines, with immunoassay and chromatography platforms capturing divergent volume-mix profiles.
- Immunoassays:Ligand-binding platforms including ELISA, electrochemiluminescence, and radioimmunoassay dominate routine pharmacokinetic and immunogenicity testing. Biotechnology firms in Germany and Switzerland rely on immunoassay workflows for clinical trial support where throughput and cost efficiency determine contract awards.
- Chromatography:Liquid chromatography-mass spectrometry integration enables quantitative analysis of oligonucleotides and antibody-drug conjugates with pg/mL sensitivity. CROs serving EMA jurisdictions are expanding chromatography capacity to meet evolving bioanalytical method validation standards.
- NGS:Next-generation sequencing supports viral vector identity confirmation and cell line characterization for gene therapy programs.
- PCR:Polymerase chain reaction methods enable nucleic acid quantification in cell and gene therapy biodistribution studies.
Immunoassays retain the largest installed base, though chromatography is expanding most quickly.
End User:
Customer segmentation reflects divergent outsourcing maturity, with pharmaceutical companies and biotechnology firms representing distinct procurement behaviors and technical requirements.
- Pharmaceutical Companies:Large sponsors maintain selective outsourcing strategies, retaining complex method development in-house while contracting high-volume clinical sample analysis. Consolidated procurement arrangements with master service agreements and volume commitments are replacing transactional RFP processes among top-20 pharmaceutical developers.
- Biotechnology Firms:Mid-cap and emerging biotechs lack internal bioanalytical infrastructure, creating full-service dependency on CRO partners for IND-enabling through Phase III support. Cambridge and South San Francisco biotech clusters generate sustained contract volumes for providers with established FDA inspection histories.
- Research Institutes:Academic and government laboratories utilize bioanalytical services for mechanistic pharmacology and biomarker discovery with grant-funded budgets.
- Contract Laboratories:Central laboratory networks and specialized CROs represent both customers and competitors in complex subcontracting arrangements.
Pharmaceutical companies command the greatest contract value per engagement, while biotechnology firms are gaining share fastest.
Application:
Application mix shifts with therapeutic development stage, creating distinct capacity planning requirements across preclinical, clinical, and commercial support.
- Clinical Trials:Phase I-III pharmacokinetic and immunogenicity testing requires GLP-compliant facilities with validated assay platforms and documented regulatory inspection histories. Sponsors conducting multi-regional trials demand concurrent FDA, EMA, and NMPA method validation to avoid redundant transfers.
- Preclinical Studies:IND-enabling toxicokinetic and biodistribution studies in rodent and non-human primate models establish exposure-response relationships. Charles River Laboratories and WuXi AppTec anchor positions through integrated safety assessment and bioanalytical capabilities.
- Quality Control:Lot release testing and stability studies for commercial biologics require GMP-compliant analytical methods with stringent change control.
- Regulatory Compliance:Method validation, transfer, and documentation support for health authority submissions demands specialized regulatory affairs integration.
Clinical trials absorb the greatest service capacity, while preclinical studies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate low price elasticity for immunogenicity assay development, while sponsors in India and Southeast Asia prioritize cost efficiency in routine pharmacokinetic testing. This divergence shapes regional service provider strategies and facility investment patterns.
United States
FDA immunogenicity guidance updates and biosimilar comparability study volumes drive premium service demand. The agency's tightened bioanalytical method validation expectations favor CROs with documented inspection histories. Boston and San Diego biotech clusters generate concentrated contract volumes for specialized cell and gene therapy analytical programs.
Germany
EMA bioanalytical method validation standards and biosimilar development pipelines sustain high-value outsourcing relationships. German biotechnology firms route complex immunogenicity work to GLP-compliant facilities with European regulatory track records. The Munich and Heidelberg life science corridors concentrate sponsor R&D investment and associated testing demand.
China
NMPA regulatory reforms and indigenous biopharma innovation policies expand domestic bioanalytical infrastructure requirements. The agency's evolving GLP inspection standards push sponsors toward locally operated compliant facilities. Shanghai and Suzhou biotech parks anchor regional contract research capacity for both domestic and international sponsors.
Switzerland
Swissmedic alignment with EMA standards and precision medicine initiatives sustain specialized bioanalytical demand. Swiss pharmaceutical sponsors maintain selective outsourcing for complex cell-based potency assays. The Basel pharmaceutical cluster generates sustained contract volumes for high-complexity analytical programs.
United Kingdom
MHRA post-Brexit regulatory autonomy and cell therapy development pipelines reshape bioanalytical procurement patterns. UK biotechnology firms seek CRO partners with concurrent FDA and MHRA method validation capabilities. The Cambridge and Oxford life science clusters concentrate gene therapy analytical demand.
Large Molecule Bioanalytical Testing Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Mass spectrometry platform specialists command premium positioning for biosimilar comparability studies, while high-throughput immunoassay providers compete on operational scale and geographic coverage. Three archetypes dominate: integrated central laboratory networks, specialized biologics CROs, and emerging Asia-Pacific scale players. Consolidated procurement arrangements and dedicated capacity allocation agreements represent the dominant competitive moves, displacing transactional RFP processes among mid-cap and large sponsors.
Within the integrated central laboratory tier, Laboratory Corporation of America Holdings occupies a position exemplifying high-throughput clinical trial support across multiple therapeutic areas. Charles River Laboratories represents the specialized biologics archetype through its extension into complex cell and gene therapy analytical programs. WuXi AppTec anchors the Asia-Pacific scale player category, serving both domestic Chinese and international sponsor demand from substantial GLP-compliant facilities. These three entities collectively illustrate the geographic and capability segmentation shaping contract awards.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Charles River Laboratories |
| IQVIA |
| Syneos Health |
| ICON plc |
| SGS SA |
| WuXi AppTec |
| Intertek Group plc |
| Pace Analytical Services LLC |
| Others |
Cost & Logistics Intelligence
Ninety-day lead times for certified reference materials concentrate pricing power among qualified reagent vendors and force bioanalytical CROs into long-term procurement commitments. This inventory pressure elevates per-test material costs while compressing margins on routine ELISA workflows, pushing providers toward mass spectrometry platforms where reagent substitution flexibility and higher pricing tolerances offset supply concentration risks.
Pricing Analysis
After-sales revenue from method validation support and regulatory documentation drives lifetime contract value beyond initial project fees. Three-tier pricing structure across premium, standard, and economy levels separates GLP-compliant bioassay development from high-throughput clinical sample analysis and exploratory preclinical screening. Price differentiation hinges on regulatory inspection history and therapeutic area specialization, with cell and gene therapy potency assays commanding substantial premiums over monoclonal antibody pharmacokinetic testing. Cost compression in routine immunoassay services is intensifying because sponsor procurement teams are consolidating vendor panels under master service agreements with volume commitments. Biotechnology firms exhibit the highest price sensitivity, prioritizing cost efficiency in IND-enabling studies, while large pharmaceutical sponsors demonstrate low elasticity for immunogenicity assay development requiring documented FDA inspection histories.
Supply Chain Analysis
Strategic stockpiling of critical assay components dominates inventory strategy as qualified vendor concentration creates single-source vulnerabilities for high-purity reagents. Supply concentrates in the United States, Germany, and China for certified reference materials, specialized cell lines, and chromatography consumables respectively. Raw material dependencies include antibody reagents, stable isotope-labeled internal standards, and viral vector reference preparations. Single-source vulnerability around recombinant protein suppliers exposes method development timelines to disruption from manufacturing site inspections or capacity constraints. Distribution runs through direct vendor relationships for high-value reagents and distributor networks for routine consumables, with consolidated procurement arrangements increasingly displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough in early-stage biotech funding, with sponsor R&D budgets expanding as capital markets reopen to clinical-stage assets and FDA biosimilar approval volumes accelerate method development demand.
For Market Incumbents: Secure dedicated capacity allocation agreements with top-20 pharmaceutical sponsors before competitors capture preferred provider status under consolidated procurement arrangements. Deepen backward integration into critical reagent manufacturing to reduce dependency on concentrated qualified vendors and defend margin position from material cost inflation. Investment in AI-enabled chromatography data systems addresses emerging FDA and EMA algorithm validation requirements while creating differentiation against regional competitors lacking regulatory inspection histories.
For New Entrants and Emerging Players: FDA fast-track certification for immunogenicity assay platforms opens immediate contracting opportunities with Boston and San Diego biotech clusters lacking internal bioanalytical infrastructure. Target mid-cap gene therapy developers in the United Kingdom and Germany where concurrent FDA-EMA method validation demand exceeds established CRO capacity. A go-to-market angle bundling pharmacokinetic testing with companion diagnostic co-development creates stickier sponsor relationships and higher contract values than transactional sample analysis.
For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical companies spinning off non-core bioanalytical capabilities as they consolidate outsourcing relationships. Long-term viability favors specialized biologics CROs with cell and gene therapy analytical expertise over generalist central laboratory networks facing commoditization pressure. The signal to watch is NMPA inspection standard harmonization with FDA-EMA protocols, which would validate China-based facility investments and trigger acquisition premiums for GLP-compliant domestic operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Inspection History Investment | Documented FDA and EMA inspection records unlock preferred provider status under consolidated procurement arrangements. |
| AI-Enabled Peak Integration Development | Machine learning algorithms for chromatography data processing reduce analyst time while satisfying EU AI Act validation requirements. |
| Cell and Gene Therapy Capability Expansion | Viral vector potency assays and CAR-T pharmacokinetic characterization command premium pricing and create sponsor lock-in. |
| China Domestic Facility Buildout | NMPA regulatory reform alignment with international GLP standards positions operators for indigenous biopharma demand growth. |
| Companion Diagnostic Co-Development Bundling | Pharmacokinetic testing integrated with biomarker assay development generates higher contract values and multi-year sponsor commitments. |
Research Approach
A spread of perspectives from bioanalytical laboratory directors, regulatory affairs leads at biopharmaceutical sponsors, CRO procurement managers, and cell therapy development executives converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA guidance documents, EMA bioanalytical method validation standards, ClinicalTrials.gov protocol registries, and SEC filings from publicly traded contract research organizations. Bottom-up triangulation across service line volumes and top-down cross-checks against sponsor R&D expenditure patterns anchored the market sizing framework.
Segmentation dimensions modeled include technology platform, therapeutic application, development stage, and geographic regulatory cluster across the projection horizon. CAGRs were derived from sponsor pipeline analysis and outsourcing penetration assumptions, with cell and gene therapy pipeline expansion and biosimilar comparability study volumes serving as key demand-side inputs. The analytical framework incorporated instrument capacity constraints and qualified scientific talent availability as supply-side moderators.
Decision-makers should treat outputs as directional under assumptions of sustained biopharmaceutical R&D investment and stable regulatory inspection standards; material deviation would warrant model refresh. Revision becomes warranted when FDA immunogenicity guidance updates or NMPA inspection harmonization timelines cross thresholds that materially alter sponsor outsourcing behavior or CRO competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global GMP Testing Service Market
Testing Services
Biomarker Testing Services Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Drug Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Rapid Test Cards Market
Testing Services
Global Bioburden Testing Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Zika Virus Testing Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Cholesterol Test Market