
 Global Emollient Esters Market | 2026-2036
Global Emollient Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emollient Esters Market Foresight
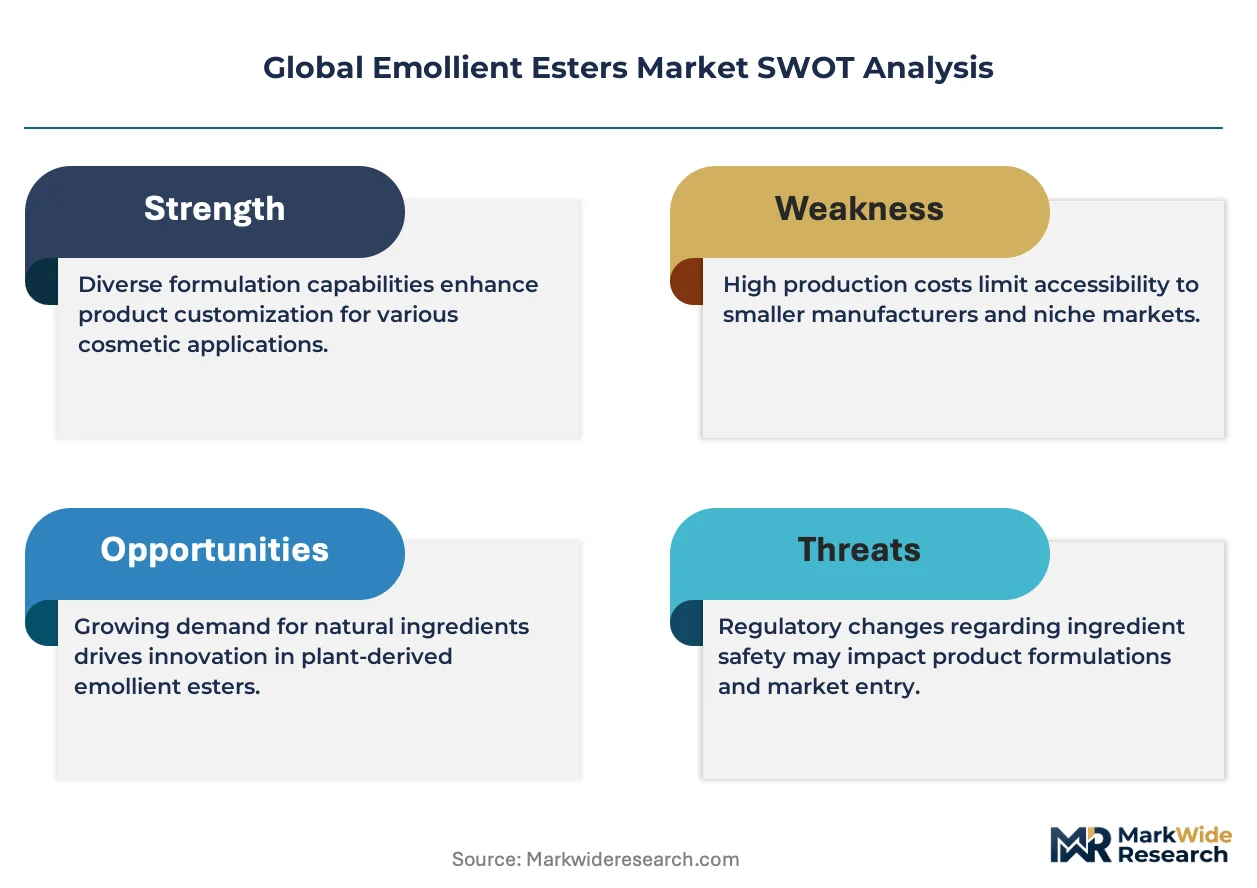
Specialty chemical production in Germany is restructuring as domestic emollient ester capacity shifts toward high-purity grades for regulated cosmetic applications. BASF leverages its integrated Ludwigshafen complex to sustain captive feedstock advantages across glyceryl stearate and alkyl benzoate lines. Croda International Plc anchors its position through lipid technology leadership and backward integration into bio-based feedstocks. Evonik Industries AG competes via specialized ester chemistry for dermatological-grade formulations.
Emollient esters constitute fatty acid esters synthesized through esterification of long-chain alcohols with carboxylic acids, typically exhibiting melting points between 25°C and 60°C and oil solubility parameters critical for skin barrier function. These compounds primarily serve as occlusive agents, emollients, and solvents in topical delivery systems, reducing transepidermal water loss while enhancing spreadability. Glyceryl stearate dominates product type volumes due to its dual emulsification and emollient functionality in cream and lotion matrices. C12-15 alkyl benzoate occupies the fastest-expanding niche, driven by its light skin feel and compatibility with organic sunscreen filters. Skin moisturizers anchor application demand, though makeup primers represent an emerging margin pool as hybrid cosmetic-skincare positioning gains traction among cosmetic brands.
REACH registration requirements in Europe, FDA cosmetic ingredient safety assessments in the United States, and China's GB standards for cosmetic raw materials collectively elevate analytical and documentation burdens for emollient ester suppliers. These frameworks favor manufacturers with dedicated regulatory affairs teams and certified manufacturing facilities, effectively raising barriers for unqualified entrants. Stakeholders must monitor evolving definitions of nanomaterial status for certain ester formulations, as regulatory reclassification could trigger additional testing protocols and restrict market access for non-compliant producers.
Market Dynamics
REACH compliance deadlines and FDA cosmetic ingredient safety assessments are compressing supplier qualification timelines, forcing specialty chemical manufacturers to restructure quality assurance protocols and documentation systems ahead of regulatory enforcement waves.
Growth Catalysts
- Hybrid cosmetic-skincare positioning:Makeup primers incorporating emollient esters for skin barrier function are expanding addressable volume beyond traditional moisturizers.
- REACH registration tiers:ECHA's tonnage-based registration deadlines are accelerating substitution of unregistered commodity esters with compliant specialty grades.
- Organic sunscreen filter compatibility:C12-15 alkyl benzoate's solubility profile for avobenzone and oxybenzone alternatives is pulling demand from conventional emollients.
Market Restraints
- Palm oil and coconut oil feedstock volatility:Fatty acid precursor costs fluctuate with Malaysian and Indonesian export policies, compressing margin predictability for glyceryl stearate producers.
- Ludwigshafen-Rotterdam corridor concentration:European high-purity capacity clusters along the Rhine create geographic vulnerability to logistics disruptions.
- Silicone emollient substitution:Dimethicone and cyclomethicone formulations compete in premium skin feel applications, particularly in Asian color cosmetics.
Strategic Opportunities
- Brazilian ANVISA cosmetic registration pathway:Mercosur harmonization is opening consolidated market access for compliant ester suppliers across South America.
- Dermatological-grade certification:National Eczema Association seals and similar third-party validations command 15-25% price premiums in sensitive skin segments.
- Bio-fermentation feedstock convergence:Microbial lipid platforms are intersecting with traditional oleochemical routes to yield novel branched-chain ester structures.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified toxicologists and REACH dossier preparers command premium compensation, constraining mid-tier supplier expansion.
- Multi-jurisdiction certification timelines:Parallel FDA, ECHA, and NMPA submissions require 18-36 month coordination cycles before commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emollient Esters Market |
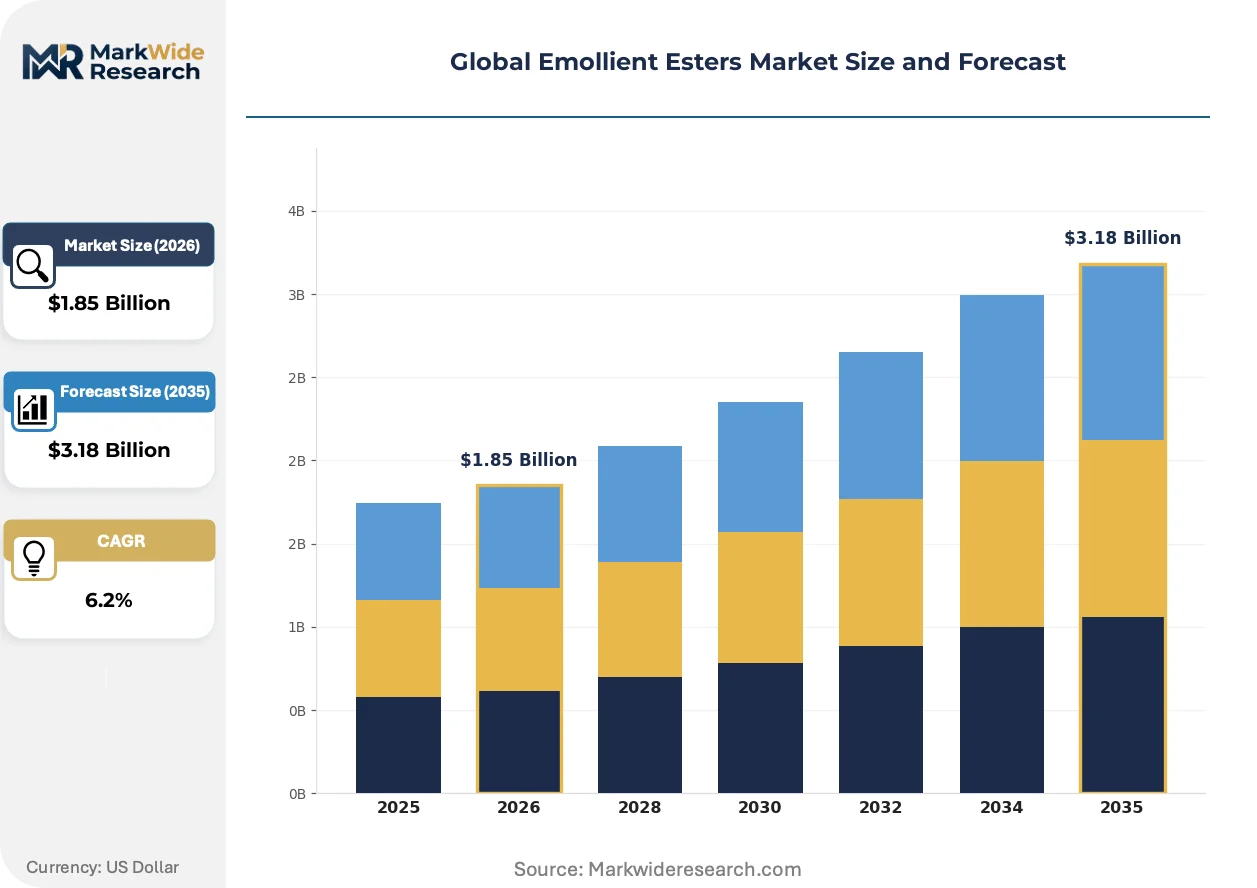
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isopropyl Myristate, Cetyl Palmitate, Octyl Stearate, Glyceryl Stearate, C12-15 Alkyl Benzoate Application: Skin Moisturizers, Hair Conditioners, Lip Balms, Sunscreens, Makeup Primers End User: Personal Care Manufacturers, Cosmetic Brands, Dermatology Centers, Spa & Wellness Centers Form: Liquid, Powder, Paste, Gel, Emulsion |
| Companies Covered | The Lubrizol Corporation, Croda International Plc, Stepan Company, BASF, Evonik Industries AG, Clariant, Eastman Chemical Company, Solvay, Innospec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emollient Esters Market Shifts & Advancements
Process intensification and modular manufacturing architectures are displacing batch esterification across specialty chemical production, while regulatory data requirements and bio-based feedstock verification are reshaping competitive qualification standards.
Continuous flow reactor technology for fatty acid esterification is modularizing production economics for mid-volume specialty grades. German and Swiss contract manufacturers are adopting skid-mounted systems for campaign-based dermatological ester output. This architecture is compressing capital requirements for GMP-compliant capacity expansion.
ECHA's revised guidance on nanomaterial definitions for cosmetic ingredients is forcing analytical protocol upgrades across ester suppliers. The classification uncertainty around certain micro-emulsion formulations is triggering additional particle size distribution studies. Small and mid-size suppliers without in-house electron microscopy capabilities are outsourcing to certified testing laboratories in Germany and the Netherlands.
Direct procurement contracts between personal care brands and ester manufacturers are displacing traditional distributor intermediaries in North American and Western European supply chains. Sephora Clean and similar retailer certification programs are demanding chain-of-custody documentation that distributors cannot economically provide. This disintermediation is most pronounced in California and New York, where clean beauty positioning dominates premium shelf space.
Global Emollient Esters Market Segmentation
Emollient ester procurement decisions hinge on formulation compatibility, regulatory clearance speed, and supply chain traceability. Segmentation reveals where capital deployment concentrates and which niches command premium positioning.
Product Type:
Capital intensity varies sharply across ester chemistries, with continuous flow reactor requirements and GMP certification tiers driving fixed-cost differentials.
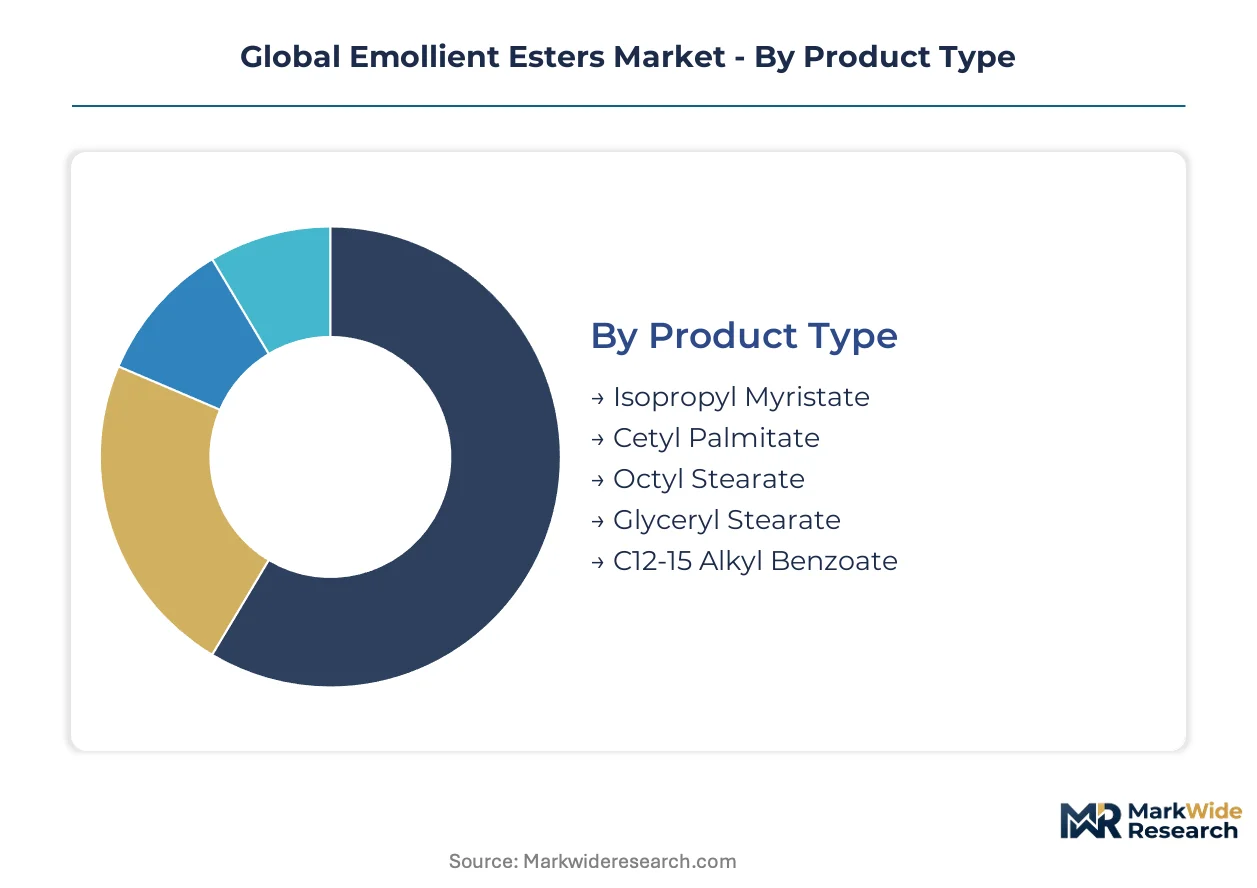
- Glyceryl Stearate:A glycerol ester of stearic acid functioning as both emollient and primary emulsifier in oil-in-water matrices. German specialty chemical clusters at Ludwigshafen and Marl host the densest installed capacity, serving formulators seeking REACH-registered grades for mass-market moisturizers.
- C12-15 Alkyl Benzoate:A benzoate ester blend with solubility parameters optimized for avobenzone and other organic UV filters. Demand concentrates in French and Italian sunscreen manufacturers pivoting toward reef-safe formulations under ECHA scrutiny.
- Isopropyl Myristate:A branched-chain ester prized for rapid skin penetration and dry after-feel.
- Cetyl Palmitate:A saturated wax ester delivering occlusive properties in stick formulations.
- Octyl Stearate:A medium-chain ester balancing spreadability with moderate occlusivity.
Most installed capacity flows through Glyceryl Stearate. Expansion is steepest in C12-15 Alkyl Benzoate.
Application:
Margin profiles diverge across application tiers, with clinical positioning and certification requirements dictating pricing power.
- Skin Moisturizers:The foundational application anchoring volume demand across mass and prestige tiers. German and Dutch formulators prioritize dermatological-grade glyceryl stearate for eczema-prone skin positioning, while US clean beauty brands drive chain-of-custody documentation requirements.
- Makeup Primers:Hybrid cosmetic-skincare formulations requiring esters with dual functionality—immediate sensorial appeal plus sustained barrier support. Korean and Japanese color cosmetics manufacturers are pulling specialized alkyl benzoate grades for silicone-free texture engineering.
- Hair Conditioners:Cationic-compatible ester systems for rinse-off and leave-in treatments.
- Lip Balms:High-melting-point wax esters for stick stability and occlusive endurance.
- Sunscreens:Solubilizing esters for organic filter compatibility and photostability.
Volume leadership sits with Skin Moisturizers. Makeup Primers are climbing the fastest as hybrid positioning gains shelf space.
End User:
Procurement sophistication varies by buyer type, with regulatory affairs capabilities and direct sourcing appetite shaping supplier selection criteria.
- Personal Care Manufacturers:Contract manufacturers and toll producers purchasing esters in bulk for white-label and branded production. German mid-tier specialists are consolidating supplier bases to reduce REACH dossier duplication costs.
- Cosmetic Brands:Direct procurement from ester manufacturers is displacing distributor relationships, particularly among Sephora Clean and similar certified lines requiring full supply chain documentation.
- Dermatology Centers:Clinical-grade ester sourcing for prescription-compounding and physician-dispensed skincare.
- Spa & Wellness Centers:Boutique volume demand for premium sensory positioning in treatment protocols.
Contract volume concentrates with Personal Care Manufacturers. Direct brand procurement is expanding most quickly as clean beauty certification tightens.
Form:
Processing economics and formulation flexibility trade off across physical states, with liquid grades dominating continuous manufacturing compatibility.
- Liquid:Pumpable esters enabling automated dosing and cold-process formulation. Swiss and German contract manufacturers favor liquid alkyl benzoates for modular continuous flow systems serving campaign-based dermatological output.
- Emulsion:Pre-dispersed systems reducing energy requirements and process variability for mid-tier formulators.
- Powder:Solid esters for anhydrous stick and powder cosmetic applications.
- Paste:Semi-solid concentrates requiring controlled temperature handling.
- Gel:Structured systems for specific rheological targeting in premium textures.
Production throughput favors Liquid. Emulsion is gaining share fastest as energy-conscious manufacturing spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's specialty chemical clusters command premium-grade emollient ester output, while the United States drives regulatory complexity through FDA cosmetic ingredient reviews and clean beauty certification demands.
United States
California and New York personal care brands are accelerating direct procurement from ester manufacturers to satisfy Sephora Clean documentation requirements. FDA cosmetic ingredient safety assessments compress supplier qualification timelines to 18-24 months. The Northeast Corridor hosts concentrated contract manufacturing capacity serving prestige skincare formulators.
Germany
Ludwigshafen's integrated chemical complex sustains captive feedstock advantages for glyceryl stearate and alkyl benzoate production. REACH registration deadlines enforce substitution of unregistered commodity esters with compliant specialty grades. The Marl chemical park anchors high-purity capacity expansion for dermatological-grade formulations.
France
Paris-based cosmetic houses are pulling C12-15 alkyl benzoate grades for reef-safe sunscreen reformulations under ECHA scrutiny. ANSM oversees cosmetic ingredient safety alongside EU-wide REACH compliance. The Lyon-Avignon corridor concentrates toll manufacturing capacity for organic UV filter solubilizers.
China
Shanghai and Guangzhou formulators are adopting bio-based emollient esters to align with NMPA cosmetic raw material standards and dual carbon policy targets. GB standards for cosmetic ingredients elevate analytical documentation burdens for imported specialty grades. The Yangtze River Delta clusters mid-tier personal care contract manufacturers.
Brazil
São Paulo cosmetic manufacturers are leveraging ANVISA cosmetic registration pathways opened through Mercosur harmonization for consolidated South American market access. Brazilian regulators are aligning cosmetic ingredient standards with EU REACH benchmarks. The Campinas industrial corridor hosts expanding toll production capacity for Latin American skincare brands.
Global Emollient Esters Market Competitive Landscape
German producers anchor one tier of high-purity specialty ester supply; Anglo-Dutch and Swiss specialists hold differentiated positions in lipid technology and dermatological certification. The vendor base concentrates around integrated petrochemical complexes and independent oleochemical innovators. Three strategic archetypes dominate: integrated chemical conglomerates with captive feedstock, lipid technology specialists with backward bio-based integration, and mid-tier toll manufacturers with modular continuous flow capacity. Competitive moves center on regulatory dossier consolidation and direct brand procurement relationships displacing distributor intermediaries.
Among integrated chemical conglomerates, BASF and Evonik Industries AG exemplify the scale-driven archetype through Ludwigshafen-based production ecosystems. Croda International Plc occupies a distinct position representing lipid technology leadership and bio-based feedstock integration. These three entities anchor the competitive structure through divergent strategic postures: captive verticality versus specialized biotechnology pathways versus hybrid integration models.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Croda International Plc |
| Stepan Company |
| BASF |
| Evonik Industries AG |
| Clariant |
| Eastman Chemical Company |
| Solvay |
| Innospec Inc. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in German chemical parks anchor supply discipline through captive oleochemical processing, translating feedstock control into pricing power that resists spot-market volatility. This ownership pattern reinforces long-term contracting behavior among personal care manufacturers seeking REACH-compliant ester grades.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade glyceryl stearate, pressuring mid-tier European producers. Three-tier pricing structure across dermatological-certified, REACH-registered, and economy grades separates buyers by documentation burden and purity threshold. Cost compression in standard grades intensifies because of Malaysian palm oil export policy swings. Mass-market personal care manufacturers exhibit highest price sensitivity; prestige cosmetic brands absorbing certification premiums show least.
Supply Chain Analysis
Skilled process chemist availability tightens across Ludwigshafen and Marl chemical parks, constraining campaign-based output flexibility for dermatological-grade esters. Supply concentrates in Germany, France, and China, with German clusters commanding high-purity capacity and Chinese sites scaling bio-based fermentation routes. Feedstock chains draw from Malaysian palm oil, Indonesian coconut oil, and emerging microbial lipid platforms. Single-source vulnerability runs through the Rotterdam-Ludwigshafen barge corridor. Distribution runs through direct manufacturer-brand contracts displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Emollient Esters Market reads as a late-cycle quality story, with procurement shifting toward dermatological-certified grades that command sustained premium positioning over commodity alternatives.
For Market Incumbents: Extend regulatory dossier consolidation across REACH, FDA, and NMPA filings to compress qualification timelines for multinational cosmetic brands. Deepen captive feedstock integration into bio-based oleochemical routes before microbial lipid platforms achieve cost parity. Silicone emollient substitution in Asian color cosmetics represents the pressing substitution threat; counter via texture-engineering partnerships with Korean formulators. For New Entrants and Emerging Players: Launch via toll manufacturing partnerships with Swiss-German contract manufacturers possessing modular continuous flow capacity and existing GMP certification. Brazilian ANVISA registration pathways offer the most penetrable geography, leveraging Mercosur harmonization for consolidated South American access without parallel multi-jurisdiction submissions. Target makeup primer applications, where hybrid cosmetic-skincare positioning creates formulation complexity incumbents serve reluctantly. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier toll manufacturers with modular capacity and dormant regulatory dossiers awaiting activation. Five-to-ten year viability hinges on successful navigation of ECHA nanomaterial reclassification risk and bio-fermentation feedstock convergence. Watch for National Eczema Association certification velocity as inflection signal—accelerated seal acquisition indicates pricing power capture in sensitive skin segments.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Consolidation | Compresses 18-36 month multi-jurisdiction timelines into unified regulatory submissions for ECHA, FDA, and NMPA. |
| Backward Integration into Bio-Based Feedstocks | Secures supply independence from Malaysian palm oil volatility while aligning with EU Green Deal cosmetic ingredient targets. |
| Modular Continuous Flow Capacity Expansion | Enables campaign-based dermatological ester output with compressed capital requirements for GMP-compliant production. |
| Direct Brand Procurement Relationships | Displaces distributor intermediaries to capture Sephora Clean certification documentation margins in California and New York. |
| Dermatological-Grade Certification Investment | Commands 15-25% price premiums through National Eczema Association seals in sensitive skin market segments. |
Research Methodology
Direct dialogue with specialty chemical plant managers, personal care procurement leads at multinational cosmetic brands, REACH dossier preparers, and Swiss-German toll manufacturing operators grounded qualitative findings. Secondary validation drew from ECHA registration databases, FDA cosmetic ingredient safety assessments, customs trade data for fatty acid ester flows, and SEC filings of listed specialty chemical producers. Bottom-up capacity estimates and top-down demand triangulation cross-checked segment outputs.
Segment-level value projections across the analysis window reflect modeled interactions between grade tier, end-use application, and regional regulatory cluster. The framework incorporated ester chemistry type, dermatological certification status, and bio-based feedstock share as core segmentation dimensions. CAGRs derived from regression against historical tonnage flows and forward capacity announcements, with palm oil price volatility and REACH enforcement intensity as key sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA nanomaterial reclassification or sustained Indonesian export restrictions. Projections assume continued clean beauty certification expansion and stable Mercosur regulatory harmonization. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Global White Oil Market
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Stearic Acid Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Alpha Olefin Sulfonates Market