
 Triisostearyl Citrate Market | 2026-2036
Triisostearyl Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Triisostearyl Citrate Market Analytics
REACH is recalibrating the cost-of-entry calculus for specialty ester suppliers serving European cosmetic brands. Croda International leverages its integrated oleochemistry platform to sustain premium positioning in skin conditioning agents. BASF anchors its competitive stance through backward integration into renewable feedstocks for citrate ester production. Jeen International Corporation differentiates via specialized emulsifier grades tailored for clean-label cosmetic formulations.
Triisostearyl citrate functions as a branched-chain fatty acid ester synthesized through citric acid esterification with isostearyl alcohol, yielding a light, non-greasy emollient with a melting point near room temperature. The compound serves primarily as a skin conditioning agent and emollient in cosmetic and personal care formulations, delivering spreadability and pigment wetting in color cosmetics. Emulsifiers and skin conditioning agents together capture the dominant share of product type demand, with thickening agents representing the fastest-growing category as silicone-free formulations gain traction. Cosmetics applications lead volume consumption, while pharmaceutical-grade specifications command the deepest margin pools due to purity certification requirements.
EMA cosmetic ingredient guidelines, REACH substance registration thresholds, and FDA cosmetic labeling rules collectively shape product standards and market access for triisostearyl citrate suppliers. ECHA's evolving restrictions on persistent organic pollutants are pushing formulators toward biodegradable ester alternatives, directly benefiting citrate-based chemistry. Stakeholders must monitor regulatory divergence between EU hazard classification protocols and emerging state-level cosmetic disclosure laws in the US, as compliance fragmentation will determine which suppliers retain cross-border formulation approval.
Market Dynamics
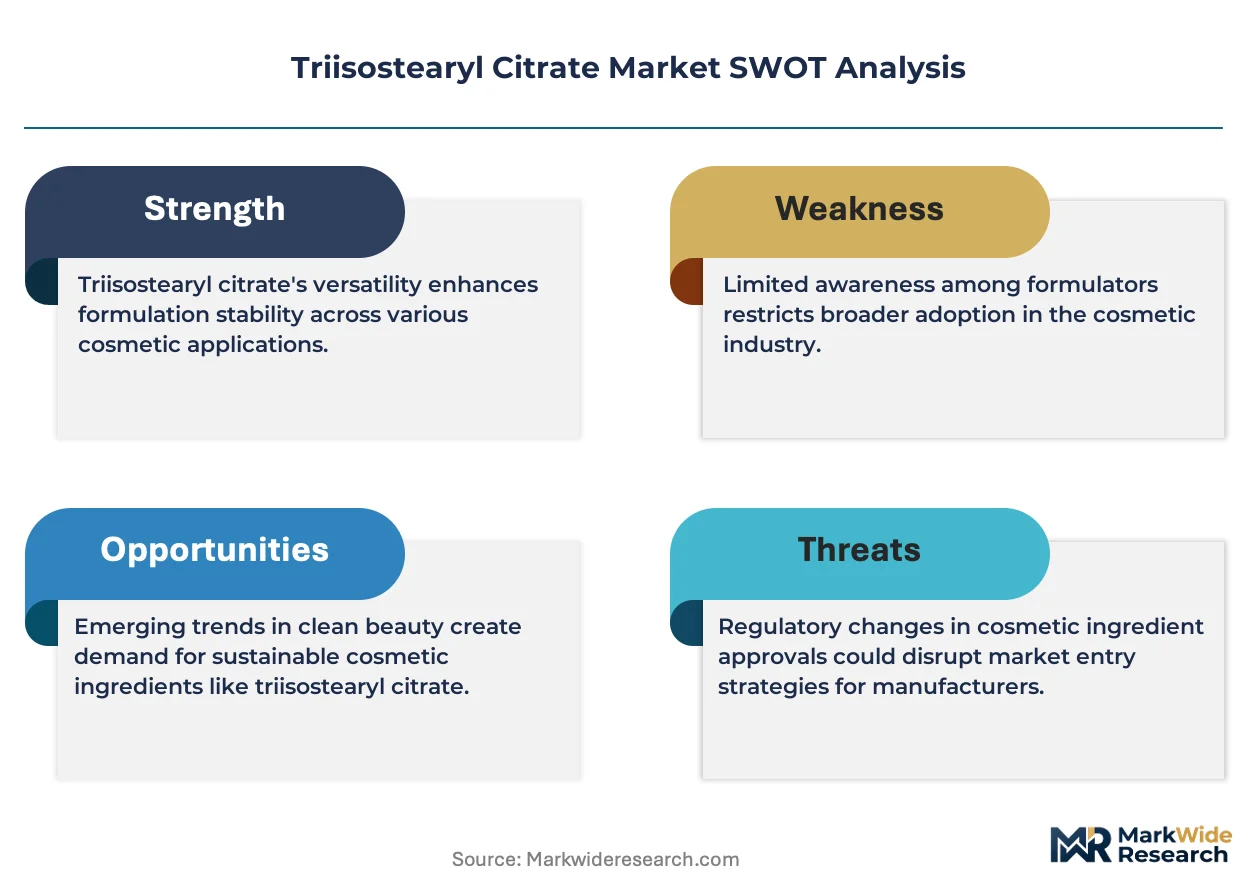
REACH substance registration thresholds and ECHA's evolving restrictions on persistent organic pollutants are recalibrating the cost-of-entry calculus for specialty ester suppliers, forcing formulators toward biodegradable citrate-based chemistry over petrochemical alternatives.
Growth Catalysts
- EMA cosmetic ingredient guidelines:European regulatory harmonization elevates demand for plant-derived emollients with full toxicological dossiers, accelerating substitution of synthetic alternatives in color cosmetics formulations.
- China domestic manufacturing scale-up:Chinese esterification capacity expansion serves both local cosmetic brands and export markets, concentrating supply-side investment in Zhejiang and Jiangsu provinces.
- Silicone-free formulation migration:Thickening agent applications in skin conditioning products displace cyclomethicone and dimethicone, opening volume channels for triisostearyl citrate as a spreadability enhancer.
Market Restraints
- Isostearyl alcohol feedstock volatility:Branched-chain fatty alcohol pricing fluctuates with palm kernel and coconut oil commodity cycles, compressing margin stability for ester manufacturers without captive oleochemical supply.
- REACH registration cost burden:Substance registration thresholds above one tonne annually impose toxicological testing expenditures that disadvantage smaller ester producers lacking integrated regulatory affairs capabilities.
- Petrochemical ester price competition:Synthetic emollients derived from polyethylene glycol and mineral oil maintain cost advantages in mass-market personal care, limiting citrate ester penetration in economy-tier formulations.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP monograph compliance for excipient applications commands premium pricing pools, with dermatological and transdermal delivery systems representing underpenetrated end-uses.
- EU Green Deal bio-based mandates:Renewable content thresholds in public procurement and corporate sustainability reporting create preferential market access for plant-derived emollients with verified carbon footprints.
- Direct-to-brand distribution platforms:Indie cosmetic formulators and clean-label startups bypass traditional distributor networks through specialized chemical marketplaces, enabling margin capture by specialty ester suppliers.
Industry Challenges
- Esterification process optimization:Achieving consistent color specifications and low acid values requires precise control of catalyst loading and reaction temperature profiles, demanding skilled chemical engineering talent scarce in emerging manufacturing regions.
- Multi-jurisdiction compliance synchronization:Divergence between EU hazard classification protocols and emerging state-level cosmetic disclosure laws in California and New York fragments formulation approval workflows, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triisostearyl Citrate Market |
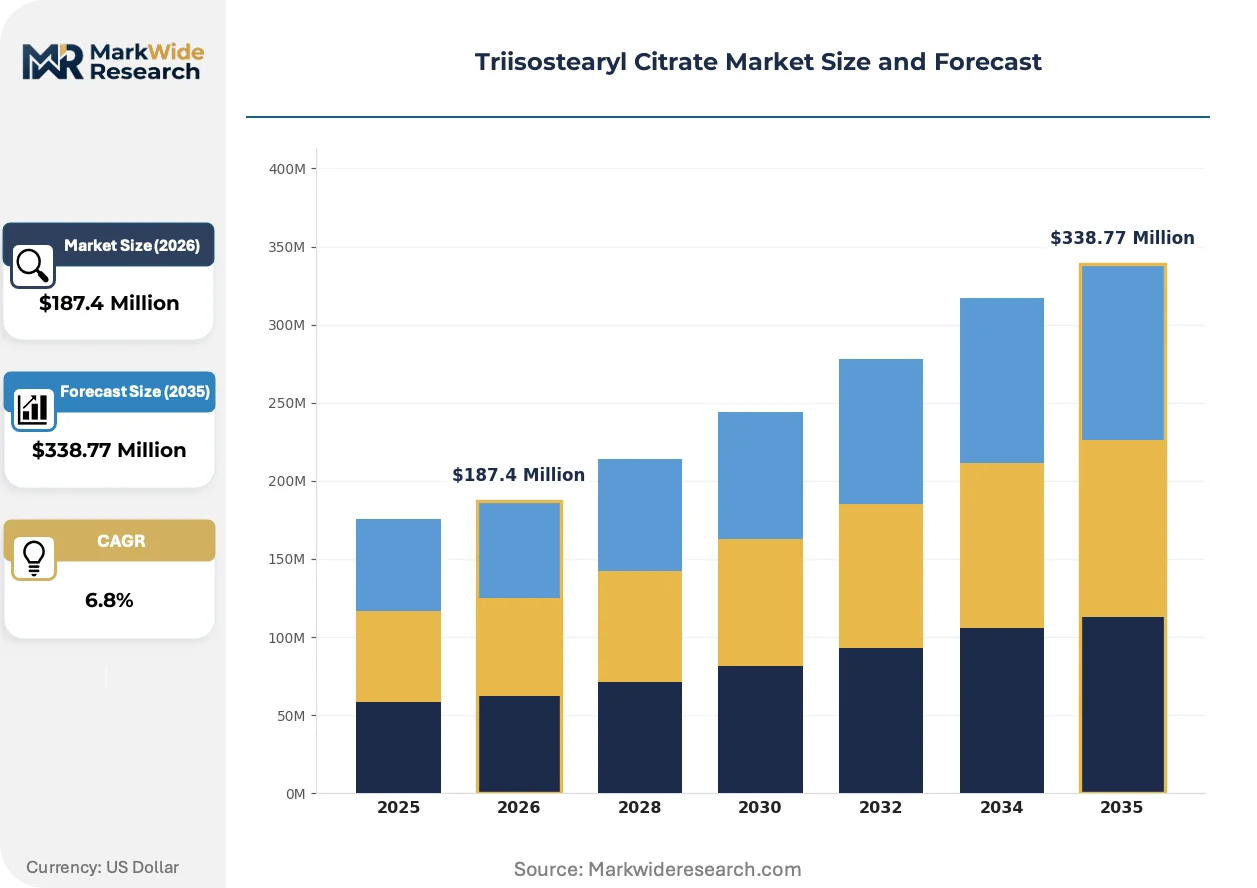
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Skin Conditioning Agents, Thickening Agents, Solubilizers Application: Cosmetics, Personal Care, Pharmaceuticals, Industrial End User: Manufacturers, Retailers, Distributors, Laboratories Packaging Type: Bulk Containers, Sachets, Bottles, Drums |
| Companies Covered | The Lubrizol Corporation, Alzo International, Phoenix Chemical, Jeen International Corporation, Guangzhou Mannerchem, Oleon, Taizhou Chemical, Croda International, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triisostearyl Citrate Market Evolving Landscape
Biotechnology-enabled feedstock diversification and regulatory-driven formulation chemistry are converging to reshape emollient ester production, with sustainability verification becoming a non-negotiable specification in premium personal care procurement.
Enzymatic esterification using immobilized lipase biocatalysts is integrating into commercial triisostearyl citrate manufacturing, replacing traditional acid-catalyzed processes. Specialty chemical producers in Germany and Switzerland adopt this technology to achieve milder reaction conditions and reduced byproduct formation. The structural consequence is enabling pharmaceutical-grade purity specifications without multiple purification stages, compressing capital intensity for high-margin segment entry.
REACH restriction proposals on microplastics and persistent organic pollutants are tightening allowable specifications for cosmetic ingredients with environmental persistence. ECHA's 2023-2027 rolling action plan specifically targets synthetic polymers and non-biodegradable esters used in rinse-off applications. Color cosmetics and sun care formulations in Northern Europe face the most immediate compliance pressure, with formulators accelerating citrate ester substitution timelines.
Clean-label procurement criteria now mandate full supply chain transparency from feedstock cultivation through final esterification. Indie beauty brands and B-Corp certified manufacturers in France, the United Kingdom, and California reject emollients lacking mass-balance certification or segregated sustainable palm documentation. This behavioral shift is most visible in premium skin care, where ingredient storytelling drives consumer price tolerance and brand loyalty metrics.
Triisostearyl Citrate Market Segmentation
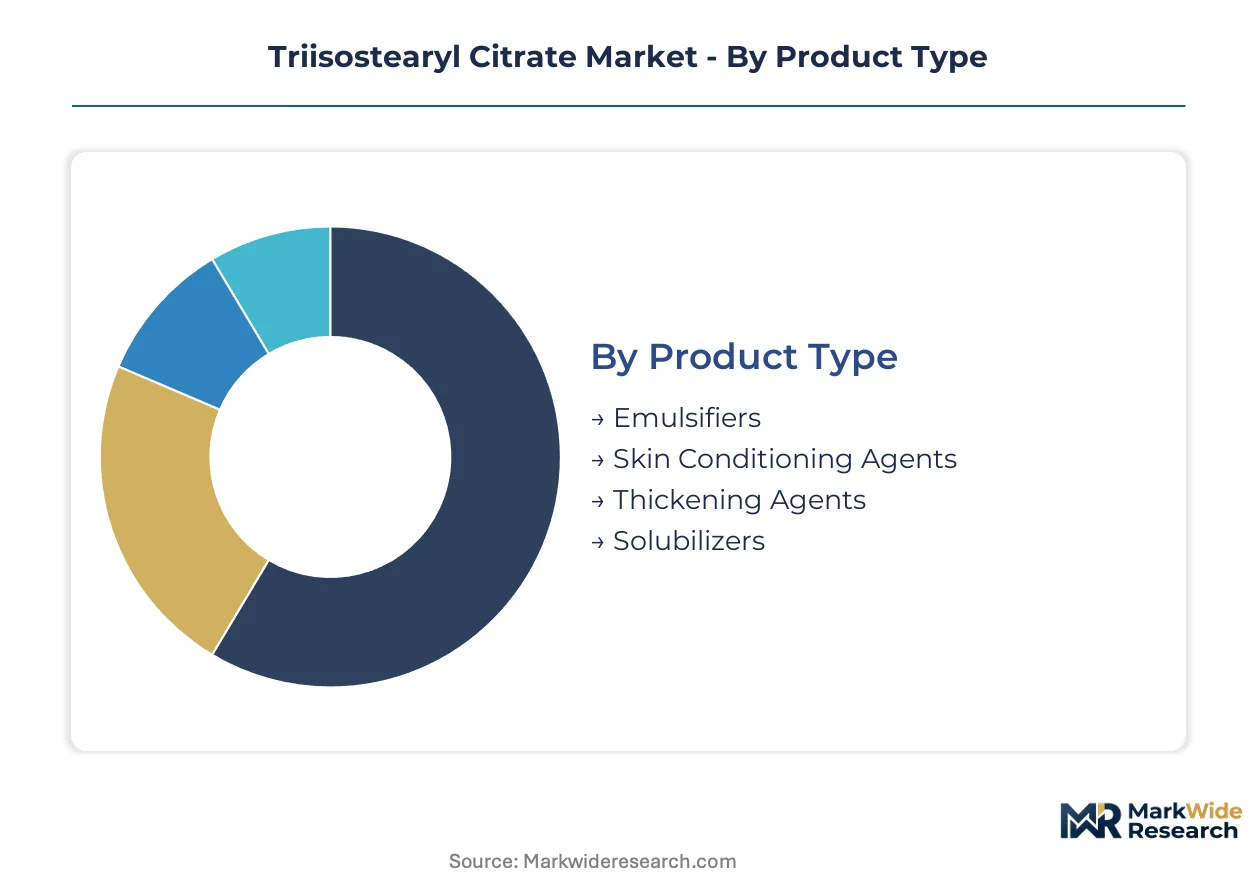
Segmentation in the triisostearyl citrate market reflects divergent certification burdens and margin structures across functional grades. EMA cosmetic ingredient guidelines, USP pharmaceutical monographs, and REACH registration thresholds create tiered compliance costs that reshape supplier positioning and customer targeting strategies.
Product Type:
Certification requirements vary sharply by functional classification, with pharmaceutical-grade emulsifiers demanding USP and EP compliance while industrial-grade solubilizers operate under less stringent purity protocols.
- Emulsifiers:Stabilize oil-water interfaces in color cosmetics and sun care formulations through amphiphilic molecular architecture. Demand concentrates in premium skin care brands seeking silicone-free alternatives, driven by ECHA microplastic restrictions on synthetic polymer emulsifiers.
- Skin Conditioning Agents:Deliver occlusive and emollient properties through branched-chain fatty acid ester structure. Formulators in France and California prioritize these grades for clean-label positioning, constrained by mass-balance certification requirements for sustainable palm-derived feedstocks.
- Thickening Agents:Provide viscosity modification without silicone-derived polymers. Fastest adoption in rinse-off applications facing REACH environmental persistence scrutiny.
- Solubilizers:Enable dispersion of hydrophobic actives in aqueous systems. Industrial applications tolerate lower purity specifications, reducing regulatory compliance overhead.
Emulsifiers sit at the top of the volume ranking, with thickening agents climbing the fastest as silicone-free formulation migration accelerates.
Application:
End-use segments stratify by margin potential, with pharmaceutical specifications commanding premium pricing pools against commodity-grade industrial consumption.
- Cosmetics:Color cosmetics and skin care formulations leverage triisostearyl citrate for spreadability and pigment wetting. Zhejiang and Jiangsu province manufacturers supply both domestic Chinese brands and export markets, scaling esterification capacity to capture clean-label procurement growth.
- Personal Care:Hair care and body care applications emphasize biodegradability credentials for rinse-off compliance under ECHA's evolving persistent organic pollutant restrictions.
- Pharmaceuticals:Dermatological and transdermal delivery systems require USP and EP monograph compliance, creating the deepest margin pools through purity certification barriers.
- Industrial:Lubricant and coating applications utilize technical-grade specifications with minimal regulatory documentation, competing primarily on cost against petrochemical ester alternatives.
Cosmetics applications hold the dominant volume position, with pharmaceuticals expanding most quickly as excipient certification requirements deepen supplier differentiation.
End User:
Customer type determines procurement sophistication, with integrated manufacturers pursuing direct supplier relationships while distributor-dependent retailers prioritize formulation flexibility.
- Manufacturers:Cosmetic and pharmaceutical formulators with captive R&D capabilities negotiate long-term supply agreements based on toxicological dossier completeness and carbon footprint verification.
- Retailers:Indie beauty brands and clean-label startups bypass traditional channels through specialized chemical marketplaces, demanding smaller batch sizes with full supply chain transparency documentation.
- Distributors:Regional chemical distributors aggregate demand from mid-tier formulators, managing inventory risk for REACH-registered specialty ester grades.
- Laboratories:Contract research and analytical testing facilities consume reference-grade materials for method development and regulatory submission support.
Manufacturers represent the largest procurement volume, with retailers gaining share fastest through direct-to-brand platform proliferation.
Packaging Type:
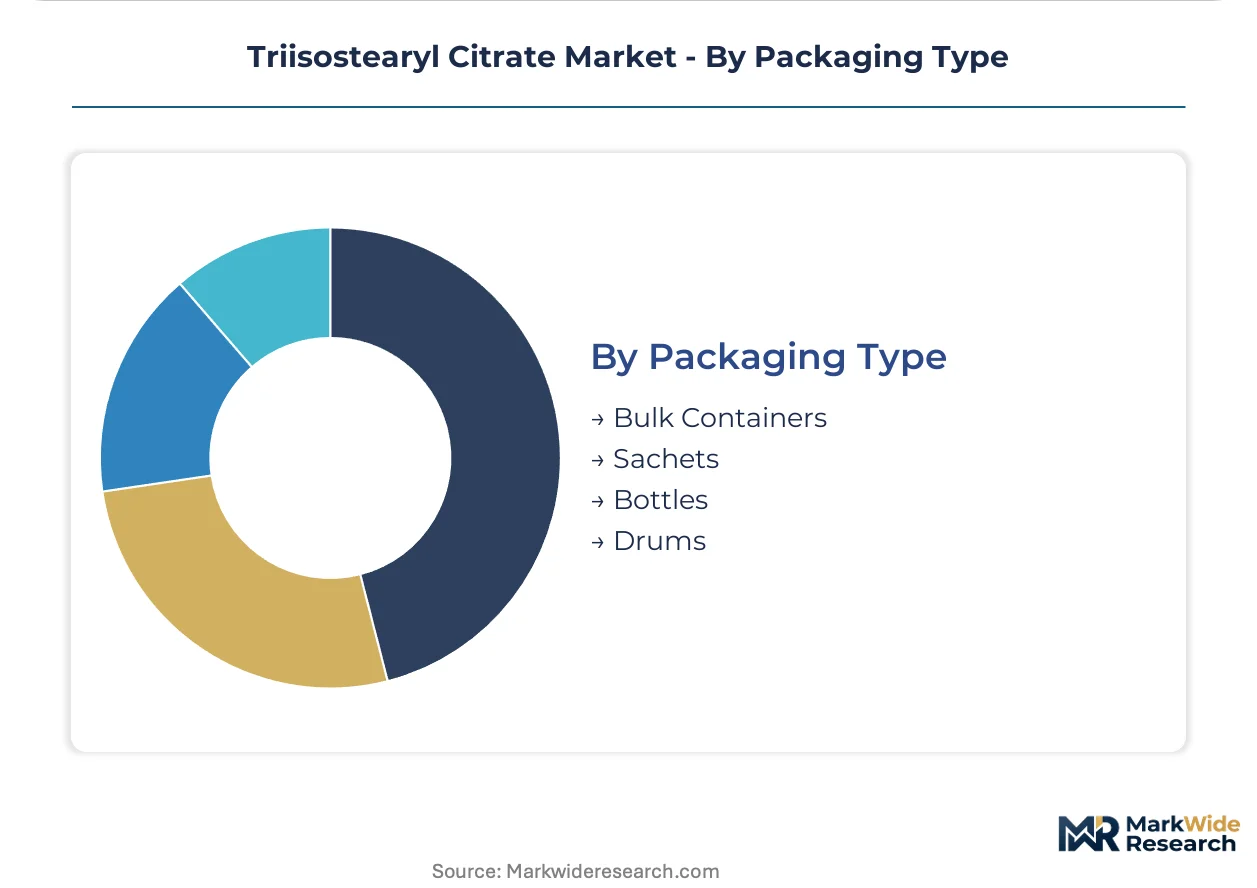
Packaging configuration aligns with customer scale and handling infrastructure, from bulk tanker deliveries for integrated manufacturers to sachet sampling for formulation development.
- Bulk Containers:Intermediate bulk containers and tanker shipments serve high-volume cosmetic manufacturers with dedicated storage and handling capabilities.
- Sachets:Single-use sampling formats support formulation laboratories and indie brand product development cycles with minimal material commitment.
- Bottles:Standard retail and professional-size packaging for mid-tier personal care formulators with moderate throughput requirements.
- Drums:Steel and fiber drums dominate pharmaceutical-grade distribution, ensuring contamination prevention through sealed closure systems.
Drums maintain the highest shipment frequency in value terms, with bulk containers expanding most quickly as Chinese domestic manufacturing scale-up concentrates procurement volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters in Germany's Ruhr Valley and Switzerland's Basel region anchor European specialty ester innovation. Chinese process engineers concentrate in Zhejiang and Jiangsu provinces, driving esterification capacity scale-up.
Germany
Cosmetic formulators in Hamburg and Düsseldorf drive demand for REACH-compliant emollients with full toxicological dossiers. ECHA's evolving restrictions on persistent organic pollutants accelerate substitution of synthetic alternatives. Specialty chemical producers in the Cologne-Leverkusen corridor invest in enzymatic esterification technology to achieve pharmaceutical-grade purity specifications.
China
Domestic cosmetic brands in Shanghai and Hangzhou expand procurement of plant-derived emollients for clean-label positioning. SAMR's tightening cosmetic ingredient disclosure rules elevate demand for biodegradable alternatives over petrochemical esters. Manufacturers in Zhejiang province scale esterification capacity to serve both local brands and export markets across Southeast Asia.
United States
Indie beauty brands in California and New York prioritize supply chain transparency for B-Corp certification compliance. FDA cosmetic labeling rules and emerging state-level disclosure laws in California fragment formulation approval workflows. Formulation laboratories in New Jersey and Illinois develop silicone-free skin conditioning products using citrate-based thickeners.
Switzerland
Pharmaceutical excipient manufacturers in Basel demand USP and EP monograph compliance for dermatological delivery systems. Swissmedic's pharmaceutical-grade certification requirements create premium pricing pools for high-purity ester grades. Biotechnology-enabled producers in the Basel region adopt immobilized lipase biocatalysts for milder reaction conditions.
France
Premium skin care formulators in Paris and Lyon reject emollients lacking mass-balance certification for sustainable palm documentation. ANSM cosmetic ingredient guidelines align with EMA standards to elevate plant-derived emollient specifications. Clean-label startups in the Île-de-France region bypass traditional distributor networks through specialized chemical marketplaces.
Triisostearyl Citrate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the triisostearyl citrate market. The supplier base organizes into three tiers: integrated oleochemistry majors with captive feedstock supply, mid-scale esterification specialists serving regional cosmetic brands, and boutique producers targeting pharmaceutical-grade certification. Strategic moves center on backward integration into renewable feedstocks and enzymatic process technology licensing to compress capital intensity for high-margin segment entry.
Among European integrated oleochemistry platforms, Croda International and BASF exemplify archetypes of feedstock-backward majors with carbon footprint verification capabilities. Jeen International Corporation represents the specialized emulsifier grade tier targeting clean-label cosmetic formulations. Guangzhou Mannerchem and Taizhou Chemical anchor Chinese domestic capacity expansion serving both local brands and export markets.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Alzo International |
| Phoenix Chemical |
| Jeen International Corporation |
| Guangzhou Mannerchem |
| Oleon |
| Taizhou Chemical |
| Croda International |
| BASF |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap esterification specialists in Zhejiang and Jiangsu provinces anchor Chinese supply capacity, enabling disciplined pricing through captive oleochemical processing while European integrated majors leverage carbon footprint verification to sustain premium positioning against commodity-grade imports.
Pricing Analysis
Bundled certification-and-delivery contracts dominate pharmaceutical-grade procurement, while unbundled spot transactions govern industrial solubilizer sales. Three-tier pricing structure across premium, standard, and economy levels separates USP/EP-certified excipients from REACH-registered cosmetic grades and technical specifications. Pricing pressure stems from isostearyl alcohol feedstock volatility tied to palm kernel oil commodity cycles. Mass-market personal care manufacturers exhibit highest price sensitivity, whereas Swiss and German pharmaceutical excipient buyers prioritize purity certification over unit cost.
Supply Chain Analysis
REACH registration and USP monograph qualification gating constrain supplier entry, concentrating pharmaceutical-grade output among Basel-region and Cologne-Leverkusen producers while cosmetic-grade capacity expands across China. Feedstock supply draws from Malaysian and Indonesian palm kernel oil plantations, German biotechnology-enabled biocatalyst providers, and Chinese isostearyl alcohol distillation units. Single-source vulnerability in enzymatic biocatalyst supply threatens pharmaceutical-grade production scaling. Distribution runs through regional chemical distributors for mid-tier formulators and direct-to-brand platforms for indie cosmetic startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through enzymatic process technology adoption that compresses purification stages for pharmaceutical-grade entry, while clean-label procurement premiums widen spreads between certified and uncertified grades.
For Market Incumbents: Lock in feedstock security through backward integration into Malaysian palm kernel supply or long-term offtake agreements with Zhejiang alcohol distillers. Invest in immobilized lipase biocatalyst licensing to defend pharmaceutical-grade positioning against emerging Chinese competitors with conventional acid-catalyzed capacity. For New Entrants and Emerging Players: Enter via pharmaceutical-grade certification white space in dermatological delivery systems, where USP/EP compliance barriers limit incumbent saturation. Target direct-to-brand distribution platforms serving California and French clean-label startups with mass-balance-certified cosmetic grades and full supply chain transparency documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Chinese esterification specialists lacking REACH registration capabilities but possessing expandable Zhejiang capacity. Five-to-ten year viability hinges on regulatory divergence between EU hazard classification and emerging US state-level disclosure laws. Monitor ECHA microplastic restriction implementation timelines as inflection signal for citrate ester substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Technology Licensing | Enables pharmaceutical-grade purity without multiple purification stages, compressing capital intensity for Basel-region producers. |
| Backward Integration into Renewable Feedstocks | Croda and BASF anchor competitive positioning through captive supply of palm-derived isostearyl alcohol with verified carbon footprints. |
| Pharmaceutical-Grade Certification Investment | USP and EP monograph compliance commands deepest margin pools through purity barriers in dermatological delivery systems. |
| Direct-to-Brand Distribution Platform Development | Indie beauty startups in California and France bypass traditional channels, enabling margin capture by specialty ester suppliers. |
| Chinese Domestic Capacity Scale-Up | Zhejiang and Jiangsu manufacturers serve both local cosmetic brands and Southeast Asian export markets. |
Research Methodology
Bottom-up cosmetic and pharmaceutical formulation modeling reconciled against top-down esterification capacity tracking forms the analytical core. Primary interviews with cosmetic R&D directors, pharmaceutical excipient procurement managers, specialty chemical plant engineers, and distributor channel partners were validated against secondary sources including ECHA registration databases, USP monograph publications, SAMR cosmetic ingredient filings, and ACC specialty chemical trade statistics. Triangulation across supply-side capacity announcements and demand-side procurement patterns ensures forecast robustness.
Historical trendline analysis of emollient ester consumption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include certification grade tier, end-use application, packaging format, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating silicone-free formulation migration rates and REACH restriction implementation timelines. Forecast inputs include palm kernel oil price volatility indices and enzymatic biocatalyst adoption curves among European producers.
Inputs from ECHA substance registration databases and USP monograph revision notices were available through the study window; gaps in Chinese provincial environmental compliance disclosures introduce uncertainty bands around domestic capacity expansion timelines. Forecasts reflect assumptions regarding regulatory harmonization between EU and emerging US state-level cosmetic disclosure protocols. A model refresh is warranted upon material change in ECHA persistent organic pollutant restriction scope or SAMR cosmetic ingredient disclosure rule enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Isostearic Acid Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
1-Decene Market
Oleochemicals
Estolides Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Isobutyl Stearate Market