
 Isopropyl Esters Market | 2026-2036
Isopropyl Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Isopropyl Esters Market Foresight
Malaysia is narrowing the supply gap for palm-derived oleochemical feedstocks that underpin isopropyl ester production across Asia. KLK OLEO leverages integrated plantation-to-ester operations that sustain cost advantages in fatty alcohol derivatives. BASF SE anchors European supply through specialized esterification technology at Ludwigshafen. IOI Oleochemicals competes on volume, extending Malaysian capacity into global cosmetic and lubricant channels.
Isopropyl esters comprise fatty acid esters synthesized from isopropanol and long-chain carboxylic acids, typically exhibiting viscosities between 5 and 15 cSt at 40°C and pour points below -10°C for liquid grades. These compounds function primarily as emollients, solvents, and lubricity modifiers in personal care, pharmaceutical, and industrial formulations. Isopropyl myristate dominates cosmetic applications due to its rapid skin penetration and low comedogenic rating, while isopropyl palmitate captures margin pools in premium skincare where oxidative stability commands price premiums. Isopropyl stearate occupies a narrower but defensible position in pharmaceutical ointment bases where crystallinity control determines formulation performance.
REACH registration requirements in Europe mandate full toxicological dossiers for cosmetic-grade esters above one-tonne annual thresholds, elevating compliance costs for importers. FDA oversight through 21 CFR 172.856 and 21 CFR 173.340 governs food-contact and indirect additive uses, restricting residual alcohol specifications. The EPA's Safer Choice program is reshaping surfactant and solvent selections in institutional cleaning, creating qualification pathways for bio-based ester alternatives. Stakeholders must monitor evolving biopreferred procurement standards and oleochemical carbon accounting methodologies to secure position in contract manufacturing for multinational personal care brands.
Market Dynamics
Pharmaceutical-grade purity mandates from FDA and ECHA are compressing supplier margins while simultaneously locking qualified producers into long-term contract positions with multinational formulators.
Growth Catalysts
- REACH registration thresholds:One-tonne annual volume triggers for cosmetic-grade esters are consolidating the European supplier base around compliant producers, reducing price competition for qualified entrants.
- Southeast Asia cosmetics expansion:Emollient procurement from personal care manufacturers in Indonesia, Thailand, and Vietnam is accelerating demand for isopropyl myristate in skin-penetration formulations.
- Indian oleochemical scaling:Domestic palm kernel and coconut oil processing capacity is expanding to serve regional pharmaceutical and personal care formulation industries with reduced import dependency.
Market Restraints
- Feedstock concentration:Malaysian and Indonesian palm oil supply chains dominate fatty acid precursors, exposing ester producers to weather-driven oleochemical price volatility.
- Residual alcohol specifications:FDA 21 CFR 172.856 and 173.340 restrictions on isopropanol carryover in food-contact applications limit process efficiency and elevate purification costs.
- Ester substitution pressure:Caprylic/capric triglycerides and squalane alternatives are capturing share in premium cosmetic segments where oxidative stability and natural positioning command buyer preference.
Strategic Opportunities
- EPA Safer Choice qualification:Bio-based ester pathways into institutional cleaning and industrial solvent applications are opening as the program reshapes surfactant procurement standards.
- Carbon accounting methodologies:Oleochemical lifecycle assessment protocols are emerging as contract qualification criteria for multinational personal care brands seeking scope 3 emissions reductions.
- Pharmaceutical ointment bases:Isopropyl stearate applications in crystallinity-controlled formulations represent underpenetrated demand within topical drug delivery systems.
Industry Challenges
- Toxicological dossier compilation:REACH full substance registrations demand specialized regulatory affairs capabilities that mid-scale ester producers struggle to staff.
- Esterification reactor capex:Pharmaceutical-grade continuous processing equipment requires capital deployment that stretches balance sheets for non-integrated compounders.
- Legacy batch process retrofitting:Converting existing fatty ester plants to meet FDA process analytical technology standards involves extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isopropyl Esters Market |
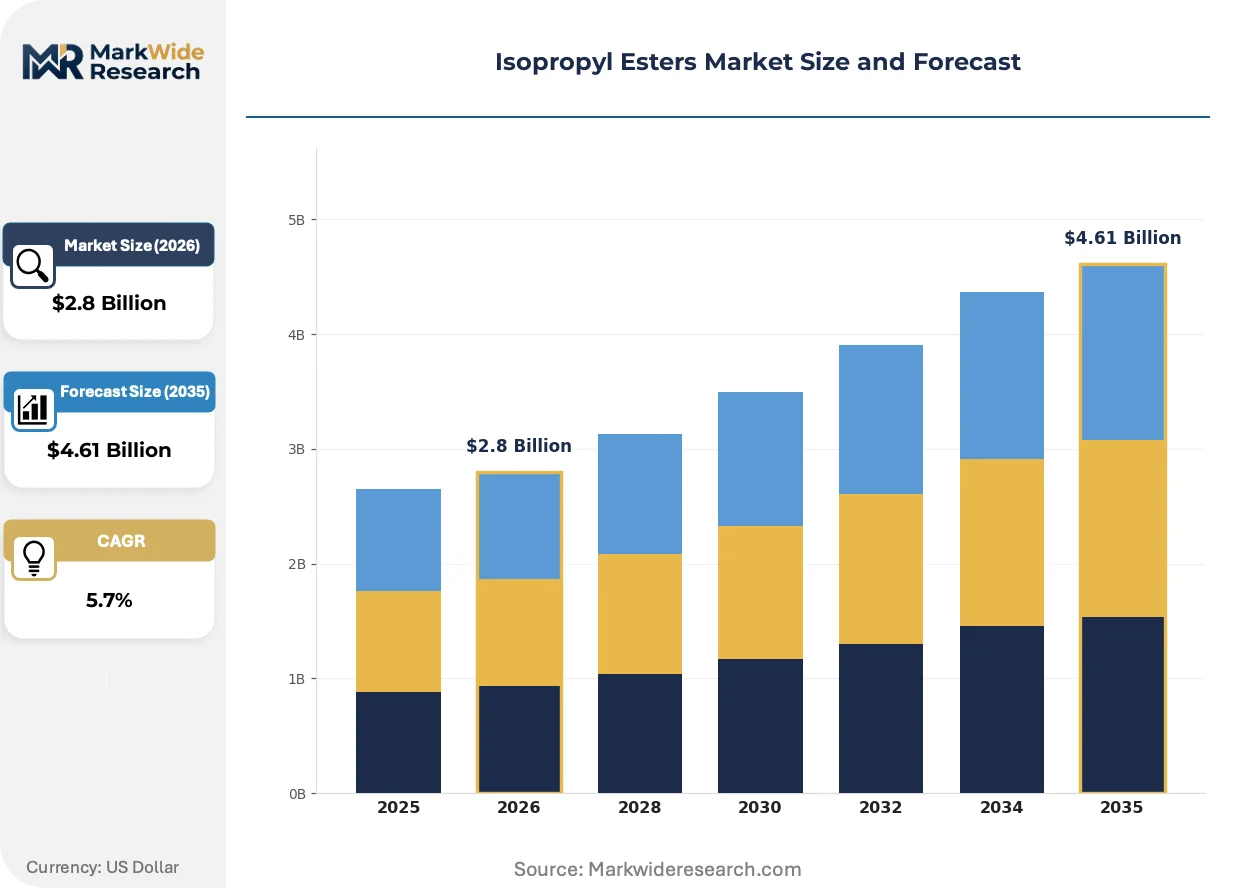
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isopropyl Myristate, Isopropyl Palmitate, Isopropyl Stearate, Isopropyl Oleate End Use Industry: Cosmetics, Pharmaceuticals, Food & Beverage, Textiles Form: Liquid, Powder, Granule, Paste Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Oleon NV, KLK OLEO, BASF SE, Musim Mas, IOI Oleochemicals, Croda International Plc, Stepan Company, Wilmar International, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isopropyl Esters Market Shifts & Advancements
Process intensification and regulatory data requirements are converging to reshape how isopropyl esters are synthesized, qualified, and supplied to formulation houses across personal care and pharmaceutical end uses.
Enzymatic esterification is hybridizing with conventional acid-catalyzed processes in pilot-scale installations. Specialty chemical producers in Germany and Switzerland are adopting lipase-mediated routes to reduce energy inputs and enable milder operating conditions for heat-sensitive fatty acid feeds. This technology is hybridizing process economics by lowering downstream purification burdens while simultaneously complicating scale-up validation for pharmaceutical-grade output.
ECHA's expanding REACH authorization requirements for CMR-classified substances are tightening substance volume tracking across cosmetic supply chains. Importers of isopropyl esters above one-tonne thresholds now face elevated costs for full toxicological dossiers and substance identity testing. European formulators are responding by consolidating supplier panels around registered domestic producers with established IUCLID-compliant data packages.
Specification-driven procurement is compressing supplier qualification cycles for multinational personal care brands. Buyers are unbundling technical service from material supply, demanding standalone regulatory documentation packages that accelerate internal formulation approvals. This pattern is most visible in contract manufacturing relationships serving US and European markets, where formulation lock-in periods now extend across multi-year supply agreements.
Isopropyl Esters Market Segmentation
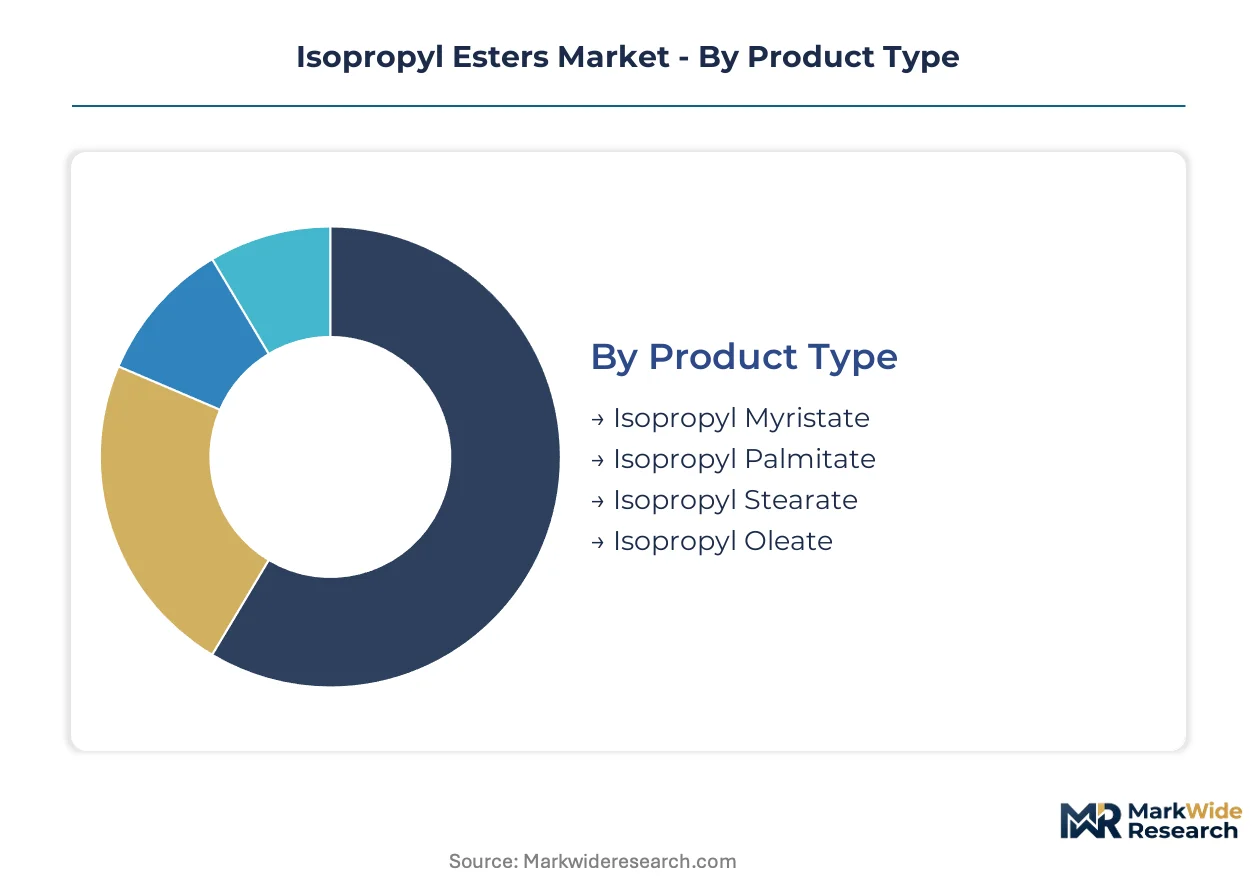
Segmentation in isopropyl esters reveals how formulation requirements split procurement patterns across personal care, pharmaceutical, and industrial channels. Technical specifications for viscosity, pour point, and residual alcohol content create distinct qualification barriers that reshape supplier-customer relationships.
Product Type:
After-sales service intensity varies sharply across ester chemistries, with pharmaceutical-grade isopropyl stearate demanding batch-specific certificates of analysis and regulatory documentation support that cosmetic-grade alternatives rarely require.
- Isopropyl Myristate:A C14 fatty acid ester with viscosity near 7 cSt at 40°C and exceptional skin penetration characteristics. Demand concentrates in Southeast Asian cosmetic manufacturing, where Indonesian and Thai formulators specify this emollient for rapid-absorption skincare products facing humid climate performance requirements.
- Isopropyl Palmitate:The C16 saturated ester offers superior oxidative stability compared to unsaturated alternatives. Premium skincare brands in Germany and Switzerland specify this grade for antioxidant-sensitive formulations, paying stability premiums that sustain margin pools above standard cosmetic grades.
- Isopropyl Stearate:Pharmaceutical ointment bases requiring crystallinity control drive specification.
- Isopropyl Oleate:Industrial lubricant and textile softener applications dominate offtake.
By volume, isopropyl myristate leads. By growth pace, isopropyl palmitate is ahead.
End Use Industry:
Cost tier stratification separates commodity industrial applications from premium pharmaceutical and cosmetic segments, with FDA and ECHA compliance costs creating pricing cliffs between qualified and unqualified supply.
- Cosmetics:Emollient and solvent functions in skincare, haircare, and color cosmetic formulations. Procurement from multinational personal care brands now requires standalone regulatory documentation packages that accelerate internal formulation approvals, consolidating supplier panels around registered producers with IUCLID-compliant REACH dossiers.
- Pharmaceuticals:Ointment bases, topical drug delivery vehicles, and excipient applications. FDA 21 CFR 172.856 and 173.340 residual alcohol restrictions compress process efficiency and elevate purification costs, locking qualified producers into long-term contract positions with multinational formulators.
- Food & Beverage:Limited food-contact applications under strict residual specifications.
- Textiles:Fiber lubricants and softening agents in yarn processing.
Cosmetics generates the largest absolute volume. Pharmaceuticals delivers the steepest expansion trajectory.
Form:
Application requirements dictate physical state selection, with liquid grades dominating continuous-process manufacturing and solid forms serving batch-compounding operations.
- Liquid:Dominant form for cosmetic and pharmaceutical formulations, with viscosities between 5 and 15 cSt at 40°C and pour points below -10°C enabling pumpable handling in automated production lines. Malaysian integrated producers leverage liquid bulk logistics for cost-advantaged supply into regional personal care manufacturing.
- Powder:Solid dosage form applications and dry blend compatibility requirements.
- Granule:Controlled-release pharmaceutical and specialty industrial applications.
- Paste:High-viscosity ointment bases and topical delivery systems.
Liquid forms command volume leadership. Paste formulations are climbing the fastest on pharmaceutical ointment demand.
Distribution Channel:
Customer type splits procurement behavior, with multinational formulators demanding direct technical service relationships while regional compounders accept distributor-mediated supply.
- Online:Emerging channel for sample procurement and small-volume technical grade orders.
- Retail:Limited to specialty chemical boutiques and reagent suppliers.
- Wholesalers:Volume aggregation for mid-scale cosmetic and textile compounders.
- Distributors:Technical service bundling for pharmaceutical and premium cosmetic segments, with specification-driven procurement compressing qualification cycles as buyers unbundle regulatory documentation from material supply.
Distributors handle the largest volume flows. Online channels are gaining share fastest on sample-to-production scaling workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH registration requirements anchor European demand qualification, while FDA oversight governs US pharmaceutical-grade specifications. Indian domestic oleochemical capacity is scaling to serve regional formulation industries.
United States
Pharmaceutical ointment bases and topical drug delivery systems drive specification-heavy procurement from New Jersey and Pennsylvania formulators. FDA 21 CFR 172.856 residual alcohol restrictions compress process efficiency for domestic compounders. The Greater Philadelphia cluster hosts contract manufacturing organizations locking qualified ester suppliers into multi-year supply agreements.
Germany
Premium skincare brands in Hamburg and Cologne specify isopropyl palmitate for oxidative stability in antioxidant-sensitive formulations. ECHA's expanding REACH authorization requirements for CMR-classified substances tighten substance volume tracking across cosmetic supply chains. The Ludwigshafen chemical complex anchors European supply through specialized esterification technology operations.
India
Domestic palm kernel and coconut oil processing capacity in Maharashtra and Gujarat is expanding to serve regional pharmaceutical and personal care industries. CDSCO pharmaceutical-grade purity mandates compress supplier margins while locking qualified producers into contract positions. The Mumbai-Pune industrial corridor concentrates formulation manufacturing for domestic and export markets.
Malaysia
Integrated plantation-to-ester operations sustain cost advantages in fatty alcohol derivatives for export-oriented production. The country's national standards body enforces quality specifications for oleochemical exports to European and US markets. The Klang Valley cluster houses integrated producers extending Malaysian capacity into global cosmetic and lubricant channels.
Indonesia
Personal care manufacturers in Jakarta and Surabaya are accelerating procurement of isopropyl myristate for rapid-absorption skincare products facing humid climate performance requirements. The national food and drug regulator tightens import documentation for cosmetic-grade raw materials. The Batam free trade zone facilitates re-export processing for regional Southeast Asian markets.
Isopropyl Esters Market Competitive Landscape
Capability concentration sits with integrated oleochemical majors possessing plantation-to-ester operations; scale advantage sits with diversified chemical conglomerates leveraging specialized esterification technology. The supplier base stratifies around three archetypes: integrated palm oil processors with captive fatty acid supply, European specialty chemical houses with REACH-registered dossiers, and regional compounders serving price-sensitive industrial segments. Dominant competitive moves include backward integration into fatty alcohol production and qualification for EPA Safer Choice bio-based procurement pathways.
Within the integrated processor tier, KLK OLEO and IOI Oleochemicals exemplify Malaysian producers leveraging plantation control for feedstock cost positioning. BASF SE anchors the European specialty tier through Ludwigshafen-based operations. Among diversified conglomerates, Wilmar International occupies a position spanning plantation assets through downstream oleochemical distribution.
| Leading Market Players |
|---|
| Oleon NV |
| KLK OLEO |
| BASF SE |
| Musim Mas |
| IOI Oleochemicals |
| Croda International Plc |
| Stepan Company |
| Wilmar International |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Malaysian palm oil price volatility determines both the spread between pharmaceutical and cosmetic grade pricing tiers and the geographic clustering of integrated esterification capacity. Feedstock concentration in Southeast Asian oleochemical corridors compresses margins for non-integrated compounders while rewarding plantation-linked producers with captive fatty acid supply.
Pricing Analysis
Price spreads between German and Malaysian supply origins exceed those within any single production corridor. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade levels segments buyers by certification burden and residual alcohol specifications. Cost compression in standard cosmetic grades is intensifying because Indonesian and Thai formulators are consolidating procurement volumes around qualified regional suppliers. Contract manufacturers serving FDA-regulated applications exhibit the lowest price sensitivity due to formulation lock-in periods, while industrial textile compounders drive spot-market negotiations.
Supply Chain Analysis
Extended payment terms from multinational personal care brands are forcing working capital restructuring among mid-scale Malaysian compounders. Supply concentrates in Malaysia, Indonesia, and India, with German and Belgian facilities serving REACH-registered European demand. Production draws from palm kernel oil, coconut oil derivatives, and isopropanol feedstocks. Single-source vulnerability in Malaysian oleochemical precursors exposes downstream ester producers to El Niño-driven crop yield fluctuations. Distribution runs through integrated plantation-to-ester majors for bulk cosmetic supply and specialized distributors for pharmaceutical-grade documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory documentation services now generate recurring revenue streams that outpace base chemical sales growth, as REACH dossier maintenance and FDA certificate of analysis support become multi-year contractual obligations.
For Market Incumbents: Harden backward integration into fatty alcohol production to secure margin position against IOI Oleochemicals and KLK OLEO plantation control. Invest in continuous pharmaceutical-grade reactor capacity at Ludwigshafen or comparable European hubs to lock ECHA-registered supply relationships. Prioritize EPA Safer Choice qualification to capture institutional cleaning procurement shifts. For New Entrants and Emerging Players: Pursue enzymatic esterification pilot partnerships with German or Swiss specialty houses to differentiate on energy intensity and heat-sensitive feedstock handling. Target Indian domestic pharmaceutical formulation demand where CDSCO compliance costs have thinned the qualified supplier base. Lead with standalone regulatory documentation packages that accelerate multinational formulator approval cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated oleochemical majors with captive feedstock and established IUCLID dossiers. Five-to-ten year viability hinges on scope 3 carbon accounting capabilities becoming contract qualification criteria. Acquisition focus should center on Malaysian or Indonesian producers with plantation linkages and emerging REACH registration completion. Monitor EPA Safer Choice program expansion into industrial solvent categories as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Production | KLK OLEO and IOI Oleochemicals demonstrate how plantation control secures feedstock cost positioning against spot-market volatility. |
| EPA Safer Choice Qualification | Bio-based ester pathways into institutional cleaning open as the program reshapes surfactant procurement standards. |
| Continuous Pharmaceutical-Grade Reactor Investment | FDA process analytical technology standards favor capital-intensive continuous processing over legacy batch retrofitting. |
| REACH Full Substance Registration | ECHA's one-tonne threshold triggers are consolidating European supply around dossier-compliant domestic producers. |
| Enzymatic Esterification Scale-Up | German and Swiss pilot installations reduce energy inputs and downstream purification burdens for heat-sensitive feeds. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic formulators, pharmaceutical excipient procurement managers, oleochemical plant engineers, and REACH regulatory affairs specialists. Secondary validation drew from ECHA registration databases, FDA 21 CFR guidance documents, Malaysian Palm Oil Board production statistics, and customs trade flow records. Bottom-up capacity modeling and top-down demand segmentation were triangulated against operating data.
Calibration against historical price spreads and capacity utilization rates anchored the analytical framework across the analysis window. Segmentation dimensions included ester chemistry type, end-use industry, grade tier, and regional production hub. CAGRs were derived from installed capacity expansion timelines and formulation demand growth in personal care and pharmaceutical channels. Forecast inputs incorporated palm oil yield projections and regulatory registration completion schedules.
Sensitivities concentrate around El Niño crop yield impacts, REACH authorization expansions for CMR-classified substances, and FDA residual alcohol specification tightening. Forecasts reflect assumptions on oleochemical capacity commissioning and multinational formulator supplier consolidation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Esters Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
1-Decene Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Global Creosote Oil Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Global Specialty Oleochemicals Market