
 Electric Utility Vehicle Market | 2026-2036
Electric Utility Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Utility Vehicle Market Analytics
High-voltage lithium-ion battery architectures with integrated thermal management are reshaping how electric utility vehicles deliver torque and range in commercial duty cycles. Polaris Inc leverages its powersports engineering heritage to anchor performance expectations in off-road utility segments. John Deere sustains its agricultural equipment dominance by extending electric drivetrains into farm and turf applications. Club Car specializes in compact electric utility vehicles for campus and resort environments where noise ordinances restrict internal combustion.
An electric utility vehicle is a battery-powered commercial transport unit engineered for cargo hauling, personnel movement, or equipment towing across industrial, municipal, or agricultural sites, typically operating at speeds below 50 km/h with payload ratings from 500 kg to over 2,000 kg depending on chassis class. Manufacturing emphasizes welded steel frames, sealed lead-acid or lithium-ion battery packs, and regenerative braking systems calibrated for stop-start duty cycles. Pickup trucks and vans capture the largest share of current procurement volume, driven by logistics fleet replacements and municipal service contracts. Solid-state batteries represent the fastest-growing battery type segment, as early adopters seek higher energy density and reduced thermal runaway risk in continuous-use environments. Municipal end users generate stable recurring demand through street maintenance, park services, and airport ground support contracts.
The EPA tailpipe emission standards and the NHTSA Federal Motor Vehicle Safety Standards govern product compliance and market access for manufacturers selling into the United States. OSHA workplace safety regulations additionally shape vehicle design requirements for industrial and construction site operation. The ISO 6469 standard for electric vehicle safety provides international benchmarking for battery system integrity and crashworthiness protocols. Stakeholders must monitor evolving state-level zero-emission procurement mandates and charging infrastructure commitments to align production capacity with fleet electrification timelines.
Market Dynamics
Solid-state battery commercialization is compressing development timelines across the electric utility vehicle supply chain, forcing incumbent manufacturers to accelerate thermal management integration and recalibrate range-performance tradeoffs for commercial duty cycles.
Growth Catalysts
- US Federal Procurement Mandates:Executive orders requiring federal fleet electrification are creating guaranteed offtake volume for domestic manufacturers serving postal, park service, and military ground support applications.
- Last-Mile Logistics Electrification:Parcel carriers are replacing diesel step-vans with battery-powered alternatives to comply with municipal zero-emission delivery zones in California and New York.
- Lithium Iron Phosphate Chemistry:LFP cell production scale-up is reducing pack costs for medium-duty utility platforms while improving cycle life in high-utilization commercial environments.
Market Restraints
- Cathode Material Concentration:Refined lithium and cobalt processing capacity clusters in China, creating geographic supply vulnerability for North American and European cell manufacturers.
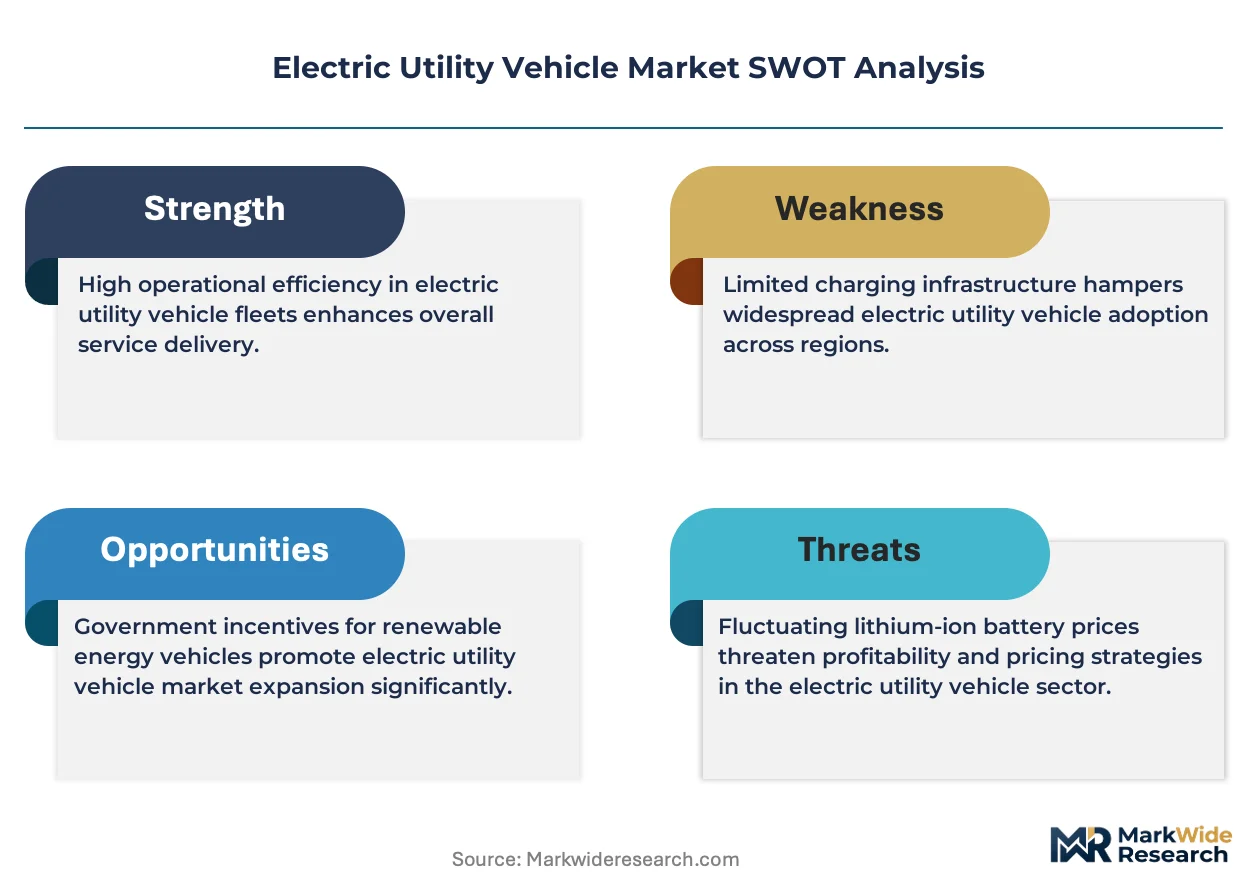
- Charging Infrastructure Gap:Rural commercial depots lack 480V three-phase service upgrades necessary for overnight fleet charging, delaying conversion timelines for agricultural and municipal operators.
- Payload-Range Tradeoff Physics:Current lithium-ion energy density limits force utility vehicle designers to choose between cargo capacity and operational radius, constraining adoption in heavy-haul turf maintenance and construction segments.
Strategic Opportunities
- India Commercial Fleet Subsidies:Faster Adoption and Manufacturing of Electric Vehicles scheme Phase III extends purchase incentives to light commercial vehicles, opening procurement channels for compact utility platforms in last-mile delivery and intra-factory logistics.
- Vehicle-to-Grid Integration:Bidirectional charging hardware convergence with stationary energy storage is enabling fleet operators to monetize battery assets during peak demand periods through utility demand-response programs.
- Autonomous Yard Operations:Sensor fusion and localization technology maturation is creating deployment pathways for driverless electric utility vehicles in controlled environments such as distribution centers, airports, and mining sites.
Industry Challenges
- Battery Thermal Runaway Containment:Engineers must integrate multi-layer cell isolation and venting systems to satisfy UN 38.3 transport regulations and NFPA 855 stationary storage fire codes, adding design complexity and validation cost.
- Legacy Fleet Integration:Mixed-fleet operators face telematics protocol fragmentation between internal combustion assets and new electric platforms, complicating unified dispatch and maintenance scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Utility Vehicle Market |
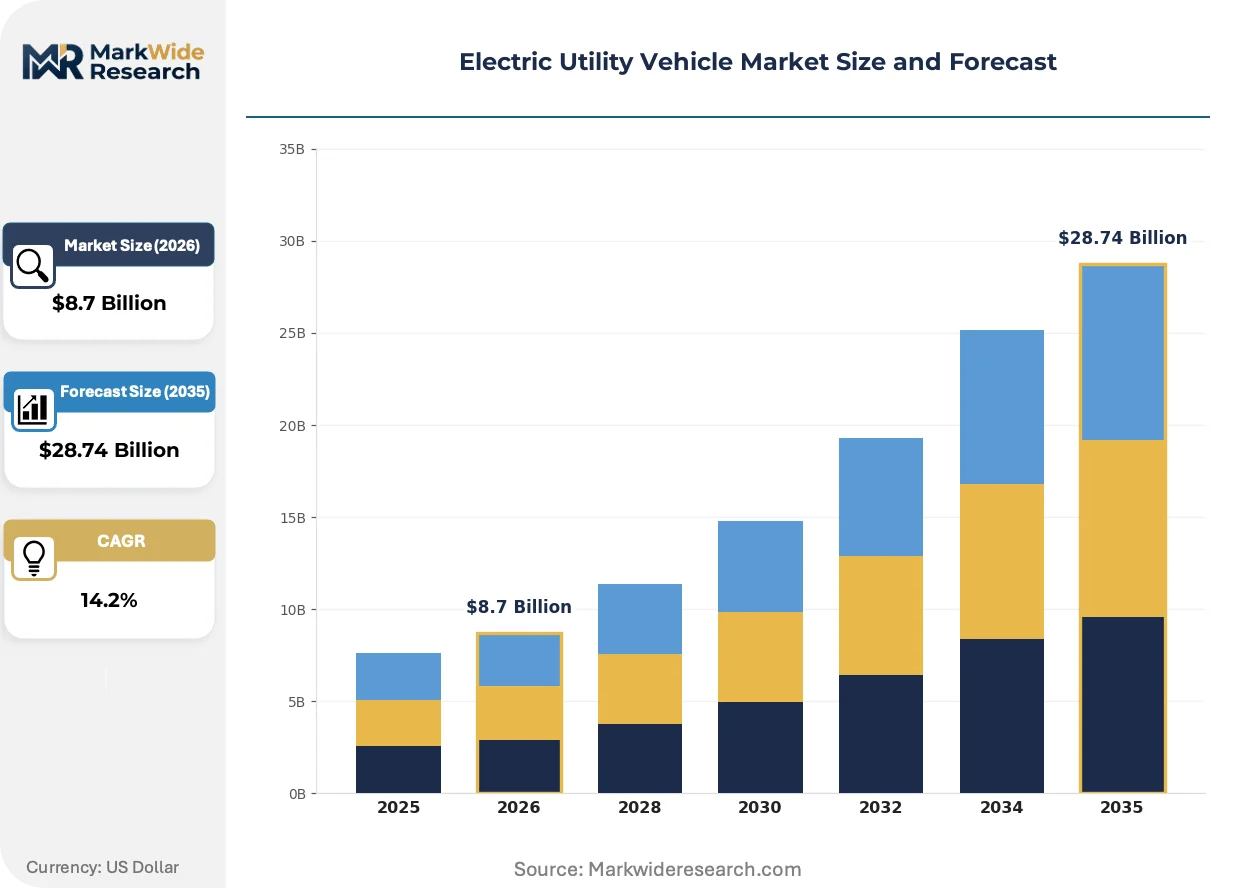
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Pickup Trucks, Vans, Buses, Trailers Battery Type: Lithium-ion, Lead Acid, Nickel-Metal Hydride, Solid State End User: Municipalities, Logistics Companies, Rodeo Businesses, Construction Firms Charging Infrastructure: Fast Chargers, Standard Chargers, Wireless Chargers, Mobile Charging Units |
| Companies Covered | Club Car, Textron Specialized Vehicles, Toro Company, Polaris Inc, John Deere, Yamaha Motor, Columbia Vehicle Group, American Landmaster, Alke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Utility Vehicle Market Evolving Landscape
Battery chemistry advancement and thermal architecture innovation are redefining performance benchmarks for commercial utility platforms. Manufacturers now compete on total cost of ownership rather than upfront acquisition price.
Silicon-anode lithium-ion cells with pre-lithiated architectures are rendering obsolete conventional graphite-anode designs in high-payload utility applications. Agricultural equipment manufacturers are adopting these cells for extended-range turf tractors and orchard sprayers. The technology is rendering obsolete the historical 80-kilometer daily range ceiling that constrained electric utility vehicle deployment in large-acreage farming operations.
The EPA's proposed Phase 3 greenhouse gas standards for heavy-duty vehicles are tightening CO2 limits for Class 2b-3 commercial trucks starting with model year 2027. Equipment manufacturers must certify electric utility vans and chassis cab variants under modified test procedures. Municipal and utility fleet managers in California, Texas, and Florida are accelerating procurement timelines to lock in federal tax credit eligibility before domestic content requirements tighten.
Leasing structures are displacing direct purchase for electric utility vehicle acquisition among mid-size logistics operators. Third-party fleet management providers are bundling vehicles, charging infrastructure, and energy management into per-mile contracts. This shift is most pronounced in Germany and the Netherlands, where sustainability-linked financing instruments reduce effective lease rates for operators meeting verified carbon reduction thresholds.
Electric Utility Vehicle Market Segmentation
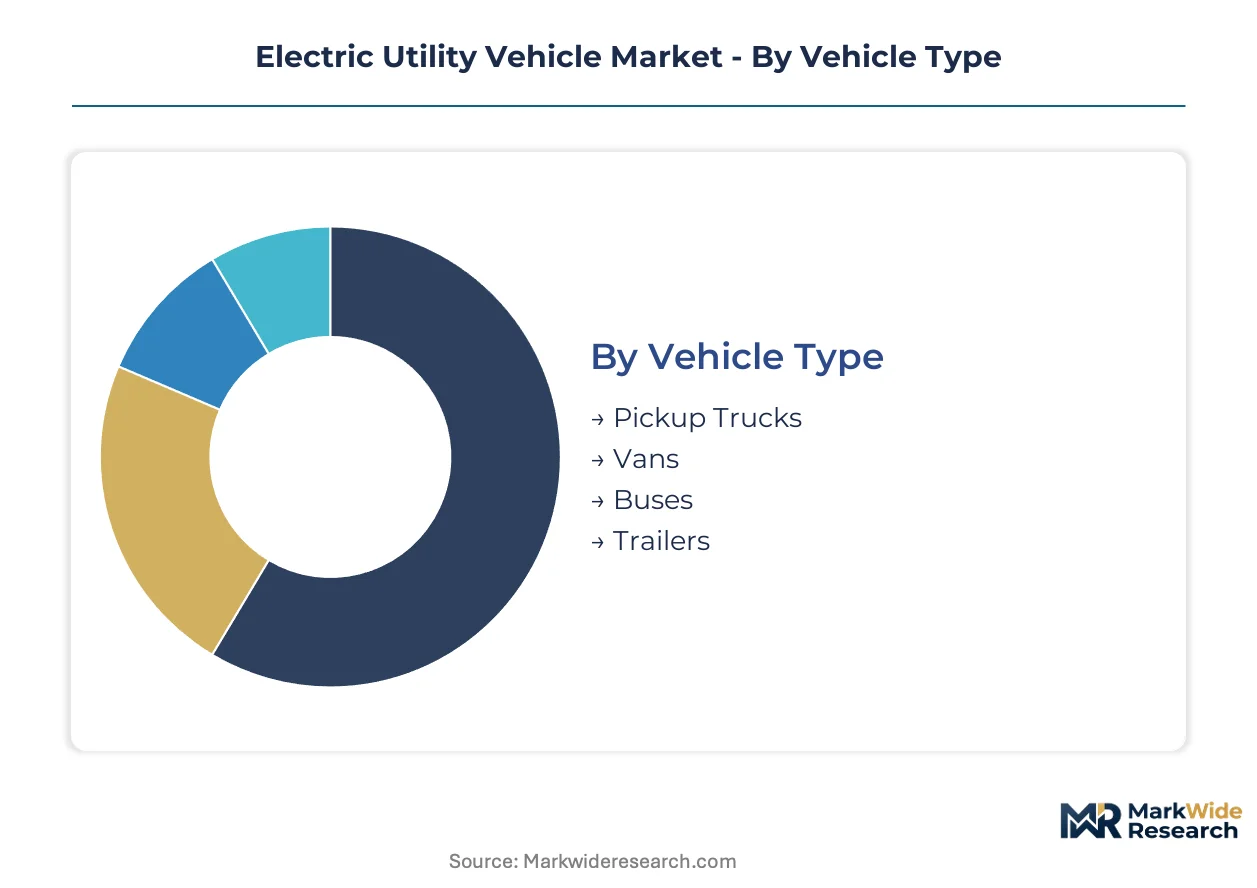
Segmentation reveals how duty cycle requirements and energy infrastructure shape procurement patterns across commercial transport applications. Fleet managers select configurations based on payload demands, route predictability, and depot electrical capacity rather than upfront cost alone.
Vehicle Type:
Mature chassis designs dominate procurement volumes while emerging configurations test specialized applications.
- Pickup Trucks:Open-bed architectures with 1,000-2,000 kg payload ratings serve municipal maintenance crews and construction site supervisors. Demand concentrates in Texas and California where federal fleet electrification mandates drive replacements of gasoline-powered service vehicles.
- Vans:Enclosed cargo compartments with walk-through cabin access enable parcel sorting during transit. Logistics operators in New York and Los Angeles deploy these for last-mile delivery compliance with municipal zero-emission zones.
- Buses:Low-floor designs accommodate 12-20 passengers plus standing room for airport shuttles and campus transit.
- Trailers:Unpowered towed units with electric landing gear and auxiliary power units support mobile equipment staging.
Pickup trucks handle the majority of throughput; vans are the fastest mover on share.
Battery Type:
Cost tier stratification separates proven chemistries from next-generation architectures in commercial validation.
- Lithium-ion:Nickel-manganese-cobalt and lithium iron phosphate cells deliver 150-300 Wh/kg energy density with established recycling pathways. Agricultural equipment manufacturers in Iowa and Illinois specify these for daily duty cycles under 200 kilometers.
- Solid State:Ceramic electrolyte architectures eliminate liquid thermal runaway risks while targeting 400+ Wh/kg density. Early adopters in mining and airport ground support test these for continuous 24-hour operations.
- Lead Acid:Flooded and absorbed glass mat designs persist in price-sensitive campus maintenance applications.
- Nickel-Metal Hydride:Rare-earth hydride chemistries occupy niche roles in cold-climate deployments.
Lithium-ion chemistry commands current procurement volume; solid-state architectures are expanding most quickly in pilot fleet deployments.
End User:
Application-driven specifications create divergent performance requirements across operational environments.
- Logistics Companies:Hub-and-spoke operators prioritize route-optimized range with telematics integration for real-time battery state-of-charge monitoring. Amazon and UPS electrification commitments in California and New York reshape van procurement specifications.
- Municipalities:Street maintenance departments require 10-year asset lifecycles with standardized parts availability across mixed fleets. Park service contracts in Arizona and Colorado specify off-road capability for trail maintenance access.
- Construction Firms:Job site mobility demands ruggedized suspensions and IP67 ingress protection.
- Rodeo Businesses:Arena transport applications emphasize low-speed maneuverability and spectator safety.
Logistics companies drive volume concentration; municipalities provide the steadiest recurring replacement demand.
Charging Infrastructure:
Customer type segmentation separates fleet operators with depot control from those requiring public network access.
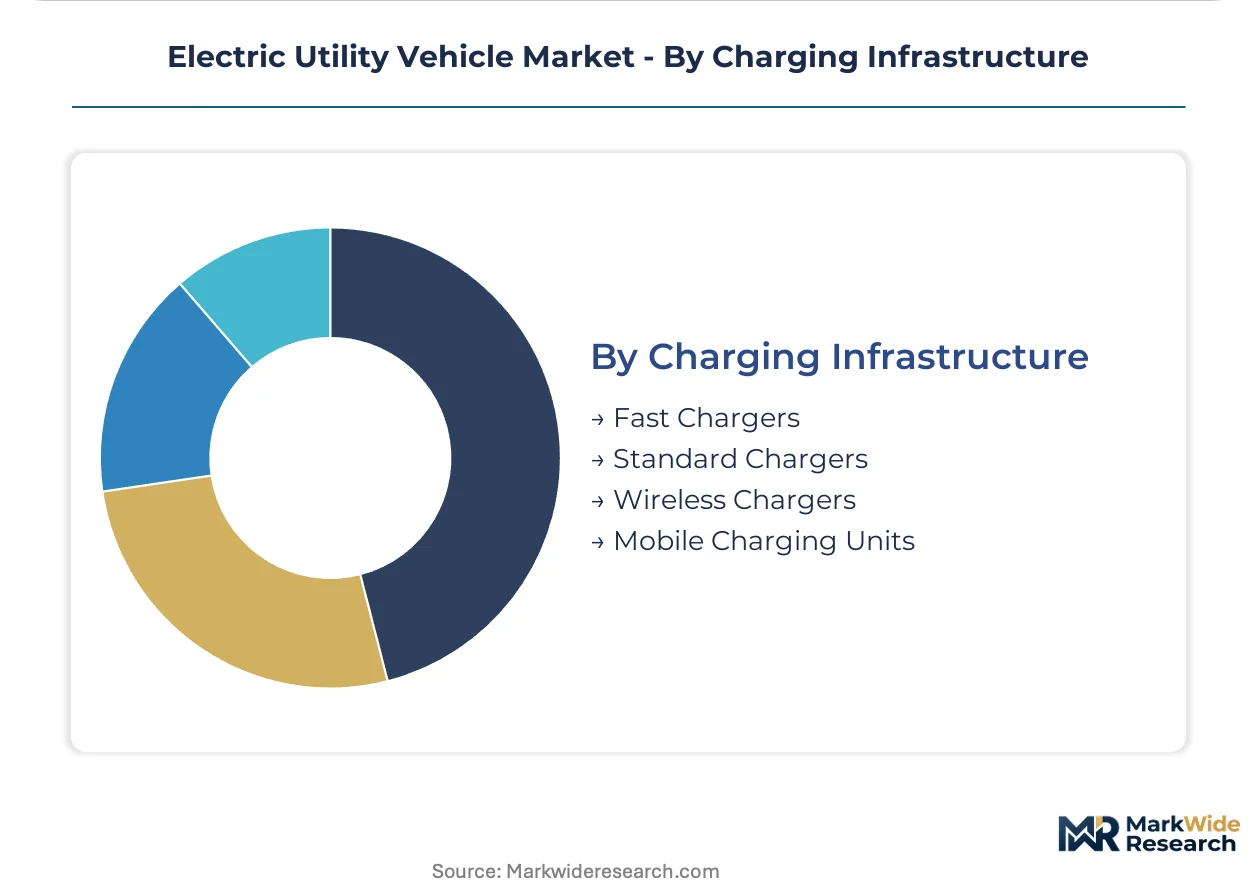
- Fast Chargers:150-350 kW DC systems deliver 80% state-of-charge in 30-60 minutes for opportunity charging during driver breaks. Regional logistics hubs in Ohio and Pennsylvania install these to maximize asset utilization across double-shift operations.
- Standard Chargers:7-22 kW AC units provide overnight replenishment for predictable return-to-base routes.
- Wireless Chargers:Inductive pad systems enable automated charging for autonomous yard vehicles.
- Mobile Charging Units:Trailer-mounted battery banks extend range for remote construction and agricultural sites lacking grid infrastructure.
Standard chargers handle baseline fleet requirements; fast chargers are climbing the fastest as logistics operators compress turnaround times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement managers in logistics and municipal sectors concentrate demand across specific national markets where charging infrastructure investments and zero-emission procurement mandates align. Each geography presents distinct regulatory frameworks and industrial clustering patterns that shape electric utility vehicle deployment timelines.
United States
Federal fleet electrification mandates under Executive Order 14057 guarantee offtake volume for postal and park service applications. The EPA tailpipe emission standards and NHTSA Federal Motor Vehicle Safety Standards govern product compliance for domestic manufacturers. Procurement clusters in California and Texas drive replacements of gasoline-powered service vehicles under state-level zero-emission programs.
Germany
Leasing structures for electric utility vehicle acquisition dominate among mid-size logistics operators seeking sustainability-linked financing instruments. The KBA enforces type approval requirements for commercial vehicle certification. Industrial concentration in North Rhine-Westphalia and Bavaria supports manufacturing hubs serving municipal fleet contracts across the EU Green Deal implementation corridor.
China
Domestic battery cell production scale-up reduces pack costs for medium-duty utility platforms serving last-mile delivery networks. The MIIT establishes GB standards for electric vehicle safety and battery system integrity. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta supply lithium iron phosphate cells to agricultural equipment producers in Shandong Peninsula.
India
Faster Adoption and Manufacturing of Electric Vehicles scheme Phase III extends purchase incentives to light commercial vehicles for intra-factory logistics. The CEA regulates charging infrastructure standards for commercial depot installations. Industrial corridors in Maharashtra and Gujarat host assembly operations targeting compact utility platforms for campus maintenance and resort environments.
Japan
Sensor fusion technology maturation enables deployment pathways for driverless electric utility vehicles in controlled airport and distribution center environments. METI coordinates national hydrogen and electrification roadmaps affecting commercial vehicle transition timelines. Manufacturing concentration in the Chubu region around Nagoya anchors precision engineering for thermal management systems.
Electric Utility Vehicle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct market tiers. Powersports and agricultural equipment conglomerates anchor performance expectations in off-road utility segments through established dealer networks. Compact vehicle specialists dominate campus and resort environments where noise ordinances restrict internal combustion. The competitive terrain rewards backward integration into battery pack assembly and strategic partnerships with charging infrastructure providers.
Among North American equipment manufacturers, Polaris Inc and John Deere exemplify diversified industrial conglomerates extending electric drivetrains into specialized utility applications. Club Car occupies a position within the compact vehicle specialist tier, representing manufacturers focused on low-speed commercial transport for controlled environments. These three entities anchor distinct competitive vectors without overlapping core market positioning.
| Leading Market Players |
|---|
| Club Car |
| Textron Specialized Vehicles |
| Toro Company |
| Polaris Inc |
| John Deere |
| Yamaha Motor |
| Columbia Vehicle Group |
| American Landmaster |
| Alke |
| Others |
Value Network & Pricing Analysis
Overcapacity in lithium iron phosphate cell production across China's Yangtze River Delta is compressing pack costs for North American utility vehicle assemblers while simultaneously eroding supplier pricing power in contract negotiations. This utilization dynamic forces tier-one battery integrators toward longer-term offtake agreements with indexed cathode material clauses to stabilize input costs.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked lithium carbonate indexation dominate procurement between cell manufacturers and utility vehicle OEMs. Three-tier pricing structure across premium solid-state, standard NMC, and economy LFP configurations differentiates based on energy density certification and thermal management complexity. Pricing pressure stems from LFP oversupply in China as domestic producers seek export volume absorption. Municipal fleet operators exhibit highest price sensitivity due to fixed annual appropriations, while mining and airport ground support buyers prioritize reliability over unit economics.
Supply Chain Analysis
Export control regimes restricting semiconductor lithography equipment to Chinese fabs are constraining power electronics availability for North American motor controller suppliers. Cell production concentrates in China, South Korea, and Japan, with refined lithium hydroxide processing anchored in Chile and Australia. Raw material dependencies span spodumene concentrate, nickel sulfate, and copper foil for current collectors. Single-source vulnerability persists in ceramic electrolyte substrates for solid-state architectures. Distribution runs through authorized dealer networks for agricultural and construction segments, with direct fleet sales dominating municipal and logistics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery commercialization represents a high-growth disruption as energy density inflections unlock heavy-haul applications previously reserved for internal combustion platforms. Federal procurement mandates under Executive Order 14057 guarantee demand visibility through the projection horizon.
For Market Incumbents: Pre-empt LFP cost compression by accelerating backward integration into cathode active material production in North America, insulating margin structures from Chinese oversupply volatility. Secure long-term nickel offtake agreements to derisk NMC supply for premium utility segments. Prioritize thermal management IP accumulation as solid-state validation timelines compress. For New Entrants and Emerging Players: Rural municipal depots lacking 480V three-phase infrastructure present the most penetrable white-space opportunity, with mobile charging unit bundling as the differentiated go-to-market angle. Target agricultural cooperatives in Iowa and Illinois with lease-to-own structures that circumvent upfront capital constraints. Develop retrofit kits for existing chassis platforms to accelerate fleet conversion without full asset replacement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across LFP pack assembly as equipment utilization improves, improving return thresholds for mid-scale manufacturing investments. Acquisition candidates should demonstrate captive customer relationships with municipal procurement offices or logistics fleet operators. Watch solid-state pilot deployment announcements from mining and airport operators as signal of chemistry transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term LFP cell contracts with Yangtze River Delta producers secure cost visibility for Texas municipal fleet deliveries. |
| Charging Infrastructure Partnership | Collaboration with utility providers on 480V depot upgrades unlocks rural agricultural conversion timelines in Illinois. |
| Platform Standardization | Modular chassis architectures reduce tooling costs across pickup, van, and turf maintenance variants for John Deere. |
| Software-Defined Vehicle Investment | Over-the-air thermal management calibration extends battery cycle life in high-utilization airport ground support duty. |
| Geographic Manufacturing Footprint | Midwest assembly proximity to Iowa agricultural equipment demand reduces logistics cost and delivery lead times. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at UPS and Amazon, municipal maintenance directors in California and Texas, agricultural equipment dealers in Iowa, and battery pack engineering leads at tier-one suppliers. Secondary validation drew from EPA certification filings, NHTSA safety standard documentation, state-level zero-emission procurement databases, and lithium trade flow customs records. Bottom-up unit shipment estimates triangulated against top-down fleet electrification budget allocations across federal, municipal, and commercial operator categories.
Calibration against historical adoption curves in California municipal fleets and German logistics leasing markets anchored growth rate assumptions across the projection horizon. Segmentation modeling spanned vehicle type, battery chemistry, end-use application, and charging infrastructure configuration, with additional dimensioning by payload class and thermal management architecture. CAGRs derived from logistic curve fitting to fleet replacement cycles and infrastructure deployment timelines. Forecast inputs included federal procurement mandate execution rates, state-level ZEV program expansion, and solid-state battery pilot validation schedules.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, copper futures, or utility electricity rates would shift the trajectory of fleet conversion economics. Forecasts reflect documented assumptions on battery cost decline slopes and charging infrastructure buildout pace. Supply chain disruption from export control expansion or cathode material processing bottlenecks represents primary revision risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Solar Vehicle Market