
 Forklift-Mounted Computers Market | 2026-2036
Forklift-Mounted Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Forklift-Mounted Computers Market Foresight
Software-defined fleet management subscriptions is hardening into the core revenue model for forklift-mounted computer vendors. Honeywell leverages its industrial automation heritage to sustain channel control across North American distribution networks. Zebra Technologies anchors its position through deep specialization in enterprise mobility hardware and real-time data capture systems.
Forklift-mounted computers are ruggedized computing terminals engineered to withstand vibration, temperature extremes, and IP65+ ingress conditions while providing real-time data access to operators in material handling environments. These devices integrate touchscreen interfaces, wireless connectivity modules, and barcode scanning engines to synchronize warehouse execution with enterprise resource planning systems. Panel PCs and mobile computers lead installed value, while edge computing-enabled units represent the fastest-growing technology tier as warehouses push latency-sensitive processing closer to operational endpoints. RFID and Wi-Fi technology segments command mature, high-volume positions, though GPS-integrated units are gaining traction in yard management and cross-dock applications.
OSHA mandates operator safety certification and equipment ergonomics standards that directly influence mounting hardware and display visibility requirements for forklift-mounted systems. FCC Part 15 regulations govern wireless transmission protocols, while EU CE marking and RoHS compliance shape market access for devices sold into European manufacturing plants and logistics hubs. Stakeholders must monitor how evolving cybersecurity frameworks for operational technology networks reshape device authentication and data encryption specifications.
Market Dynamics
Software-defined fleet management subscriptions are hardening into the dominant revenue architecture, compressing hardware margins while locking operators into recurring service relationships. This shift restructures vendor economics away from terminal sales toward data monetization and predictive maintenance platforms.
Growth Catalysts
- E-commerce fulfillment center automation:Third-party logistics operators in the United States are retrofitting existing forklift fleets with ruggedized terminals to synchronize real-time inventory visibility with warehouse execution systems.
- OSHA workplace safety mandates:Operator visibility and ergonomic mounting requirements are accelerating replacement cycles for legacy non-compliant hardware across distribution networks.
- Edge computing module integration:Latency-sensitive processing at the operational endpoint is enabling autonomous navigation pilot programs without full infrastructure overhauls.
Market Restraints
- Semiconductor supply concentration:Industrial-grade processor and wireless chipset sourcing remains concentrated among a limited supplier base in East Asia, creating procurement vulnerability.
- Capital intensity of fleet-wide deployment:Full-forklift computerization requires simultaneous investment in mounting hardware, wireless infrastructure, and enterprise systems integration.
- Technical limitation of battery thermal management:Extended operation in cold-storage environments degrades lithium-ion performance, constraining deployment in pharmaceutical and food logistics.
Strategic Opportunities
- Yard management GPS integration:Cross-dock and outdoor material handling applications represent underpenetrated deployment scenarios for location-aware ruggedized terminals.
- German Industrie 4.0 adoption:Manufacturing plant digitalization incentives are creating procurement pull for machine-to-machine communication-enabled forklift systems.
- RFID-Wi-Fi convergence:Hybrid scanning engines combining radio-frequency identification with wireless local area network triangulation are opening automated inventory reconciliation applications.
Industry Challenges
- Operational technology cybersecurity skill scarcity:Warehouse operators lack in-house expertise to configure device authentication and data encryption specifications mandated by evolving network security frameworks.
- FCC Part 15 certification timelines:Wireless transmission protocol approvals for new frequency bands extend product launch schedules, compressing competitive windows.
- Legacy warehouse management system integration:Proprietary data formats in incumbent enterprise resource planning systems require expensive middleware development for real-time synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forklift-Mounted Computers Market |
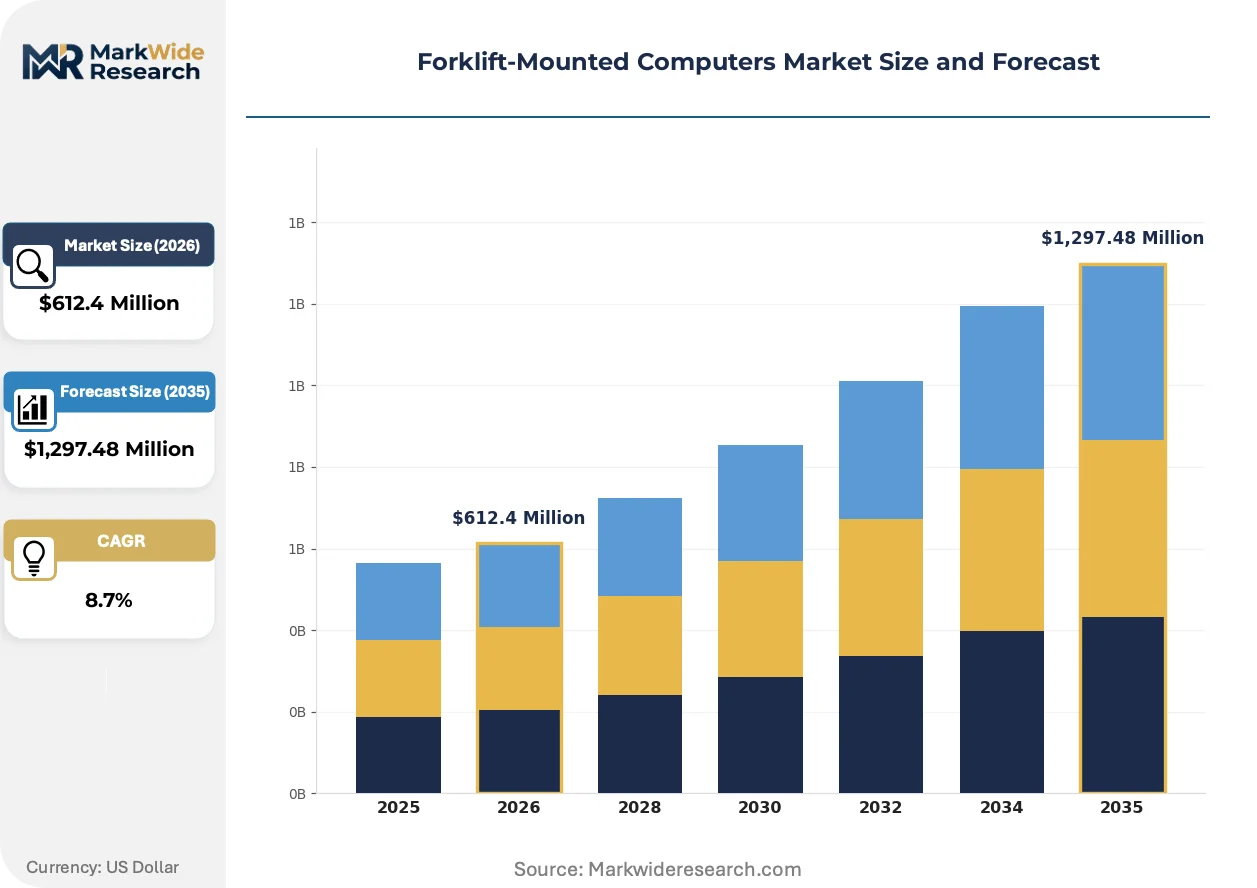
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel PCs, Touchscreen Displays, Barcode Scanners, Keypads, Mobile Computers Technology: RFID, Wi-Fi, Bluetooth, GPS, Edge Computing Application: Warehouse Management, Inventory Control, Asset Tracking, Order Fulfillment, Quality Assurance End User: Distribution Centers, Manufacturing Plants, Third-Party Logistics, Wholesale Facilities |
| Companies Covered | Honeywell, Zebra Technologies, Advantech, Winmate, JLT Mobile Computers, NEXCOM International, Datalogic, Glacier Computer, RuggON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forklift-Mounted Computers Market Shifts & Advancements
Edge computing architectures are migrating processing workloads from centralized servers to forklift-mounted endpoints, reducing latency for autonomous navigation and real-time decision support. This decentralization is reshaping hardware specifications and vendor competitive positioning.
Panel PC form factors with integrated edge processing modules are consolidating warehouse computing infrastructure by eliminating separate gateway devices. E-commerce fulfillment operators in Germany and the United States are deploying these consolidated units at scale. The technology is compressing total cost of ownership while simplifying maintenance protocols across multi-site distribution networks.
FCC Part 15 regulations governing unlicensed wireless transmission are tightening emission standards for industrial devices operating in congested spectrum bands. Manufacturers must redesign antenna configurations and shielding to maintain certification. Forklift computer vendors serving North American logistics hubs are prioritizing pre-certified radio modules to accelerate deployment timelines.
Subscription-based fleet management platforms are displacing perpetual-license software procurement in material handling operations. Third-party logistics providers in China are demanding outcome-based contracts tying vendor compensation to uptime metrics and throughput improvements. This purchasing transformation is most visible among multinational contract logistics operators consolidating vendor relationships across regional warehouse networks.
Forklift-Mounted Computers Market Segmentation
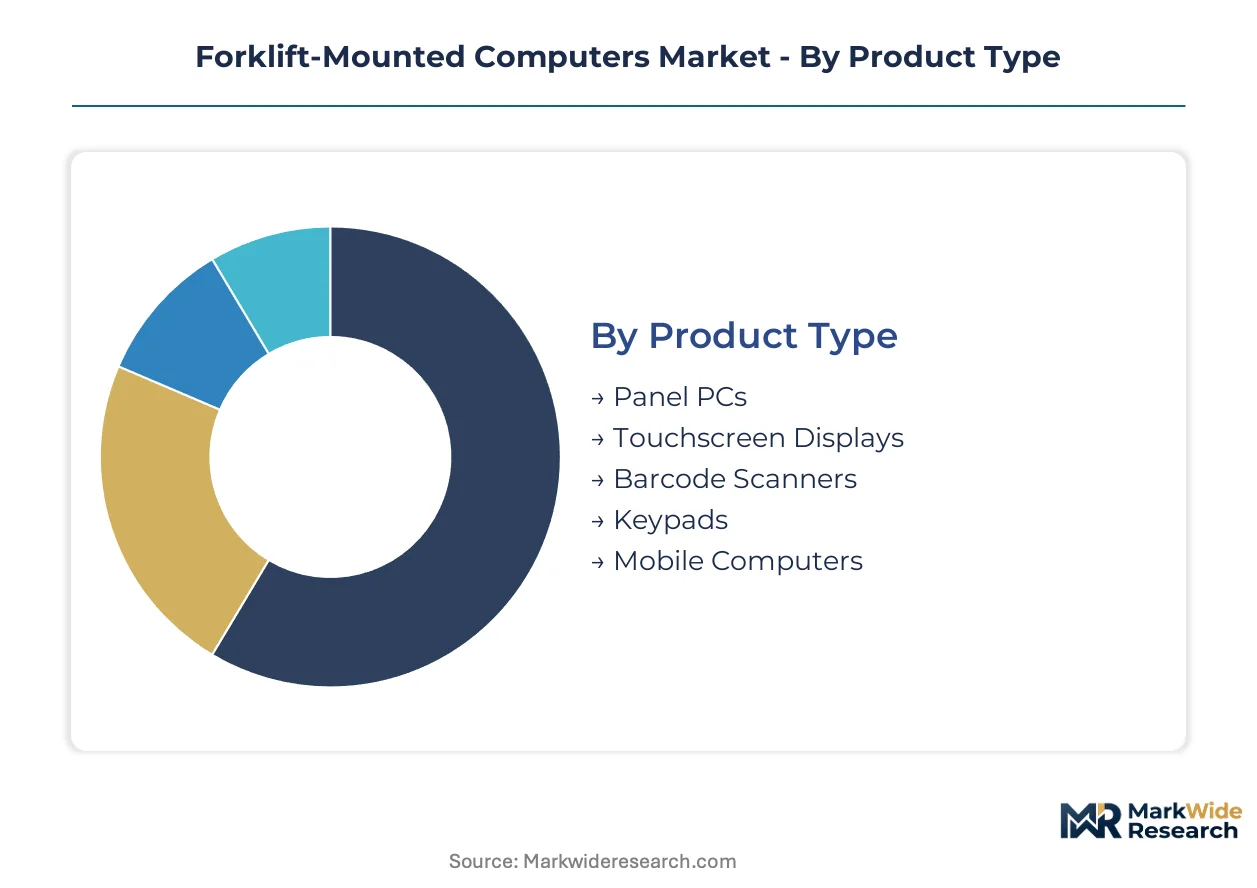
Forklift-mounted computer procurement varies sharply by operational environment. Capital allocation priorities differ between cold-storage distribution networks and high-velocity e-commerce fulfillment centers. Understanding segment boundaries clarifies where technology investments concentrate and which specifications command pricing premiums.
Product Type:
Capital intensity peaks with integrated systems requiring simultaneous hardware, mounting infrastructure, and wireless backbone deployment. Standalone peripherals demand lower upfront commitment but generate higher lifetime integration costs.
- Panel PCs:Ruggedized all-in-one computing terminals with sealed enclosures rated for IP65+ ingress protection and vibration tolerance. Demand concentrates in United States distribution centers where OSHA ergonomic mandates drive replacement of legacy display systems. These units consolidate computing, visualization, and edge processing into single mounting configurations.
- Mobile Computers:Handheld or vehicle-mounted terminals with detachable form factors enabling operator mobility beyond the forklift cab. German manufacturing plants favor these for flexible workstation assignments across multi-line production facilities. Battery thermal management limitations constrain deployment in pharmaceutical cold storage.
- Touchscreen Displays:Dedicated visualization panels without integrated computing modules.
- Barcode Scanners:Laser or imaging-based data capture peripherals.
- Keypads:Ruggedized input devices for high-velocity data entry.
Most installed capacity flows through Panel PCs. Expansion is steepest in Mobile Computers.
Technology:
Wireless certification requirements reshape procurement timelines across technology tiers. FCC Part 15 compliance for unlicensed spectrum devices extends vendor development cycles and concentrates sourcing among pre-certified module suppliers.
- Edge Computing:Onboard processing modules enabling latency-sensitive autonomous navigation and real-time decision support without centralized server dependency. United States third-party logistics operators deploy these for pilot programs in yard management automation. Processing localization reduces infrastructure overhaul requirements.
- Wi-Fi:Wireless local area network connectivity for real-time ERP synchronization.
- RFID:Radio-frequency identification for automated inventory reconciliation.
- Bluetooth:Short-range wireless for peripheral device pairing.
- GPS:Satellite positioning for outdoor yard and cross-dock applications.
Wi-Fi and RFID dominate current installed base. Edge Computing is gaining share fastest.
Application:
Application selection tracks warehouse management system maturity and integration complexity. Legacy ERP environments constrain real-time synchronization capabilities regardless of terminal sophistication.
- Warehouse Management:Real-time inventory visibility and location tracking synchronized with enterprise execution systems. Chinese e-commerce fulfillment centers deploy these systems at scale to manage high-SKU-density operations. FCC wireless certification requirements shape vendor selection timelines.
- Order Fulfillment:Pick-path optimization and verification for direct-to-consumer shipment accuracy.
- Inventory Control:Cycle counting and stock-level monitoring automation.
- Asset Tracking:Equipment and container location monitoring across facility footprints.
- Quality Assurance:Inspection data capture and defect documentation workflows.
Warehouse Management captures the largest technology spend. Order Fulfillment shows the steepest climb trajectory.
End User:
End-user procurement patterns diverge by fleet scale and outsourcing strategy. Captive operations favor perpetual-license software while third-party logistics operators increasingly demand subscription-based fleet management platforms.
- Distribution Centers:High-velocity fulfillment facilities serving retail and e-commerce channels. United States operators retrofit existing forklift fleets to synchronize real-time inventory visibility with warehouse execution systems. OSHA workplace safety mandates accelerate replacement cycles for non-compliant legacy hardware.
- Third-Party Logistics:Contract operators managing multi-client warehouse networks.
- Manufacturing Plants:Production-floor material handling integrated with MES and ERP systems.
- Wholesale Facilities:Bulk distribution operations with lower velocity but higher SKU variety.
Distribution Centers anchor hardware procurement volume. Third-Party Logistics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as vendors relocate final assembly to jurisdictions with streamlined FCC-equivalent certification pathways. Cost-of-compliance gaps between mature and emerging certification regimes are accelerating production migration decisions.
United States
Third-party logistics operators in Memphis and Indianapolis are retrofitting forklift fleets with ruggedized terminals to synchronize warehouse execution systems. OSHA workplace safety mandates on operator visibility and ergonomic mounting are accelerating hardware replacement cycles. Chicago distribution corridors concentrate deployment of edge-computing-enabled units for autonomous navigation pilot programs.
Germany
Manufacturing plants in Bavaria and Baden-Württemberg are procuring machine-to-machine communication-enabled forklift systems under Industrie 4.0 digitalization incentives. EU CE marking and RoHS compliance requirements shape vendor selection for devices sold into European logistics hubs. The Ruhr industrial cluster is consolidating multi-site warehouse networks with subscription-based fleet management platforms.
China
E-commerce fulfillment centers in Shanghai and Shenzhen are deploying high-SKU-density warehouse management systems at scale. MIIT wireless certification requirements and GB standards govern domestic device specifications. The Yangtze River Delta is emerging as a concentration zone for cold-storage pharmaceutical logistics despite lithium-ion thermal management constraints.
Japan
Automotive and electronics manufacturers in Aichi Prefecture are integrating forklift-mounted computers with MES systems for just-in-time production workflows. METI industrial digitalization programs are subsidizing operational technology upgrades. The Kansai region around Osaka is standardizing on hybrid RFID-Wi-Fi scanning engines for automated inventory reconciliation.
United Kingdom
Retail distribution networks in the Midlands are replacing legacy display systems to meet post-Brexit customs documentation requirements for cross-border fulfillment. The country's national workplace safety regulator enforces operator certification standards that influence mounting hardware specifications. London-area third-party logistics operators are demanding outcome-based vendor contracts tied to uptime metrics.
Forklift-Mounted Computers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with industrial automation heritage conferring channel control advantages in North American distribution networks. The vendor base organizes into three tiers: diversified electronics conglomerates with captive industrial divisions, pure-play ruggedized computing specialists, and regional system integrators with localization capabilities. Consolidation pressure is intensifying as software-defined revenue models favor scale economies in fleet management platform development. Strategic moves center on backward integration into wireless module sourcing and geographic expansion through certified reseller networks.
Among diversified technology conglomerates, Honeywell International Inc. and Zebra Technologies Corporation exemplify the industrial automation-to-enterprise-mobility pivot that dominates premium-tier positioning. Taiwan-based Advantech Co., Ltd. anchors the specialist tier with concentrated exposure to industrial computing form factors. These three entities collectively represent the competitive archetypes reshaping procurement relationships: the automation heritage player, the data-capture hardware specialist, and the industrial computing pure-play.
| Leading Market Players |
|---|
| Honeywell |
| Zebra Technologies |
| Advantech |
| Winmate |
| JLT Mobile Computers |
| NEXCOM International |
| Datalogic |
| Glacier Computer |
| RuggON |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FCC Part 15 pre-certified modules and uncertified commodity hardware manifests in both margin structures and sourcing strategies. Premium-tier vendors capture pricing power through captive wireless module supply while commodity assemblers absorb certification timeline risk and margin compression.
Pricing Analysis
Distributor margin layers of 15-25 percent separate direct-to-OEM volume contracts from reseller-channel transactions. Subscription-based fleet management platforms stratify across premium, standard, and economy tiers based on edge computing capability and predictive maintenance bundling. Cost compression in hardware-only sales is intensifying as software-defined revenue models displace perpetual licenses. Third-party logistics operators demonstrate highest price sensitivity due to outcome-based contract structures, while captive distribution centers accept premium positioning for OSHA compliance assurance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States third-party logistics operators and German manufacturing consolidators. Industrial-grade processor and wireless chipset sourcing concentrates in Taiwan, South Korea, and China, creating procurement vulnerability. Assembly draws from precision metal fabrication in Mexico and electronics integration in Malaysia. Single-source vulnerability in FCC pre-certified radio modules threatens deployment timelines. Distribution runs through certified reseller networks anchored by industrial automation specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forklift-mounted computers function as a stable compounder anchored by regulatory-mandated replacement cycles and e-commerce fulfillment infrastructure expansion. OSHA ergonomic mandates and FCC certification requirements create non-discretionary demand that sustains replacement revenue.
For Market Incumbents: Deploy backward integration into wireless module sourcing to compress certification timelines and defend margin position against emerging contract manufacturers. Prioritize captive supply of FCC Part 15 pre-certified radio components to accelerate deployment schedules for United States distribution center retrofits. Channel control through industrial automation heritage remains defensible against pure-play ruggedized computing specialists.
For New Entrants and Emerging Players: Cold-storage pharmaceutical logistics operators represent an underserved buyer archetype constrained by lithium-ion thermal management limitations. Yard management GPS-integrated units for cross-dock applications offer penetrable white space with lower incumbent saturation. Target German Industrie 4.0 manufacturing subsidies through machine-to-machine communication-enabled system bundling.
For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined fleet management platforms require scale economies in predictive maintenance algorithm development. Five-to-ten year viability favors vendors with dual capability in edge computing hardware and recurring service revenue architecture. Acquisition target archetype: regional system integrators with MIIT or METI certification pathways and established reseller relationships. Signal to watch: outcome-based contract penetration rates among multinational third-party logistics operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wireless Modules | Captive FCC Part 15 certification accelerates deployment timelines for North American logistics hubs. |
| Subscription Platform Migration | Recurring fleet management revenue locks third-party logistics operators into long-term service relationships. |
| Edge Computing Module Development | Onboard processing enables autonomous navigation pilots without full warehouse infrastructure overhauls. |
| German Industrie 4.0 Certification Pathway | EU CE marking and RoHS compliance open procurement channels in Bavarian manufacturing plant digitalization. |
| Cold-Storage Battery Thermal Engineering | Extended lithium-ion performance in pharmaceutical logistics addresses constrained deployment scenario. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged warehouse operations directors, OEM procurement teams, industrial automation channel partners, and aftermarket service heads across United States, German, and Chinese distribution networks. Secondary validation drew from FCC equipment authorization databases, OSHA enforcement records, customs trade data, and SEC filings from diversified industrial technology conglomerates. Bottom-up terminal deployment estimates and top-down warehouse automation spending analysis were triangulated for convergence.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include product form factor, wireless technology tier, application workflow, and end-user fleet scale. CAGRs were derived from logistic diffusion curves fitted to technology adoption patterns in material handling operations. Forecast inputs incorporated e-commerce fulfillment center buildout pipelines, OSHA compliance audit frequencies, and wireless certification backlog data.
Underlying measurement precision varies by segment; edge computing-enabled units and subscription revenue streams carry tighter precision than legacy hardware sales. Forecasts reflect assumptions regarding semiconductor supply normalization and regulatory certification timeline stability. Periodic stress-testing of base assumptions is recommended given operational technology cybersecurity framework evolution and lithium-ion thermal management constraint resolution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Smart Factory Market
Industrial Automation
Motion Control Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Intralogistics Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Industrial Automation Products Market