
 Servo Gripper Market | 2026-2036
Servo Gripper Market Size, Share, and Industry Trends Forecast 2026-2036
Servo Gripper Market Analytics
Automotive buyer concentration is consolidating as EV manufacturers merge battery and powertrain assembly into single facilities, forcing gripper suppliers to serve larger contract volumes. SCHUNK GmbH & Co. KG leverages its modular electric gripper architecture to anchor high-volume automotive contracts. Festo Group competes through integrated pneumatic-to-electric migration programs for legacy factory retrofits. SMC Corporation sustains channel control via its dense distributor network across East Asian manufacturing hubs.
A servo gripper is an electromechanical end-effector that uses servo motors to control jaw position, force, and velocity with repeatability typically below 0.02 mm, enabling precise manipulation of delicate or variably shaped objects in automated production lines. Electric grippers dominate premium installations where energy efficiency and programmability offset higher capital costs, while pneumatic grippers retain share in high-speed packaging lines where compressed air infrastructure already exists. Vision-based technology segments are expanding fastest as machine learning edge processors enable real-time object recognition without external PC dependency.
ISO 10218 collaborative robot safety standards and EU Machinery Directive 2006/42/EC force manufacturers to certify force-sensitive gripper modes before European market entry. Japan's METI safety guidelines for next-generation robots add compliance layers for force-sensitive technology deployments. Stakeholders must monitor how regional certification divergence between EU CE marking and Japanese JIS standards affects product platform standardization costs.
Market Dynamics
Automotive electrification is consolidating assembly footprints, forcing servo gripper suppliers to reengineer force-control architectures for battery module handling while absorbing tenfold volume increases from merged powertrain-battery facilities.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Force-limiting certification requirements for collaborative robot deployments are accelerating replacement of legacy pneumatic systems with programmable electric grippers in German automotive plants.
- Edge machine learning processors:On-gripper vision systems with embedded neural inference engines are eliminating external PC dependencies, reducing integration costs for small-batch electronics manufacturers.
- Stuttgart-Munich corridor concentration:Dense clustering of industrial automation R&D facilities is creating localized knowledge spillovers that compress development cycles for adaptive gripper algorithms.
Market Restraints
- Rare-earth magnet supply concentration:Servo motor production depends on neodymium supply chains concentrated in Chinese processing facilities, exposing manufacturers to export quota volatility.
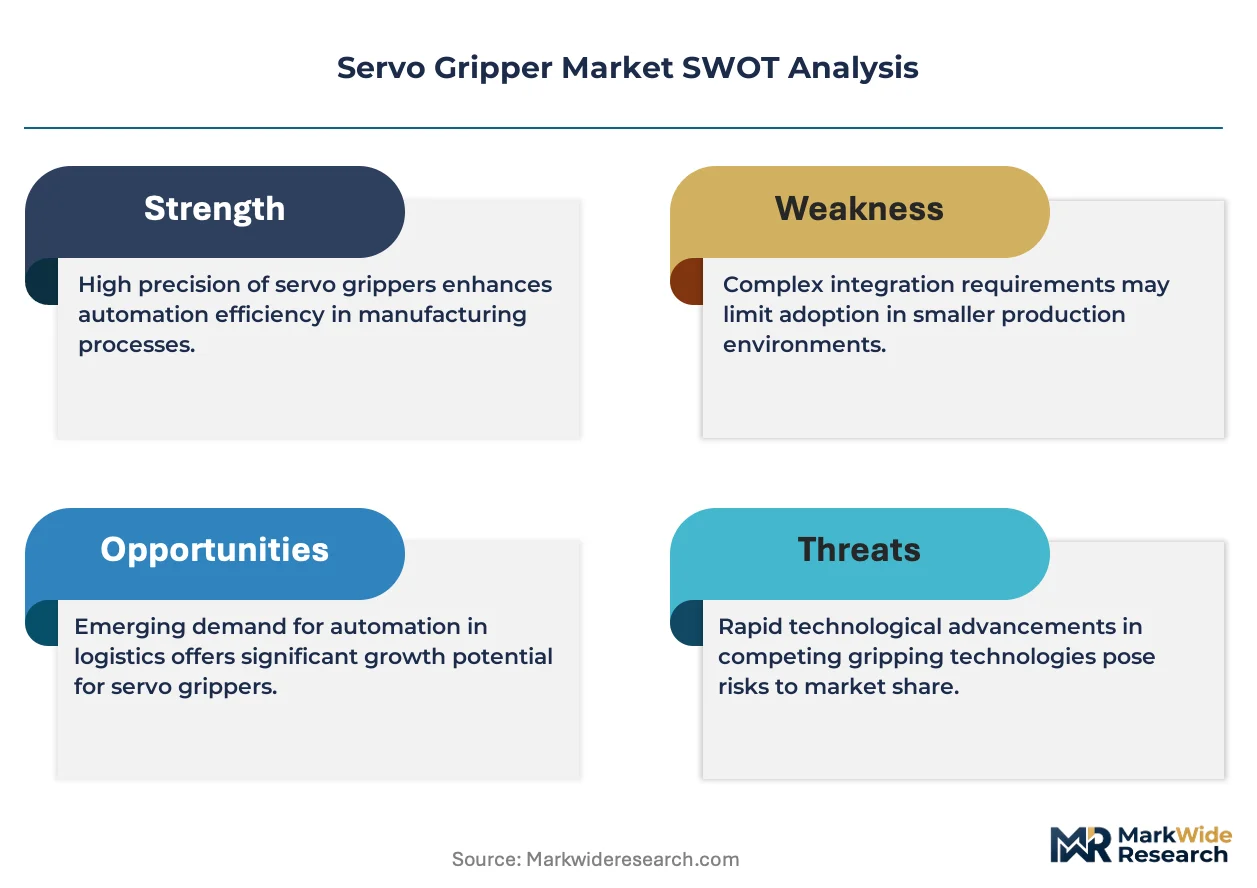
- Pneumatic infrastructure lock-in:Existing compressed air networks in high-speed packaging facilities create switching costs that delay electric gripper adoption despite superior precision.
- ISO 10218 certification timelines:Force-sensitive collaborative modes require extensive third-party testing, extending product launch cycles by 8-14 months for European market entry.
Strategic Opportunities
- India PLI scheme for advanced manufacturing:Production-linked incentives for electronics and automotive component sectors are attracting gripper suppliers to establish localized assembly for duty-advantaged domestic supply.
- Soft robotics convergence:Integration of elastomeric finger surfaces with traditional servo actuation enables handling of irregular agricultural produce, opening food processing applications previously closed to rigid grippers.
- Japan METI next-generation robot guidelines:Force-sensitive technology mandates for eldercare automation are creating certified-product preferences that reward early compliance investments.
Industry Challenges
- Mechatronics talent scarcity:Shortage of engineers with combined servo control and mechanical design expertise is constraining R&D throughput for mid-tier suppliers.
- Retrofit integration complexity:Legacy PLC architectures in established automotive lines require custom gateway development to communicate with modern Ethernet-based servo gripper controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Servo Gripper Market |
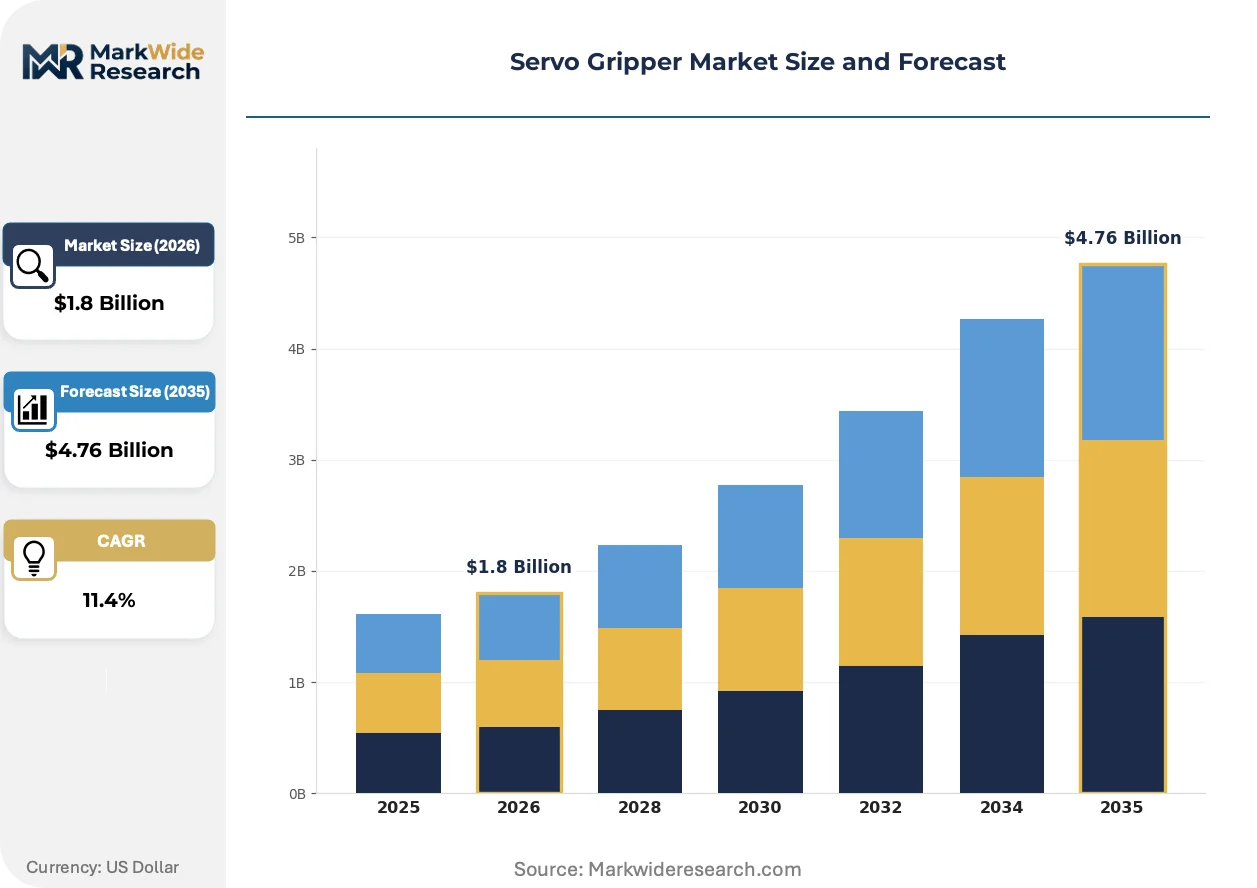
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grippers, Pneumatic Grippers, Mechanical Grippers, Magnetic Grippers End User: Manufacturing, Automotive, Electronics, Food & Beverage Technology: AI-Driven, Vision-Based, Force-Sensitive, Customizable Application: Assembly, Packaging, Material Handling, Robotics |
| Companies Covered | SCHUNK GmbH & Co. KG, Festo Group, SMC Corporation, Zimmer Group, Yaskawa Electric Corporation, PHD Inc, Effecto Group SpA, T.M. Präzisionstechnik GmbH, Toyo Automation Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Servo Gripper Market Evolving Landscape
Control architectures are migrating toward decentralized intelligence, with processing power shifting from factory-level PLCs to edge-capable end-effectors that execute closed-loop force adjustments in sub-millisecond cycles.
Direct-drive torque motors are eliminating backlash-prone gearboxes from servo gripper joints. Medical device manufacturers in Switzerland and Massachusetts are adopting these systems for sterile assembly environments where lubricant contamination risks exclude traditional transmissions. This hardware simplification is integrating maintenance intervals into annual production shutdowns rather than quarterly service windows.
REACH substance restrictions on PFAS lubricants are compelling gripper manufacturers to reformulate bearing greases and switch to ionic liquid alternatives. The European Chemicals Agency enforcement timeline is compressing supplier qualification schedules, with automotive Tier-1s now demanding material declarations three tiers up the supply chain. German gripper producers are responding by vertically controlling lubricant specification to maintain CE marking continuity.
Buying committees in battery manufacturing are unbundling after-sales service contracts from hardware procurement, selecting specialized regional integrators for deployment support rather than defaulting to OEM service networks. This disintermediation is visible most acutely in Nevada and Hungary, where gigafactory construction timelines outstrip manufacturer field engineering capacity.
Servo Gripper Market Segmentation
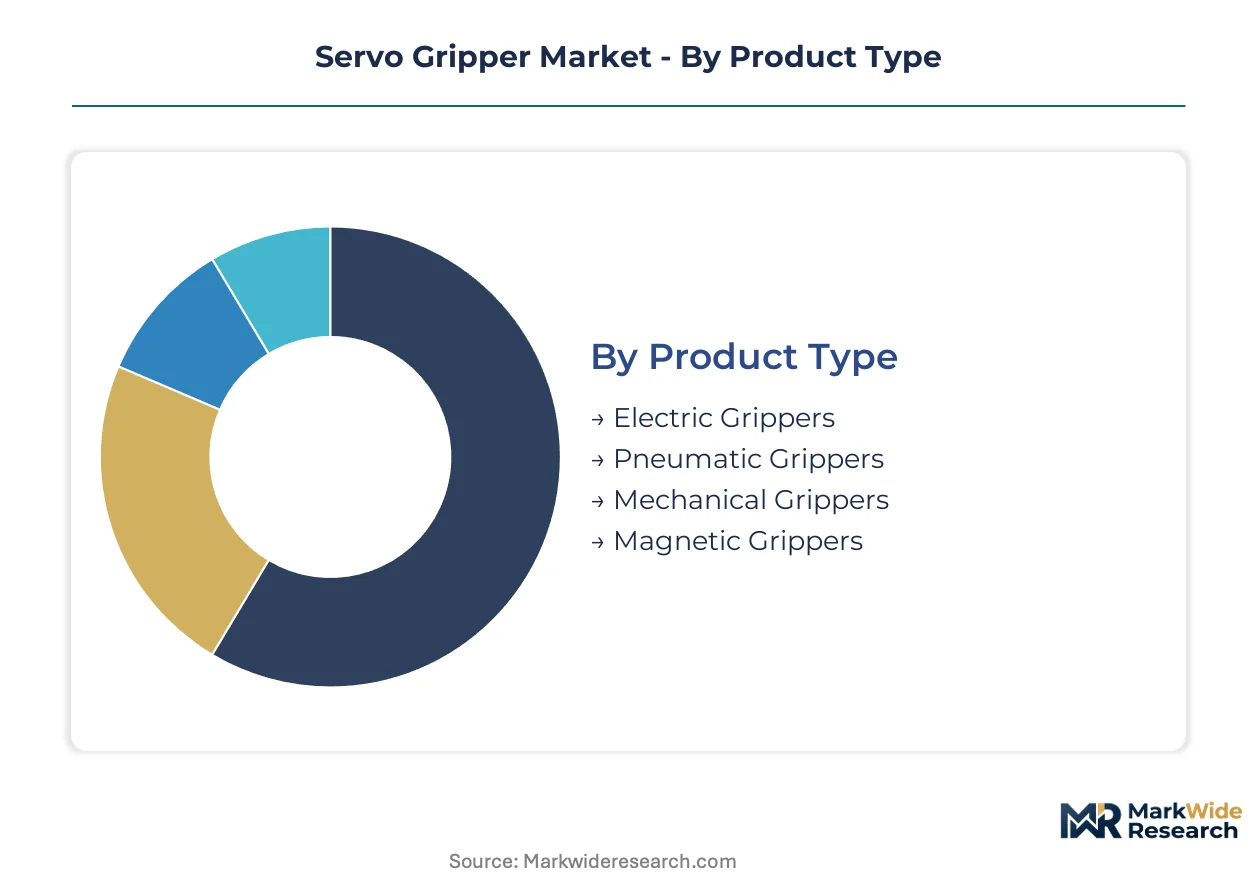
Servo gripper procurement diverges sharply between precision-demanding applications requiring programmable force control and high-throughput operations where speed dominates specification sheets. Segment boundaries are blurring as automotive electrification forces hybrid architectures that combine electric precision with pneumatic cycle rates.
Product Type:
Standardization pressure from automotive OEMs is compressing customization margins, yet battery module handling demands bespoke force curves that resist commoditization.
- Electric Grippers:Servo motor architectures deliver closed-loop position control with sub-0.02 mm repeatability, enabling delicate wafer handling in semiconductor fabrication facilities. German automotive plants are mandating electric systems for collaborative robot deployments under EU Machinery Directive force-limiting requirements.
- Pneumatic Grippers:Compressed air actuation achieves cycle times under 50 milliseconds where existing infrastructure supports high-speed packaging lines. Existing pneumatic networks in East Asian consumer goods factories create switching cost barriers despite precision limitations.
- Mechanical Grippers:Cam-driven and linkage mechanisms persist in legacy stamping press automation where electrical retrofit costs exceed replacement value.
- Magnetic Grippers:Electromagnetic and permanent magnet configurations handle ferrous sheet metal in automotive body shops, eliminating pneumatic hose routing around welding robots.
Most installed capacity flows through Electric Grippers. Expansion is steepest in Vision-Based technology segments.
End User:
Application maturity varies dramatically, with electronics manufacturing demanding micron-level precision while food processing prioritizes washdown compatibility.
- Manufacturing:General industrial automation spans metal fabrication, plastics molding, and assembly operations requiring adaptive gripping for mixed product flows. Discrete manufacturing facilities in Stuttgart and Munich are consolidating supplier relationships around multi-year framework agreements.
- Automotive:Battery module assembly and electric powertrain integration require force-sensitive handling of pouch cells and busbar connections. Merged powertrain-battery facilities are absorbing tenfold volume increases from consolidated production footprints.
- Electronics:Smartphone and semiconductor fabrication demands electrostatic discharge protection and cleanroom-compatible materials in gripper construction.
- Food & Beverage:IP69K washdown ratings and FDA-compliant materials dominate specification sheets for meat processing and dairy packaging lines.
Procurement volumes concentrate in Automotive. Steepest expansion trajectory appears in Electronics as miniaturization accelerates.
Technology:
Edge computing migration is redistributing intelligence from factory PLCs to end-effector embedded processors.
- AI-Driven:Embedded neural inference engines execute real-time grasp planning without external PC dependency, reducing integration costs for small-batch electronics manufacturers. On-gripper machine learning is eliminating teach-pendant programming for variable object geometries.
- Vision-Based:Integrated camera and lighting modules perform 3D point cloud generation for bin picking unstructured parts. Edge processor price declines are democratizing vision capability to mid-tier integrators previously priced out of robotic guidance.
- Force-Sensitive:Strain gauge and piezoelectric feedback enable collaborative robot safety certification under ISO 10218 requirements. European market entry demands extensive third-party testing extending launch cycles.
- Customizable:Modular finger geometries and quick-change jaw systems support mixed-model production with sub-minute changeover intervals.
Deployment volumes favor Force-Sensitive systems. AI-Driven architectures are climbing fastest as semiconductor inference engines penetrate price-sensitive tiers.
Application:
Task specificity determines actuator selection, with assembly demanding precision and material handling prioritizing payload capacity.
- Assembly:Precision insertion and fastening operations require force-torque sensing to prevent component damage during delicate operations. Medical device manufacturers in Switzerland specify sterile-compatible direct-drive architectures.
- Packaging:High-speed case packing and palletizing operations exploit pneumatic velocity where product variability remains low. Consumer goods facilities in Hungary are unbundling after-sales service from hardware procurement.
- Material Handling:Bin picking, machine tending, and warehouse logistics span payload ranges from grams to hundreds of kilograms.
- Robotics:Collaborative and mobile robot platforms demand lightweight, low-power consumption end-effectors extending battery-operated duty cycles.
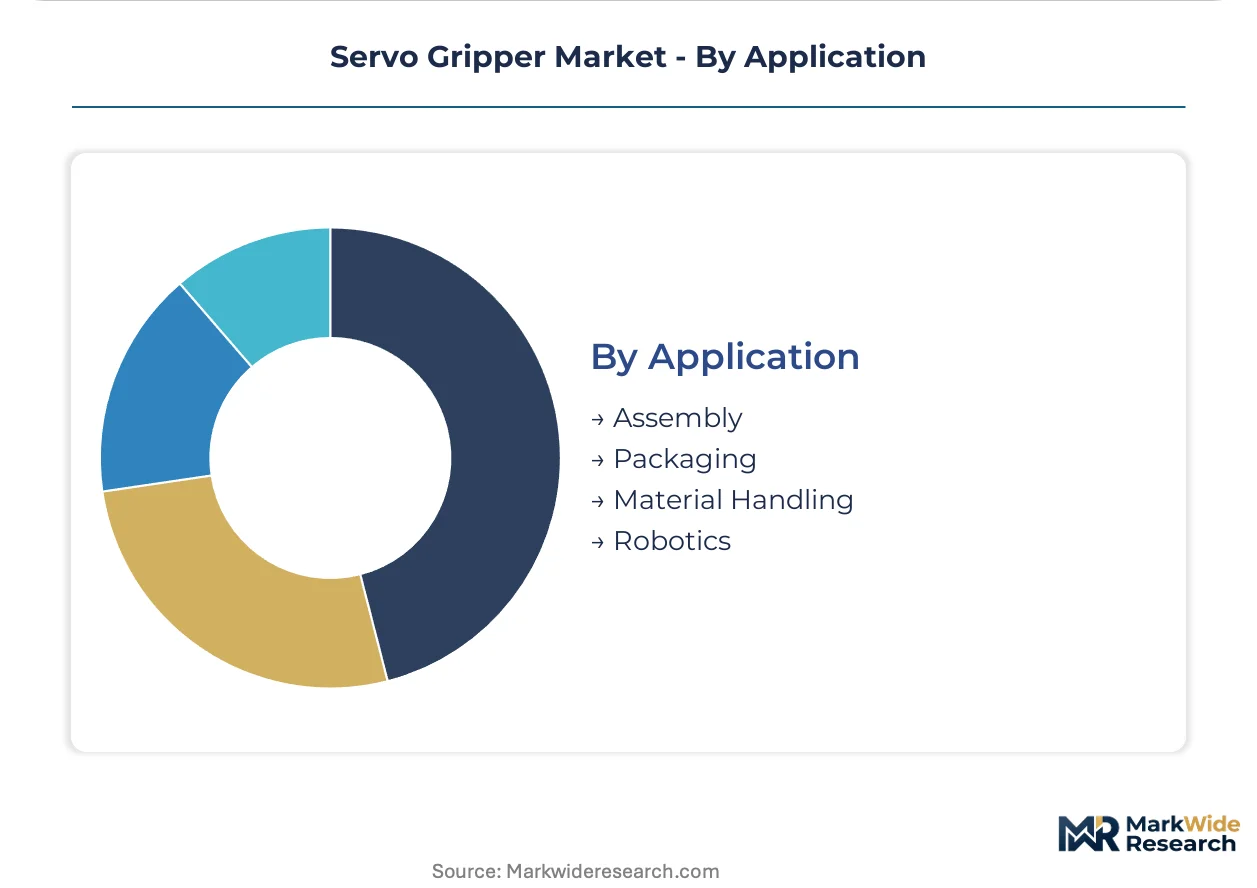
Assembly commands the largest installed base. Material Handling is gaining share fastest as warehouse automation investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor generates denser servo gripper procurement than China's fragmented manufacturing base, while Japan's precision engineering culture sustains premium-tier demand despite smaller absolute volumes.
Germany
Automotive electrification and battery gigafactory construction absorb programmable electric gripper systems at unprecedented scale. EU Machinery Directive 2006/42/EC force-limiting mandates accelerate collaborative robot certification requirements. The Stuttgart-Munich corridor concentrates R&D facilities and Tier-1 supplier headquarters, compressing development cycles for adaptive gripper algorithms.
China
Electric vehicle production scaling and consumer electronics manufacturing drive servo motor demand across multiple industrial clusters. MIIT industrial robot development guidelines and GB standards for collaborative safety shape product certification pathways. Shenzhen and Shanghai manufacturing hubs prioritize high-volume pneumatic-to-electric migration programs despite existing compressed air infrastructure.
United States
Battery manufacturing investment in Nevada and automotive retooling in Michigan create concentrated demand for force-sensitive handling systems. OSHA workplace safety guidelines and emerging collaborative robot standards influence gripper specification requirements. The Great Lakes industrial corridor hosts merged powertrain-battery facilities requiring tenfold volume absorption capacity from suppliers.
Japan
Semiconductor fabrication and precision medical device assembly sustain demand for sub-0.02 mm repeatability systems. METI next-generation robot safety guidelines for eldercare automation create certified-product preferences rewarding early compliance. Nagoya and Osaka manufacturing clusters specialize in direct-drive torque motor architectures for sterile environments.
India
Electronics manufacturing incentives and automotive component localization attract gripper suppliers seeking duty-advantaged domestic supply. PLI scheme production-linked incentives for advanced manufacturing compress supplier establishment timelines. Karnataka and Tamil Nadu industrial corridors host emerging automation integrator ecosystems serving contract electronics manufacturers.
Servo Gripper Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. German and Japanese industrial automation groups anchor premium-tier positioning through integrated motion control portfolios. Three strategic archetypes dominate: full-range platform providers, application-specific module specialists, and regional system integrators with captive gripper fabrication. Competitive moves concentrate on pneumatic-to-electric migration service bundling and collaborative robot safety certification pre-qualification.
Within the precision engineering tier, SCHUNK GmbH & Co. KG and Festo Group exemplify divergent strategic postures—one representing modular electric architecture specialization, the other integrated migration program capabilities. SMC Corporation occupies a position bridging pneumatic legacy infrastructure and electric transition demand across East Asian manufacturing hubs. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific technology or market outcomes.
| Leading Market Players |
|---|
| SCHUNK GmbH & Co. KG |
| Festo Group |
| SMC Corporation |
| Zimmer Group |
| Yaskawa Electric Corporation |
| PHD Inc |
| Effecto Group SpA |
| T.M. Präzisionstechnik GmbH |
| Toyo Automation Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Neodymium magnet costs flow from Chinese processing facilities through servo motor manufacturers to gripper assemblers, with price stratification emerging between rare-earth-tethered premium tiers and ferrite-alternative economy lines serving packaging applications.
Pricing Analysis
Capacity additions in China's rare-earth magnet sector are reshaping price floors for servo motor-dependent electric grippers. Three-tier pricing structure across premium, standard, and economy levels separates force-sensitive collaborative systems from pneumatic-replacement electric units and legacy mechanical grippers. Price differentiation stems from ISO 10218 certification tier and volume scale of automotive contracts. Cost compression in standard-tier electric grippers is intensifying because German Tier-1s are consolidating supplier panels around multi-year framework agreements. Small-batch electronics manufacturers exhibit highest price sensitivity, while battery gigafactory operators absorb premium pricing for force-control precision.
Supply Chain Analysis
Neodymium supply rests on Chinese mining and separation facilities, with Japanese magnet finishing and German motor winding completing the upstream chain. Raw material dependencies span rare-earth oxides, copper windings, and precision bearings from Switzerland and Japan. Single-source vulnerability concentrates in Chinese export quota administration for processed neodymium. Distribution runs through dense distributor networks across East Asian manufacturing hubs, with direct OEM relationships dominating German automotive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI production-linked incentives compress supplier establishment timelines versus EU Machinery Directive compliance costs that extend European product launch cycles by 8-14 months.
For Market Incumbents: Deepen backward integration into rare-earth magnet specification to insulate against Chinese export quota volatility. Anchor high-volume automotive contracts through modular electric architectures that absorb tenfold volume increases from merged powertrain-battery facilities. Certification investment in Japan's METI eldercare guidelines creates certified-product preferences that reward early compliance against emerging pure-play specialists. For New Entrants and Emerging Players: AI-driven embedded vision systems offer a technology-first wedge into small-batch electronics manufacturing where external PC dependencies previously priced out mid-tier integrators. Target India's Karnataka and Tamil Nadu industrial corridors where PLI scheme incentives attract gripper suppliers seeking duty-advantaged domestic supply. Go-to-market angle: unbundle after-sales service from hardware procurement, mirroring Nevada and Hungary gigafactory buying committee preferences. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with captive gripper fabrication because pneumatic-to-electric migration programs create recurring service revenue streams that outstrip hardware margins. Acquisition target archetype: application-specific module specialists in soft robotics convergence for agricultural produce handling. Signal to watch: battery manufacturing procurement committees unbundling service contracts from hardware across additional geographies.| Strategic Initiative | Industry Significance |
|---|---|
| Pneumatic-to-Electric Migration Program | Festo Group's integrated retrofit capabilities capture legacy factory upgrade budgets across East Asian consumer goods facilities. |
| Force-Sensitive Certification Investment | Early ISO 10218 compliance creates European market entry barriers that extend launch cycles for non-compliant competitors. |
| Soft Robotics Convergence R&D | Elastomeric finger surface integration opens food processing applications previously closed to rigid servo actuation architectures. |
| Regional Integrator Acquisition | Specialized deployment support capabilities address Nevada and Hungary gigafactory timelines that outstrip OEM field engineering capacity. |
| Direct-Drive Torque Motor Adoption | Backlash elimination enables Swiss and Massachusetts medical device manufacturers to meet sterile assembly environment requirements. |
Research Methodology
Bottom-up automotive and electronics manufacturing modeling reconciled against top-down servo motor production tracking forms the analytical core. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and automation integrators combined with secondary validation from customs/trade data, SEC 10-K filings, and IHS Markit vehicle production databases. Triangulation across stakeholder inputs and secondary sources ensures segment-level accuracy.
Historical trendline analysis of electric gripper penetration rates against pneumatic legacy installed base informs projection framework construction. Segmentation dimensions span product type, end-use industry, technology tier, and regional production cluster. CAGRs derive from fitted growth curves applied to base-year estimates across the analysis window. Industry-specific forecast inputs include battery gigafactory construction timelines and EU Machinery Directive enforcement intensity.
The model holds under stable rare-earth export quota administration and sustained automotive electrification investment; deviation in Chinese supply policy or EV demand deceleration would shift volume trajectories. Forecasts reflect documented assumptions about regulatory timeline adherence and technology cost curves. A small set of named triggers—neodymium export restrictions, collaborative robot safety standard divergence, and pneumatic infrastructure lock-in persistence—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
Germany Cloud Robotics Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Smart Worker Market