
 Global Effervescent Packaging Market | 2026-2036
Global Effervescent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Effervescent Packaging Market Analysis
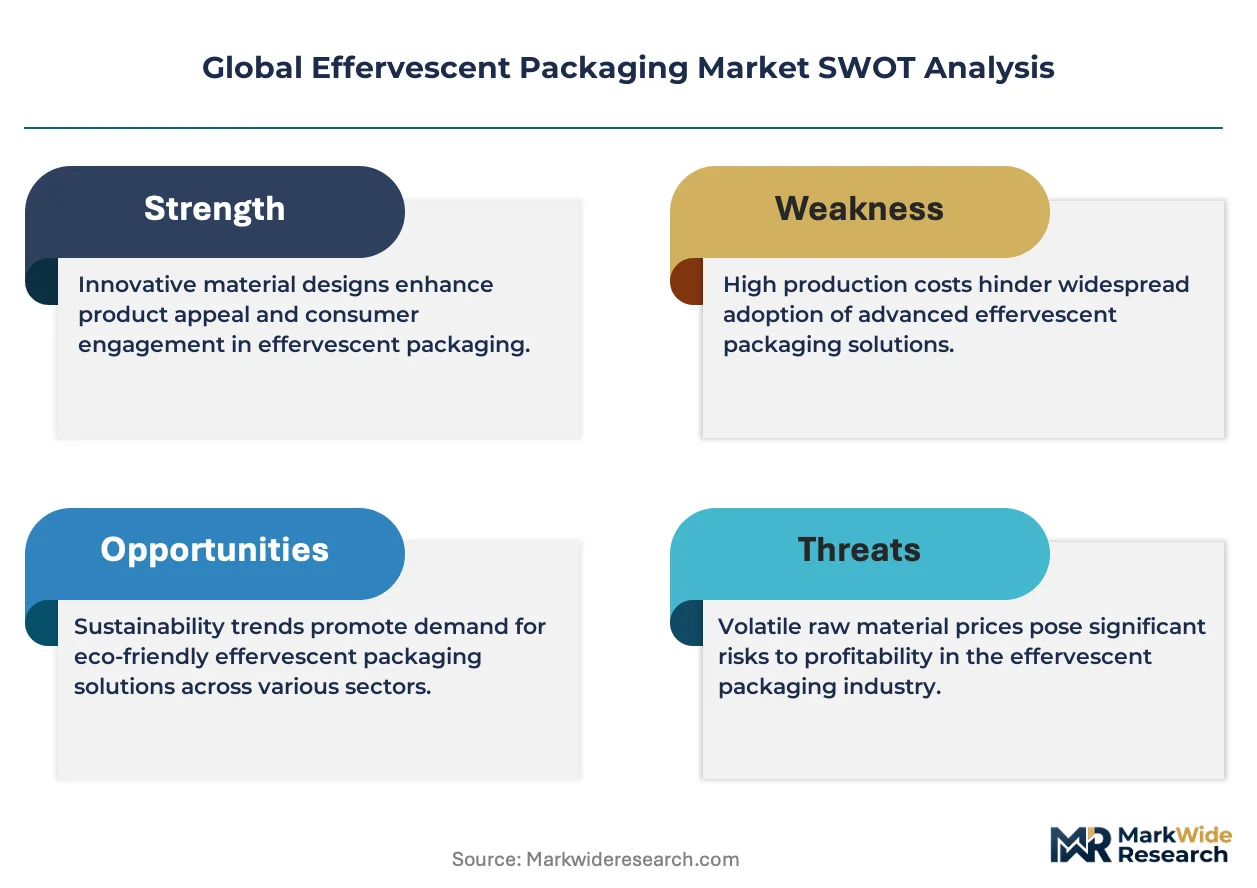
The gap between premium moisture-barrier packaging and commodity-grade wraps is shifting from a price tier into a capability divide. Gerresheimer AG leverages its glass-primary expertise to dominate high-barrier tube and desiccant-cap systems for pharmaceutical effervescents. Amcor Plc competes through global film-lamination scale, while Sanner GmbH anchors its position with German-engineered desiccant polymers for tropical-climate stability.
Effervescent packaging denotes primary and secondary containment systems engineered to exclude moisture, carbon dioxide, and oxygen from reactive carbonate-acid formulations, typically achieving water vapor transmission rates below 0.1 g/m²/day through multi-layer aluminum-polymer laminates or glass with desiccant closures. Its core purpose centers on preserving chemical stability and effervescent reactivity from manufacture through patient or consumer use. Tablet formats lead volume due to established pharmaceutical tooling and dosing precision, though powder and granule segments attract margin as functional beverage applications expand. Plastic and aluminum laminates capture the bulk of unit demand, while glass retains premium positioning for light-sensitive and high-potency pharmaceutical effervescents.
FDA stability guidelines for effervescent drug products, EU MDR requirements for pharmaceutical primary packaging, and REACH restrictions on certain polymer additives collectively elevate barrier-performance standards and narrow the supplier base qualified for regulated markets. Germany's KBA and France's ANSM enforce batch-level traceability that favors integrated converters with serialization infrastructure. Stakeholders must monitor evolving EMA guidance on extractables and leachables testing, as this will determine which material platforms retain market access across European pharmaceutical supply chains.
Market Dynamics
Pharmaceutical serialization mandates and REACH restrictions on fluorinated barrier films are compressing the qualified supplier base while pushing converters toward aluminum-polymer laminates with integrated desiccant functionality.
Growth Catalysts
- EU MDR traceability requirements:Germany's KBA and France's ANSM enforce batch-level serialization that favors integrated converters with track-and-trace infrastructure, locking in long-term supply relationships.
- Tropical-climate pharmaceutical expansion:Demand for moisture-stable effervescent formats in Southeast Asia and Latin America pulls German-engineered desiccant polymer systems into new distribution networks.
- Carbonate-acid formulation innovation:Extended-release effervescent therapeutics require higher-barrier primary packaging, expanding addressable volume for multi-layer aluminum laminates.
Market Restraints
- Aluminum price volatility:Primary aluminum input costs swing with energy-intensive smelter economics, squeezing converter margins on fixed-price pharmaceutical contracts.
- German production cluster concentration:Specialized effervescent tube and desiccant-cap manufacturing concentrates in Rhineland-Palatinate and Bavaria, creating single-source vulnerability for global pharmaceutical supply chains.
- Glass-to-laminate substitution ceiling:High-potency light-sensitive effervescents remain captive to borosilicate glass with desiccant closures, limiting total addressable market expansion for flexible formats.
Strategic Opportunities
- India CDSCO accelerated approval pathways:Domestic pharmaceutical manufacturing incentives under PLI schemes create demand for localized effervescent packaging conversion capacity.
- Functional beverage powder segments:Electrolyte and nootropic effervescent powders in single-serve sachets open margin-rich volume outside regulated drug channels.
- Desiccant-printed film convergence:Integration of moisture-scavenging chemistry directly into sealant layers eliminates separate desiccant canister handling and assembly costs.
Industry Challenges
- EMA extractables and leachables validation timelines:New polymer additive approvals require 18-24 month migration studies, delaying material platform launches.
- Serialization equipment capex intensity:Line-level aggregation and verification hardware demands seven-figure capital deployment per production site.
- Multi-layer laminate recycling compliance:Extended producer responsibility frameworks in France and Germany force redesign for separable material streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Effervescent Packaging Market |
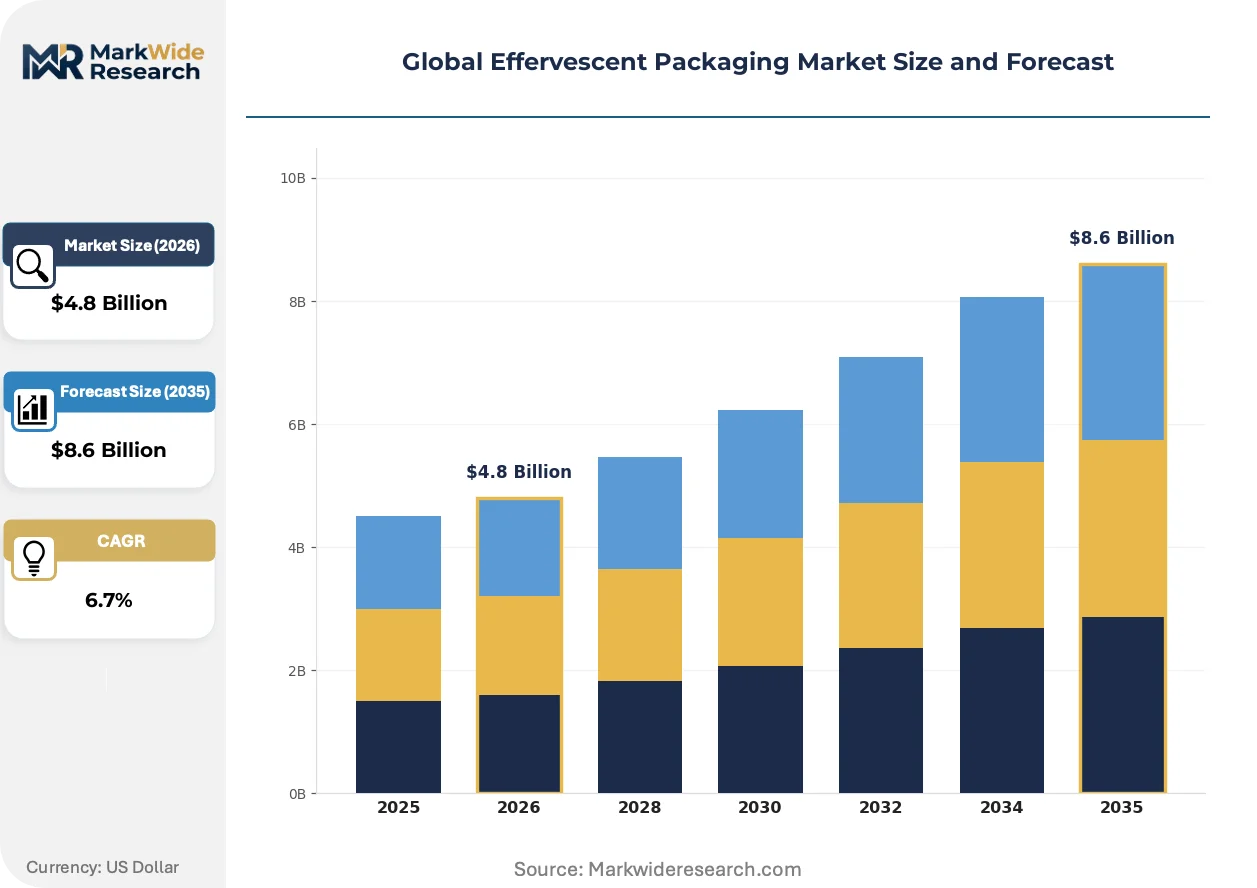
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powders, Granules, Capsules Material: Plastic, Glass, Aluminum, Paper End Use Industry: Pharmaceutical, Food & Beverage, Personal Care, Cleaning Products Technology: Direct Compression, Freeze Drying, Spray Drying, Coating |
| Companies Covered | Gerresheimer AG, Amcor Plc, Romaco Pharmatechnik GmbH, Berry Global Inc., Sanner GmbH, Constantia Flexibles Group GmbH, WestRock Company, AptarGroup Inc., Unither Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Effervescent Packaging Market Emerging Trajectories
Barrier material science and regulatory chemistry requirements are converging to reshape how effervescent formats achieve moisture exclusion, with implications for converter equipment footprints and pharmaceutical qualification timelines.
Desiccant-integrated coextruded films are decentralizing the traditional two-step process of primary packaging plus separate desiccant insertion. Pharmaceutical contract packagers in Germany and Switzerland are adopting these films for high-volume vitamin effervescents, collapsing assembly stations and reducing line changeover downtime. The structural consequence is compression of mid-tier converters lacking coextrusion capability.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating high-barrier fluoropolymer coatings from European pharmaceutical packaging workflows. Converters are pivoting to aluminum oxide vapor-deposited polyester laminates that achieve comparable water vapor transmission rates without regulated chemistry. The segment most affected is tropical-stability effervescents, where German and French manufacturers are accelerating EMA leachables dossier preparation.
Hospital and pharmacy procurement consolidation is compressing supplier rosters for effervescent pharmaceutical packaging. Large German pharmacy chains and French hospital purchasing groups are mandating direct-to-distributor serialization and aggregated quality documentation, displacing fragmented local converter relationships. This concentration is most visible in the DACH region, where three pharmacy cooperatives control majority procurement volume for OTC effervescents.
Global Effervescent Packaging Market Segmentation
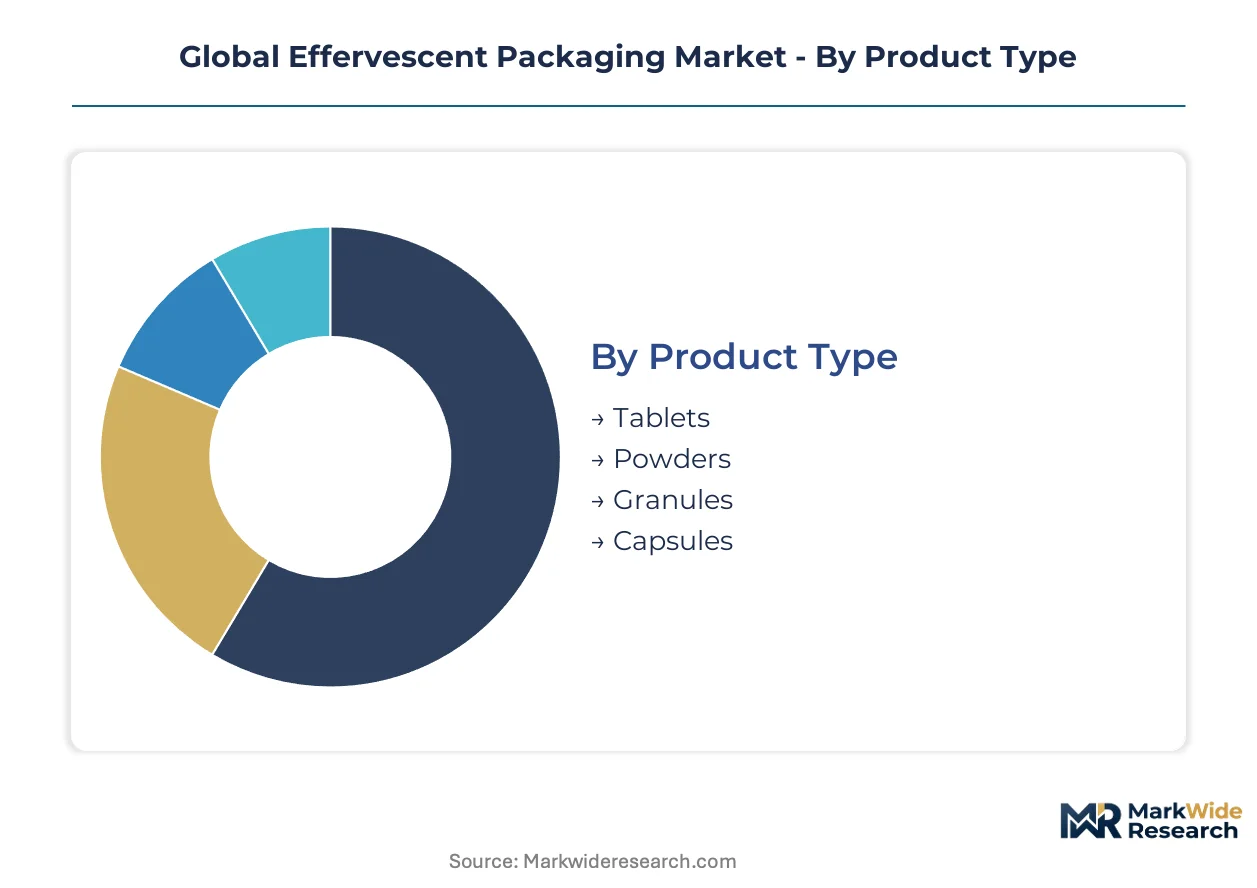
Effervescent packaging segmentation reveals how regulatory burden distributes unevenly across material platforms and end-use channels. Pharmaceutical-grade formats demand EMA leachables dossiers and FDA stability validation, while food and beverage applications operate under lighter FSSAI and FDA food-contact frameworks.
Product Type:
Pharmaceutical tablets require the most intensive certification pathway, with EU MDR batch-level traceability and tropical-stability validation for carbonate-acid formulations driving qualification timelines.
- Tablets:Established pharmaceutical tooling enables precise dosing for prescription effervescents. Demand concentrates in Germany and Switzerland, where Gerresheimer and Sanner anchor specialized tube production for moisture-sensitive formats. EMA extractables requirements and KBA serialization mandates compress the qualified supplier base for this segment.
- Powders:Single-serve sachets for electrolyte and nootropic applications use multi-layer aluminum-polymer laminates with integrated desiccant functionality. Functional beverage brands in Southeast Asia and Latin America pull German-engineered desiccant polymer systems into expanded distribution networks.
- Granules:Intermediate format for pediatric and geriatric dosing flexibility.
- Capsules:Niche positioning for controlled-release effervescent therapeutics.
Leading the category by volume: Tablets. Growing fastest: Powders.
Material:
Cost tiers separate premium moisture-barrier systems from commodity wraps, with aluminum-polymer laminates commanding price premiums over standard plastic films.
- Plastic:Polypropylene and polyethylene terephthalate films serve cost-sensitive vitamin effervescents with moderate barrier requirements. REACH restrictions on fluorinated coatings push converters toward aluminum oxide vapor-deposited alternatives.
- Glass:Borosilicate tubes with desiccant closures retain captive demand for high-potency light-sensitive pharmaceuticals. German and Swiss manufacturers maintain premium positioning despite higher unit costs.
- Aluminum:Multi-layer laminates with aluminum foil cores achieve water vapor transmission rates below 0.1 g/m²/day.
- Paper:Limited to outer secondary packaging with moisture-barrier overwrap requirements.
Highest certification burden: Glass. Steepest expansion trajectory: Aluminum laminates.
End Use Industry:
Application maturity determines whether segments face pharmaceutical serialization mandates or lighter consumer goods regulation.
- Pharmaceutical:Primary packaging for prescription and OTC effervescents demands EMA leachables validation and FDA stability compliance. Hospital and pharmacy procurement consolidation in Germany and France compresses supplier rosters for this segment.
- Food & Beverage:Electrolyte powders and functional drink mixes operate under FDA food-contact and FSSAI frameworks with reduced testing burdens.
- Personal Care:Effervescent bath tablets and skincare formats.
- Cleaning Products:Household effervescent tablets for detergent applications.
Most regulated segment: Pharmaceutical. Expanding most quickly: Food & Beverage.
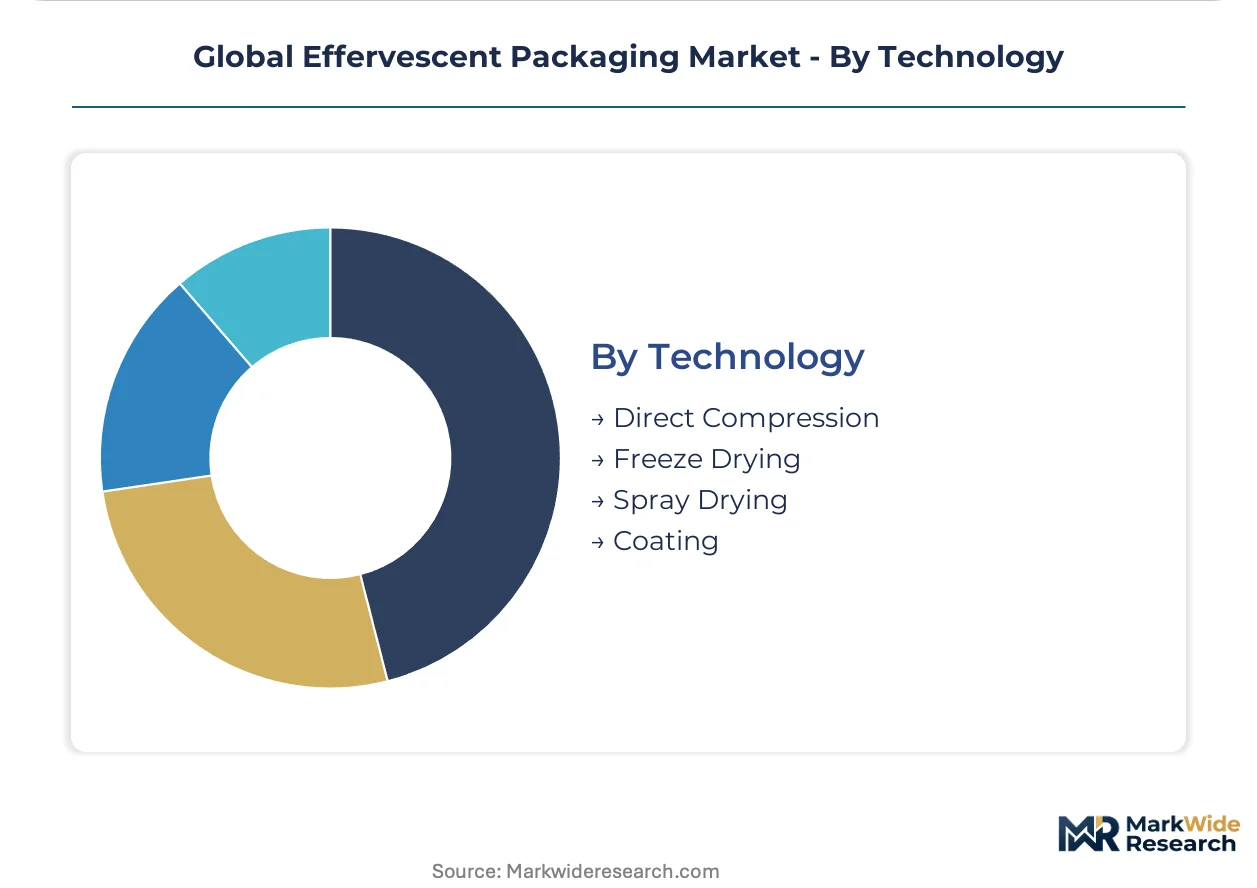
Technology:
Manufacturing process selection correlates with barrier-performance requirements and customer scale.
- Direct Compression:Dominant tableting method for high-volume pharmaceutical production. German contract packagers adopt desiccant-integrated coextruded films to collapse assembly stations and reduce line changeover downtime for direct-compression formats.
- Freeze Drying:Preserves effervescent reactivity in heat-sensitive formulations for tropical-distribution stability.
- Spray Drying:Enables powder granulation with controlled particle size distribution.
- Coating:Applied for moisture-resistant outer layers on effervescent cores.
Dominant by volume: Direct Compression. Gaining share fastest: Freeze Drying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhineland-Palatinate anchors specialized effervescent tube manufacturing, with German converters supplying moisture-barrier systems to pharmaceutical networks across three continents.
Germany
KBA serialization mandates and EU MDR batch-level traceability requirements pull demand toward integrated converters with track-and-trace infrastructure. REACH restrictions on fluorinated barrier films push manufacturers toward aluminum-polymer laminates with desiccant functionality. Production clusters in Bavaria and Rhineland-Palatinate concentrate specialized tube and desiccant-cap manufacturing for tropical-climate pharmaceutical exports.
United States
FDA stability guidelines for effervescent drug products elevate barrier-performance standards for prescription and OTC formats. Hospital procurement consolidation and pharmacy benefit manager integration compress supplier rosters. Contract packaging hubs in New Jersey and Pennsylvania specialize in high-volume vitamin effervescents with integrated desiccant film systems.
India
CDSCO accelerated approval pathways under PLI schemes create demand for localized effervescent packaging conversion capacity. Domestic pharmaceutical manufacturing incentives pull German-engineered desiccant polymer systems into joint venture arrangements. Mumbai-Pune and Ahmedabad clusters emerge as contract packaging centers for Southeast Asian and African export markets.
Switzerland
Swissmedic requirements for pharmaceutical primary packaging maintain premium positioning for borosilicate glass with desiccant closures. High-potency light-sensitive effervescents remain captive to German-Swiss glass-primary expertise. Basel and Zurich regions concentrate specialized tube finishing and serialization infrastructure for regulated European supply chains.
France
ANSM enforcement of batch-level traceability favors integrated converters with aggregation and verification hardware. Hospital purchasing group consolidation in the Île-de-France and Auvergne-Rhône-Alpes regions displaces fragmented local converter relationships. Paris and Lyon hubs specialize in tropical-stability validation for carbonate-acid formulations distributed to former colonial markets.
Global Effervescent Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and serialization capability. The qualified supplier base compresses as EMA extractables validation timelines and REACH fluoropolymer restrictions eliminate mid-tier converters lacking coextrusion infrastructure. Three archetypes dominate: glass-primary specialists with desiccant-closure integration, global film-lamination scale players, and German-engineered desiccant polymer system providers. Competitive moves concentrate on strategic partnerships for tropical-climate validation and capacity expansion into Indian pharmaceutical manufacturing zones.
Among Germany-based specialists, Gerresheimer AG and Sanner GmbH exemplify the premium-tier archetype through Rhineland-Palatinate and Bavaria production concentration. Amcor Plc occupies a position as the scale-driven film-lamination anchor with global converter networks. Romaco Pharmatechnik GmbH represents the equipment-integrated packaging system provider archetype, sitting within the German machinery corridor that supplies complete effervescent packaging lines.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Amcor Plc |
| Romaco Pharmatechnik GmbH |
| Berry Global Inc. |
| Sanner GmbH |
| Constantia Flexibles Group GmbH |
| WestRock Company |
| AptarGroup Inc. |
| Unither Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap converters in Rhineland-Palatinate and Bavaria anchor pricing discipline through captive desiccant-polymer formulation expertise, limiting price transparency and forcing pharmaceutical buyers into long-term offtake relationships rather than spot-market procurement.
Pricing Analysis
Value-based pricing anchored to tropical-stability outcomes dominates pharmaceutical-grade contracts, with German-engineered desiccant systems commanding premiums tied to EMA leachables validation status rather than commodity aluminum input costs. Certification tier and volume scale drive price differentiation, with KBA-serialization-qualified converters extracting margin premiums over non-integrated competitors. Cost compression in standard-grade vitamin effervescents is intensifying because REACH fluoropolymer restrictions force material platform conversions without immediate pass-through mechanisms. Hospital purchasing groups exhibit lowest price sensitivity due to consolidated procurement mandates, while functional beverage brands show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Frankfurt-Rhine-Main and Rotterdam-Antwerp handle hub-and-spoke patterns for European pharmaceutical networks, with secondary spokes extending to Mumbai-Pune and São Paulo for tropical-climate markets. Manufacturing concentrates in Germany, Switzerland, and India, with raw material dependencies on primary aluminum from Norwegian smelters, polyester films from Belgium, and molecular sieve desiccants from Japan. Single-source vulnerability runs through Rhineland-Palatinate tube finishing capacity. Distribution runs through pharmaceutical contract packagers with integrated serialization infrastructure rather than open-market wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over desiccant-polymer formulation chemistry separates premium-tier converters from margin-compressed assemblers.
For Market Incumbents: Anchor position through backward integration into aluminum oxide vapor-deposition capacity and captive desiccant-printed film production, eliminating separate canister assembly stations. EMA extractables validation timelines compress the qualified supplier base; incumbents should lock in 18-24 month leachables dossier pipelines before REACH restrictions eliminate fluoropolymer alternatives entirely. For New Entrants and Emerging Players: CDSCO accelerated approval pathways in India open a window for localized conversion capacity serving PLI-scheme pharmaceutical manufacturers with German-engineered desiccant polymer systems through joint venture structures. Functional beverage powder segments in Southeast Asia offer the most penetrable white space, with single-serve sachet demand outpacing qualified local supply. Go-to-market through direct relationships with electrolyte and nootropic brand owners bypasses entrenched pharmaceutical procurement gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with coextrusion infrastructure but incomplete serialization compliance in Germany and Switzerland, where KBA and Swissmedic mandates have stranded assets lacking seven-figure aggregation hardware investment. Long-term viability hinges on EMA guidance finalization around extractables testing protocols. Watch for leachables dossier submission volumes as the inflection signal for which material platforms retain market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desiccant Film Coextrusion | Eliminates separate canister handling and collapses assembly station footprints for German contract packagers. |
| EMA Leachables Dossier Preparation | Secures market access for aluminum oxide vapor-deposited laminates before REACH fluoropolymer phase-out deadlines. |
| Joint Venture in Indian Pharmaceutical Clusters | Captures CDSCO pathway demand from PLI-scheme manufacturers targeting Southeast Asian export markets. |
| Serialization Infrastructure Deployment | Meets KBA and ANSM batch-level traceability mandates required by consolidated pharmacy procurement groups. |
| Functional Beverage Channel Expansion | Diversifies revenue beyond regulated pharmaceuticals into electrolyte and nootropic powder sachets with lighter FSSAI frameworks. |
Methodological Framework
Trade flow databases, EMA regulatory submission records, and pharmaceutical packaging customs declarations formed the secondary backbone, supplemented by primary interviews with effervescent contract packaging directors, desiccant polymer R&D leads, hospital GPO procurement managers, and pharmacy cooperative formulary directors. Bottom-up and top-down triangulation validated volume estimates across material platforms and end-use channels.
Bottom-up modeling tracked individual converter capacity and utilization rates, while top-down analysis cross-referenced pharmaceutical effervescent dosage form production data against packaging yield coefficients. Segmentation dimensions included product type, material platform, end-use industry, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves for tropical-stability pharmaceutical exports and functional beverage powder adoption trajectories. Aluminum price volatility and REACH compliance cost curves fed scenario-weighted projections.
Caveats apply where EMA extractables guidance revisions or aluminum smelter energy cost shocks could materially shift the outlook for converter margin structures and qualified supplier base composition. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Carton Form Fill Seal Machine Market
Packaging
Hand Sealers Market
Packaging
Case Packing Machines Market
Packaging
Coding and Marking Equipment Market
Packaging
Cement Packaging Market
Packaging
Europe Food Contract Manufacturing and Packaging Market
Packaging
Kraft Paper Shopping Bag Market
Packaging
Hermetic Storage Bags Market
Packaging
Polystyrene Packaging Market
Packaging
Plastic Tamper Evident Closures Market
Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Packaging
Anti-Static Polyethylene Bag Market
Packaging
Printed Plastic Films Market
Packaging
Beverage Metal Cans Market
Packaging
Asia-Pacific Pouch Packaging Market
Packaging
Germany Glass Packaging Market