
 Corrugated Plastic Box Market | 2026-2036
Corrugated Plastic Box Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Plastic Box Market Outlook
ISO 18601 packaging and environment standards is reorganizing competitive access across the corrugated plastic box supply base. DS Smith leverages its European recycling infrastructure to meet closed-loop packaging mandates. Coroplast anchors North American production through extrusion capabilities that sustain consistent flute geometry for automated handling systems.
Corrugated plastic boxes consist of twin-wall polypropylene or polyethylene sheets formed with fluted cores between flat liner layers, typically extruded in thicknesses from 2 mm to 12 mm to achieve specific load-bearing and impact-resistance parameters. These containers serve industrial and commercial sectors requiring moisture-resistant, reusable transport packaging that outlasts corrugated fiberboard in closed-loop supply chains. The food storage application within the application dimension leads volume absorption as cold-chain operators replace wax-coated cardboard with washable, FDA-compliant polypropylene totes. E-commerce shipping represents the fastest-expanding segment as last-mile distributors adopt foldable, collapsible designs to reduce reverse logistics cube and fuel burn per delivery cycle.
FDA food-contact regulations and EU REACH chemical compliance frameworks shape material formulation choices and colorant restrictions for manufacturers serving pharmaceutical and food end users. EPA recycled content guidelines in the United States and Japan's METI resource circulation policies further direct R&D investment toward post-industrial and post-consumer feedstock integration. Stakeholders must track evolving extended producer responsibility schemes and determine whether regional recycling infrastructure maturity justifies premium pricing for certified circular-grade resin formulations.
Market Dynamics
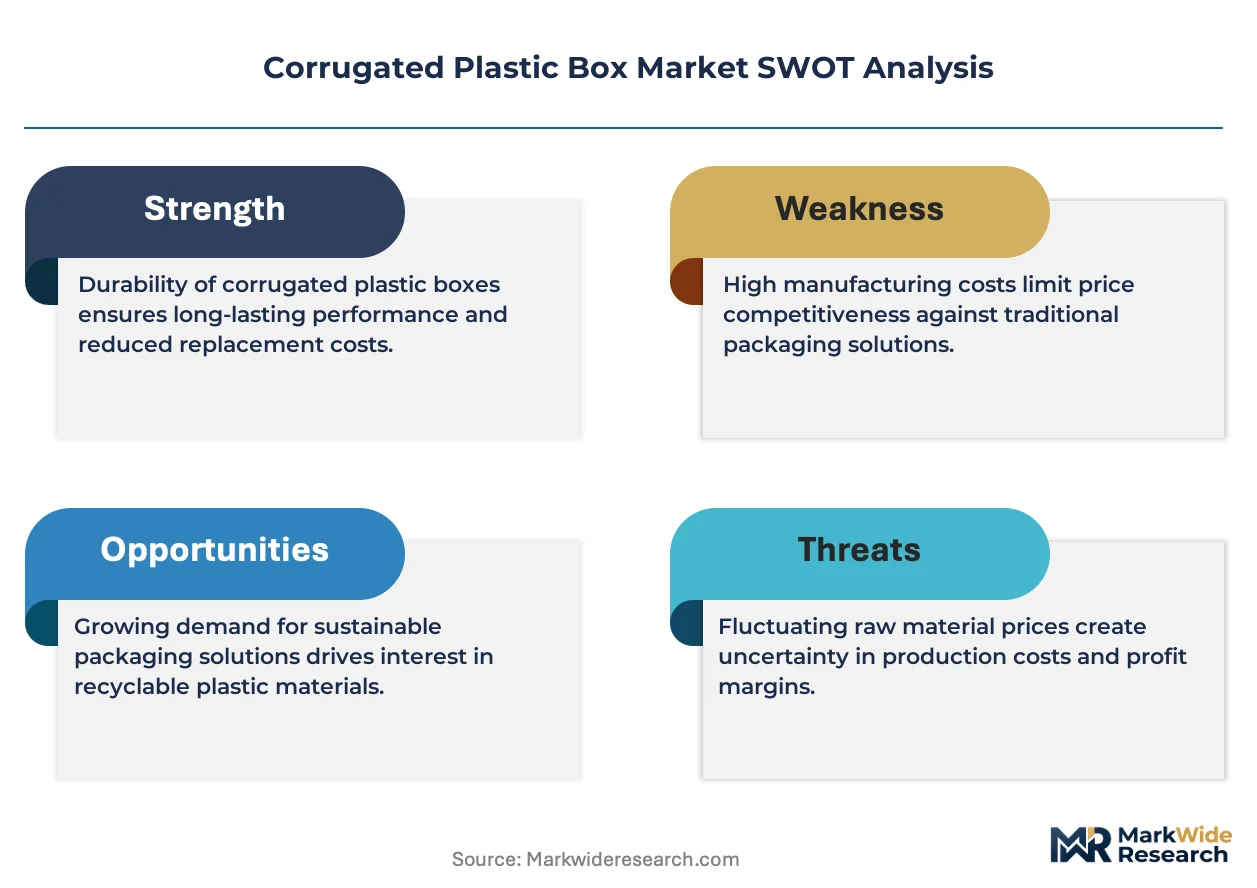
Closed-loop supply chain mandates from EU packaging waste directives are forcing automotive and electronics manufacturers to replace single-use fiberboard with returnable corrugated plastic containers, compressing replacement cycles and reshaping procurement specifications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Automotive parts suppliers in Germany and France must achieve reusable packaging ratios that favor twin-wall polypropylene totes over expendable alternatives.
- China's e-commerce logistics density:Foldable, lightweight totes withstand multi-cycle handling across warehouse-to-doorstep distribution networks in Shanghai and Shenzhen.
- Cold-chain food safety:FDA-compliant polypropylene boxes replace wax-coated cardboard in temperature-controlled distribution, eliminating fiberboard contamination risks.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings tied to naphtha and propylene monomer markets compress converter margins unpredictably.
- Extrusion equipment concentration:High-capacity twin-screw extruders for consistent flute geometry concentrate among German and Austrian machinery suppliers.
- Corrugated fiberboard cost floor:Recycled paperboard maintains price advantage for single-trip applications in low-margin agricultural distribution.
Strategic Opportunities
- India's pharmaceutical cold chain:CDSCO compliance requirements for drug distribution create demand for washable, trackable insulated totes in Mumbai and Hyderabad.
- Japan's METI resource circulation policies:Container recycling laws incentivize domestic manufacturing of returnable packaging with embedded RFID tracking.
- Automated warehouse convergence:Integration of machine-vision sorting with standardized foldable designs enables touchless handling in distribution centers.
Industry Challenges
- Flute geometry calibration:Maintaining consistent crush resistance across extrusion runs requires specialized polymer rheology expertise that remains scarce.
- Post-consumer resin certification:EPA recycled content guidelines demand chain-of-custody documentation that extends batch tracking to raw material origins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Plastic Box Market |
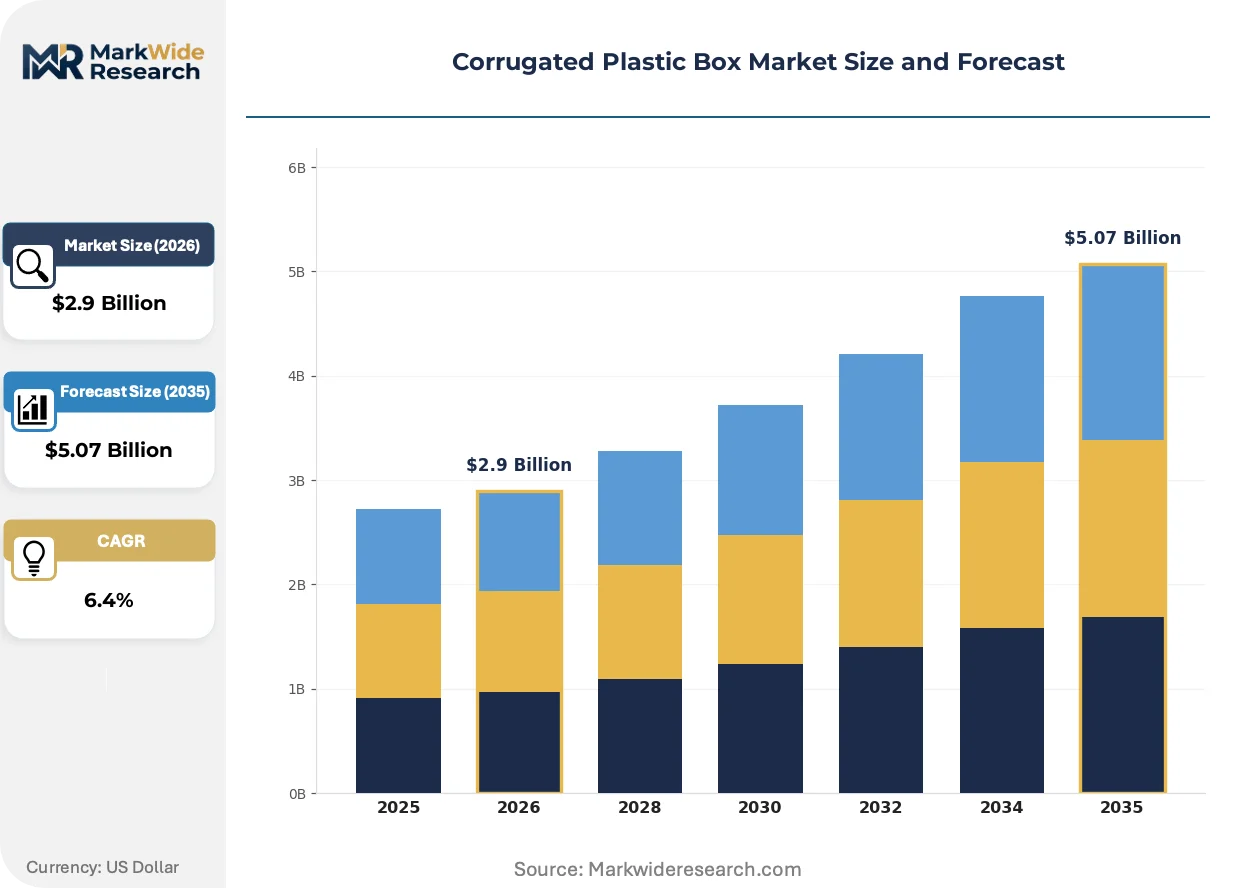
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Pallets, Bins End User: Retail, Agriculture, Automotive, Pharmaceuticals Packaging Type: Reusable, Disposable, Foldable, Customizable Application: Food Storage, Industrial Packaging, Shipping, E-commerce |
| Companies Covered | DS Smith, Coroplast, Inteplast Group, Penda Corporation, Primex Plastics, NW Packaging, Tulox Plastics, Sohner Plastics, Universal Package, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Plastic Box Market Strategic Shifts
Material science advances and regulatory compliance automation are compressing product development timelines while expanding the functional envelope of returnable packaging beyond traditional load-bearing parameters.
Co-extruded barrier layers incorporating ethylene vinyl alcohol are decomposing the historical trade-off between moisture resistance and recyclability in food-contact applications. Cold-chain operators in the Netherlands and Denmark are specifying these constructions for pharmaceutical distribution. The technology is decomposing incumbent wax-coated fiberboard's remaining foothold in temperature-sensitive logistics.
EU REACH chemical compliance frameworks now mandate substance-of-very-high-concern screening across entire packaging supply chains. Manufacturers serving pharmaceutical and food end users must reformulate colorants and stabilizers to eliminate restricted phthalates and heavy metal pigments. German automotive suppliers are accelerating supplier audits to preempt registration deadlines.
Leasing models for returnable packaging assets are replacing outright purchase in European electronics distribution. Third-party pool operators in the Netherlands now manage container fleets for Philips and ASML, absorbing utilization risk and reverse logistics coordination. This shift concentrates procurement authority among specialized fleet managers rather than end-user packaging engineers.
Corrugated Plastic Box Market Segmentation
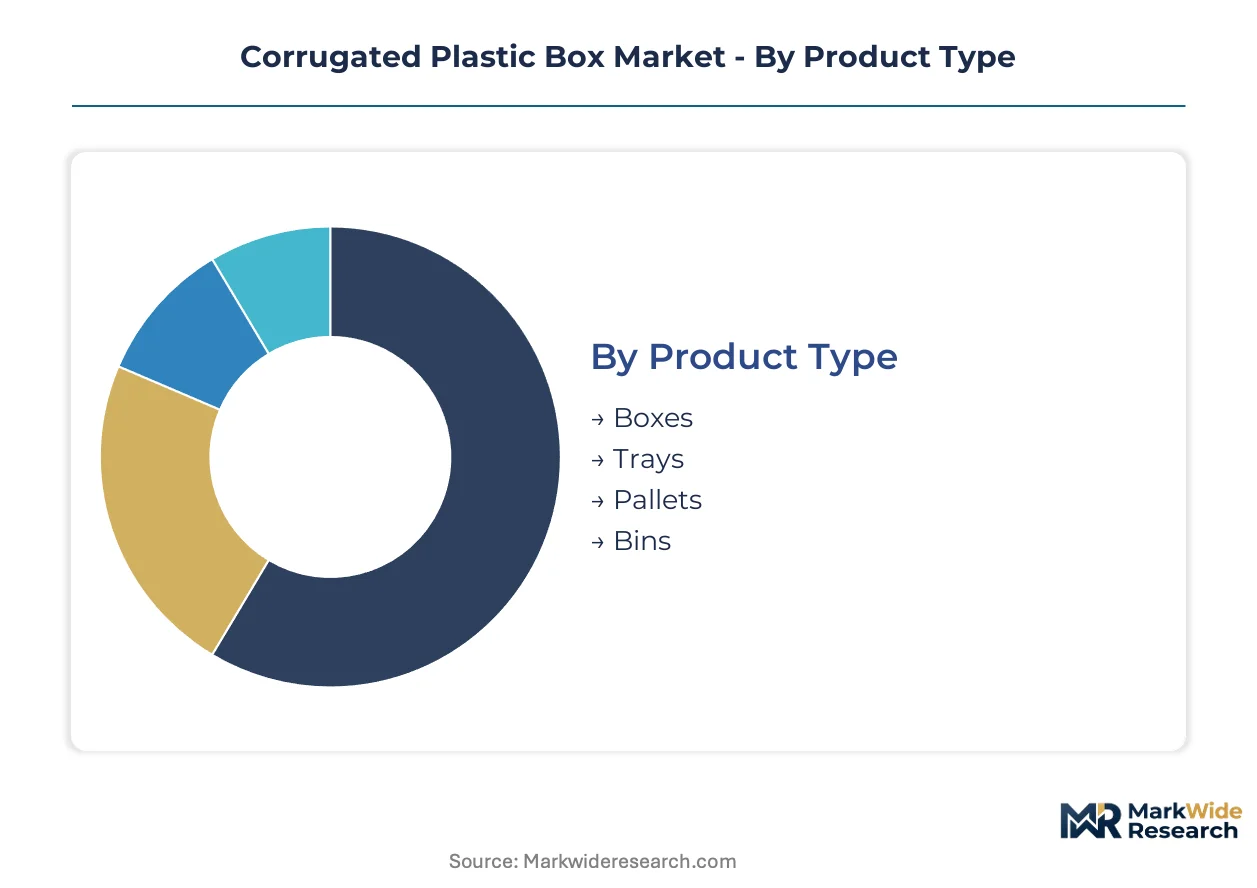
Corrugated plastic box procurement specifications diver sharply across end-use sectors, with FDA food-contact mandates and EU automotive returnable packaging directives creating incompatible performance thresholds that reshape converter product portfolios.
Product Type:
Corrugated fiberboard substitution pressure concentrates on pallets and bins, where load-bearing specifications and multi-cycle durability requirements expose paperboard performance gaps most severely.
- Boxes:Twin-wall polypropylene sheets extruded in 3-10 mm thicknesses form the standard tote configuration for automated handling systems. Cold-chain operators in the Netherlands and Denmark specify co-extruded barrier layers for pharmaceutical distribution, displacing wax-coated fiberboard in temperature-sensitive lanes.
- Trays:Shallow-depth designs with reinforced corner posts serve layer-picking operations in electronics distribution centers. Philips and ASML procurement specifications in the Netherlands now mandate RFID-embedded tray formats for automated warehouse convergence.
- Pallets:Rackable twin-sheet constructions withstand 1,500+ kg dynamic loads across closed-loop automotive supply chains.
- Bins:Collapsible bulk containers with drop-down access panels dominate agricultural harvest collection in California's Central Valley.
Boxes anchor the volume base while bins gain share at the steepest rate.
End User:
Cost-tier stratification separates premium-certified pharmaceutical demand from price-sensitive agricultural procurement, with automotive and retail occupying intermediate positions.
- Automotive:Returnable packaging mandates from Germany's KBA compliance frameworks force tier-one suppliers to achieve reusable container ratios above single-use fiberboard thresholds. BMW and Volkswagen procurement specifications in Bavaria and Lower Saxony now exclude expendable alternatives for inbound parts logistics.
- Pharmaceuticals:CDSCO compliance requirements in Mumbai and Hyderabad drive demand for washable, trackable insulated totes with embedded temperature loggers. FDA 21 CFR food-contact regulations and EU REACH chemical compliance frameworks impose colorant and stabilizer restrictions that elevate material costs.
- Retail:Last-mile distributors adopt foldable designs to reduce reverse logistics cube.
- Agriculture:Seasonal harvest collection in California and Florida prioritizes lowest-unit-cost procurement.
Automotive anchors the volume base while pharmaceuticals climbs the fastest.
Packaging Type:
Application maturity separates established reusable pool systems from emerging customizable formats serving short-run e-commerce requirements.
- Reusable:Third-party pool operators in the Netherlands manage container fleets under leasing models that absorb utilization risk and reverse logistics coordination. EU packaging waste directives compress replacement cycles by mandating minimum reuse thresholds.
- Foldable:Collapsible designs with hinge-integrated sidewalls reduce return-trip cube by 70% in Shanghai and Shenzhen e-commerce distribution networks. China's logistics density favors lightweight twin-wall polypropylene over heavier alternatives.
- Customizable:Short-run digital printing and modular divider systems serve promotional and seasonal requirements.
- Disposable:Single-trip formats retain cost advantage in low-margin agricultural distribution.
Reusable formats anchor the volume base while foldable designs expand most quickly.
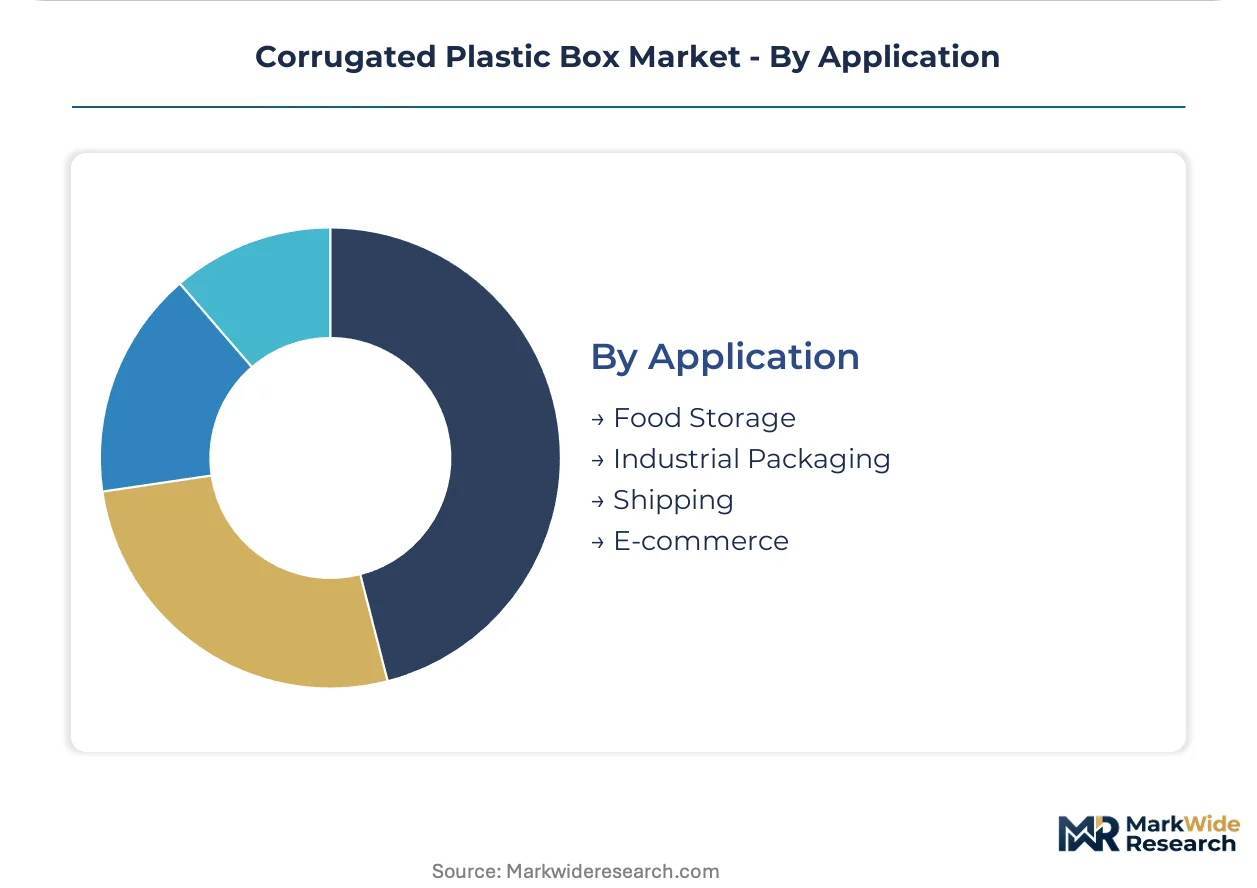
Application:
Volume concentration in food storage contrasts with margin expansion in e-commerce, where last-mile efficiency requirements justify premium pricing.
- Food Storage:FDA-compliant polypropylene totes replace wax-coated cardboard in temperature-controlled distribution, eliminating fiberboard contamination risks. Cold-chain operators specify washable surfaces that withstand sanitizer exposure across multi-year service lives.
- E-commerce:Last-mile distributors in China's warehouse-to-doorstep networks adopt collapsible designs to reduce fuel burn per delivery cycle. Foldable formats with machine-vision-readable barcodes enable touchless handling in automated sortation facilities.
- Industrial Packaging:Automotive and electronics manufacturers specify crush-resistant flute geometry for automated conveyor systems.
- Shipping:Multi-modal freight applications demand impact resistance across truck-rail-air interchanges.
Food storage anchors the volume base while e-commerce shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive procurement engineers in Germany and electronics logistics managers in the Netherlands drive premium specification demand, while e-commerce fulfillment operators in China and cold-chain distributors in the United States absorb volume at scale.
United States
FDA food-contact compliance mandates and EPA recycled content guidelines reshape material formulation priorities for cold-chain operators. California's Central Valley agricultural clusters specify collapsible bulk containers with drop-down access panels for harvest collection. Texas-based automotive suppliers adopt rackable twin-sheet pallets to withstand dynamic loads across inbound parts logistics.
Germany
BMW and Volkswagen procurement specifications in Bavaria and Lower Saxony exclude expendable fiberboard for reusable packaging ratios. KBA compliance frameworks force tier-one suppliers toward returnable container systems. E-commerce pool operators in the Ruhr region manage RFID-embedded fleets under leasing models that absorb utilization risk.
China
Shanghai and Shenzhen warehouse-to-doorstep networks favor foldable, lightweight totes that reduce reverse logistics cube. MIIT industrial standards and dual carbon goals accelerate domestic manufacturing of recyclable transport packaging. Yangtze River Delta logistics density sustains multi-cycle handling requirements at scale.
Netherlands
Philips and ASML procurement specifications mandate RFID-embedded tray formats for automated warehouse convergence. EU packaging waste directives compress replacement cycles through minimum reuse thresholds. Randstad-based third-party pool operators manage container fleets that coordinate reverse logistics across electronics distribution networks.
Japan
METI resource circulation policies incentivize domestic manufacturing with embedded tracking capabilities. Container recycling laws reshape procurement specifications for pharmaceutical and automotive sectors. Kansai-region automotive suppliers specify washable, trackable insulated totes for closed-loop supply chain compliance.
Corrugated Plastic Box Market Competitive Environment
Player mix skews toward integrated converters with captive extrusion capacity and regional specialists serving single-country procurement frameworks. Consolidation pressure concentrates among European and North American operators seeking closed-loop packaging mandates compliance. Two strategic archetypes dominate: vertically integrated resin-to-box converters controlling flute geometry consistency, and fleet-management specialists operating third-party pool logistics. Capacity expansion and strategic partnerships represent the dominant competitive moves as participants seek geographic coverage and technology access.
Within the integrated converter tier, DS Smith and Coroplast exemplify divergent regional anchoring strategies. DS Smith leverages European recycling infrastructure to meet closed-loop packaging mandates through its UK-based operations. Coroplast occupies a position as a North American production anchor through extrusion capabilities that sustain consistent flute geometry. Inteplast Group represents the scale-driven archetype among North American fabricators, sitting within a competitive set that prioritizes volume absorption across diversified end-use segments.
| Leading Market Players |
|---|
| DS Smith |
| Coroplast |
| Inteplast Group |
| Penda Corporation |
| Primex Plastics |
| NW Packaging |
| Tulox Plastics |
| Sohner Plastics |
| Universal Package |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of polypropylene resin inventory buffers extrusion converters against propylene monomer price swings, concentrating pricing power among German and Austrian machinery-anchored producers while squeezing margin-pinned North American fabricators. This lead-time asymmetry between raw material procurement and finished goods delivery shapes contract structures across automotive and cold-chain procurement tiers.
Pricing Analysis
Cost-plus contracts indexed to ICIS propylene monomer benchmarks dominate converter-buyer agreements, with premium-mid-economy pricing differentiation separating FDA-certified pharmaceutical grades from standard industrial totes and agricultural disposables. Certification level and volume scale drive price spreads, with automotive procurement compressing margins through multi-year offtake commitments while cold-chain operators absorb premium markups for traceable insulated formats. Pricing pressure stems from naphtha-linked resin volatility, with agricultural distributors exhibiting highest price sensitivity and pharmaceutical buyers showing least elasticity due to CDSCO and FDA compliance mandates.
Supply Chain Analysis
German and Austrian twin-screw extruder manufacturing creates a machinery chokepoint that constrains capacity expansion for consistent flute geometry production. Polypropylene resin supply concentrates in Saudi Arabia, South Korea, and the United States, with converters drawing from regional petrochemical complexes to minimize freight exposure. Single-source vulnerability runs through specialized polymer rheology expertise for crush-resistance calibration. Distribution feeds from captive extrusion facilities through third-party pool operators in the Netherlands and direct sales to automotive tier-one suppliers in Bavaria and Lower Saxony.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrugated plastic box market sits in a cyclical recovery phase as automotive production restocking and e-commerce logistics densification drive container fleet replenishment. Polypropylene resin price normalization following petrochemical cycle troughs supports margin stabilization for extrusion converters.
For Market Incumbents: Compound defensive positioning through backward integration into post-industrial resin collection networks that secure EPA recycled content guideline compliance. Add extrusion capacity in the Yangtze River Delta to capture China's e-commerce logistics expansion. Certify flute geometry consistency for automated handling systems to preempt emerging Asian machinery competitors.
For New Entrants and Emerging Players: Fleet-management software layers represent an under-served service gap where incumbents lack digital-native reverse logistics coordination capabilities. Target India's pharmaceutical cold chain with CDSCO-compliant insulated totes featuring embedded temperature loggers. Pursue leasing-model partnerships with Mumbai and Hyderabad drug distributors to bypass capital-intensive extrusion equipment barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU packaging waste directives and Japan's METI resource circulation policies create durable demand for returnable packaging assets that outlast commodity cycles. Acquire mid-cap converters with captive extrusion capacity and established automotive OEM qualifications. Monitor polypropylene resin price volatility indices as the key inflection signal for margin expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Collection | Captive post-industrial feedstock secures EPA recycled content compliance for automotive contracts. |
| Co-extruded Barrier Layer Development | Ethylene vinyl alcohol constructions displace wax-coated fiberboard in Netherlands pharmaceutical distribution. |
| RFID Fleet Management Platform | Embedded tracking capabilities satisfy Japan's METI container recycling law mandates. |
| Yangtze River Delta Capacity Expansion | Proximity to Shanghai and Shenzhen e-commerce hubs reduces logistics cube in reverse networks. |
| Third-party Pool Operator Partnership | Leasing models transfer utilization risk from Philips and ASML procurement to specialized fleet managers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with extrusion plant managers, automotive tier-one procurement leads, cold-chain logistics directors, and pharmaceutical distribution specialists; and secondary validation through customs and trade data, SEC filings of integrated packaging converters, EPA recycled content guideline documentation, and EU REACH compliance registries. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across product types and end-use sectors.
Across the projection horizon, the analytical framework modeled demand by packaging type, end-user industry, application, and regional regulatory cluster to isolate mandate-driven procurement shifts from cyclical restocking patterns. CAGRs derived from segment-level volume trajectories incorporated polypropylene resin price elasticity assumptions and automotive production forecasts. Industry-specific inputs included KBA reusable packaging ratio compliance timelines and China's MIIT industrial standards for recyclable transport packaging.
Underlying assumptions cover resin price stabilization, regulatory enforcement continuity, and e-commerce logistics densification, with deviation risk concentrated in propylene monomer supply disruptions and EU packaging waste directive implementation delays. Practitioners should keep alternative scenarios live as automotive electrification rates and cold-chain infrastructure investment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Plastic Tumblers Market