
 Automatic Glue Machine Market | 2026-2036
Automatic Glue Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Glue Machine Market Outlook
Direct distribution from equipment makers to tier-one contract manufacturers is rewriting how automatic glue machines reach factory floors. Nordson Corporation leverages its polymer melt expertise to sustain premium positioning in hot melt systems across North American packaging lines. Musashi Engineering, Inc. dominates precision dispensing for semiconductor and PCB assembly in East Asian electronics hubs. Graco Inc. anchors industrial-grade installations with fluid handling systems that extend into automotive sealing applications.
An automatic glue machine is an electromechanical system that meters, dispenses, and controls adhesive deposition through programmable valves, pressure tanks, or positive-displacement pumps, typically achieving placement accuracy within microns for electronics applications. These systems bond substrates in manufacturing processes ranging from consumer electronics assembly to automotive panel lamination. Hot melt equipment leads installed base value due to its dominance in high-speed packaging lines, while robotic dispensing technology captures the fastest expansion as electronics assemblers replace semi-automatic stations for flexible production. Water-based adhesive systems are maturing in furniture and construction applications where VOC regulations have already forced formulation shifts, leaving margin pools concentrated in precision robotic cells for medical device and semiconductor packaging.
The EU Machinery Directive and REACH compliance framework shape product design by mandating safety interlocks and restricting hazardous adhesive chemistries in equipment sold across Europe. EPA air quality standards and OSHA workplace exposure limits in the United States pressure manufacturers to engineer enclosed dispensing systems with vapor recovery capabilities. Stakeholders must monitor how evolving chemical regulations in multiple jurisdictions will force simultaneous equipment redesign and adhesive formulation changes, creating compliance windows that favor suppliers with integrated material-equipment expertise.
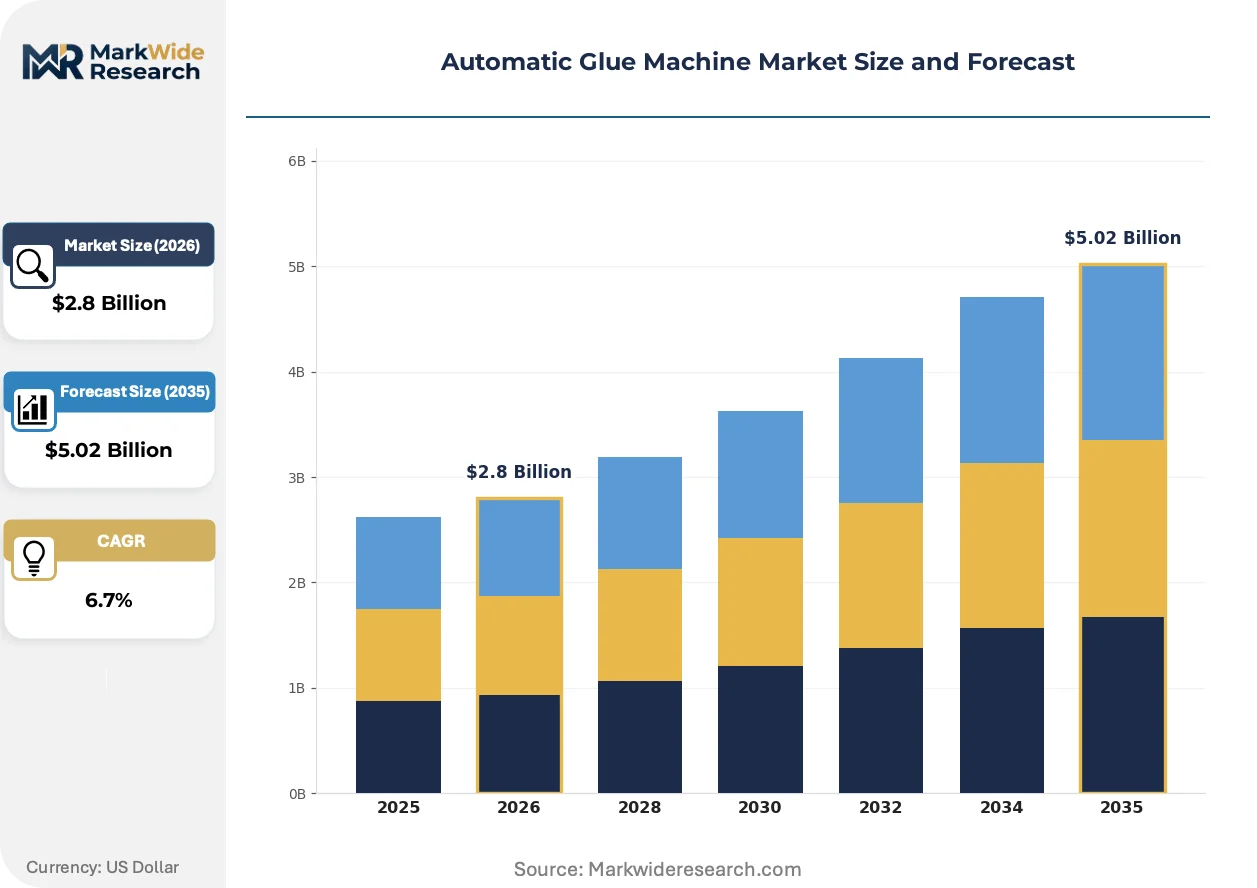
Market Dynamics
Electronics miniaturization is compressing dispensing tolerances from millimeters to single-digit microns, forcing equipment makers to integrate vision-guided robotics with real-time viscosity compensation. This precision arms race is concentrating R&D budgets among suppliers with captive motion-control expertise.
Growth Catalysts
- REACH chemical compliance deadlines:European manufacturers are accelerating equipment replacement cycles to handle reformulated low-VOC adhesives before restricted substance prohibitions take effect.
- Semiconductor advanced packaging:Die-attach and underfill processes for chiplet architectures now require sub-5-micron repeatability that only robotic dispensing achieves.
- Guangdong Province cluster upgrading:Contract assemblers in Shenzhen and Dongguan are retiring manual stations for fully automatic lines to meet Apple and Samsung supplier qualification standards.
Market Restraints
- Specialized servo motor supply:High-resolution linear actuators for precision valves depend on Japanese and German component suppliers with 16-20 week lead times.
- Fluoropolymer seal material costs:Perfluoroelastomer O-rings for solvent-resistant pumps have experienced volatile pricing due to constrained tetrafluoroethylene monomer availability.
- EU Machinery Directive safety certification:Interlock and emergency-stop redesigns for European market entry add 8-12 months to product launch timelines.
Strategic Opportunities
- Medical device micro-dosing:Catheter and implantable device manufacturers in Massachusetts and Minnesota are qualifying new adhesive platforms for biocompatible bonding.
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor and mobile phone assembly are creating first-mover advantages for dispensing equipment installation.
- Thermal interface material dispensing:Battery pack assembly for electric vehicles requires new volumetric pump technologies that merge adhesive deposition with gap-filler application.
Industry Challenges
- Multi-axis motion programming expertise:Equipment operators with combined robotics and fluid dynamics training command 40-60% wage premiums in manufacturing labor markets.
- Legacy PLC integration complexity:Brownfield automotive plants require protocol translation layers to connect new dispensing cells with 1990s-era shop floor control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Glue Machine Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Pressure Sensitive, Solvent-Based, Water-Based Technology: Manual, Semi-Automatic, Fully Automatic, Robotic End User: Packaging, Automotive, Electronics, Furniture Application: Labeling, Product Assembly, Surface Bonding, Construction |
| Companies Covered | Nordson Corporation, Musashi Engineering, Inc., Graco Inc., Fisnar Inc., Glue Machinery Corporation, Valco Melton, Techcon Systems, Scheugenpflug GmbH, SAEJONG SMT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Glue Machine Market Strategic Shifts
Adhesive deposition technology is converging with adjacent manufacturing disciplines, blurring traditional boundaries between dispensing, inspection, and surface preparation. Equipment architectures are being rebuilt around data continuity rather than mechanical isolation.
Pneumatic-positivedisplacement hybrid pumps are hybridizing pressure-time and volumetric dispensing methods into single-head architectures. Smartphone camera module assemblers in South Korea and Taiwan are adopting these systems to eliminate changeover downtime between dot and bead applications. The technology is hybridizing what were previously separate equipment categories, compressing supplier margins on standalone pneumatic systems.
REACH Annex XVII restrictions on diisocyanates and certain epoxy hardeners are forcing adhesive formulators to validate alternative chemistries with shorter pot lives and different rheology profiles. Equipment makers must redesign heating zones and purge sequences to handle these faster-curing materials without premature polymerization. Medical device manufacturers in Germany and Ireland are most affected, accelerating validation partnerships with dispensing system suppliers.
Contract manufacturers are consolidating adhesive specification authority from individual plant engineers to centralized procurement functions with total-cost-of-ownership models. This concentrates purchasing leverage among Foxconn, Jabil, and Flex facilities, displacing regional equipment distributors in favor of direct OEM relationships. The shift is most visible in Mexico's Baja California electronics corridor, where tier-one assemblers now negotiate global frame agreements with Nordson and Musashi.
Automatic Glue Machine Market Segmentation
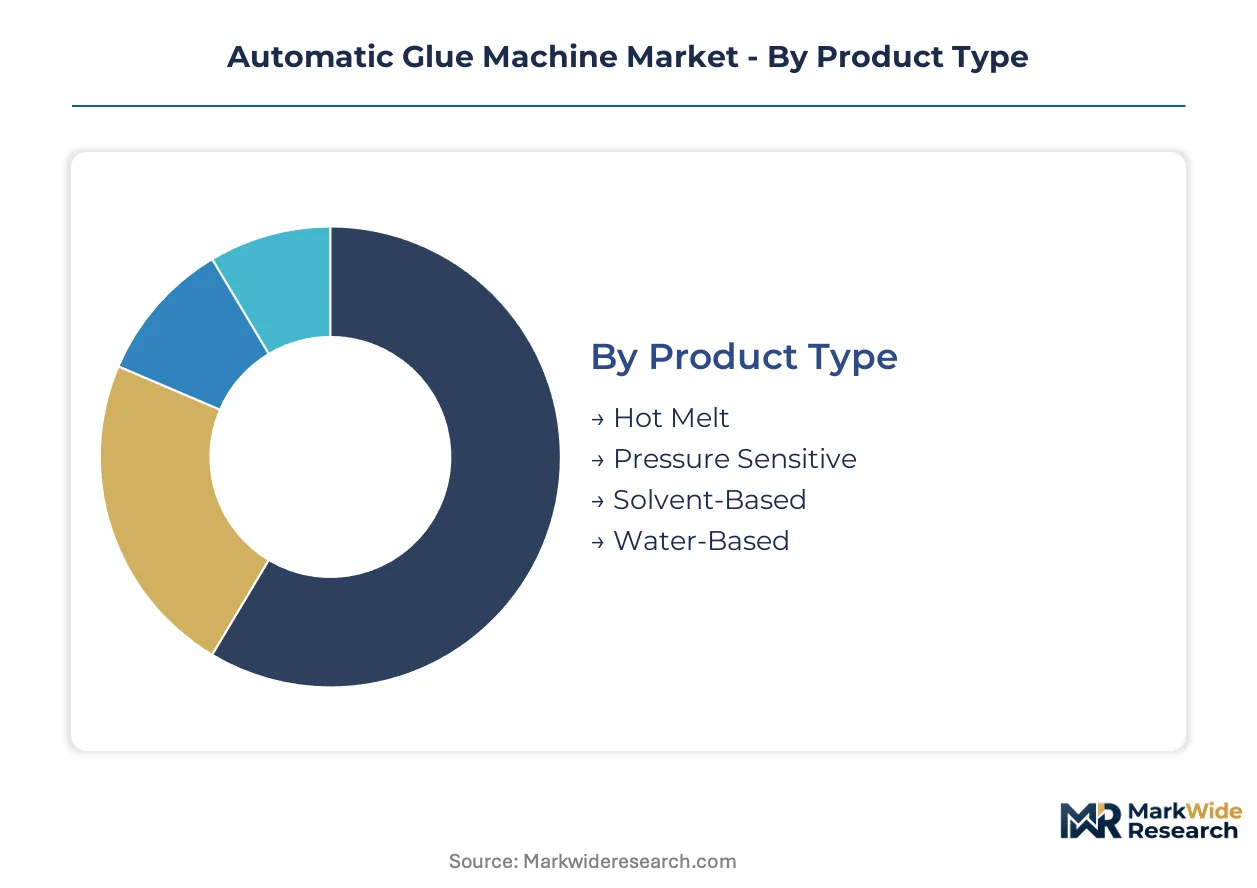
Automatic glue machine segmentation reveals how adhesive deposition technology fragments across maturity curves and precision requirements. Equipment buyers navigate trade-offs between throughput speed, placement accuracy, and total cost of ownership that reshape supplier positioning across each dimension.
Product Type:
Mature formulations dominate installed value while emerging chemistries force equipment redesign for faster curing windows and lower volatile organic compound profiles.
- Hot Melt:Thermoplastic adhesives applied at 150-200°C dominate high-speed packaging lines with instant bonding and no solvent recovery requirements. Demand concentrates in North American corrugated board and folding carton facilities where Nordson systems anchor production floors. Equipment must manage thermal cycling stress on pumps and nozzles that limits maintenance intervals.
- Pressure Sensitive:Permanent tack adhesives enable repositionable bonding for label stock and tape manufacturing without activation energy. Japanese and German automotive interior suppliers specify these systems for dashboard lamination where bond line aesthetics override structural strength requirements. Viscosity stability across temperature ranges determines pump specification authority.
- Solvent-Based:High-strength formulations for structural bonding in metal and composite assembly.
- Water-Based:Low-VOC systems maturing in furniture flat-pack and construction panel applications where REACH and EPA air quality standards have forced formulation transitions.
Hot Melt retains volume leadership; Water-Based holds the steepest expansion curve as regulatory pressure accelerates equipment replacement cycles.
Technology:
Automation intensity separates cost tiers from manual benchtop units through vision-guided robotic cells, with precision requirements dictating capital allocation patterns.
- Manual:Handheld dispensers and foot-pedal guns serve prototype shops and low-volume repair operations with minimal capital outlay. These systems persist in Mexican and Vietnamese contract assembly facilities where labor arbitrage still offsets automation economics for batch sizes below 500 units.
- Semi-Automatic:Operator-loaded fixtures with automated dispensing cycles bridge manual and fully automatic economics for mid-volume production. Electronics assemblers in Malaysia and Thailand deploy these systems for smartphone accessory manufacturing where product mix changes quarterly and full automation payback extends beyond 24 months.
- Fully Automatic:Conveyor-integrated systems with programmable dispense patterns for continuous flow manufacturing.
- Robotic:Six-axis arms with force feedback and machine vision achieve sub-10-micron repeatability for semiconductor packaging and medical device assembly.
Fully Automatic commands the largest installed base value; Robotic delivers the fastest share gain as miniaturization requirements eliminate human placement tolerance.
End User:
Application precision requirements range from millimeter-tolerant packaging to sub-micron electronics, fragmenting equipment specifications and supplier relationships.
- Packaging:Corrugated case sealing and folding carton gluing prioritize throughput over placement precision, with systems specified in cases per minute rather than micron tolerance. Major beverage and consumer goods manufacturers in Brazil and Indonesia standardize on hot melt platforms with 500+ meter per minute line speeds.
- Electronics:PCB assembly, display bonding, and semiconductor packaging demand the tightest process control. South Korean and Taiwanese camera module manufacturers specify robotic dispensing with real-time viscosity compensation and automated needle cleaning to prevent die-attach contamination.
- Automotive:Structural bonding for body-in-white and interior trim lamination with crashworthiness requirements.
- Furniture:Edge banding and panel assembly where water-based adhesive transitions have compressed margin pools.
Packaging generates the highest unit volume; Electronics drives the steepest technology premium expansion.
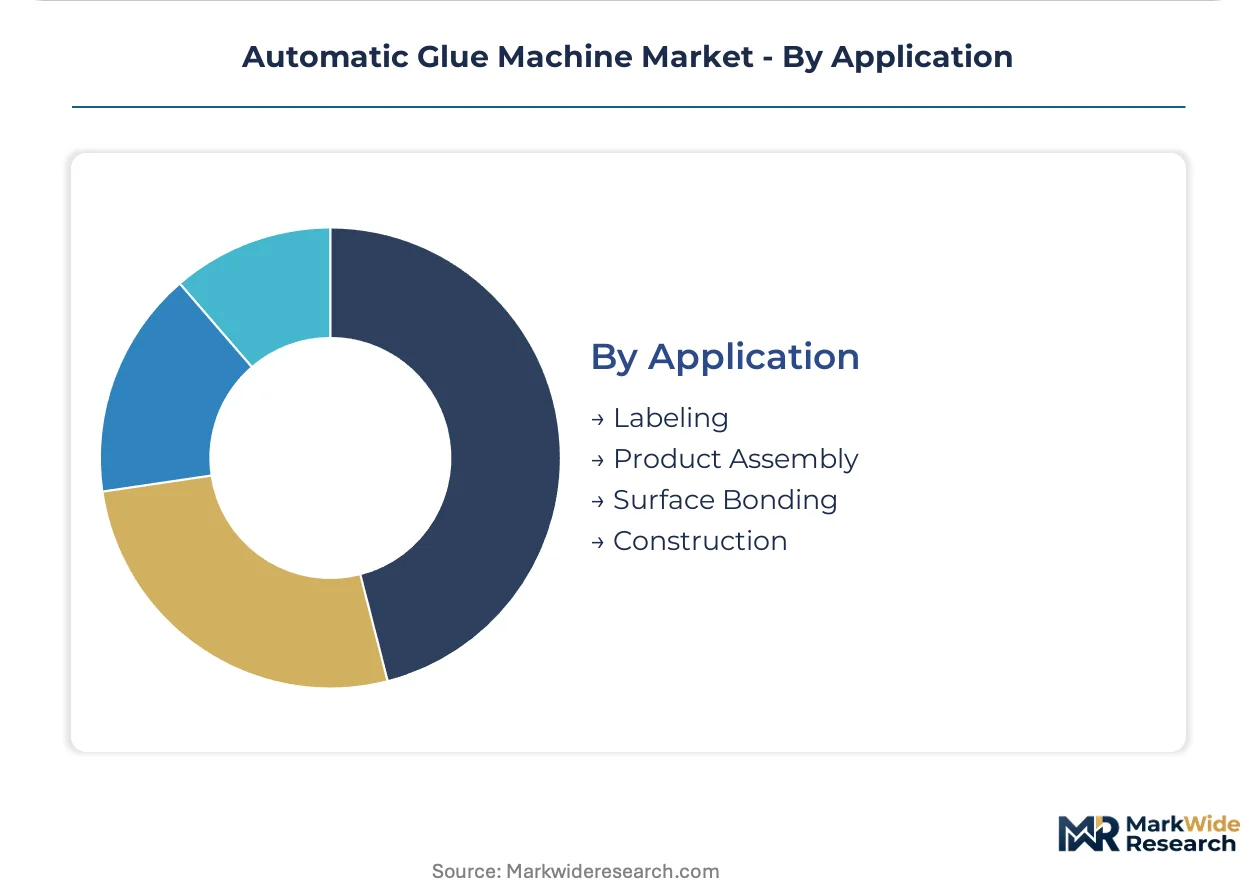
Application:
Functional purpose determines adhesive selection and equipment architecture, from surface preparation through cure verification.
- Product Assembly:Structural bonding of components into finished goods spans electronics, automotive, and consumer products with the broadest equipment specification range. Massachusetts medical device manufacturers qualify adhesive platforms for catheter assembly where biocompatibility testing adds 18-24 months to equipment validation timelines.
- Labeling:Pressure-sensitive adhesive application for primary and secondary packaging labels demands precise tension control and web handling. Food and beverage producers in Italy and Spain specify these systems for compliance with EU Packaging and Packaging Waste Directive recyclability requirements.
- Surface Bonding:Lamination and cladding operations for construction panels and automotive interiors.
- Construction:Field and factory applications for insulation, flooring, and facade systems with cure time and weather resistance specifications.
Product Assembly captures the widest equipment margin pool; Labeling maintains the most standardized platform economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment (MEE) enforces dual carbon goals that accelerate factory automation adoption. Equipment procurement concentrates in manufacturing clusters where export compliance and labor cost pressures intersect.
China
Guangdong Province contract assemblers in Shenzhen and Dongguan upgrade from manual to fully automatic dispensing systems to meet Apple and Samsung supplier qualification standards. MIIT industrial upgrading subsidies support semiconductor packaging equipment investments. Pearl River Delta electronics corridors now specify robotic dispensing with sub-5-micron repeatability for camera module production.
United States
Massachusetts and Minnesota medical device manufacturers qualify new adhesive platforms for biocompatible bonding in catheter and implantable device assembly. FDA 21 CFR Part 820 quality system regulations extend equipment validation timelines by 18-24 months. Greater Boston medical technology cluster demands integrated dispensing-inspection systems for FDA-compliant manufacturing.
Germany
Automotive interior suppliers specify pressure-sensitive adhesive systems for dashboard lamination where bond line aesthetics override structural strength requirements. EU Machinery Directive safety interlock mandates add 8-12 months to product launch timelines for European market entry. Bavarian automotive component manufacturers integrate dispensing cells with legacy PLC systems from 1990s-era brownfield plants.
South Korea
Smartphone camera module assemblers adopt pneumatic-positive displacement hybrid pumps to eliminate changeover downtime between dot and bead applications. REACH Annex XVII restrictions on diisocyanates force validation of alternative adhesive chemistries with shorter pot lives. Seoul metropolitan area electronics fabs deploy real-time viscosity compensation systems for die-attach processes.
India
PLI scheme subsidies for semiconductor and mobile phone assembly create first-mover advantages for dispensing equipment installation in emerging electronics corridors. BIS certification requirements for industrial machinery extend procurement cycles for imported systems. Karnataka and Tamil Nadu contract manufacturing parks attract tier-one assemblers qualifying new adhesive platforms for export markets.
Automatic Glue Machine Market Competitive Environment
Precision-specialist and scale-driven manufacturers split the market along application tolerance requirements. Consolidation pressure concentrates among suppliers with captive motion-control expertise for sub-10-micron repeatability. Three archetypes dominate: integrated material-equipment providers, robotics-native dispensing specialists, and industrial fluid handling conglomerates. Competitive moves center on strategic partnerships with adhesive formulators and geographic expansion into India electronics manufacturing zones.
Within the precision-specialist tier, Nordson Corporation and Musashi Engineering, Inc. exemplify divergent regional anchoring strategies. Graco Inc. occupies a position among industrial fluid handling conglomerates extending into automotive sealing applications. Scheugenpflug GmbH represents European precision automation heritage in volumetric dispensing architectures. These three anchors illustrate how supplier positioning fragments across thermal management expertise, semiconductor-native precision, and industrial-scale fluid handling capabilities.
| Leading Market Players |
|---|
| Nordson Corporation |
| Musashi Engineering, Inc. |
| Graco Inc. |
| Fisnar Inc. |
| Glue Machinery Corporation |
| Valco Melton |
| Techcon Systems |
| Scheugenpflug GmbH |
| SAEJONG SMT |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese and German servo motor foundries is compressing lead times for precision linear actuators while simultaneously hardening pricing power among equipment makers with captive motion-control expertise. This utilization squeeze feeds directly into capital equipment quotes, as robotic dispensing system builders pass through component scarcity premiums while captive suppliers extract margin from competitors forced into spot-market sourcing.
Pricing Analysis
Geographic price spreads of 15-25% separate East Asian procurement hubs from European and North American installations, driven by freight costs, import duty structures, and local certification requirements. Equipment pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in placement accuracy certification, software integration depth, and bundled after-sales service contracts. Pricing pressure stems from contract manufacturer consolidation in Guangdong Province, where Foxconn and Jabil negotiate global frame agreements that compress distributor margins. Tier-one electronics assemblers exhibit lowest price sensitivity due to total-cost-of-ownership procurement models, while mid-volume furniture and packaging buyers remain most cost-conscious.
Supply Chain Analysis
Extended payment terms stretching to 120 days have become standard for tier-one contract manufacturers, forcing equipment suppliers to access supply-chain finance facilities or absorb working capital strain. Component sourcing draws from Japan and Germany for high-resolution linear actuators, China for machined frames and pneumatic subassemblies, and the United States for specialized motion controllers. Fluoropolymer seal materials and tetrafluoroethylene monomer feedstocks present single-source vulnerability due to concentrated chemical production. Distribution runs through direct OEM relationships with tier-one assemblers, displacing regional distributors in Mexico's Baja California corridor and China's Pearl River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including predictive maintenance contracts, consumables subscription programs, and software upgrade licenses are expanding faster than hardware sales across precision dispensing segments. Equipment makers with integrated material-equipment expertise capture disproportionate recurring revenue from adhesive formulation validation and process optimization services.
For Market Incumbents: Insulate premium positioning by deepening captive supply of precision motion components and accelerating REACH-compliant equipment certification ahead of European prohibition deadlines. Vertical integration into Japanese and German servo motor supply chains defends against 16-20 week lead time vulnerability. Investment in India-based technical service infrastructure captures PLI scheme-driven installation demand before competitor footprint establishment. For New Entrants and Emerging Players: Mid-market semi-automatic dispensing systems in Vietnam and Indonesia represent the most penetrable entry point, where labor arbitrage still offsets full automation economics for batch production below 500 units. Medical device micro-dosing applications in Massachusetts and Minnesota offer second-mover qualification pathways as FDA 21 CFR Part 820 validation timelines extend incumbent lock-in. Partnership with regional adhesive formulators accelerates chemistry-equipment co-validation without captive R&D investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic dispensing sub-segments as vision-guided systems and real-time viscosity compensation layers add software and sensor content. Acquisition targets should prioritize specialists with sub-10-micron repeatability IP and established validation partnerships with semiconductor packaging houses. The signal to watch is contract manufacturer qualification velocity for die-attach and underfill processes in South Korean and Taiwanese camera module fabs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion Control Components | Captive supply of Japanese and German linear actuators insulates against lead time volatility and supplier pricing power. |
| REACH-Compliant Equipment Redesign | Pre-positioned safety interlock and heating zone architectures capture European market entry before prohibition deadlines. |
| India Technical Service Infrastructure | PLI scheme subsidies in Karnataka and Tamil Nadu create first-mover installation advantages before competitor localization. |
| Adhesive-Equipment Co-Validation Partnerships | Integrated material-process expertise accelerates medical device and semiconductor packaging qualification timelines. |
| Predictive Maintenance Platform Launch | Recurring software and consumables revenue streams expand lifetime customer value beyond initial hardware placement. |
Study Parameters
The analysis maps hot melt, pressure-sensitive, solvent-based, and water-based adhesive systems alongside manual, semi-automatic, fully automatic, and robotic technology tiers, each validated through equipment procurement directors at tier-one contract manufacturers, plant engineers at automotive interior suppliers, and aftermarket service heads at precision dispensing specialists. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, SEC 10-K filings from listed equipment makers, and MIIT industrial upgrading subsidy disclosures. Bottom-up equipment shipment tallies and top-down adhesive consumption estimates were triangulated to anchor market sizing.
Forecast assumptions held fixed the current regulatory trajectory for EU Machinery Directive safety mandates and REACH Annex XVII chemical restrictions, while varying semiconductor packaging intensity and electric vehicle battery assembly penetration across the projection horizon. The analytical framework modeled technology type, product formulation, end-user industry, and application function as core segmentation dimensions. CAGRs were derived from equipment replacement cycle analysis and adhesive formulation transition timelines. Forecast inputs included Guangdong Province contract assembler automation rates, Massachusetts medical device validation pipeline depth, and South Korean camera module production forecasts.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, automotive production volumes, or currency volatility in key procurement corridors would shift the trajectory. Forecasts reflect these documented assumptions; regulatory acceleration in chemical restrictions, breakthroughs in cold-cure adhesive chemistry, or supply chain regionalization mandates would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Europe Packaging Automation Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Robotic Packaging Machines Market