
 Smart Mirror TV Market | 2026-2036
Smart Mirror TV Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Mirror TV Market Insights
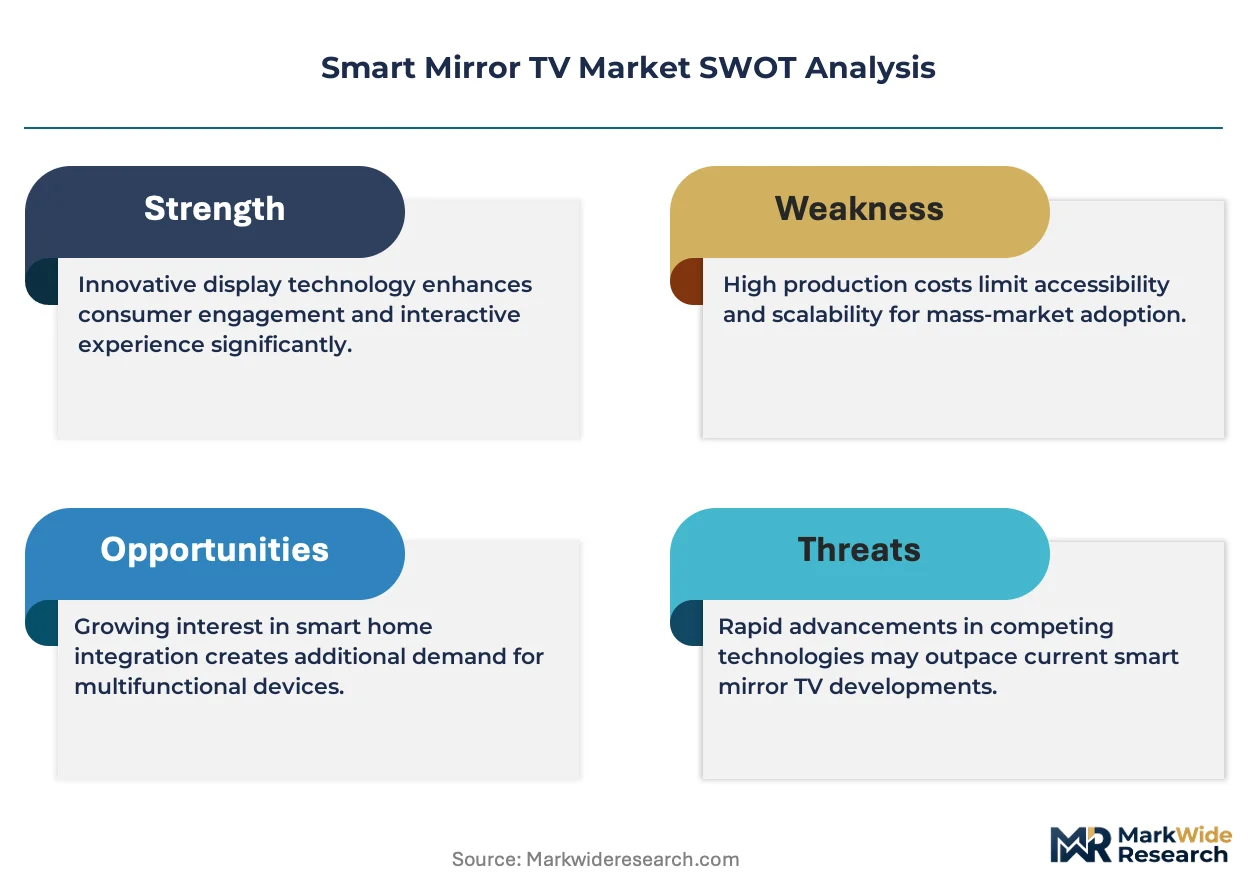
Multi-source panel procurement is recalibrating how smart mirror TV assemblers manage cost and supply security. Samsung Electronics leverages captive OLED manufacturing to control display quality and delivery timelines. Electric Mirror, Inc. anchors its position through specialized hospitality installations with custom framing and waterproofing. Seura differentiates by focusing on residential bathroom environments with integrated vanity lighting.
A smart mirror TV combines a reflective glass surface with an embedded flat-panel display, typically employing dielectric mirror coatings that transmit screen illumination while preserving reflectivity above 70 percent for grooming functions. The primary commercial purpose is to deliver streaming content, weather, and calendar data in spaces where conventional televisions cannot operate due to moisture exposure or aesthetic constraints. LCD and LED categories currently occupy the bulk of unit shipments given their cost accessibility for hospitality retrofit projects. OLED commands premium positioning in residential and luxury hotel segments where contrast ratios and slim profiles justify higher price points. Voice control and integrated smart features are expanding fastest as hotel operators seek contactless guest interaction and consumers adopt ecosystem-agnostic assistants.
FCC equipment authorization governs radio-enabled smart mirror TVs sold in the United States, while CE marking and the EU Ecodesign Directive shape efficiency and electromagnetic compliance for European distribution. REACH restrictions on hazardous substances in glass coatings and electronic assemblies add material selection complexity for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving interoperability standards between proprietary smart home ecosystems and open connectivity protocols to avoid stranded inventory or locked-out market segments.
Market Dynamics
Hospitality operators are consolidating bathroom technology spend into single-vendor smart mirror TV contracts, compressing procurement cycles and forcing display assemblers to bundle waterproofing, voice control, and content licensing into fixed-price installations.
Growth Catalysts
- EU Ecodesign Directive:Energy efficiency mandates under this framework accelerate manufacturer migration to lower-power OLED and micro-LED architectures, creating compliant product lines that unlock European distribution channels.
- Hospitality retrofit wave:Premium hotel chains are standardizing mirror displays across guest bathroom portfolios to differentiate room tiers and capture higher nightly rates through technology-enabled luxury positioning.
- Contactless interaction protocols:Voice control integration eliminates touch surfaces in moisture-rich environments, aligning with post-pandemic hygiene expectations and reducing maintenance costs for facility managers.
Market Restraints
- Display panel concentration:Captive OLED supply from South Korean vertically integrated manufacturers creates supply security vulnerabilities for assemblers lacking long-term panel allocation agreements.
- Dielectric coating cost volatility:Specialized mirror glass with 70%+ reflectivity requires precision sputtered coatings whose raw material inputs face price pressure from semiconductor and solar panel competing demand.
- Moisture ingress technical ceiling:IP65-equivalent sealing in slim form factors remains technically constrained, limiting deployment in direct-spray shower environments and compressing addressable bathroom surface area.
Strategic Opportunities
- Residential bathroom underpenetration:Consumer awareness of vanity-integrated streaming remains low outside luxury renovation segments, creating first-mover advantage for brands investing in showroom and architect education.
- Healthcare facility applications:Patient room mirror displays for entertainment and telemedicine represent an emerging vertical with distinct waterproofing and antimicrobial surface requirements.
- Smart home ecosystem convergence:Matter protocol interoperability enables single-dashboard control across lighting, climate, and mirror displays, reducing consumer friction in whole-home automation projects.
Industry Challenges
- Cross-functional engineering talent scarcity:Product development requires simultaneous expertise in optical coatings, RF antenna design for Wi-Fi/Bluetooth penetration through metalized glass, and hospitality software integration.
- Multi-jurisdiction certification timelines:FCC equipment authorization for US distribution, CE marking for European access, and REACH substance compliance create sequential launch delays and inventory stranding risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Mirror TV Market |
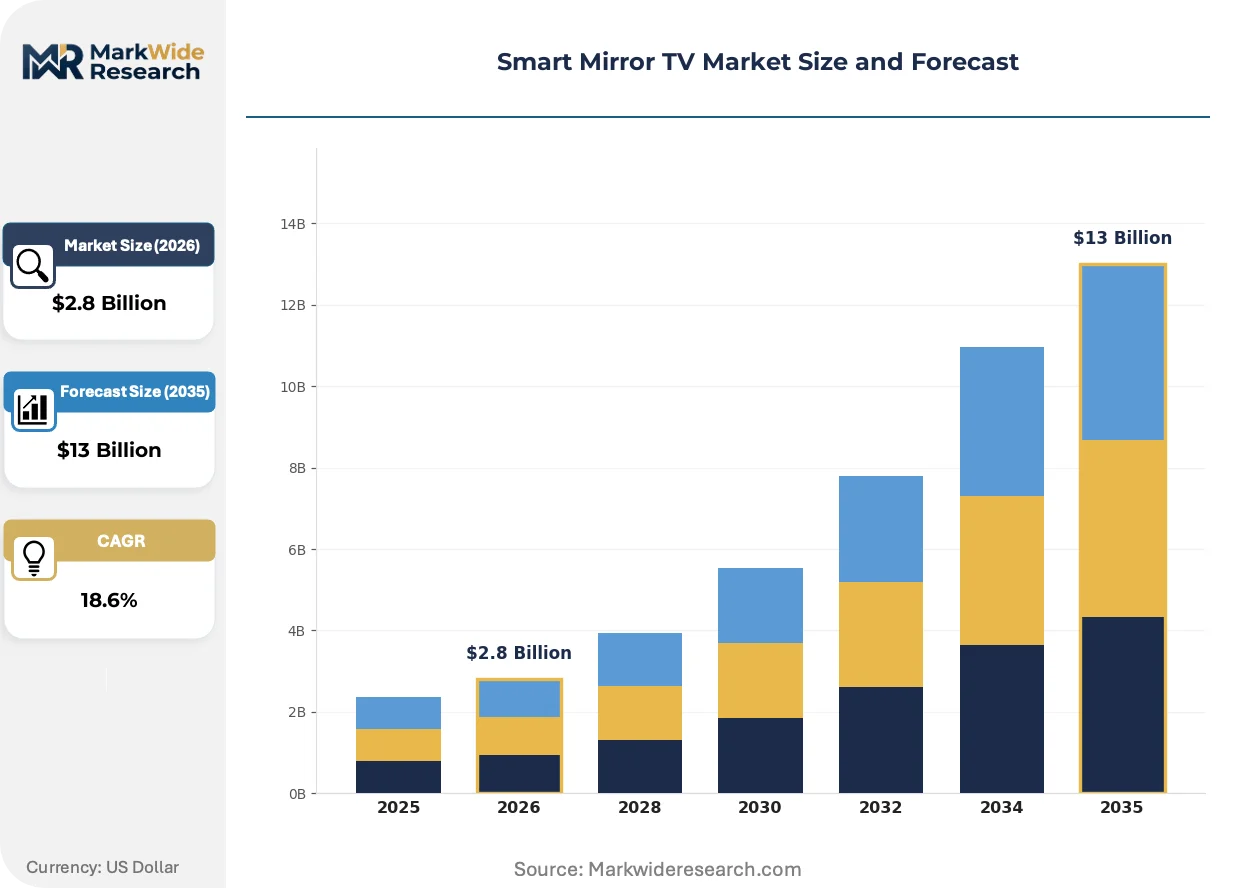
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, LED, QLED Application: Home, Hospitality, Retail, Commercial Technology: Integrated Smart Features, Voice Control, Touchscreen, Gesture Recognition End User: Consumers, Businesses, Healthcare Facilities, Educational Institutions |
| Companies Covered | Samsung Electronics, Seura, Electric Mirror, Inc., Evervue USA Inc., MirrorMedia Ltd., Ad Notam AG, Hidden Technology, Pro Display, Majestic Mirror & Frame, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Mirror TV Market Trends and Innovations
Active matrix OLED technology is compressing display thickness and expanding contrast performance, enabling mirror TV form factors that disappear entirely into bathroom architecture when powered down.
Micro-LED backlighting is overtaking conventional edge-lit LED architectures in premium hospitality installations. The technology delivers zone-dimmable illumination through mirror glass with minimal heat generation. Four-star and five-star hotel operators in Dubai and Singapore are specifying micro-LED units for new-build properties. This shift is compressing acceptable power consumption thresholds and forcing legacy LCD assemblers to source unfamiliar chip-on-board LED packages.
REACH restrictions on hazardous substances in glass coatings and electronic assemblies are reshaping material selection protocols for manufacturers serving European distribution. ECHA substance candidate list updates now cover specific mirror coating chemistries previously standard in dielectric stacks. Assembly operations with captive coating lines in Germany and the Netherlands are investing in aqueous-process alternatives. Product development teams are prioritizing coating formulations that satisfy both REACH and upcoming US state-level disclosure requirements.
Architect specification authority is displacing traditional electronics retail channels for residential smart mirror TV procurement. Interior designers and bathroom renovators now control product selection in high-value home improvement projects, demanding custom framing, sizing, and finish matching unavailable through mass-market distribution. This channel migration is most visible in California and New York metropolitan markets where renovation spend concentrates. Manufacturers are building direct-to-designer sales operations with sample lending programs and continuing education credits.
Smart Mirror TV Market Segmentation
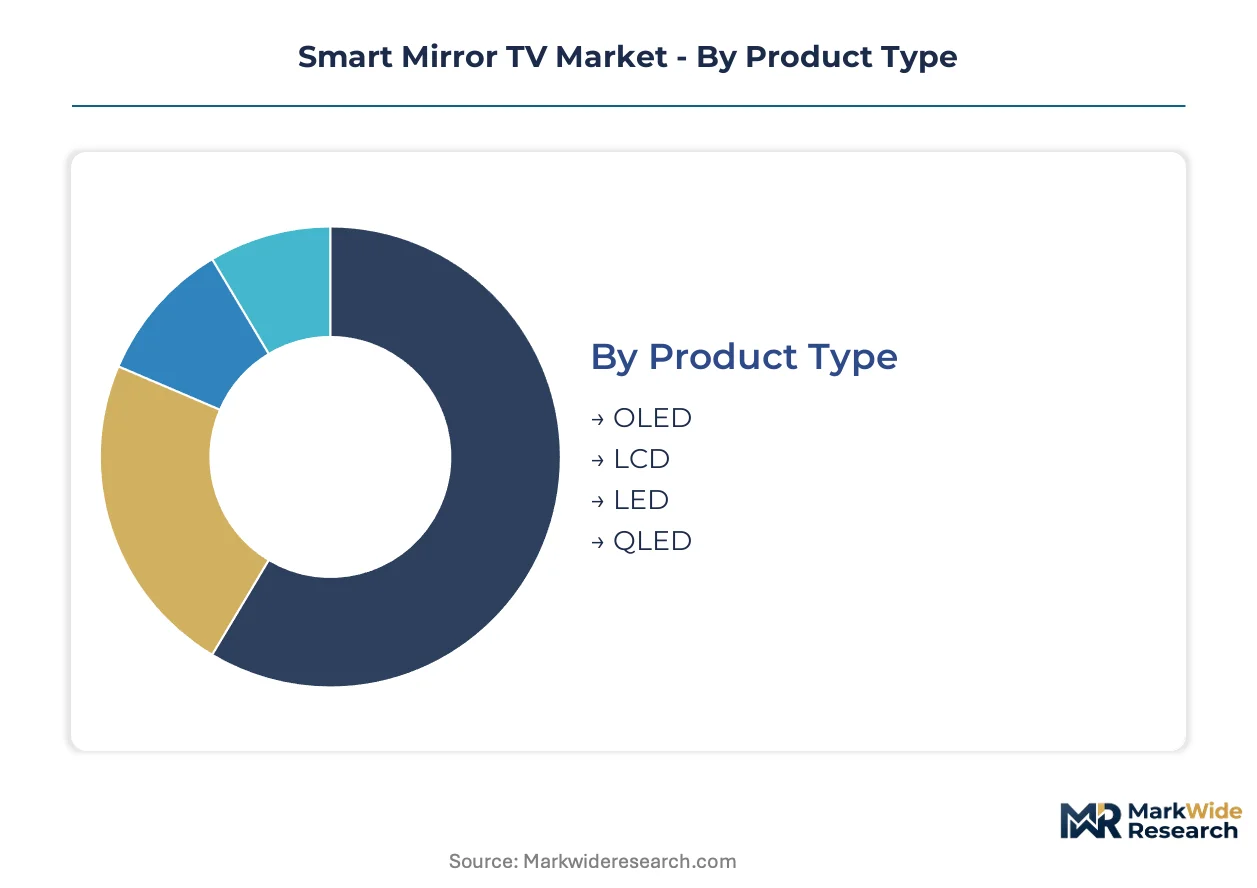
Smart mirror TV manufacturers configure production lines around display architecture, moisture sealing requirements, and software integration complexity. Segment selection determines capital allocation for coating equipment, panel procurement commitments, and certification pathways.
Product Type:
OLED and micro-LED architectures demand the heaviest upfront investment in precision deposition equipment and cleanroom infrastructure.
- OLED:Organic electroluminescent layers eliminate backlight assemblies, enabling sub-4mm profiles that recess flush into bathroom vanities. South Korean captive supply chains dominate panel allocation, with premium hospitality installations in Dubai and Singapore specifying these units for new-build properties.
- LCD:Liquid crystal matrices with edge-lit or full-array LED backlighting occupy the bulk of hospitality retrofit volume. Lower unit costs align with four-star hotel procurement budgets, though contrast ratios and viewing angles constrain placement in brightly lit bathroom environments.
- LED:Direct-lit LED configurations with zone dimming bridge price-performance gaps in mid-market residential renovations. Thermal management requirements complicate slim-form-factor designs.
- QLED:Quantum dot-enhanced films expand color gamut for luxury residential specifications. Samsung Electronics leverages this technology across its lifestyle television portfolio.
Most installed capacity flows through LCD. Expansion is steepest in OLED.
Application:
Waterproofing certification tiers and content licensing structures differentiate addressable use cases.
- Home:Residential bathroom installations emphasize vanity-integrated lighting, fog resistance, and smart home ecosystem compatibility. California and New York metropolitan markets concentrate renovation-driven demand.
- Hospitality:Guest bathroom deployments require IP65-equivalent sealing and centralized content management systems. Premium chains in Singapore and Dubai standardize mirror displays to differentiate room tiers.
- Retail:Fitting room installations leverage gesture recognition for contactless interaction. Moisture exposure is minimal, permitting thinner glass stacks.
- Commercial:Corporate lobby and wellness center applications prioritize durability and remote fleet management. Installation scales favor regional systems integrators over direct manufacturer relationships.
Hospitality captures the dominant share of current revenue. Home applications are climbing the fastest.
Technology:
RF engineering and software development intensity vary sharply across interaction modalities.
- Voice Control:Far-field microphone arrays and natural language processing engines enable hands-free operation in moisture-rich environments. FCC equipment authorization governs radio-enabled units sold in the United States.
- Integrated Smart Features:Embedded streaming platforms, calendar synchronization, and weather data require ongoing content licensing negotiations. Hotel operators favor this bundle for contactless guest service delivery.
- Touchscreen:Capacitive layers laminated behind dielectric mirror coatings sacrifice reflectivity for direct interaction. Retail fitting rooms and commercial wellness centers favor this modality.
- Gesture Recognition:Time-of-flight cameras and radar sensors interpret hand movements without surface contact. Technical complexity and component cost limit deployment to flagship installations.
Integrated smart features dominate current shipments. Voice control is gaining share fastest.
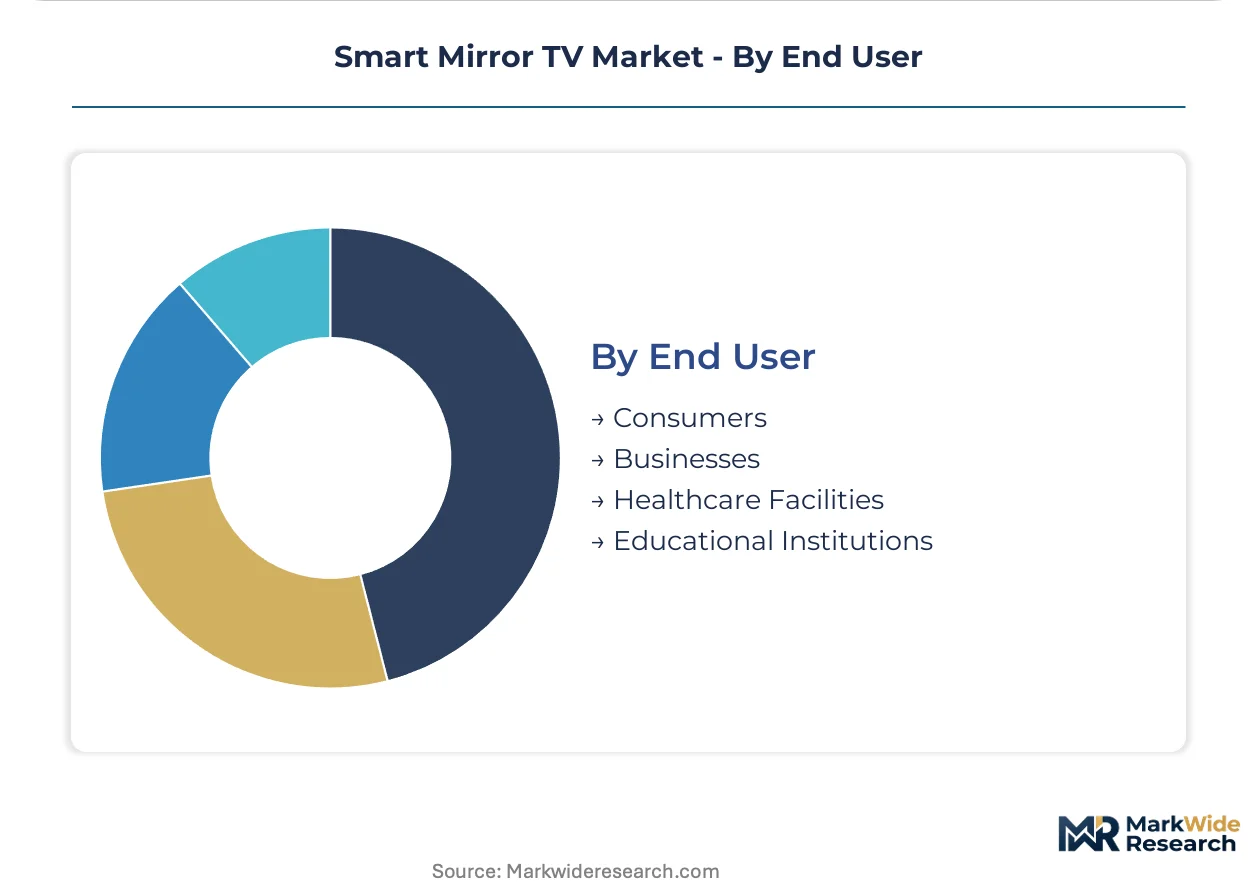
End User:
Procurement authority and specification influence determine channel strategy and margin structure.
- Consumers:Architect and interior designer specification authority concentrates in high-value residential renovation projects. California and New York markets exhibit strongest showroom-driven awareness.
- Businesses:Corporate procurement teams negotiate multi-site installation contracts with fixed-price maintenance provisions. Hospitality chains consolidate bathroom technology spend into single-vendor agreements.
- Healthcare Facilities:Patient room mirror displays for entertainment and telemedicine represent an emerging vertical with distinct antimicrobial surface requirements.
- Educational Institutions:Campus wellness centers and hospitality training facilities generate sporadic demand through capital improvement cycles.
Businesses account for the majority of installed base. Healthcare facilities represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's display manufacturing corridor anchors supply-side capacity for smart mirror TV panel production. Demand fragmentation across hospitality retrofit and residential renovation projects creates distinct regional consumption patterns. Regulatory divergence between energy efficiency mandates and electromagnetic compliance standards shapes market entry sequencing.
United States
Hospitality chains in Las Vegas and Miami drive bathroom technology consolidation into single-vendor contracts. FCC equipment authorization governs radio-enabled mirror TV distribution, with sequential certification timelines creating inventory stranding risk. California and New York metropolitan markets concentrate architect-driven residential specification through direct-to-designer sales channels.
Germany
EU Ecodesign Directive compliance requirements accelerate manufacturer migration toward lower-power OLED architectures. REACH restrictions on hazardous substances in glass coatings reshape material selection protocols for coating operations. Assembly facilities in Bavaria and North Rhine-Westphalia invest in aqueous-process alternatives to satisfy ECHA substance candidate list updates.
United Arab Emirates
Four-star and five-star hotel operators in Dubai specify micro-LED mirror displays for new-build properties. MOHAP facility standards intersect with hospitality technology procurement for wellness center and patient room applications. Premium chains standardize mirror displays across guest bathroom portfolios to differentiate room tiers and capture higher nightly rates.
Singapore
Luxury hotel operators deploy IP65-equivalent sealed units in direct-spray shower environments despite technical constraints. The city-state's position as regional hospitality hub concentrates procurement authority for Southeast Asian property portfolios. Building code harmonization with ASEAN standards influences waterproofing certification tier acceptance across neighboring markets.
United Kingdom
Interior designers and bathroom renovators control product selection in high-value home improvement projects. CE marking and electromagnetic compliance requirements shape European distribution channel access. London metropolitan market showroom-driven awareness campaigns target architect education for vanity-integrated streaming adoption.
Smart Mirror TV Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent smart home integration spaces. The vendor base stratifies across display technology specialization, with captive OLED supply chains conferring procurement advantages on vertically integrated assemblers. Three archetypes dominate: hospitality-focused installation specialists, residential vanity-integrated lighting designers, and display panel manufacturers extending into finished mirror TV products. Competitive moves concentrate on strategic partnerships for content licensing and geographic expansion through regional systems integrator relationships.
Among South Korea-based electronics conglomerates, Samsung Electronics exemplifies the display-integrated archetype through captive OLED manufacturing control. Seura occupies a position within residential bathroom specialists focused on vanity lighting integration. Electric Mirror, Inc. anchors the hospitality installation tier through custom framing and waterproofing capabilities. These three entities represent distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Samsung Electronics |
| Seura |
| Electric Mirror, Inc. |
| Evervue USA Inc. |
| MirrorMedia Ltd. |
| Ad Notam AG |
| Hidden Technology |
| Pro Display |
| Majestic Mirror & Frame |
| Others |
Pricing and Supply Chain Analysis
EU Ecodesign Directive compliance thresholds gate qualified supply for premium-tier smart mirror TV access, compressing margins for legacy LCD assemblers while rewarding OLED and micro-LED adopters with pricing power in hospitality procurement. Energy efficiency mandates reshape cost structures across dielectric coating operations and panel sourcing, forcing manufacturers to absorb certification investments or cede European distribution channels.
Pricing Analysis
Input-cost pass-through from specialized dielectric mirror coatings and captive OLED panel allocations shapes pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on IP65 waterproofing certification grade and hospitality volume scale, with retrofit hotel chains commanding steepest discounts. Pricing pressure stems from raw material competition with semiconductor and solar panel manufacturers for sputtered coating inputs. Residential renovation buyers exhibit highest price sensitivity, while Dubai and Singapore luxury hotel operators absorb premium positioning for micro-LED specifications.
Supply Chain Analysis
Workforce availability constraints in South Korea, Germany, and the Netherlands limit expansion of precision coating cleanroom operations and RF antenna engineering teams. Raw material dependencies center on OLED electroluminescent compounds, quantum dot films, and rare-earth sputtering targets for dielectric stacks. Single-source vulnerability concentrates in South Korean vertically integrated panel supply, where Samsung Electronics controls captive allocation. Distribution runs through hospitality systems integrators for commercial installations and direct-to-designer channels for residential architect specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in micro-LED hospitality specifications and healthcare facility verticals, where premium pricing power offsets dielectric coating cost volatility through energy-efficient architecture premiums.
For Market Incumbents: To counter emerging display-technology entrants from adjacent smart home ecosystems, incumbents should deepen captive OLED supply agreements with South Korean panel manufacturers and secure IP65-plus certification tiers for direct-spray shower environments. Channel control through architect education programs in California and New York metro markets reinforces specification authority against mass-market distributors. For New Entrants and Emerging Players: Regional systems integrators represent the most accessible path into fragmented hospitality procurement outside Dubai and Singapore flagship properties. White-space targets include patient room mirror displays for telemedicine applications and ASEAN market expansion through Singapore-based specification authority. Go-to-market positioning should emphasize Matter protocol interoperability for whole-home automation integration. For Investors and Strategic Acquirers: Roll-up economics work for hospitality installation specialists because procurement consolidation into single-vendor contracts compresses vendor counts and creates scale advantages in waterproofing and content licensing. Long-term viability centers on healthcare facility pivot capabilities and micro-LED technology transitions. The signal to watch is REACH substance candidate list expansion forcing aqueous-process coating investments that favor capitalized operations.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-LED Manufacturing Scale-Up | Dubai and Singapore hotel operators specify zone-dimmable units for new-build properties, compressing legacy LCD addressable market. |
| Matter Protocol Integration | Interoperability certification enables single-dashboard control across lighting, climate, and mirror displays for whole-home automation. |
| Healthcare Facility Partnership | Patient room installations for entertainment and telemedicine open antimicrobial surface requirements distinct from hospitality waterproofing. |
| Aqueous Coating Process Transition | ECHA substance candidate list updates force German and Dutch operations into REACH-compliant material selection protocols. |
| Direct-to-Designer Channel Buildout | California and New York architect specification authority displaces electronics retail for residential vanity-integrated streaming adoption. |
Research Methodology
Multiple input streams — primary interviews with hospitality technology procurement directors, RF antenna design engineers, and dielectric coating operations managers; secondary validation through FCC equipment authorization databases, EU Ecodesign Directive compliance filings, and REACH substance candidate list updates — were reconciled through bottom-up shipment analysis and top-down hospitality capex triangulation.
Historical hospitality retrofit spending patterns were cross-referenced against panel input cost trajectories and architect specification survey panels across the analysis window. Segmentation dimensions modeled include display architecture, waterproofing certification tier, application environment, and smart home ecosystem integration complexity. CAGRs were derived from installation volume build-ups by hospitality chain and residential renovation market, incorporating micro-LED technology transition curves and EU energy efficiency mandate compliance timelines.
Revisions become necessary when REACH substance restrictions expand to additional coating chemistries, South Korean panel allocation agreements shift, or healthcare facility procurement standards crystallize around antimicrobial specifications. Forecasts reflect documented assumptions regarding hospitality technology consolidation rates and residential architect education penetration. Practitioners should monitor ECHA candidate list updates, MOHAP facility standard developments in the UAE, and Matter protocol adoption curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Europe Soundbar Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
Mechanical Keyboard Market