
 Smart Home Connector Market | 2026-2036
Smart Home Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Connector Market Insights
Embedded systems engineering talent is rotating toward RF and low-power wireless design, tightening labor availability for legacy copper-cable connector programs. TE Connectivity leverages its sensor-to-cloud portfolio to anchor integrated smart home infrastructure bids. Molex competes through aggressive geographic expansion in Asian manufacturing clusters. Amphenol differentiates via mil-spec reliability credentials repurposed for residential IoT durability demands.
Smart home connectors are electromechanical interfaces engineered to transmit power and data between distributed IoT nodes, typically rated for 1-10A current loads and operating across 2.4 GHz unlicensed spectrum bands. Zigbee and Z-Wave technology segments retain installed-base dominance where mesh-network resilience matters, while Wi-Fi connectors capture retrofit demand from homeowners prioritizing single-protocol simplicity. Smart hub product types concentrate margin pools through software-attachment economics, whereas smart sensor connectors compete on unit-cost scale.
FCC Part 15 rules govern unintentional radiators in the US market, forcing electromagnetic compatibility testing into product development timelines. CE marking under the EU Radio Equipment Directive shapes access for any supplier serving European installers. Stakeholders must monitor whether Matter certification becomes a de facto gating requirement for retail channel placement.
Market Dynamics
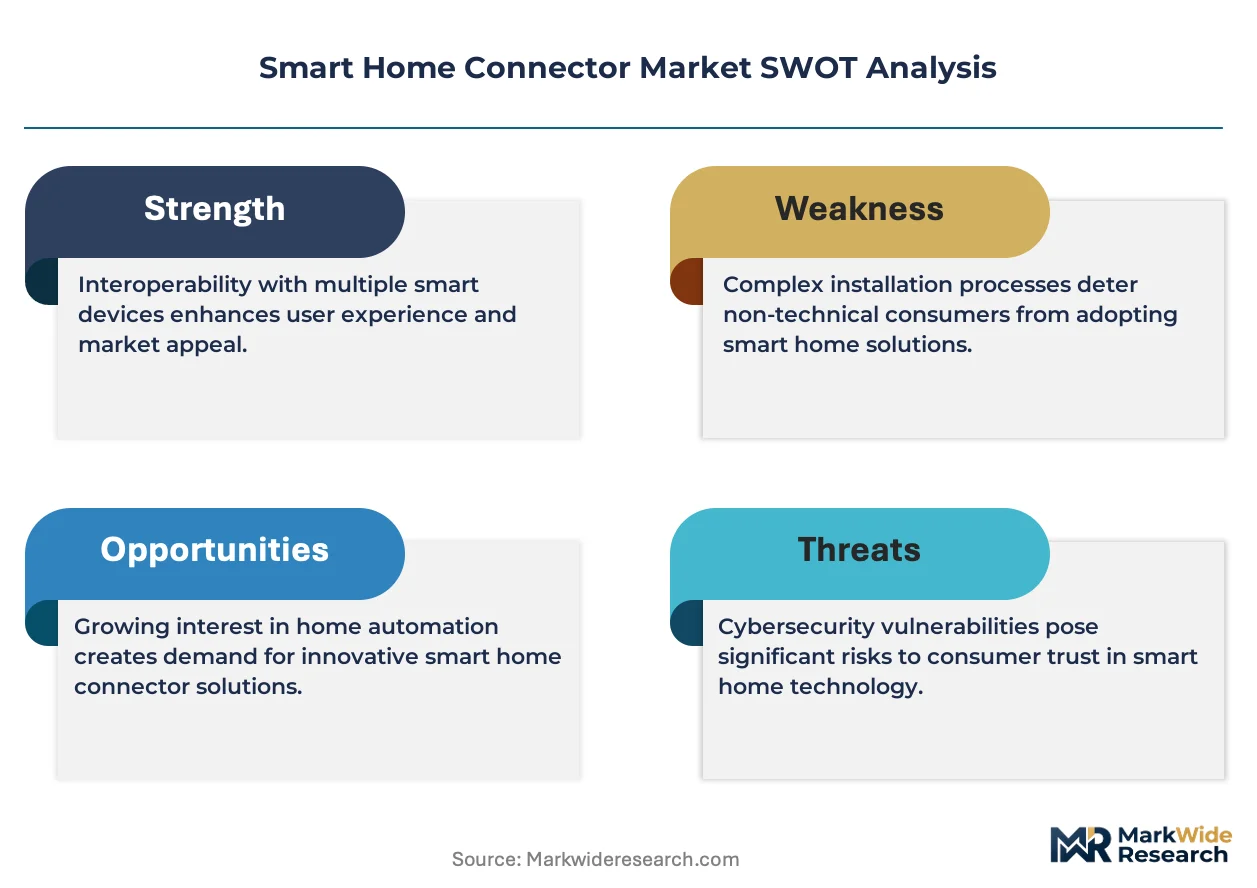
Matter protocol standardization by the Connectivity Standards Alliance is forcing connector manufacturers to retool RF validation pipelines and abandon legacy single-protocol SKUs, compressing product development cycles while expanding addressable device ecosystems.
Growth Catalysts
- Sun Belt Housing Construction:Metropolitan markets across Texas, Florida, and Arizona are embedding pre-wired smart infrastructure into new residential developments, creating captive demand for compatible connector hardware.
- FCC Part 15 Certification:Streamlined electromagnetic compliance pathways for unintentional radiators are accelerating time-to-market for Wi-Fi and Zigbee connector variants targeting US retail channels.
- Mesh Network Resilience Requirements:Industrial IoT deployments in utility and building automation sectors specify Zigbee and Z-Wave connectors for failover-critical infrastructure, sustaining premium pricing for proven reliability grades.
Market Restraints
- Copper Price Volatility:Connector housings and contact pins depend on copper alloy feedstock, exposing gross margins to London Metal Exchange commodity swings without effective hedging instruments at mid-tier manufacturer scale.
- RF Engineering Talent Scarcity:Embedded systems labor pools are rotating toward sensor-to-cloud architecture roles, leaving legacy connector program staffing gaps in North American and European design centers.
- Protocol Proliferation Risk:Matter, Thread, and proprietary vendor stacks are fragmenting SKU requirements, forcing inventory carrying costs upward for distributors serving multi-brand installer networks.
Strategic Opportunities
- Retrofit Channel Expansion:Big-box retail and direct-to-consumer e-commerce platforms are capturing Wi-Fi-first smart home upgrades from homeowners avoiding professional installation, creating connector packaging and support service opportunities.
- EU Radio Equipment Directive Alignment:CE marking harmonization across member states enables single-SKU strategies for Matter-certified connectors, reducing compliance overhead for suppliers entering German, French, and Dutch markets.
- Sensor-to-Hub Integration:Converging power and data transmission in unified connector footprints is enabling thinner wall-plate designs and reduced wiring complexity for residential automation integrators.
Industry Challenges
- Matter Certification Timelines:CSA interoperability testing queues are extending product launch windows, forcing manufacturers to sequence market entry around certification batch availability rather than production readiness.
- Legacy Z-Wave Inventory Stranding:Installer networks with sunk costs in 908.42 MHz infrastructure face technical obsolescence risk as 800-series chipsets and S2 security frameworks require connector hardware refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Connector Market |
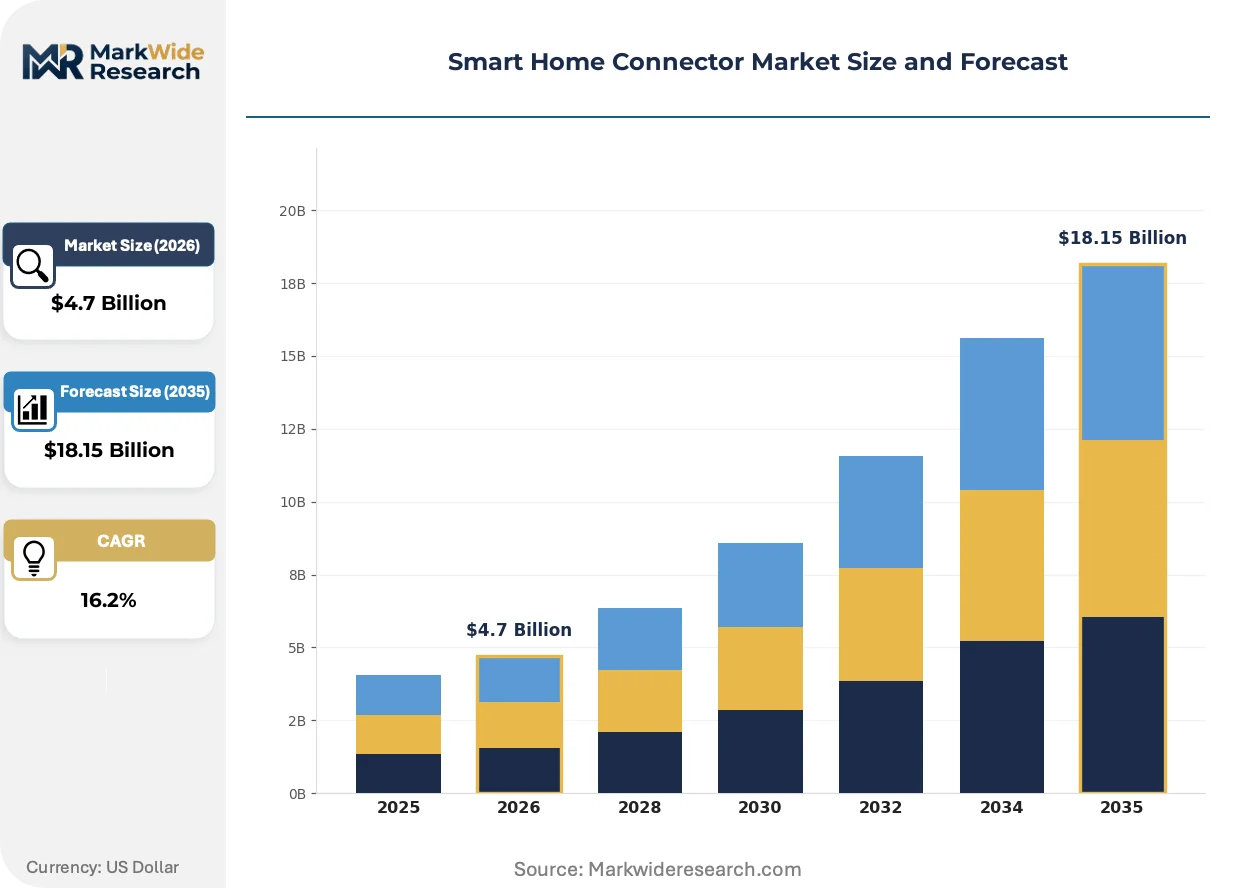
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $18.15 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Hub, Smart Plug, Smart Light Switch, Smart Sensor Technology: Zigbee, Z-Wave, Wi-Fi, Bluetooth End User: Homeowners, Property Managers, Builders, Designers Installation Type: DIY, Professional, Retrofit, New Construction |
| Companies Covered | Tyco Electronics, Amphenol, Molex, Foxconn, Yazaki, TE Connectivity, Samtec, Hirose Electric, JST Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Connector Market Trends and Innovations
Connector engineering priorities are pivoting from mechanical durability specifications toward RF performance optimization and multi-protocol software configurability, reflecting the protocol-layer convergence that Matter certification demands.
Thread radio modules with integrated PCB antennas are supplanting discrete connector-and-antenna assemblies in thermostat, lock, and lighting control hardware. Residential OEMs in the US and Germany are adopting these consolidated RF front-ends to reduce BOM line-item count and assembly labor. This integration is compressing the addressable market for standalone RF connector suppliers while expanding value-capture opportunities for module vendors with captive connector fabrication.
CE marking under the EU Radio Equipment Directive is mandating enhanced cybersecurity documentation and supply-chain traceability for radio equipment entering European markets. Connector manufacturers must now maintain technical file archives spanning material composition, firmware versioning, and electromagnetic test reports. German and Dutch distribution channels are prioritizing suppliers with pre-validated RED compliance packages, creating certification-driven supplier selection criteria.
Professional installer procurement patterns are fragmenting across specialized distributor, direct-from-manufacturer, and marketplace channels as margin pressure drives sourcing optimization. US residential automation contractors are consolidating purchases through regional electrical distributors offering credit terms and same-day availability, displacing traditional electronics component catalogs. This channel rotation is most pronounced in Texas and Florida metropolitan markets where installer density supports distributor inventory investment in Matter-certified SKUs.
Smart Home Connector Market Segmentation
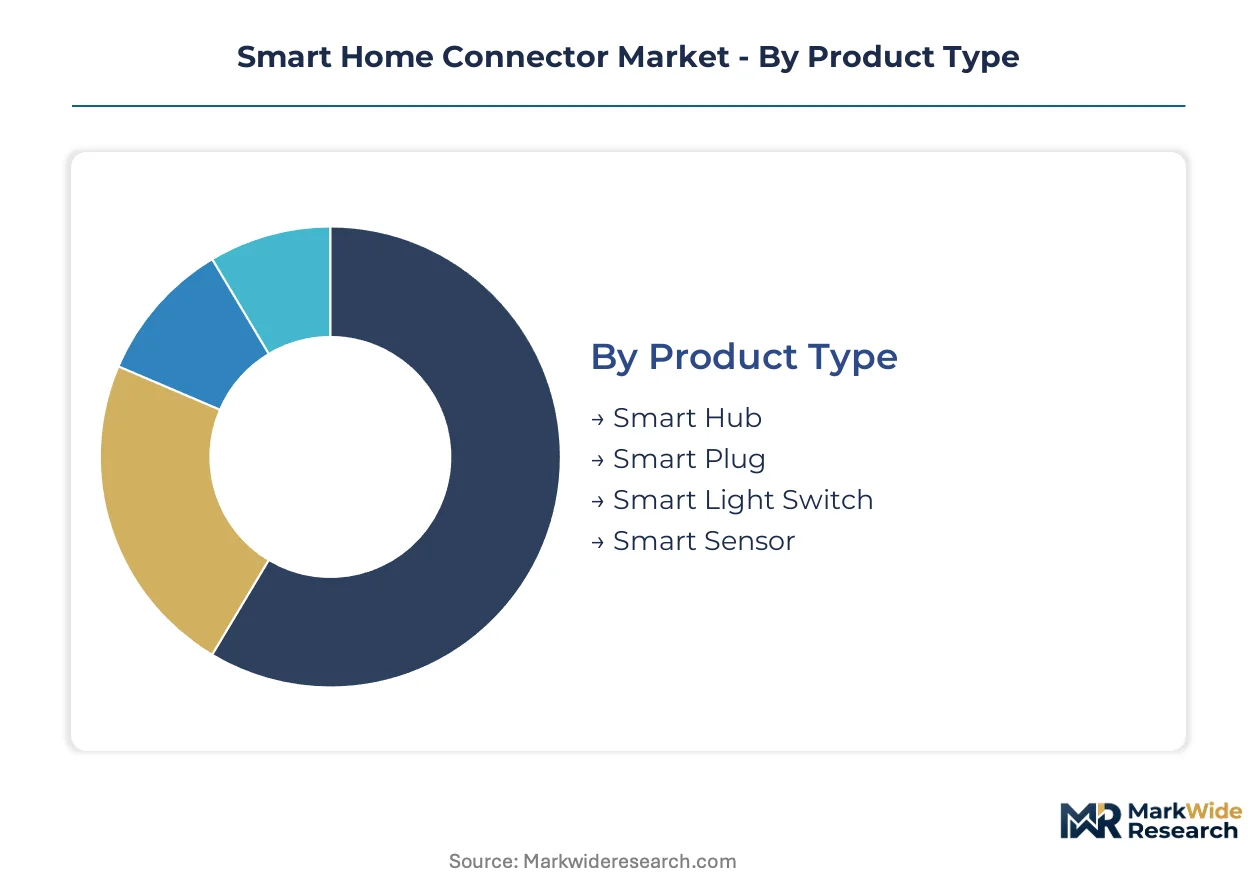
Smart home connector purchasing flows through distinct channel architectures that reward different product configurations. Segmentation reveals where margin pools concentrate versus where volume scales, guiding portfolio prioritization for manufacturers navigating protocol transition.
Product Type:
Professional integrators in Texas and Florida metropolitan markets pull smart hub connectors through electrical distributors offering credit terms and same-day availability. Big-box retail channels capture Wi-Fi-first smart plug demand from homeowners avoiding installation services.
- Smart Hub:Centralized controllers aggregate multi-protocol device traffic through unified backplanes. Demand concentrates in Sun Belt new construction where builders pre-wire infrastructure for whole-home automation, with Matter certification now gating retail placement.
- Smart Plug:Inline power control modules with integrated RF radios serve retrofit upgrades prioritizing single-protocol simplicity. Expansion concentrates in direct-to-consumer e-commerce where packaging and support services differentiate commoditized hardware.
- Smart Light Switch:Wall-plate replacements requiring neutral wire compatibility dominate professional installation channels.
- Smart Sensor:Battery-powered environmental and occupancy detectors compete on unit-cost scale in security system bundles.
Smart hub connectors dominate installed base through software-attachment economics. Smart plug variants are where expansion concentrates fastest among DIY upgraders.
Technology:
Cost tiering separates premium mesh-network resilience from economy Wi-Fi simplicity, with protocol choice determining certification burden and RF engineering intensity.
- Zigbee:Mesh-networking stack operating at 2.4 GHz with self-healing topology for failover-critical infrastructure. Demand concentrates in utility and building automation sectors specifying proven reliability grades for industrial IoT deployments.
- Wi-Fi:Single-protocol connectivity leveraging existing residential access point infrastructure without dedicated hub hardware. Expansion concentrates in retrofit channels where homeowners prioritize immediate smartphone control over ecosystem depth.
- Z-Wave:Sub-GHz mesh protocol with regional frequency variants requiring hardware customization per market.
- Bluetooth:Point-to-point pairing for proximity-based device commissioning and firmware updates.
Zigbee connectors retain installed-base dominance where mesh resilience matters. Wi-Fi variants are climbing the fastest as retrofit simplicity outweighs ecosystem lock-in concerns.
End User:
Customer type determines specification intensity, with commercial procurement demanding traceability documentation that residential buyers waive.
- Homeowners:Individual purchasers selecting Wi-Fi-first solutions through retail and marketplace channels, prioritizing smartphone app compatibility over interoperability depth.
- Property Managers:Multi-unit operators standardizing on Zigbee infrastructure for centralized building control and tenant turnover efficiency.
- Builders:New construction developers embedding pre-wired smart infrastructure in Sun Belt metropolitan housing markets, creating captive demand for Matter-certified hardware.
- Designers:Residential architects specifying invisible integration through unified power-data connectors enabling thinner wall-plate aesthetics.
Builders dominate volume commitment through development-scale procurement. Property managers represent the steepest expansion trajectory as rental housing automation penetrates secondary markets.
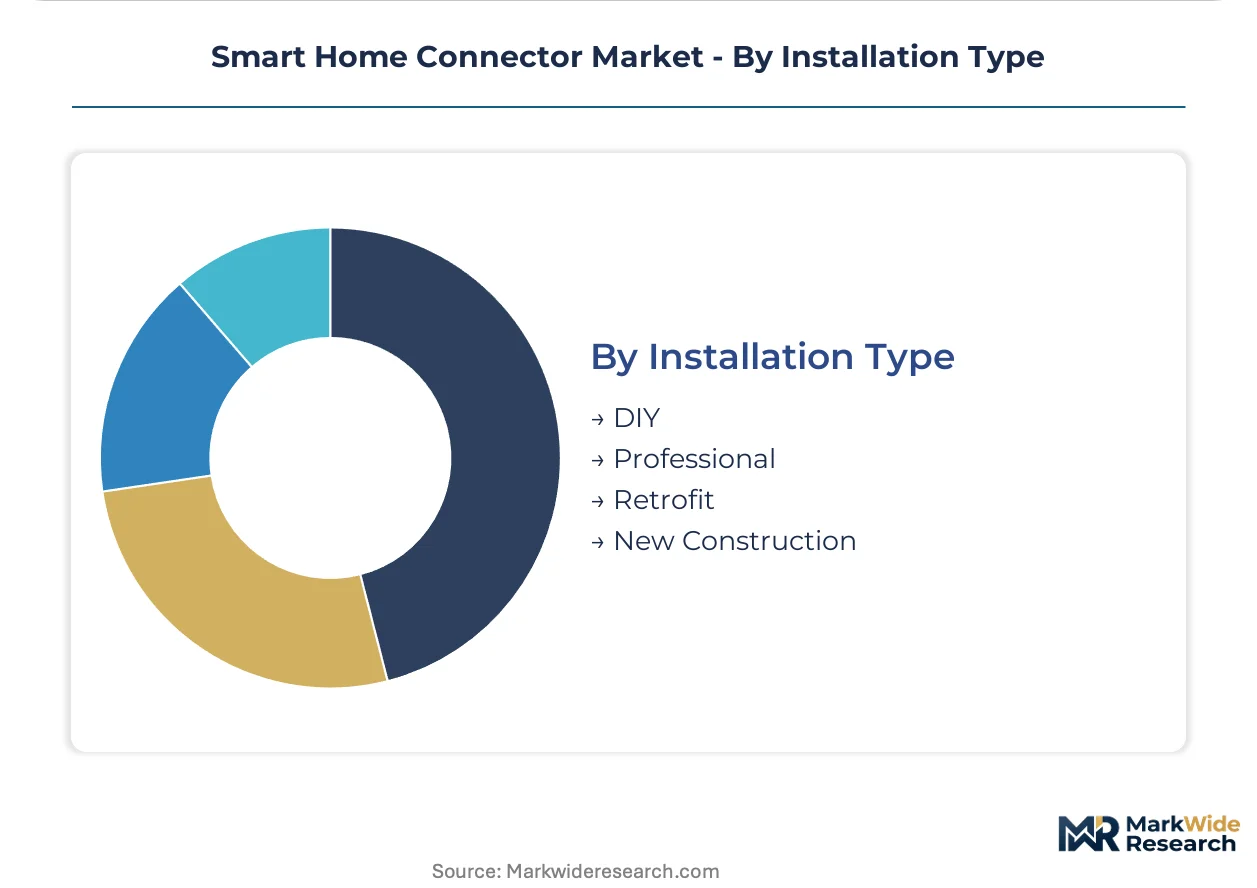
Installation Type:
Maturity differentiation separates established professional channels from emerging self-install segments, with retrofit complexity driving support service attach rates.
- Professional:Licensed electrician and automation contractor installation requiring UL-listed hardware and liability coverage, concentrated in new construction and whole-home retrofits.
- DIY:Consumer self-installation of battery-powered and plug-in devices avoiding electrical permitting, expanding through unboxing-optimized packaging and video-guided setup.
- Retrofit:Replacement of legacy switches and outlets in occupied residences, demanding compatibility with aging electrical boxes and wiring configurations.
- New Construction:Pre-wired infrastructure installation during framing and drywall phases, enabling concealed routing and dedicated neutral wires at every switch location.
Professional installation dominates value capture through labor bundling. DIY channels are gaining share fastest as simplified commissioning protocols reduce technical failure rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 certification pathways anchor North American market entry, while CE marking under the EU Radio Equipment Directive governs European access. Regional demand clusters around metropolitan housing markets with active new construction and retrofit upgrade cycles.
United States
Sun Belt metropolitan markets across Texas, Florida, and Arizona embed pre-wired smart infrastructure into new residential developments. FCC Part 15 rules govern unintentional radiators, forcing electromagnetic compatibility testing into product development timelines. Houston and Phoenix electrical distributors now carry Matter-certified SKU inventories to serve installer density.
Germany
CE marking harmonization under the EU Radio Equipment Directive enables single-SKU strategies for Matter-certified connectors. The country's national telecommunications regulator enforces cybersecurity documentation and supply-chain traceability requirements. Munich and Stuttgart industrial clusters concentrate module vendors with captive connector fabrication capabilities.
China
MIIT standards for radio transmission equipment shape domestic certification requirements for 2.4 GHz and sub-GHz connector variants. The Pearl River Delta manufacturing corridor anchors global production capacity for RF front-end modules. Shenzhen-based fabricators supply integrated PCB antenna assemblies that compress demand for discrete connector components.
Japan
METI energy efficiency guidelines influence smart home device specifications in residential construction. JIS standards govern electromechanical interface durability ratings for IoT applications. Tokyo and Osaka metropolitan areas concentrate property management automation procurement for multi-unit housing stock.
United Kingdom
Building regulations for new residential construction increasingly mandate smart-ready electrical infrastructure. The country's national standards body oversees electromagnetic compatibility testing alignment with EU frameworks pre- and post-Brexit. London and Southeast England installer networks drive demand for unified power-data connectors enabling thinner wall-plate designs.
Smart Home Connector Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium reliability grades commanding pricing power in industrial IoT segments while scale-driven manufacturers capture consumer retrofit volume. The vendor base spans three strategic tiers: diversified electromechanical conglomerates with sensor-to-cloud portfolios, specialized RF connector houses with mil-spec credentials, and integrated module vendors with captive fabrication. Competitive moves concentrate on geographic expansion in Asian manufacturing clusters and protocol certification pre-validation to accelerate retail channel placement.
Among diversified electromechanical conglomerates, TE Connectivity and Amphenol occupy positions at opposite ends of the integration spectrum. TE Connectivity exemplifies the sensor-to-cloud portfolio anchor, while Amphenol represents the mil-spec reliability credential repurposed for residential IoT durability demands. Molex sits within the geographic expansion archetype, with manufacturing presence across Asian production clusters.
| Leading Market Players |
|---|
| Tyco Electronics |
| Amphenol |
| Molex |
| Foxconn |
| Yazaki |
| TE Connectivity |
| Samtec |
| Hirose Electric |
| JST Corporation |
| Others |
Pricing and Supply Chain Analysis
FCC Part 15 electromagnetic compliance certification gates both supplier qualification and price differentiation simultaneously, forcing connector manufacturers to absorb testing overhead while tiering offerings around certification batch availability and RF validation intensity.
Pricing Analysis
US-German price spreads for Matter-certified smart hub connectors exceed those for legacy Z-Wave variants by meaningful margins due to CSA interoperability testing queues and regional distributor markup structures. Three-tier pricing structure across premium mesh-resilience, standard multi-protocol, and economy Wi-Fi-only levels separates industrial IoT procurement from residential retrofit channels. Pricing pressure stems from copper alloy feedstock volatility on the London Metal Exchange, compressing gross margins for mid-tier manufacturers lacking hedging instruments. DIY homeowners through big-box retail exhibit highest price sensitivity, while utility sector building automation contractors prioritize reliability grades over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate among Texas and Florida electrical distributors serving professional installer networks, whereas Asian module vendors maintain strategic stockpiles of integrated PCB antenna assemblies to buffer CSA certification delays. Manufacturing gravity centers on China, South Korea, and Vietnam for RF front-end module fabrication, with Shenzhen-based fabricators supplying consolidated antenna-connector assemblies. Copper alloy contact pins and 2.4 GHz radio chipsets constitute critical input dependencies, exposing production schedules to semiconductor foundry allocation cycles. Single-source vulnerability concentrates in CSA interoperability testing capacity, where batch queue extensions strand finished goods inventory. Distribution runs through regional electrical distributors in Sun Belt metropolitan markets, displacing traditional electronics component catalogs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter protocol standardization by the Connectivity Standards Alliance triggers platform-economics inflection, consolidating device ecosystems around unified certification requirements that reshape value capture toward software-attachment models and away from hardware margin stacking.
For Market Incumbents: Shield installed-base positions in Zigbee utility and building automation sectors by accelerating S2 security framework migration ahead of 800-series chipset obsolescence, while deepening backward integration into RF validation pipeline capacity to bypass CSA certification queues. Prioritize captive testing laboratory investment as the defensive lever against emerging module vendors with integrated antenna-connector fabrication. For New Entrants and Emerging Players: Differentiate on retrofit channel packaging and support services for Wi-Fi-first smart plug demand, targeting direct-to-consumer e-commerce white space where unboxing-optimized commissioning protocols reduce technical failure rates. German and Dutch markets present most penetrable geography given CE marking harmonization enabling single-SKU strategies, with Matter-certified hub connectors as the priority product entry point. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across standalone RF connector suppliers as integrated module vendors capture value through captive fabrication, compressing returns for discrete component manufacturers without sensor-to-cloud portfolio breadth. Acquisition targets should display pre-validated RED compliance packages and CSA certification batch relationships. Watch CSA interoperability testing queue lengths as the inflection signal for hardware margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Pre-Validation | CSA batch queue positioning accelerates retail channel placement before competitor hardware reaches market. |
| Sensor-to-Hub Integration R&D | Converged power-data transmission footprints enable thinner wall-plate designs for residential automation integrators. |
| Sun Belt Distributor Partnership | Texas and Florida electrical distributor credit terms capture professional installer procurement consolidation. |
| RF Engineering Talent Acquisition | Embedded systems labor rotation toward sensor-to-cloud roles leaves legacy connector program staffing gaps to exploit. |
| Copper Alloy Feedstock Hedging | London Metal Exchange commodity instruments protect gross margins against contact pin material volatility. |
Research Methodology
A standing panel of residential automation integrators, electrical distributor procurement managers, RF module vendor product strategists, and CSA certification engineers provided ongoing calibration across primary interview cycles, cross-referenced against FCC Part 15 filing databases, EU Radio Equipment Directive technical file archives, MIIT radio transmission equipment registrations, and customs trade data for connector component flows. Bottom-up unit economics from installer channel interviews triangulated against top-down market sizing from regulatory filing aggregation.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler smart home device shipment disclosures, semiconductor foundry utilization reports, and metropolitan housing construction permit databases across the analysis window. Segmentation modeling spanned product type, technology protocol, end-user archetype, and installation channel, with CAGRs derived from protocol transition velocity assumptions and new construction automation penetration curves. Copper price elasticity coefficients and RF engineering wage inflation indexes fed industry-specific forecast adjustments.
Decision-makers should treat outputs as directional under assumptions of Matter certification adoption velocity and Sun Belt housing construction continuity; material deviation in CSA queue lengths or copper volatility would warrant model refresh. Revision becomes warranted when Thread radio module integration rates cross thresholds that compress standalone connector addressable market beyond modeled compression curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Cat Accessories Market
Consumer Goods
Dog Vest Market
Consumer Goods
Waterproof Cases Market
Consumer Goods
Mexico Beard Trimmer Market
Consumer Goods
Germany Vegan Cosmetics Market
Consumer Goods
Global Residential Microwave Oven Market
Consumer Goods
Frozen Pet Food Market
Consumer Goods
Smart Connected Diaper Market
Consumer Goods
Reusable Baby Diapers and Training Pants Market
Consumer Goods
Cat Calming Treats Market
Consumer Goods
Deodorant Wipes Market
Consumer Goods
Baby Safety Products Market
Consumer Goods
Facial Rollers Market
Consumer Goods
Colombia Appliances and Electronics Market
Consumer Goods
Baby Bottle Holder Market
Consumer Goods
Hands-Free Faucet Market