
 Professional Headset Market | 2026-2036
Professional Headset Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Headset Market Analysis
Vietnam is rewriting assembly economics for professional audio hardware as contract manufacturers expand acoustic testing and driver calibration lines north of Ho Chi Minh City. Sennheiser Electronic leverages its German engineering heritage to sustain premium positioning in broadcast and studio monitoring tiers. Shure Inc. anchors professional audio channel relationships through direct distribution to touring and installed-sound contractors. Logitech International competes across mass-market corporate rollouts with unified communications certifications from Microsoft Teams and Zoom.
Professional headsets are electro-acoustic transducer assemblies designed to convert electrical signals into precise sound reproduction across 20 Hz to 20 kHz frequency ranges, with noise-canceling variants adding feedforward and feedback microphone arrays for active ambient attenuation. Their primary commercial purpose is to deliver intelligible voice communication and accurate audio monitoring in environments where acoustic isolation and extended wear comfort determine productivity outcomes. Wireless headsets incorporating Bluetooth and DECT protocols now lead corporate office and call center procurement as IT departments phase out analog desk phones. Gaming headsets represent the fastest-growing product type as esports broadcasting and streaming creator economies expand hardware requirements for positional audio and broadcast-grade microphone clarity.
FCC Part 15 governs unlicensed radio frequency emissions for Bluetooth and DECT headsets sold in the United States, while CE marking under the EU Radio Equipment Directive mandates SAR testing and interoperability disclosure for European market access. OSHA occupational noise exposure limits indirectly shape enterprise procurement criteria by favoring headsets with output limiting and volume monitoring features. Stakeholders must weigh DECT spectrum reallocation risks against Bluetooth LE Audio migration timelines when committing to multi-year platform contracts.
Market Dynamics
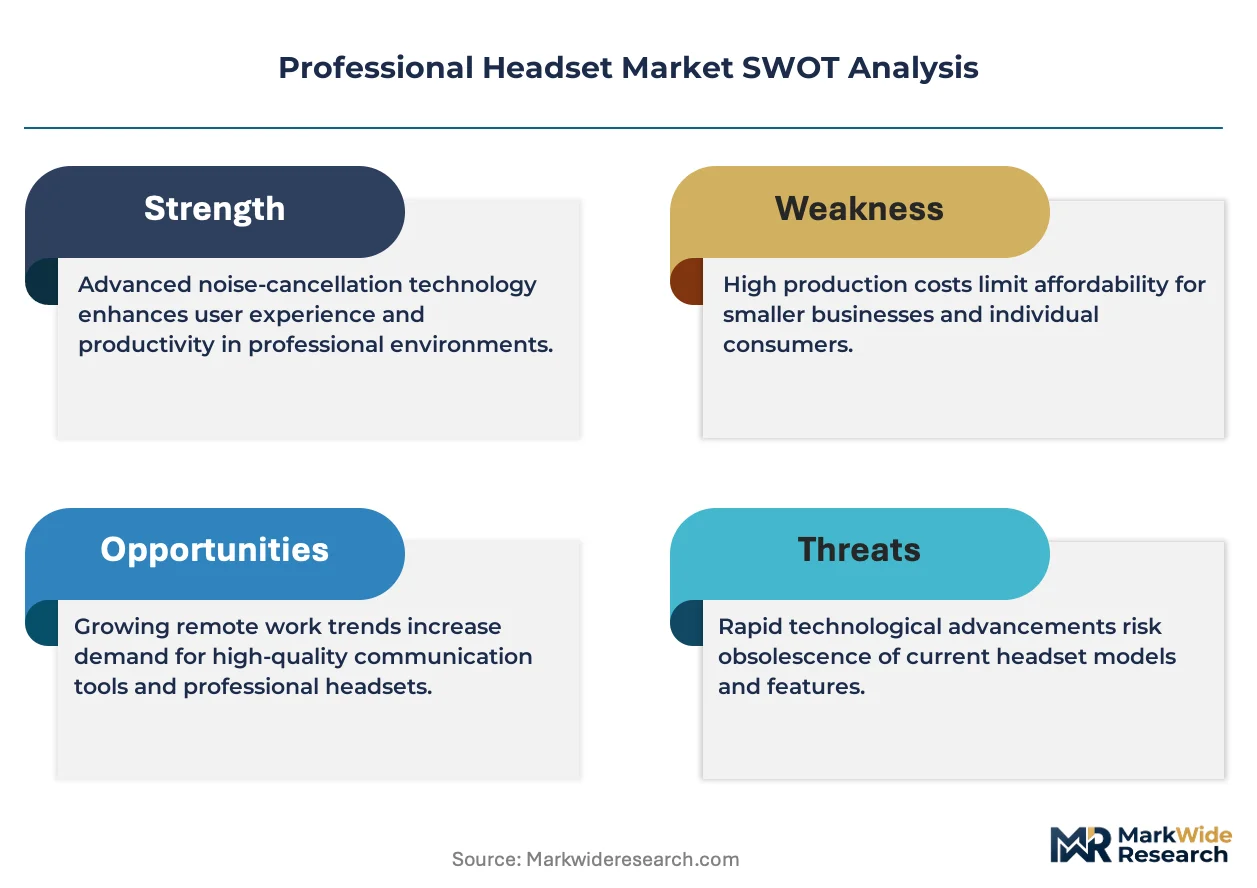
Wireless protocol migration is compressing replacement cycles across enterprise estates as IT departments sunset analog desk phones and DECT infrastructure simultaneously.
Growth Catalysts
- FCC Part 15 tightening:Stricter RF emission tolerances for unlicensed radio devices are forcing hardware refresh across call center operations in the United States.
- Hybrid work infrastructure:Corporate spending on home office equipment sustains premium headset procurement across distributed workforces.
- Bluetooth LE Audio:Next-generation codec efficiency is enabling multi-stream broadcast features that differentiate enterprise-grade wireless peripherals.
Market Restraints
- Neodymium magnet supply:Rare earth processing concentration in China creates input cost volatility for driver assembly.
- DECT spectrum reallocation:Regulatory uncertainty around 1.9 GHz band usage in Europe extends procurement decision timelines.
- Smartphone substitution:Improved native speakerphone arrays in mobile devices reduce peripheral dependency for casual voice calls.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting acoustic testing and final assembly capacity to Tamil Nadu and Karnataka clusters.
- OSHA output limiting:Occupational noise exposure compliance creates mandated upgrade paths for enterprises with volume monitoring requirements.
- AI-enhanced noise suppression:On-device neural processing convergence with beamforming microphone arrays opens broadcast-tier feature democratization.
Industry Challenges
- Acoustic engineering talent:Driver tuning and anechoic chamber calibration expertise concentrates in legacy audio hubs, constraining rapid capacity expansion.
- Unified communications certification:Microsoft Teams and Zoom platform validation timelines extend product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Headset Market |
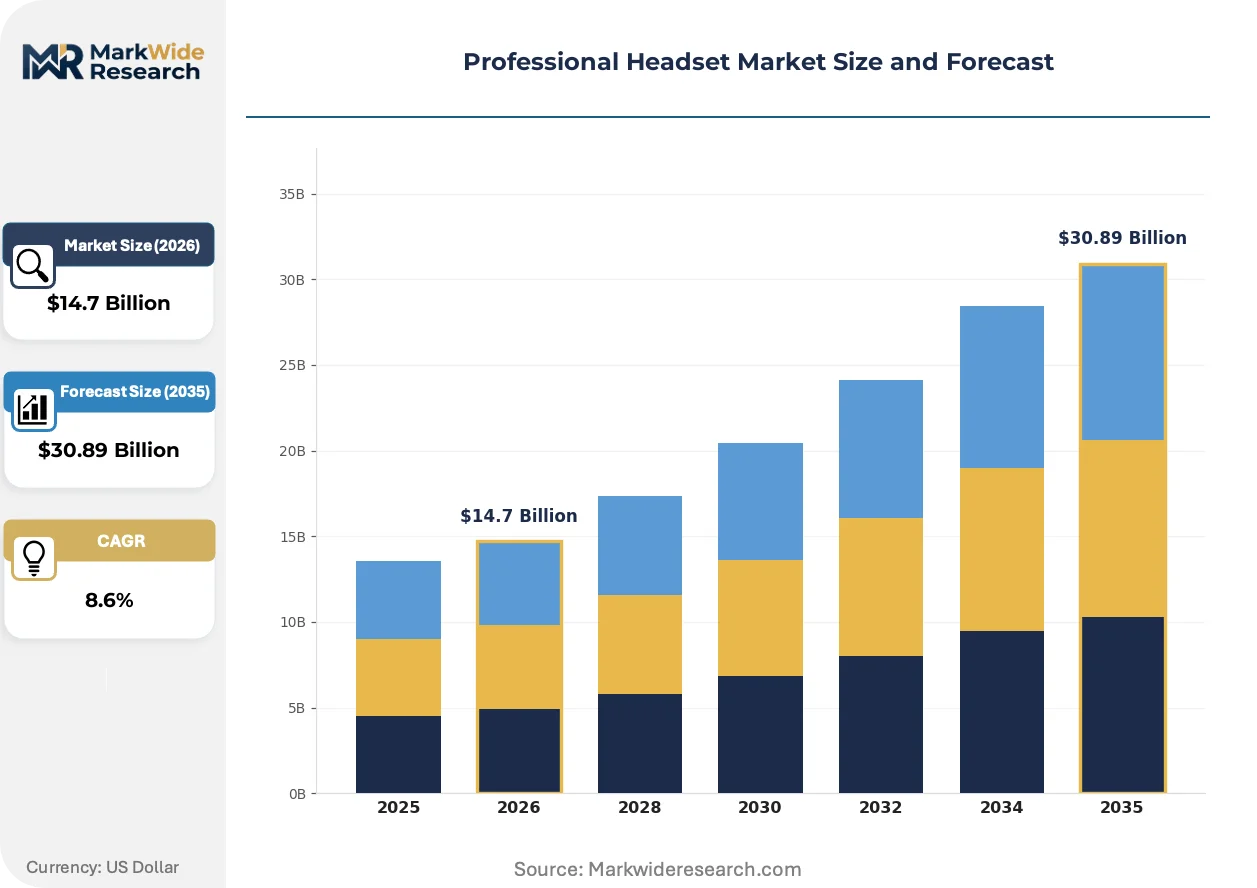
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
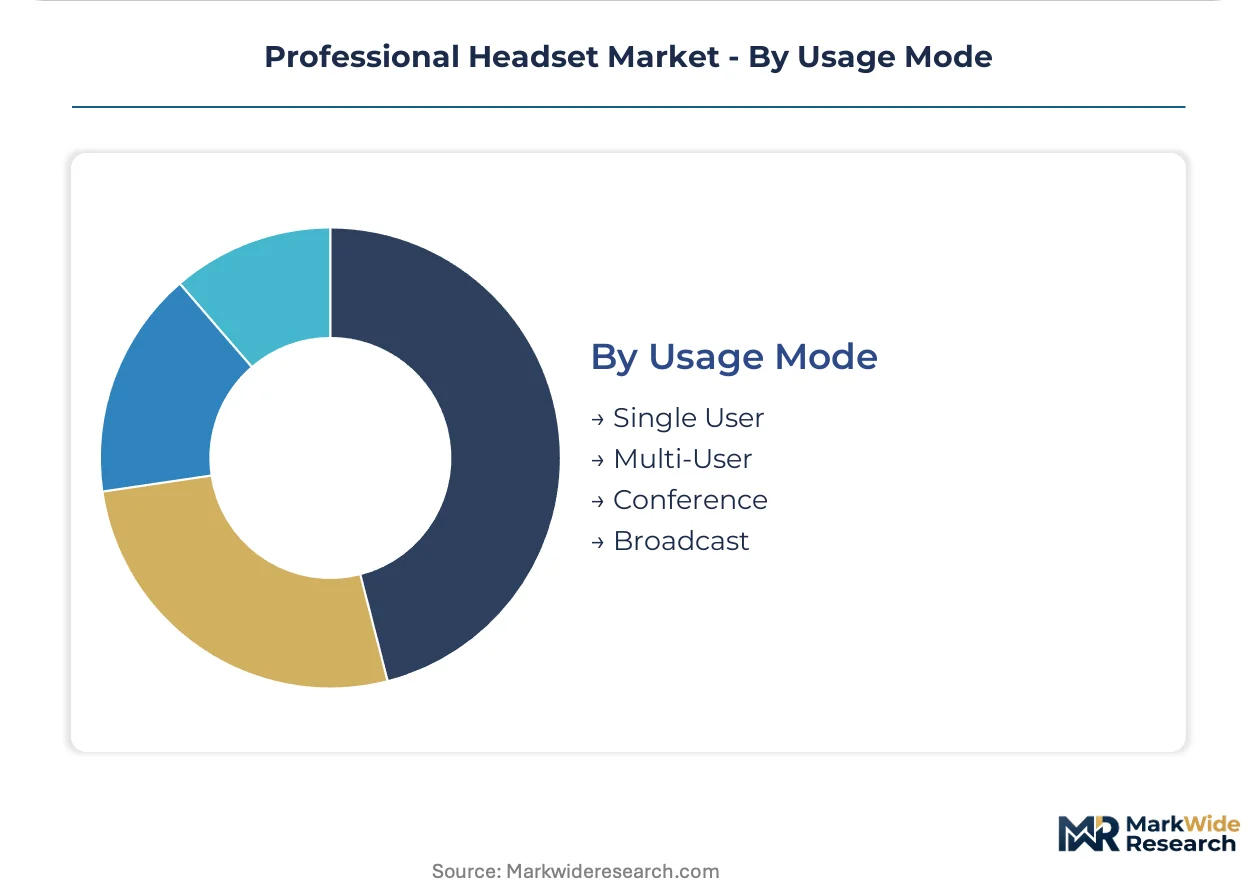
| Segmentation | Product Type: Wired Headsets, Wireless Headsets, Noise-Canceling Headsets, Gaming Headsets Technology: Bluetooth, DECT, USB-C, Analog End User: Corporate Offices, Call Centers, Home Offices, Educational Institutions Usage Mode: Single User, Multi-User, Conference, Broadcast |
| Companies Covered | Sennheiser Electronic, Shure Inc., Logitech International, Beyerdynamic, Audio-Technica Corporation, HP Inc. (Poly), Sony Corporation, SteelSeries, GN Store Nord (Jabra), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Headset Market Emerging Trajectories
Active noise cancellation architectures are fragmenting into application-specific implementations as feedforward, feedback, and hybrid topologies diverge across use cases.
Beamforming microphone arrays is hybridizing voice pickup precision with spatial audio capture for conferencing and content creation. Enterprise IT buyers are specifying three-mic configurations for open-plan environments. The technology is hybridizing call center hardware requirements with creator economy streaming specifications, collapsing previously separate product categories.
EU Radio Equipment Directive interoperability disclosure mandates are forcing firmware transparency for Bluetooth stack implementations. Manufacturers must document protocol version support and codec compatibility prior to CE marking. Professional audio channels in Germany and France are prioritizing vendors with pre-certified module architectures to accelerate deployment.
Bulk enterprise purchasing through managed service providers is displacing direct channel relationships for standardized deployments. Hardware-as-a-service models bundle device provisioning, firmware updates, and replacement logistics. This pattern concentrates in United States healthcare and financial services verticals with stringent endpoint management requirements.
Professional Headset Market Segmentation
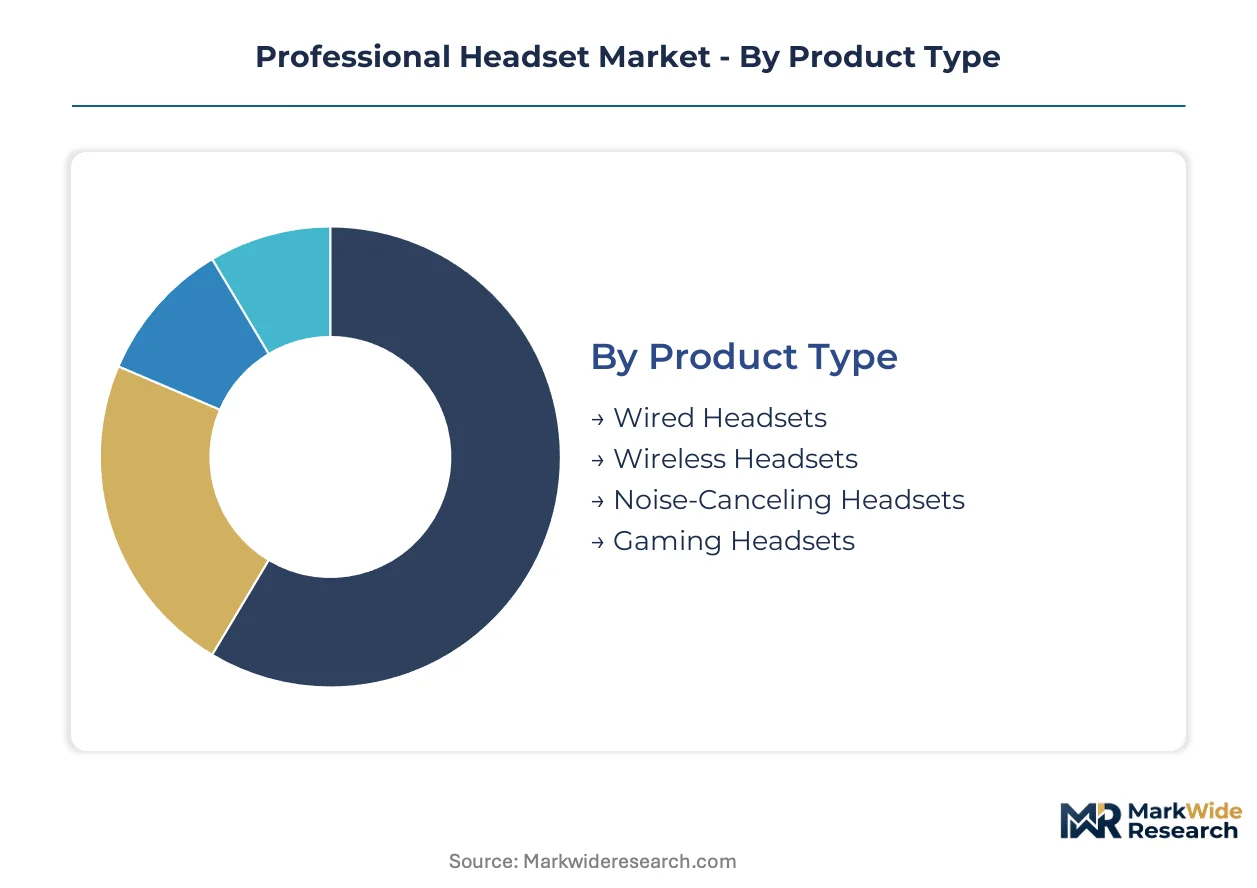
Professional headset procurement patterns diverge sharply across connectivity protocols, acoustic architectures, and deployment environments. Each segmentation dimension captures distinct margin structures, certification requirements, and replacement cycle dynamics that reshape vendor positioning.
Product Type:
Cost tier stratification separates premium acoustic engineering from mass-market standardization across four hardware categories.
- Wireless Headsets:Bluetooth LE Audio and DECT implementations now dominate corporate IT refresh cycles as enterprises phase out tethered desk phones. United States hybrid work infrastructure sustains premium procurement for distributed teams requiring all-day battery endurance and seamless device switching.
- Gaming Headsets:Positional audio processing and broadcast-grade microphone clarity serve esports broadcasting and streaming creator economies. Vietnam assembly lines north of Ho Chi Minh City are expanding driver calibration capacity to match this segment's acoustic precision demands.
- Wired Headsets:USB-C and analog variants retain niche presence in high-security environments and legacy call center estates.
- Noise-Canceling Headsets:Feedforward-feedback hybrid architectures command premium positioning for open-plan corporate deployments and frequent travelers.
Wireless configurations command the established base. The steepest expansion runs through gaming headsets.
Technology:
Protocol selection determines RF regulatory exposure, power efficiency, and interoperability certification burdens for enterprise buyers.
- Bluetooth:LE Audio codec efficiency enables Auracast broadcast features and multi-stream reception that differentiate next-generation enterprise peripherals. FCC Part 15 emission tolerances tighten hardware refresh requirements across United States corporate estates.
- DECT:Dedicated 1.9 GHz spectrum delivers interference-free voice quality in high-density call center environments. European spectrum reallocation uncertainty extends procurement decision timelines as regulators reassess band usage rights.
- USB-C:Digital audio and power delivery consolidation simplifies cable management for hot-desking corporate offices.
- Analog:3.5mm and 2.5mm connectors persist in aviation, healthcare, and legacy installed-sound systems requiring backward compatibility.
Bluetooth anchors volume leadership. DECT retains margin concentration despite regulatory headwinds.
End User:
Customer type segmentation maps acoustic isolation requirements, wear-time endurance, and fleet management complexity across four deployment contexts.
- Call Centers:Eight-hour shift endurance and OSHA output limiting compliance drive hardware specifications for agent productivity and hearing conservation. United States FCC Part 15 refresh cycles accelerate turnover in this price-sensitive volume segment.
- Corporate Offices:Hybrid work infrastructure spending sustains premium procurement across home office and headquarters deployments. Microsoft Teams and Zoom certification requirements extend product validation timelines.
- Home Offices:Individual purchasers prioritize comfort and aesthetics over enterprise-grade manageability.
- Educational Institutions:Bulk purchasing through managed service providers displaces direct procurement for standardized campus deployments.
Call centers anchor unit volume. Corporate offices capture value concentration.
Usage Mode:
Application intensity shapes microphone array complexity, acoustic isolation requirements, and multi-user hygiene protocols.
- Conference:Beamforming three-microphone configurations with spatial audio capture serve open-plan huddle rooms and video collaboration platforms. EU Radio Equipment Directive interoperability disclosure mandates force firmware transparency for Bluetooth stack implementations.
- Broadcast:Anechoic chamber-calibrated driver matching and broadcast-grade microphone clarity serve radio, podcast, and streaming production workflows. Acoustic engineering talent scarcity constrains rapid capacity expansion for this precision tier.
- Single User:Individual wear patterns dominate enterprise and consumer procurement.
- Multi-User:Shared device protocols and replaceable ear cushions address healthcare and hot-desking hygiene requirements.
Single-user configurations dominate shipment volume. Conference applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 tightening in the United States accelerates hardware refresh cycles across call center operations and corporate estates. Demand concentrates in North American and European markets where hybrid work infrastructure sustains premium procurement, while Asian manufacturing clusters expand acoustic testing capacity to serve global supply chains.
United States
Enterprise IT refresh cycles and hybrid work infrastructure spending drive premium headset procurement across corporate and home office segments. FCC Part 15 rules on unlicensed radio devices tighten RF emission tolerances for wireless audio peripherals, forcing hardware turnover. Dallas and Austin clusters anchor call center technology deployment and enterprise audio procurement.
Germany
Broadcast and studio monitoring tiers sustain demand for precision acoustic engineering in professional audio channels. CE marking under the EU Radio Equipment Directive mandates SAR testing and interoperability disclosure for market access. Berlin and Hamburg clusters concentrate acoustic engineering talent and anechoic chamber calibration expertise.
Vietnam
Contract manufacturers expand acoustic testing and driver calibration lines to capture assembly economics for professional audio hardware. The country's electronics manufacturing incentives attract final assembly capacity from established audio brands. Ho Chi Minh City northern industrial zones scale driver calibration operations for gaming headset precision demands.
India
Production-linked incentives for electronics manufacturing attract acoustic testing and final assembly capacity to southern industrial corridors. BIS certification requirements shape product localization strategies for domestic market access. Tamil Nadu and Karnataka clusters expand contract manufacturing capacity for professional audio peripherals.
United Kingdom
Corporate office deployments and managed service provider bundles sustain enterprise procurement through standardized hardware-as-a-service models. GDPR compliance requirements influence endpoint management specifications for healthcare and financial services verticals. London and Southeast England clusters concentrate unified communications platform integration and certification services.
Professional Headset Market Vendor Landscape
Precision engineering specialists and mass-market platform vendors split the market across margin-divergent tiers. German and Japanese heritage brands anchor premium broadcast and studio monitoring segments through acoustic engineering differentiation. Scale-driven peripherals manufacturers compete on unified communications certification velocity and enterprise procurement channel access. M&A activity concentrates around IP-rich acoustic engineering assets, while strategic partnerships with Microsoft Teams and Zoom accelerate platform validation timelines.
Within the heritage engineering tier, Sennheiser Electronic and Beyerdynamic exemplify European precision positioning through broadcast and studio monitoring specialization. Shure Inc. anchors professional audio channel relationships through direct distribution to touring and installed-sound contractors. Logitech International occupies the mass-market platform tier, competing across corporate rollouts with unified communications certifications.
| Leading Market Players |
|---|
| Sennheiser Electronic |
| Shure Inc. |
| Logitech International |
| Beyerdynamic |
| Audio-Technica Corporation |
| HP Inc. (Poly) |
| Sony Corporation |
| SteelSeries |
| GN Store Nord (Jabra) |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet processing concentration in China anchors driver assembly cost structures and determines margin capture downstream at OEM and brand tiers. Neodymium price volatility feeds directly into premium headset tier pricing power, while contract manufacturers in Vietnam and India arbitrage labor costs against acoustic engineering scarcity.
Pricing Analysis
United States enterprise procurement commands 40-60% premiums over Southeast Asian bulk orders for identical SKUs. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-certified tiers from corporate unified communications bundles and call center volume contracts. Cost compression in the mid-tier intensifies because Bluetooth LE Audio module commoditization erodes hardware differentiation. Call center operators exhibit highest price sensitivity; broadcast and studio monitoring buyers show least.
Supply Chain Analysis
Export control regimes on RF semiconductor components limit Bluetooth and DECT chipset flows to approved vendor lists, constraining module sourcing flexibility. Manufacturing concentrates in China, Vietnam, and India for final assembly, with driver magnets and MEMS microphones sourced from Chinese rare earth and semiconductor foundries. Single-source vulnerability runs through neodymium magnet supply. Distribution runs through managed service providers for enterprise estates and direct professional audio channels for precision tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around Microsoft Teams and Zoom certification becoming table stakes, with Bluetooth LE Audio interoperability determining hardware replacement cycle capture.
For Market Incumbents: Entrench unified communications certification velocity as the primary defensive moat against Chinese OEMs accelerating Teams and Zoom validation timelines. Secure captive neodymium magnet supply through backward integration into rare earth processing partnerships. DECT spectrum reallocation in Europe threatens installed-base service revenue; migrate enterprise accounts to Bluetooth LE Audio platforms preemptively. For New Entrants and Emerging Players: Build out AI-enhanced noise suppression firmware as a software-defined differentiation layer above commodity hardware. India PLI scheme subsidies offer the most penetrable geography for acoustic testing and final assembly capacity. Pursue hardware-as-a-service bundling with managed service providers to bypass direct channel establishment costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed unified communications peripherals platforms seeking acoustic engineering IP bolt-ons. Five-to-ten-year viability hinges on Bluetooth LE Audio multi-stream feature ownership and enterprise fleet management software integration. Target acquisition archetype: anechoic chamber-calibrated driver tuning specialists with broadcast channel relationships. Signal to watch: OSHA output limiting mandates triggering mandated enterprise refresh waves.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth LE Audio Platform Migration | Multi-stream broadcast features differentiate enterprise peripherals from DECT legacy estates. |
| Neodymium Supply Backward Integration | Captive magnet processing insulates driver assembly from Chinese rare earth volatility. |
| Unified Communications Certification Investment | Microsoft Teams and Zoom validation timelines determine enterprise procurement eligibility. |
| AI Noise Suppression Firmware Development | On-device neural processing converges with beamforming arrays for broadcast-tier democratization. |
| Hardware-as-a-Service Model Launch | Managed service provider bundles concentrate in United States healthcare and financial services verticals. |
Methodological Framework
Cross-validation between primary fieldwork and secondary regulatory filings anchors the qualitative findings in observable procurement patterns. Conversations with enterprise IT procurement officers, call center operations managers, professional audio channel distributors, and acoustic engineering directors inform demand-side dynamics. Secondary sources include FCC equipment authorization databases, CE marking notifications under EU Radio Equipment Directive, and customs trade records for neodymium magnet and headset HS codes. Bottom-up shipment estimates triangulate against top-down enterprise IT spending allocations.
Calibration against historical replacement cycle data and announced manufacturing capacity expansions validates projection assumptions across the modeling period. Segmentation dimensions include connectivity protocol, acoustic architecture, end-user deployment context, and geographic regulatory cluster. CAGRs derive from weighted average of protocol migration timelines and enterprise refresh cycle compression. Industry-specific inputs incorporate DECT spectrum reallocation probability assessments and OSHA hearing conservation rulemaking trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese OEMs accelerating certification timelines would shift outcomes. Material shifts in FCC Part 15 emission tolerance enforcement or EU DECT band reallocation decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Earphones Market
Consumer Electronics
Europe Soundbar Market
Consumer Electronics
Ereader Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Tablet Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Earbuds Market