
 Mobile Cases and Covers Market | 2026-2036
Mobile Cases and Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Cases and Covers Market Foresight
Buyer concentration among smartphone OEM bundling programs is hardening as Samsung Electronics and Apple-certified partners lock in volume commitments. Otter Products leverages its military-grade testing protocols to sustain premium positioning in North American retail channels. Spigen Inc. competes through rapid SKU turnover aligned with quarterly device release cadences from major handset manufacturers.
Mobile cases and covers are protective enclosures fabricated from thermoplastic polyurethane, polycarbonate, silicone, or leather composites, engineered to absorb impact energy and resist abrasion during device handling. Injection molding and thermoforming dominate mass production, with secondary processes adding textured grips, antimicrobial coatings, or integrated MagSafe-compatible magnetic arrays. Soft shell and TPU configurations lead volume production due to lower tooling costs and broader compatibility across device generations, while folio and wallet variants command higher unit margins by integrating card storage and screen protection. The eco-friendly feature segment is gaining structural traction as retailers impose sustainable sourcing requirements on accessories assortments.
The European Chemicals Agency enforces REACH substance restrictions that limit certain plasticizers in consumer goods, compelling reformulation of conventional TPU blends. The Bureau of Indian Standards operates mandatory certification for electronic accessories sold through domestic channels, creating compliance gates for imported inventory. China's State Administration for Market Regulation monitors product safety claims under GB standards for consumer protection. Stakeholders must weigh certification investments against the margin compression from commodity-grade competition in unregulated channels.
Market Dynamics
Smartphone refresh cycles among Gen Z and millennial consumers are compressing accessory replacement timelines, while REACH substance restrictions in the European Union are forcing wholesale reformulation of conventional TPU blends toward bio-based polymer alternatives.
Growth Catalysts
- India PLI Scheme:Domestic smartphone assembly under India's Production Linked Incentive scheme is expanding the addressable base for locally sourced protective accessories, pulling manufacturing investment toward Gujarat and Tamil Nadu industrial corridors.
- REACH Phthalate Restrictions:ECHA enforcement of plasticizer limits in consumer goods is accelerating adoption of TPU and bio-based polymer formulations that command premium shelf positioning in EU retail channels.
- MagSafe Ecosystem Expansion:Magnetic array integration in protective enclosures is automating accessory attachment workflows and creating recurring revenue streams through modular add-on sales.
Market Restraints
- Petrochemical Input Volatility:Crude oil price fluctuations directly compress margins on polycarbonate and TPU raw materials, exposing commodity-grade manufacturers to working capital stress.
- China Supply Concentration:Injection molding capacity clusters in Guangdong and Zhejiang provinces create geographic risk concentration for brands dependent on single-source OEM relationships.
- Biodegradation Performance Gap:Bio-based polymer alternatives currently exhibit inferior impact absorption and UV resistance versus conventional TPU, limiting application in ruggedized product tiers.
Strategic Opportunities
- Rural India Penetration:Tier-3 and Tier-4 cities in Maharashtra and Uttar Pradesh remain underpenetrated for branded protective accessories as smartphone ownership spreads beyond metropolitan centers.
- Antimicrobial Coating Convergence:Silver-ion and copper-oxide surface treatments are merging with standard TPU formulations to capture healthcare and institutional procurement contracts.
- Direct-to-Consumer Channel Innovation:Subscription-based accessory replacement programs are bypassing traditional electronics retail and capturing recurring revenue from device upgrade cycles.
Industry Challenges
- BIS Certification Timelines:India's Bureau of Indian Standards mandatory testing protocols for electronic accessories create 8-12 week inventory hold periods that strain import-dependent supply chains.
- SKU Proliferation Management:Quarterly device release cadences from handset manufacturers force case producers to amortize tooling investments across shrinking production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Cases and Covers Market |
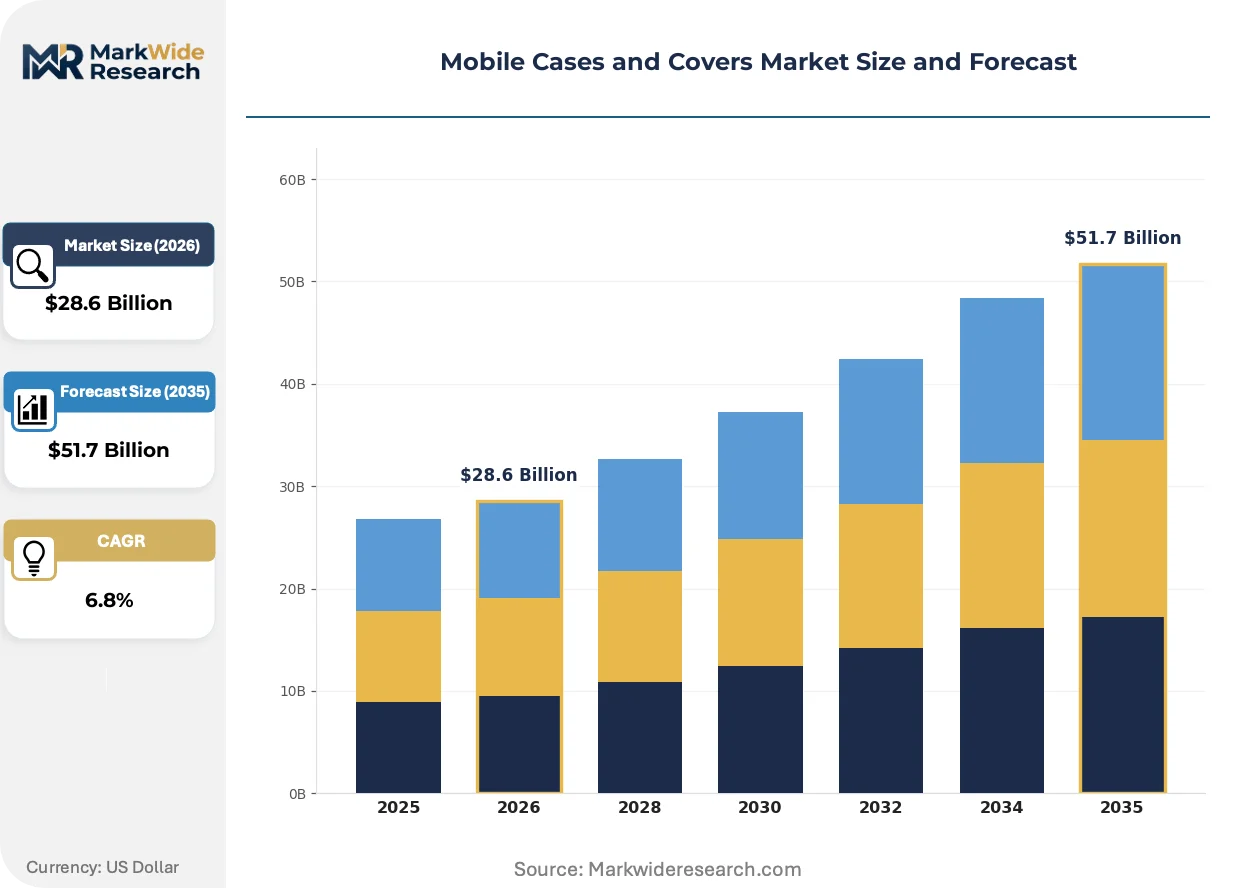
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Shell, Soft Shell, Folio, Wallet Material: Silicone, Leather, Polycarbonate, TPU Feature: Water Resistant, Shockproof, Magnetic Closure, Eco-Friendly End User: Individuals, Corporates, Retailers, Accessories Resellers |
| Companies Covered | Otter Products, Spigen Inc., Belkin International, Case-Mate, Incipio Technologies, Samsung Electronics, ZAGG Inc., Pelican Products, Tech21, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Cases and Covers Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry constraints are converging to reshape protective accessory design priorities, with sustainability credentials and automated manufacturing compatibility emerging as decisive competitive differentiators.
AI-driven generative design software is automating mold cavity optimization for impact dispersion patterns, reducing prototype iteration cycles from weeks to days. Mid-tier case manufacturers in Shenzhen and Dongguan are adopting these tools to match military-grade testing performance without premium R&D overhead. The technology is automating structural engineering decisions previously reserved for specialist firms.
ECHA's REACH substance restrictions on phthalate plasticizers are compelling TPU compounders to validate alternative formulations through SVHC screening protocols. European distributors are now requiring full material disclosure documentation as a condition of shelf access. Soft-shell product categories face the steepest compliance cost escalation as legacy formulations lose market authorization.
Gen Z consumers are treating protective accessories as fashion rotation items rather than durable goods, purchasing multiple cases per device cycle to match seasonal aesthetics. Fast-fashion retail channels in Seoul and Tokyo are responding with 4-6 week design-to-shelf timelines that outpace traditional electronics merchandising. This behavioral shift is fragmenting volume concentration away from carrier bundling programs toward direct social commerce transactions.
Mobile Cases and Covers Market Segmentation
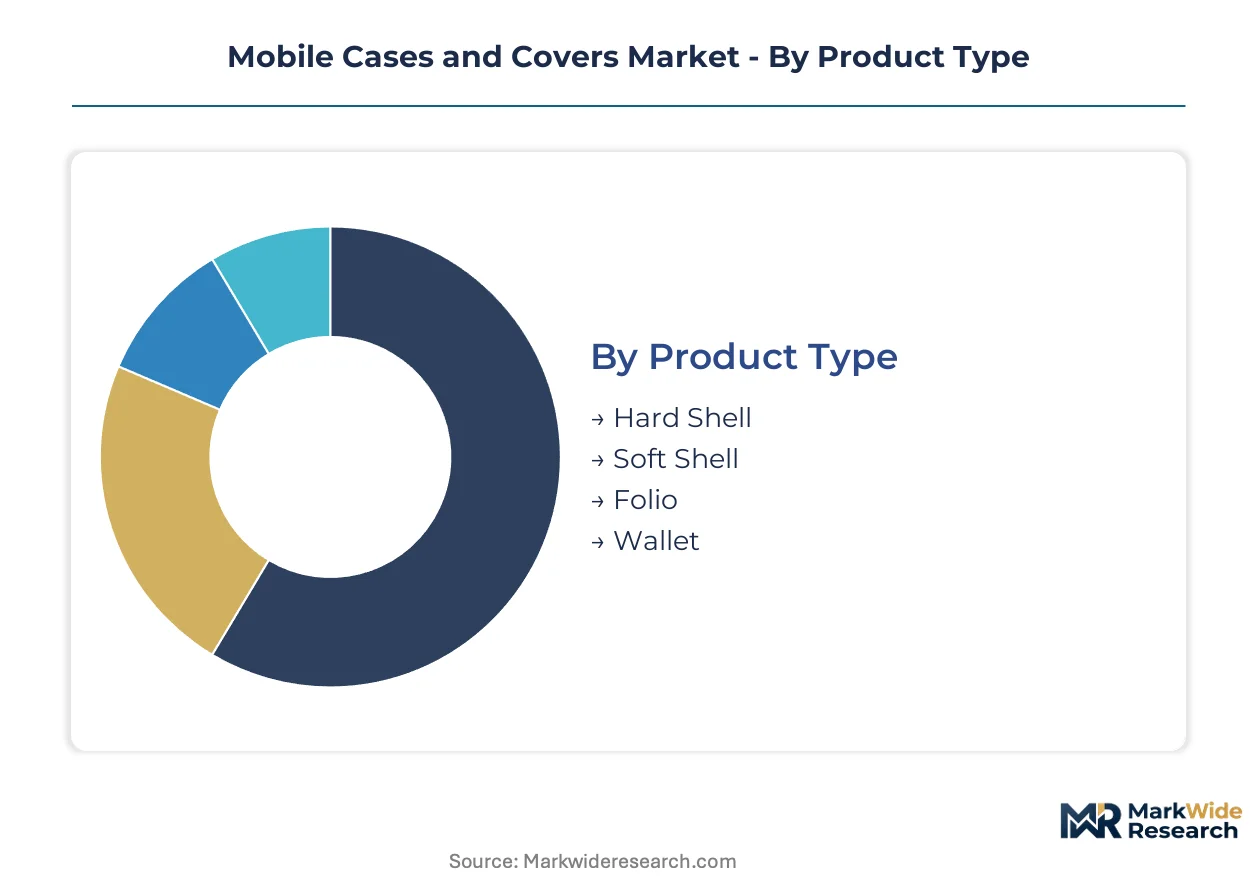
Protective accessory manufacturers must align tooling investments with segment-specific margin profiles and certification requirements. The market fragments across four structural dimensions that determine pricing power and channel access.
Product Type:
Capital intensity varies sharply across molding technologies, with multi-cavity hard-shell tooling requiring the heaviest upfront commitment.
- Hard Shell:Polycarbonate injection molding demands steel tooling with 500,000+ shot durability. Demand clusters in North American carrier bundling programs where military-grade drop certification commands shelf placement. Samsung Electronics and Apple-certified partners specify this construction for premium device launches.
- Soft Shell:TPU formulations extrude through lower-cost aluminum molds with faster changeover cycles. India's PLI scheme is pulling domestic assembly toward Gujarat industrial corridors where soft-shell production scales most efficiently. REACH phthalate restrictions in the European Union are forcing compound reformulation that elevates unit costs.
- Folio:Leather composite lamination and hinge integration require manual assembly stations. European distributors favor folio constructions for their higher retail margins and material disclosure compliance advantages.
- Wallet:Card slot integration adds secondary processing steps that constrain throughput. Japanese fast-fashion channels in Tokyo are driving 4-6 week design cycles for seasonal wallet variants.
Most installed capacity flows through Soft Shell. Expansion is steepest in Hard Shell.
Material:
Raw material selection determines regulatory compliance pathways and end-market access permissions.
- Silicone:Platinum-cured formulations deliver medical-grade biocompatibility for healthcare procurement contracts. Antimicrobial silver-ion surface treatments are converging with silicone substrates to capture institutional orders from hospital systems.
- Leather:Vegetable-tanned hides satisfy EU Green Deal sourcing requirements for sustainable retail assortments. Italian tanneries near Milan supply premium grades for folio constructions targeting fashion rotation behavior among Gen Z consumers.
- Polycarbonate:Optical clarity and rigidity suit transparent hard-shell designs. Guangdong injection molding clusters dominate polycarbonate capacity, creating geographic concentration risk for brands without dual-source relationships.
- TPU:Shore hardness tuning enables gradient protection from bumper rails to full enclosures. Bio-based polymer alternatives are gaining traction despite inferior UV resistance versus petroleum-derived grades.
TPU commands the broadest application footprint. Bio-based variants are climbing the fastest.
Feature:
Functional differentiation determines pricing tier placement and retail channel sorting.
- Water Resistant:IP-rated sealing adds gasket integration costs that push units toward outdoor and industrial end-uses.
- Shockproof:Multi-layer impact dispersion engineering targets military-specification testing protocols. Otter Products maintains premium positioning through proprietary drop-test validation.
- Magnetic Closure:MagSafe-compatible magnetic arrays automate accessory attachment and enable modular add-on revenue streams. Apple's ecosystem expansion is standardizing magnetic specifications across third-party suppliers.
- Eco-Friendly:Recycled ocean plastic and biodegradable polymer claims require third-party certification documentation. European retailers are imposing sustainable sourcing requirements as a condition of shelf access.
Shockproof features anchor the premium tier. Eco-Friendly claims are gaining share fastest.
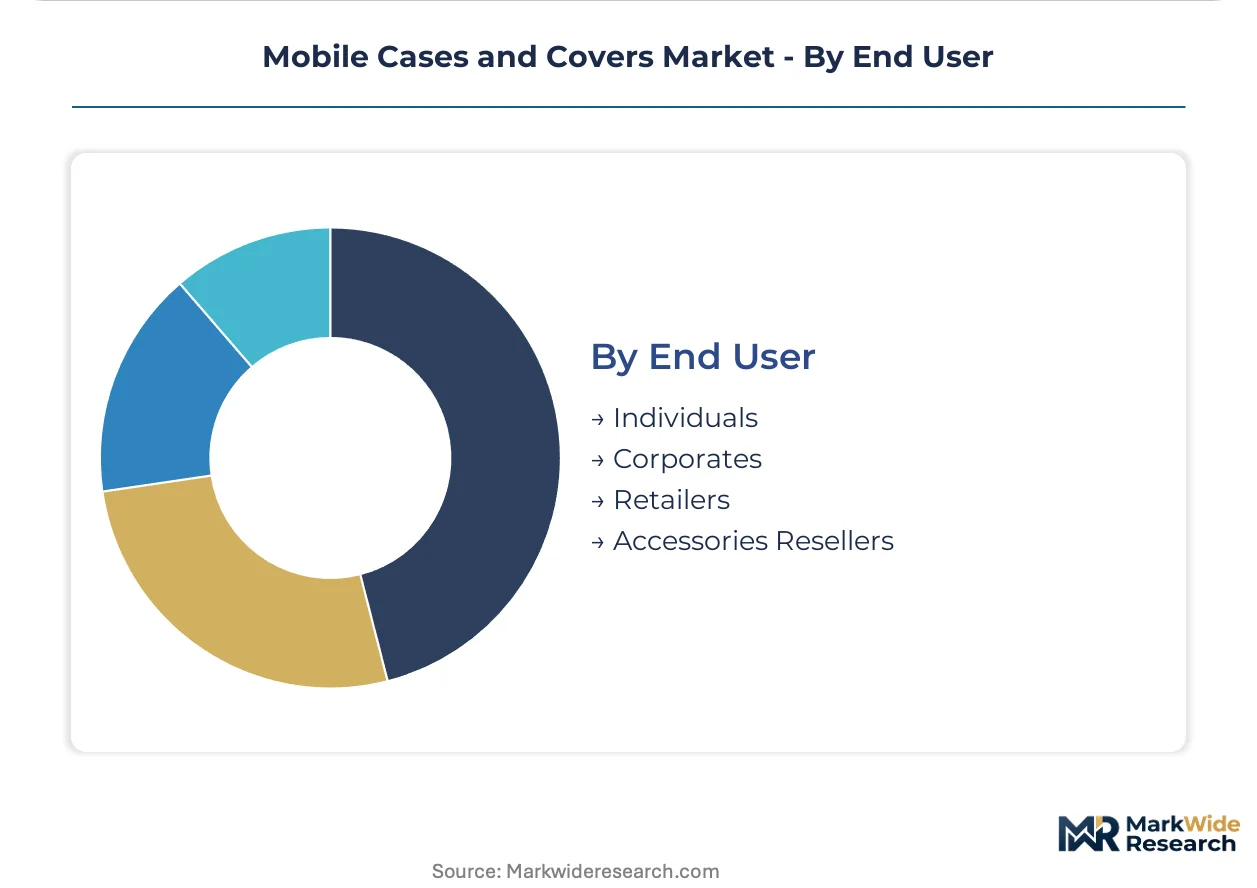
End User:
Procurement patterns diverge sharply between volume-driven institutional buyers and fragmented consumer channels.
- Individuals:Direct-to-consumer subscription programs are capturing recurring replacement revenue from device upgrade cycles. Social commerce transactions in Seoul and Tokyo are fragmenting volume away from traditional electronics retail.
- Corporates:Bulk procurement contracts specify antimicrobial coatings and standardized device fleet protection. Healthcare and financial services verticals drive specification rigor.
- Retailers:Electronics chains and carrier stores demand exclusive SKUs and guaranteed margin structures. BIS certification timelines create 8-12 week inventory holds that strain import-dependent supply chains.
- Accessories Resellers:Gray-market distributors in unregulated channels compete on price without certification overhead, compressing margins for compliant manufacturers.
Retailers concentrate the highest transaction volumes. Direct-to-consumer channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injection molding technicians and polymer compounders concentrate in Guangdong province, Shenzhen's hardware engineering talent pools, and Tamil Nadu's emerging electronics manufacturing corridors.
United States
Carrier bundling programs at Verizon and AT&T drive volume commitments for military-grade drop-certified enclosures. FCC equipment authorization requirements govern electromagnetic compatibility for MagSafe-integrated accessories. Injection molding capacity clusters in Ohio and Texas serve North American retail distribution.
China
Shenzhen and Dongguan hardware ecosystems enable 4-6 week design-to-shelf cycles for fast-fashion case variants. SAMR enforces GB standards for consumer product safety claims and magnetic array specifications. Zhejiang province thermoforming facilities supply polycarbonate shells for global brands.
Germany
ECHA REACH substance restrictions on phthalate plasticizers force TPU compound reformulation for EU market access. Premium automotive leather suppliers in Baden-Württemberg pivot into device folio constructions. Hamburg distributors demand full material disclosure documentation for shelf placement.
India
Domestic smartphone assembly under the PLI scheme expands demand for locally sourced protective accessories in Maharashtra and Tamil Nadu. BIS mandatory certification creates 8-12 week inventory holds for imported products. Gujarat industrial corridors attract soft-shell TPU production investment.
Japan
Tokyo and Osaka fast-fashion channels drive seasonal aesthetic rotation with compressed design cycles. METI oversees product safety standards for electronic accessories with magnetic components. Kanto region retail networks fragment volume toward direct social commerce transactions.
Mobile Cases and Covers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Samsung Electronics leverages device OEM bundling to lock in volume commitments, while accessory specialists pursue rapid SKU turnover aligned with quarterly handset releases. Three archetypes dominate: military-grade testing specialists, fast-fashion design houses, and contract manufacturers serving private-label programs. Strategic moves concentrate on dual-source supply relationships and antimicrobial coating convergence for healthcare procurement.
Within the premium-tier testing specialists, Otter Products and Pelican Products occupy positions defined by proprietary drop-test validation protocols. Spigen Inc. and Incipio Technologies exemplify rapid design-to-shelf specialists aligned with device release cadences. ZAGG Inc. anchors the screen protection convergence archetype. Belkin International and Case-Mate sit within the retail-channel-focused tier pursuing carrier bundling relationships. Tech21 represents material science differentiation through impact dispersion engineering.
| Leading Market Players |
|---|
| Otter Products |
| Spigen Inc. |
| Belkin International |
| Case-Mate |
| Incipio Technologies |
| Samsung Electronics |
| ZAGG Inc. |
| Pelican Products |
| Tech21 |
| Others |
Supply & Pricing Matrix
Carrier bundling programs at Verizon and AT&T anchor pricing power for military-grade drop-certified enclosures, while unbundled direct-to-consumer channels compete on rapid SKU turnover and seasonal aesthetics. This bifurcation concentrates margin capture in OEM-certified supply relationships while fragmenting price realization across social commerce transactions.
Pricing Analysis
Bundled carrier programs command fixed-margin structures with volume guarantees, whereas unbundled direct-to-consumer sales employ dynamic pricing tied to device release cadences. Price differentiation rests on certification tier and brand positioning, with military-grade testing protocols sustaining premium positioning against commodity-grade alternatives. Cost compression in soft-shell TPU tiers is intensifying due to REACH reformulation expenses and petrochemical input volatility. Gray-market resellers exhibit highest price sensitivity, while healthcare and corporate procurement verticals prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through dedicated production lines in Guangdong and Zhejiang provinces. Raw material flows draw from polycarbonate and TPU compounders clustered in Shenzhen, leather tanneries near Milan, and bio-based polymer developers in Germany. Geographic concentration in China's injection molding corridors creates single-source vulnerability for brands without dual-source relationships. Distribution runs through carrier bundling programs, electronics retail chains, and emerging subscription-based direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Gen Z consumers shift protective accessory purchasing toward fashion-rotation behavior with premium material specifications. Military-grade testing credentials and sustainable sourcing documentation increasingly sort winners from commodity-grade competitors.
For Market Incumbents: Deepen backward integration into TPU compounding capacity to hedge REACH reformulation costs and secure bio-based polymer supply. Fortify dual-source manufacturing relationships across Gujarat and Tamil Nadu industrial corridors to mitigate BIS certification timeline risks. Prioritize antimicrobial coating convergence to capture healthcare procurement contracts before specification standards harden.
For New Entrants and Emerging Players: Social commerce platforms in Tokyo and Seoul offer the most penetrable route for fast-fashion case variants with compressed design-to-shelf cycles. Target Tier-3 and Tier-4 Indian cities where smartphone ownership spreads ahead of branded accessory penetration. Deploy subscription-based replacement programs to bypass traditional electronics retail margin structures.
For Investors and Strategic Acquirers: Device OEMs and carrier bundling partners are the most active acquirers in this space, seeking captive accessory revenue streams. Focus on material science specialists with validated bio-based polymer formulations and established ECHA compliance pathways. Monitor BIS certification backlog durations as an inflection indicator for import-dependent supply chain stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Polymer Transition | ECHA REACH enforcement is compelling TPU reformulation for EU shelf access. |
| Dual-source Manufacturing Expansion | Gujarat and Tamil Nadu corridors reduce geographic concentration risk in China. |
| Antimicrobial Coating Integration | Silver-ion surface treatments capture healthcare procurement contract specifications. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models align with Gen Z device upgrade cycle behavior. |
| MagSafe Ecosystem Certification | Apple's magnetic array standardization enables modular add-on revenue streams. |
Research Methodology
Multiple input streams — case manufacturer executives, polymer compounder technical directors, electronics retail category buyers, and BIS certification consultants — were reconciled against trade customs data, SEC filings from listed accessory brands, and ECHA SVHC screening documentation. Primary fieldwork with injection molding operators in Shenzhen and Dongguan informed capacity utilization assumptions. Secondary validation drew from carrier bundling program disclosures and PLI scheme production statistics. Bottom-up SKU-level modeling and top-down category sizing were cross-referenced for triangulation.
Historical shipment patterns were cross-referenced against panel input from procurement leads at major handset OEMs to construct the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material formulation, feature integration, and end-user procurement channel. CAGRs were derived from curve-fitting approaches applied to replacement cycle data and smartphone ownership penetration curves. Forecast inputs incorporated REACH regulatory timeline assumptions and PLI scheme capacity buildout schedules.
The model assumes a particular technology adoption path for bio-based polymers; alternative pathways with faster performance parity achievement would alter the outlook. Forecasts reflect assumptions regarding BIS certification processing efficiency and petrochemical price stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Ereader Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Advanced Baby Monitors Market