
 Earphones Market | 2026-2036
Earphones Market Size, Share, and Industry Trends Forecast 2026-2036
Earphones Market Analysis
Gamers and remote professionals is bifurcating the earphones market away from casual listeners. Apple Inc. leverages its proprietary silicon and ecosystem lock-in to command premium positioning. Samsung Electronics anchors its strategy through Galaxy device bundling and cross-category integration. Sony Corporation differentiates via studio-grade drivers and cinematic spatial audio calibration.
Earphones are electroacoustic transducers designed to convert electrical audio signals into sound waves, typically employing dynamic drivers with neodymium magnets or balanced armature arrays for precise frequency response. Their primary purpose is personal sound reproduction across communication, entertainment, and professional monitoring applications. Wireless earbuds lead volume shipments while active noise cancellation commands the highest margin pools. Bone conduction technology is gaining fastest among outdoor athletes and hearing-impaired users seeking open-ear alternatives.
FCC certification governs RF emissions for wireless earphones sold in the United States, while CE marking and RoHS compliance govern European market access and material restrictions. India's BIS mandatory registration scheme now requires safety testing for imported Bluetooth audio devices, tightening entry barriers for unbranded imports. Stakeholders must monitor regulatory divergence around battery safety standards and right-to-repair mandates as these frameworks reshape design costs and product lifecycle obligations.
Market Dynamics
Bluetooth LE Audio and the LC3 codec are restructuring earphone architectures by enabling broadcast audio and Auracast deployments, compressing legacy codec licensing costs while opening new assisted-hearing and public venue applications.
Growth Catalysts
- Remote workforce audio hardware refresh:Enterprises in the United States and Germany are standardizing UC-certified wireless earbuds for hybrid employees, driving fleet procurement volumes.
- India's PLI scheme for electronics manufacturing:Production-linked incentives for mobile phone and component assembly are pulling Bluetooth audio supply chains into Tamil Nadu and Karnataka.
- CE marking for hearing aids convergence:The EU MDR framework is expanding to cover hearing-assistive earphones, creating regulatory clarity for medical-grade consumer crossover products.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing for dynamic driver magnets remains concentrated in China's Inner Mongolia and Jiangxi provinces, exposing cost volatility.
- BIS mandatory registration timeline:India's safety testing requirements for imported Bluetooth devices extend product launch cycles by 8-14 weeks for unregistered brands.
- Bone conduction frequency response limits:Open-ear transducers sacrifice sub-bass reproduction below 250Hz, constraining adoption among bass-forward music listeners.
Strategic Opportunities
- Auracast broadcast deployment in transit hubs:Airports in Denmark and the Netherlands are piloting LE Audio public address systems, creating installed-base demand for compatible receivers.
- Gaming-optimized low-latency stacks:Sub-40ms audio pipelines combining proprietary codecs with 2.4GHz dongles are penetrating esports tournaments and streaming setups.
- Right-to-repair battery accessibility:France's repairability index mandates and pending EU battery passport rules are incentivizing modular driver and cell designs for aftermarket servicing.
Industry Challenges
- RF coexistence engineering talent scarcity:Bluetooth/Wi-Fi antenna isolation expertise is concentrated among semiconductor vendors, forcing OEMs into costly reference design dependencies.
- FCC Part 15 certification backlog:Wireless earphone RF emissions testing queues at accredited labs are extending time-to-market for new SKUs by 6-10 weeks.
- Spatial audio calibration fragmentation:Proprietary head-related transfer function databases across Apple, Sony, and Samsung ecosystems force developers into multi-platform mastering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earphones Market |
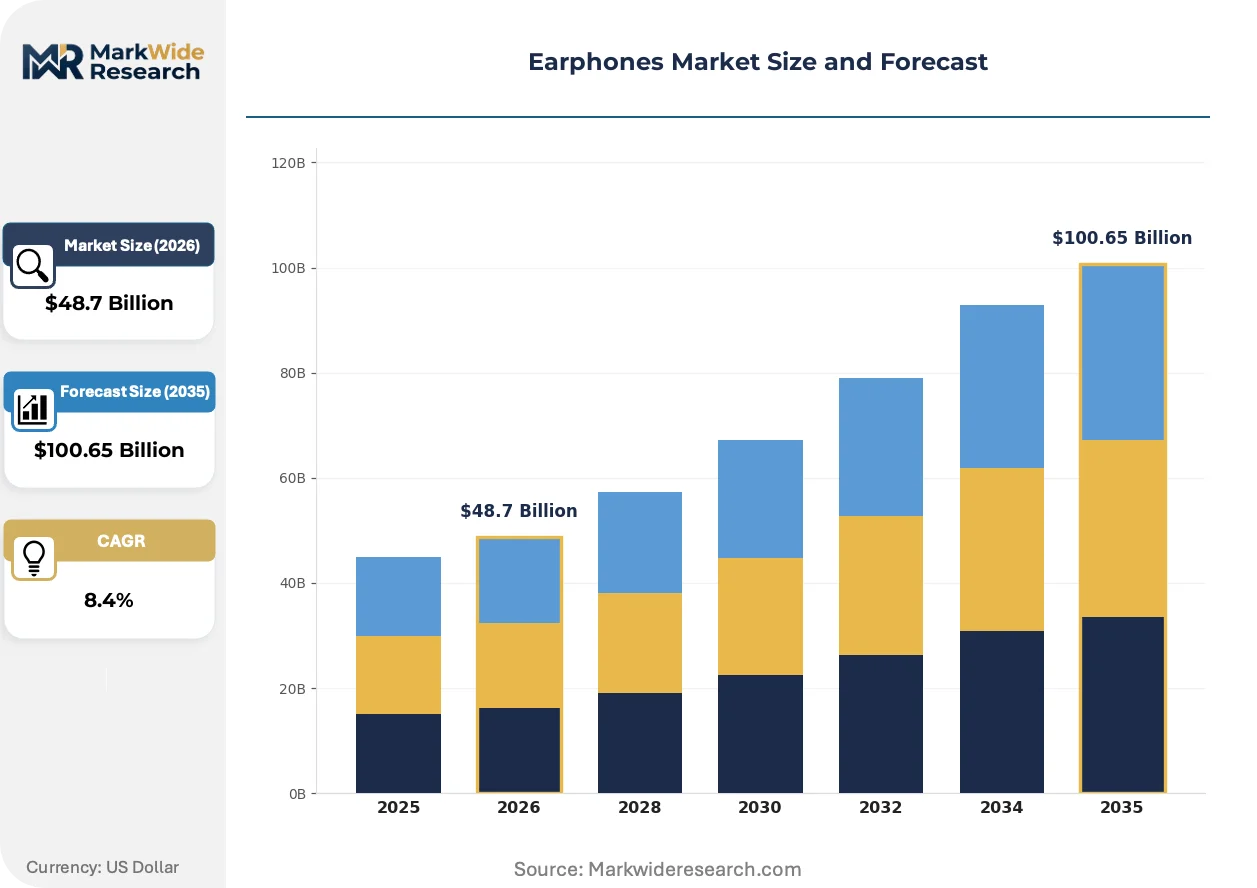
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ear, On-Ear, Over-Ear, Wireless Technology: Active Noise Cancellation, Bluetooth, Wired, Bone Conduction End User: Professional Musicians, Audiophiles, Casual Users, Gamers Form Factor: Earbuds, Headphones, Neckband, True Wireless |
| Companies Covered | Apple Inc., Samsung Electronics, Sony Corporation, Bose Corporation, Harman International, Sennheiser electronic GmbH & Co. KG, Skullcandy Inc., JVC Kenwood Corporation, Logitech International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earphones Market Emerging Trajectories
Codec standardization and broadcast audio capabilities are converging to reshape how earphones connect to devices and environments, compressing proprietary lock-in while enabling new assistive and public-use cases.
LC3 and LC3plus codecs are supplanting SBC and AAC as default wireless transmission standards in Android and Windows ecosystems. Hearing aid manufacturers and mobile OEMs are co-developing Auracast-compatible firmware stacks ahead of public venue rollouts. This codec transition is compressing Qualcomm and Apple proprietary audio licensing revenues while democratizing low-latency, high-efficiency transmission across tier-two chipset vendors.
France's repairability index and the EU's forthcoming battery passport regulation are mandating disassembly scores and cell traceability for wireless audio products sold in member states. Manufacturers must redesign glue-free housings and standardize cell connectors to achieve index thresholds above 6.0. Premium tier brands with direct-to-consumer channels are responding fastest, integrating modular battery trays and publishing repair manuals before mandatory deadlines.
Enterprise procurement of unified communications-certified earphones is displacing consumer retail as the dominant volume channel for mid-tier wireless SKUs. IT departments in the United States and United Kingdom are consolidating vendor contracts around Teams and Zoom certification programs, bundling hardware refresh cycles with software licensing renewals. This shift is most visible in financial services and professional services verticals where security-compliant audio endpoints are becoming standard issue for hybrid employees.
Earphones Market Segmentation
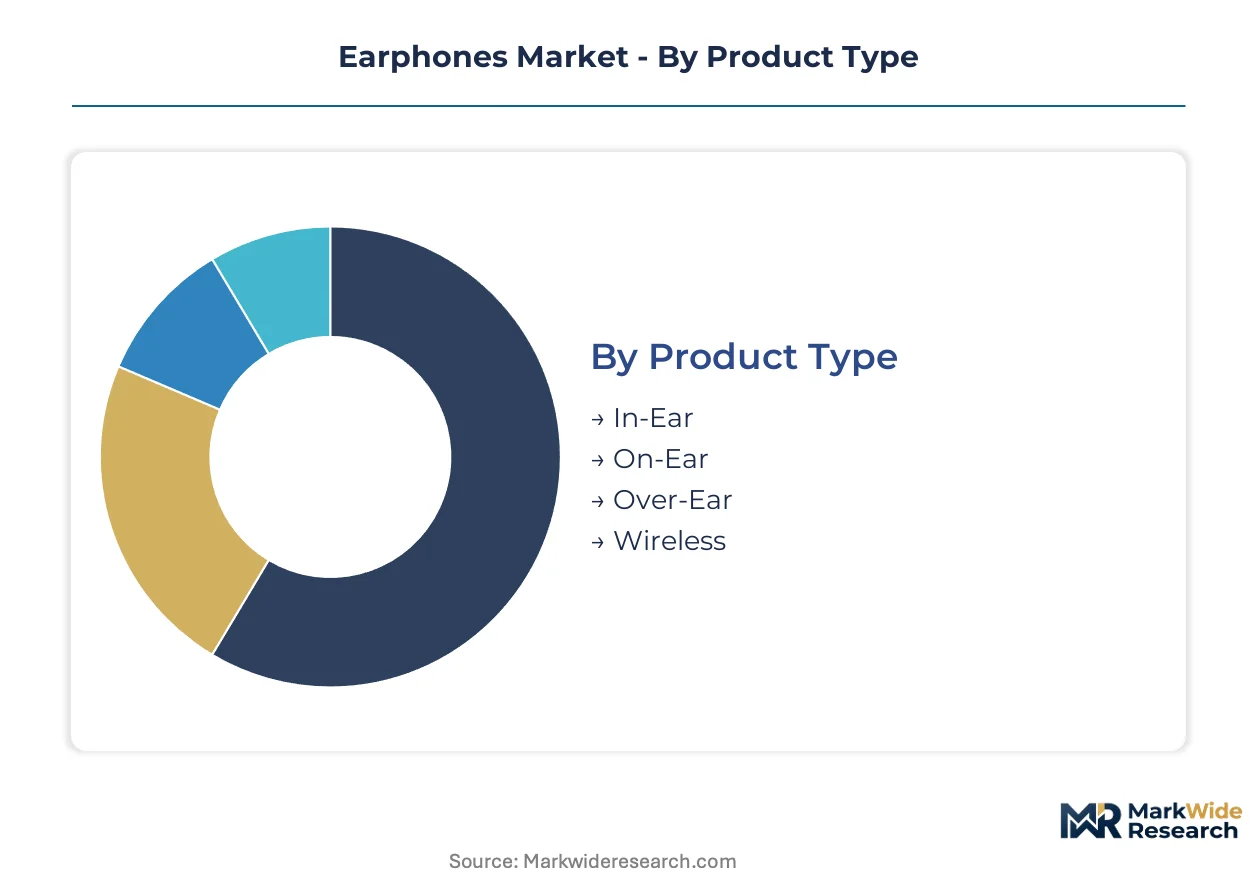
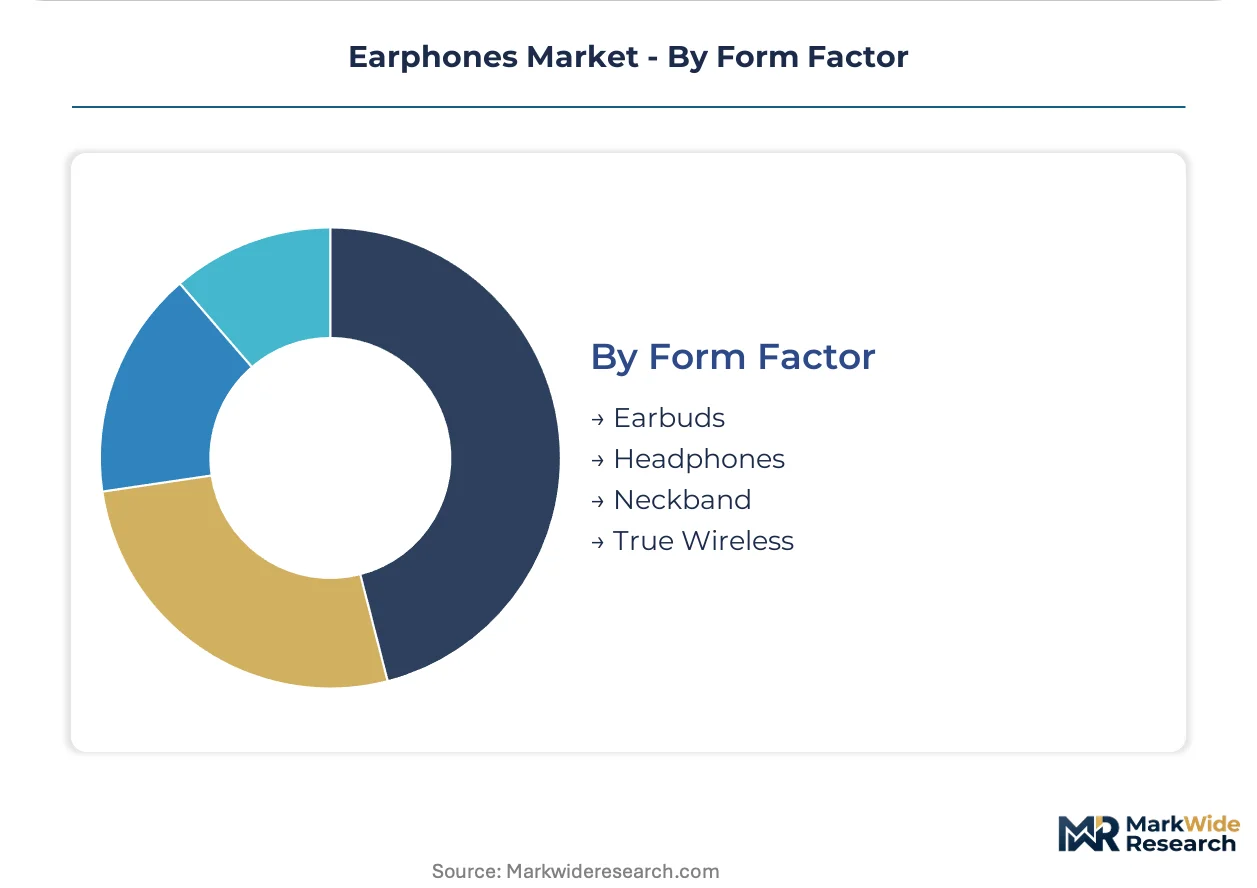
Earphone manufacturers calibrate R&D allocation across four intersecting taxonomies. Product type and technology choices determine margin capture, while end-user targeting and form factor selection govern channel strategy and inventory velocity.
Product Type:
Over-ear configurations command the highest margin pools within this category due to driver array complexity and spatial audio calibration requirements.
- In-Ear:Dynamic drivers with neodymium magnets or balanced armature arrays deliver precise frequency response in compact housings. Demand concentrates among commuters in India and China seeking portability combined with passive isolation from urban noise environments.
- Over-Ear:Circumaural designs accommodate larger planar magnetic or electrostatic driver configurations for extended frequency reproduction. Professional monitoring applications in Germany and Japan drive premium procurement, with spatial audio calibration for cinematic workflows adding service revenue attachment.
- On-Ear:Supra-aural pads balance portability against acoustic isolation, typically employing 40mm dynamic drivers. Fitness enthusiasts and office workers favor this middle-ground format.
- Wireless:Radio frequency transmission architectures eliminate cable tethering while introducing battery, antenna, and codec integration challenges. Bluetooth LE Audio adoption is expanding broadcast audio capabilities beyond paired-device limitations.
Over-ear holds installed capacity. Wireless is rotating up the share rankings.
Technology:
Active noise cancellation generates supernormal returns through proprietary algorithm licensing and microphone array integration complexity.
- Active Noise Cancellation:Feedforward and feedback microphone arrays generate anti-phase waveforms for environmental sound suppression. Hybrid ANC implementations in premium tiers now achieve 40dB+ attenuation, with enterprise procurement in the United States standardizing UC-certified variants for open-plan office deployments.
- Bluetooth:Radio frequency protocols from 2.4GHz ISM band transmission enable untethered mobility. LC3 codec adoption across Android and Windows ecosystems is compressing legacy AAC and SBC licensing costs while extending battery endurance.
- Wired:Analog or digital tethered connections eliminate latency and battery dependency. Audiophile communities in Japan and South Korea sustain demand for balanced 2.5mm and 4.4mm termination standards.
- Bone Conduction:Transducers vibrate temporal bone to bypass eardrum transmission, maintaining situational awareness. Outdoor athletes and hearing-impaired users in Australia and the United Kingdom adopt this open-ear alternative despite sub-bass reproduction constraints below 250Hz.
Bluetooth dominates unit economics. Bone conduction is climbing the fastest.
End User:
Gamers generate the steepest expansion trajectory through low-latency audio stack requirements and tournament sponsorship visibility.
- Gamers:Sub-40ms audio pipelines combining proprietary codecs with 2.4GHz dongles penetrate esports tournaments and streaming setups. China and South Korea host the densest competitive gaming populations, driving refresh cycles for spatial audio positioning accuracy.
- Professional Musicians:Flat frequency response and minimal harmonic distortion specifications govern studio monitoring and live in-ear monitor applications. Nashville and London recording clusters sustain demand for custom-molded universal fit variants.
- Audiophiles:High-resolution audio certification and lossless codec support justify premium pricing. Enthusiast communities in Germany and Japan drive limited-edition collaborations with driver manufacturers.
- Casual Users:General consumption of music, podcasts, and communication applications dominates volume shipments. Price sensitivity in India and Indonesia channels demand toward unbranded or white-label imports.
Casual users anchor volume scale. Gamers are gaining share fastest.
Form Factor:
True wireless configurations concentrate manufacturing investment due to charging case integration and miniaturization engineering intensity.
- True Wireless:Completely cable-free bilateral earbuds with independent RF chains and synchronized playback. Apple and Samsung ecosystem lock-in sustains premium pricing, while Indian domestic manufacturers capture economy tiers through PLI scheme incentives.
- Earbuds:Wired or wireless in-ear designs with cable connection between housings. Fitness applications favor sweat-resistant IP ratings and wingtip stabilization.
- Neckband:Cable connection between housings rests on collarbone, consolidating battery and controls in a central module. Motorcycle commuters in Vietnam and Thailand prefer this secure fit format.
- Headphones:Over-ear or on-ear headband-mounted designs distribute clamping force across cranial structure. Long-haul aviation and contact center deployments sustain demand for replaceable earpad and headband padding architectures.
Headphones retain legacy infrastructure. True wireless is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing for neodymium driver magnets clusters in China's Inner Mongolia and Jiangxi provinces, creating cost volatility that ripples through assembly operations in Vietnam and India. Component fabrication and final assembly distribute across four demand centers where regulatory frameworks and manufacturing incentives reshape competitive positioning.
China
Domestic brands capture economy-tier volumes through Shenzhen and Dongguan manufacturing clusters while BYD Electronics and Luxshare Precision expand component supply to Apple and Samsung. MIIT enforces GB standards for Bluetooth RF emissions and battery safety certification. The Yangtze River Delta and Pearl River Delta concentrate 70% of global driver magnet processing capacity.
United States
Enterprise procurement of UC-certified wireless earbuds for hybrid workforces drives fleet volumes through IT departments in financial services and professional services verticals. FCC Part 15 certification governs RF emissions testing with accredited lab queues extending time-to-market by 6-10 weeks. Austin and Seattle host dense concentrations of audio engineering talent for spatial audio calibration.
India
PLI scheme incentives for mobile phone and component assembly pull Bluetooth audio supply chains into Tamil Nadu and Karnataka manufacturing zones. BIS mandatory registration now requires 8-14 week safety testing cycles for imported devices. Domestic manufacturers capture true wireless economy tiers through Bengaluru and Chennai assembly operations.
Germany
Professional monitoring applications in recording studios and broadcast facilities sustain premium over-ear procurement with spatial audio calibration service attachments. CE marking and RoHS compliance govern European market access with ECHA monitoring substance restrictions. Berlin and Hamburg anchor audiophile retail distribution and custom-molded in-ear monitor fitting services.
Japan
High-resolution audio certification and lossless codec support justify premium pricing through enthusiast communities and limited-edition driver collaborations. METI oversees radio equipment certification under Radio Law requirements. Tokyo and Osaka metropolitan areas concentrate specialty audio retail and studio monitoring equipment distribution.
Earphones Market Vendor Landscape
Concentration sits with ecosystem-integrated technology conglomerates and audio-specialized component suppliers. The vendor base stratifies across three tiers: proprietary silicon owners commanding premium positioning, device bundlers capturing mid-market scale, and specialist driver manufacturers serving professional monitoring niches. Strategic moves center on reference design licensing partnerships and modular battery architecture standardization for repairability compliance.
Within the ecosystem-integrated tier, Apple Inc. and Samsung Electronics exemplify platform lock-in strategies through proprietary silicon and cross-device integration. Sony Corporation occupies a position bridging consumer and professional audio archetypes. Sennheiser electronic GmbH & Co. KG represents the specialist engineering heritage segment. Bose Corporation and Harman International anchor the acoustic research and automotive audio extension vectors respectively.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Sony Corporation |
| Bose Corporation |
| Harman International |
| Sennheiser electronic GmbH & Co. KG |
| Skullcandy Inc. |
| JVC Kenwood Corporation |
| Logitech International |
| Others |
Supply Flow & Price Mechanics
Driver magnet processing scale in China's Inner Mongolia and Jiangxi provinces compresses unit economics for dynamic driver arrays, concentrating cost leverage among vertically integrated OEMs while forcing tier-two brands toward white-label assembly in Vietnam and India.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ecosystem-locked flagships from UC-certified enterprise SKUs and unbranded imports. Price differentiation hinges on ANC algorithm licensing depth and BIS/FCC certification status. Cost compression in economy tiers intensifies because Indian domestic manufacturers exploit PLI scheme incentives. Casual users in Southeast Asia exhibit highest price sensitivity; audiophile communities in Germany and Japan show lowest elasticity.
Supply Chain Analysis
Inventory cycles for neodymium magnets and Bluetooth chipsets extend lead times when Inner Mongolia rare earth processing faces environmental compliance audits. Component sourcing draws from China for driver magnets, Vietnam for final assembly, and India for PLI-subsidized domestic production. Single-source vulnerability concentrates in rare earth processing. Distribution runs through Shenzhen component markets, Bengaluru contract manufacturers, and direct-to-consumer channels for premium tier brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The earphones market is exiting a component shortage cycle as Bluetooth LE Audio chipset supply normalizes and India's manufacturing capacity comes online, positioning volume recovery ahead of enterprise refresh cycles.
For Market Incumbents: Fortify reference design partnerships with MediaTek and Qualcomm to secure codec licensing leverage before LC3 standardization erodes proprietary lock-in. Expand captive magnet processing through joint ventures in Jiangxi to hedge rare earth price volatility. Deepen enterprise channel control through Teams and Zoom certification bundling.
For New Entrants and Emerging Players: After-sales battery replacement services represent an under-served layer where incumbents optimize for sealed-case obsolescence. Target India's BIS-registered domestic manufacturing tier through Tamil Nadu assembly partnerships. Pursue right-to-repair compliance as a go-to-market differentiator in France and pending EU markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise UC-certified vendors with IT department contract structures. Long-term viability favors specialist driver manufacturers with planar magnetic IP and medical-grade hearing aid crossover capability. Watch Auracast public venue deployment velocity as inflection indicator for LE Audio ecosystem maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| LC3 Codec Integration | Reduces licensing costs for Android OEMs while enabling broadcast audio applications. |
| PLI Scheme Manufacturing Localization | Pulls assembly capacity into Tamil Nadu and Karnataka for Indian domestic market access. |
| Right-to-Repair Modular Design | Positions premium brands ahead of France's repairability index mandates and EU battery passport rules. |
| Auracast Receiver Certification | Opens transit hub and assisted-hearing applications in Denmark and Netherlands pilot markets. |
| Enterprise UC Certification | Captures fleet procurement volumes from financial services IT departments in the United States. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the earphones value chain, including RF engineering leads at semiconductor vendors, procurement directors at contract manufacturers in Vietnam and India, audio calibration specialists in Germany and Japan, and enterprise IT hardware buyers in financial services. Primary interview insights were cross-referenced against secondary sources including FCC equipment authorization databases, BIS registration records, MIIT GB standard filings, and customs trade data for Bluetooth audio component flows. Bottom-up shipment modeling and top-down consumer electronics expenditure triangulation validated volume estimates.
Across the analysis window, the forecasting framework modeled unit shipments and value flows through product type, technology tier, end-user application, and geographic manufacturing cluster dimensions. CAGRs were derived from trend extrapolation of historical codec transition cycles and enterprise hardware refresh patterns. Key inputs included PLI scheme capacity buildout timelines, Auracast deployment roadmaps in European transit authorities, and rare earth processing capacity utilization in China's primary magnet production zones.
Forecasts assume regulatory continuity in FCC Part 15 certification, CE marking and RoHS compliance, and India's BIS mandatory registration scheme; material policy shifts would require re-modeling of time-to-market assumptions. Revision becomes warranted when Bluetooth LE Audio adoption rates in Android ecosystems cross thresholds that compress proprietary codec licensing revenues.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Education PC Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Tattoo Stencil Printer Market