
 Smart Audio Devices Market | 2026-2036
Smart Audio Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Audio Devices Market Intelligence
The use of recycled fabrics and advanced polymers in device casings is expanding the market's appeal to environmentally-conscious consumers, replacing conventional ABS plastics. Apple leverages its tightly integrated software and hardware ecosystem to promote its full range of audio products. Amazon dominates the entry-level smart speaker space through its Alexa platform, while Sonos differentiates with a focus on high-fidelity, multi-room audio experiences.
Smart audio devices are electronics engineered for audio playback and voice-based interaction with a digital virtual assistant. These products incorporate core components like microphone arrays, dedicated processors, and wireless transceivers for hands-free control. The smart speakers category represents a mature segment, while wireless earbuds represent the fastest-growing product type. Among end users, Households remain the largest adopter, with new applications emerging in Businesses for conferencing and background music.
Manufacturers must comply with electronic and wireless regulations, including FCC rules on radio frequency emissions in the United States and CE marking requirements in Europe. In China, adherence to GB standards for electronic safety and power consumption is mandatory for market access. Navigating the evolving landscape of data privacy and AI governance, such as the EU AI Act, will be a critical determinant of success for all vendors.
Market Dynamics
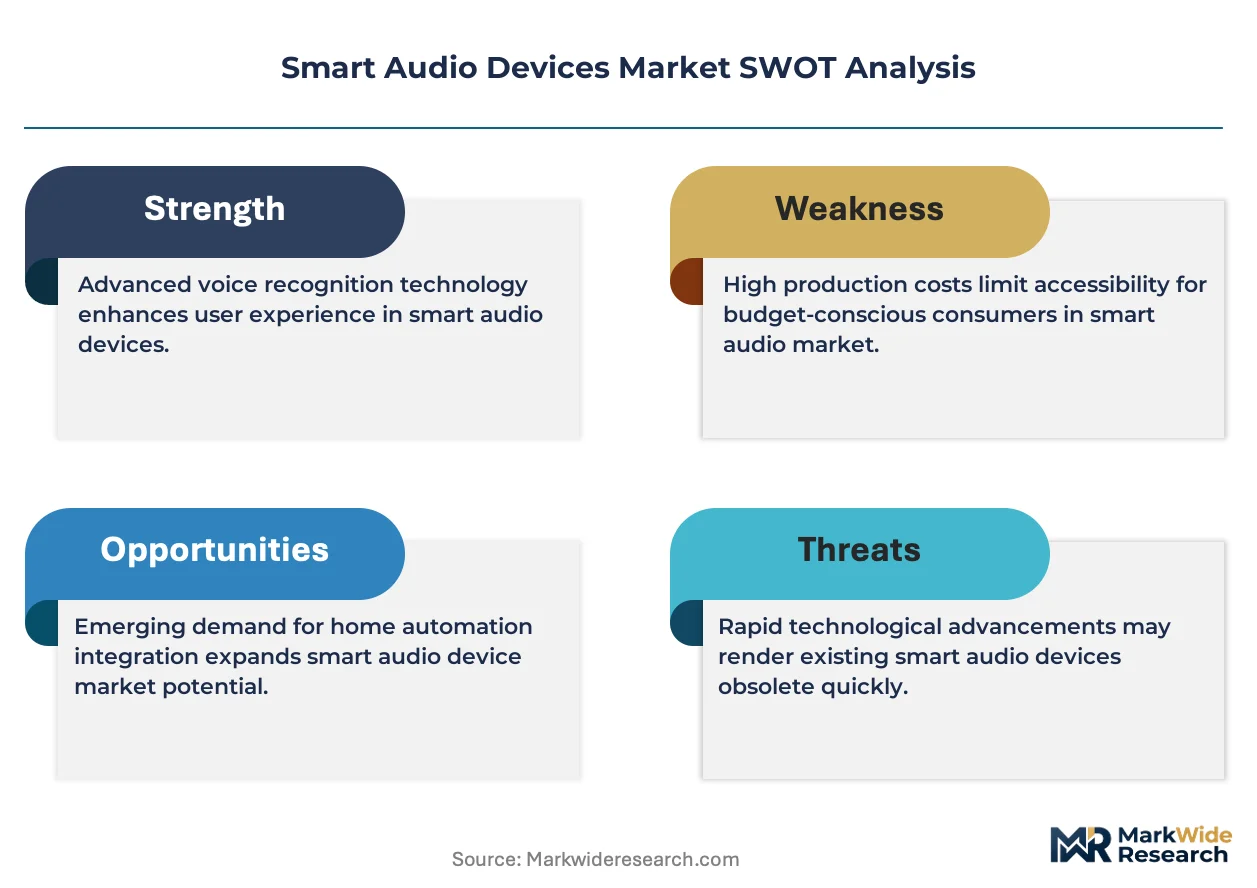
The market's evolution is defined by the conflict between stringent data privacy mandates, such as the EU AI Act, and the data-intensive requirements of sophisticated voice recognition AI. This tension directly influences processor selection and on-device processing capabilities.
Growth Catalysts
- Advanced Voice Recognition:Maturation of natural language processing algorithms and neural network processors improves user interaction and expands functionality, driving adoption in household and business environments.
- Smart Home Ecosystem Expansion:Consumer demand for integrated home automation in the United States and Europe positions smart audio devices as central control hubs for lighting, security, and entertainment systems.
- Sustainable Materials:The use of recycled fabrics and advanced polymers, replacing traditional ABS plastics, attracts environmentally-conscious consumer segments and aligns with circular economy principles.
Market Restraints
- Data Privacy Concerns:Consumer apprehension regarding passive listening and data collection by virtual assistants, amplified by regulations like GDPR, can slow adoption rates in sensitive user segments.
- Fragmented Ecosystems:A lack of interoperability between competing virtual assistant platforms creates vendor lock-in and complicates multi-brand smart home setups for end users.
- Processor Cost Volatility:Fluctuations in the price of specialized audio processors and high-performance microphone arrays create margin pressure for manufacturers, particularly in the entry-level segment.
Strategic Opportunities
- Enterprise Applications:Expanding use cases in corporate environments for smart conferencing systems and ambient audio in retail or hospitality settings presents a new revenue stream beyond the household segment.
- On-Device AI Processing:Developing devices with powerful edge AI capabilities that process voice commands locally reduces latency and addresses privacy concerns, creating a new premium product tier.
- Emerging Market Penetration:Adapting voice recognition models for diverse languages and dialects in high-growth markets like India and Brazil opens access to a large, untapped consumer base.
Industry Challenges
- Navigating AI Governance:Adhering to the evolving landscape of AI regulations, such as the EU AI Act, requires significant legal and R&D investment to ensure compliant algorithm development.
- Wireless Component Sourcing:Managing the supply chain for critical wireless transceivers and Bluetooth modules, subject to geopolitical trade friction, poses an operational risk for hardware manufacturers.
- Matter Protocol Integration:The complex process of integrating the Matter smart home standard across product lines creates development bottlenecks and can delay seamless interoperability for consumers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Audio Devices Market |
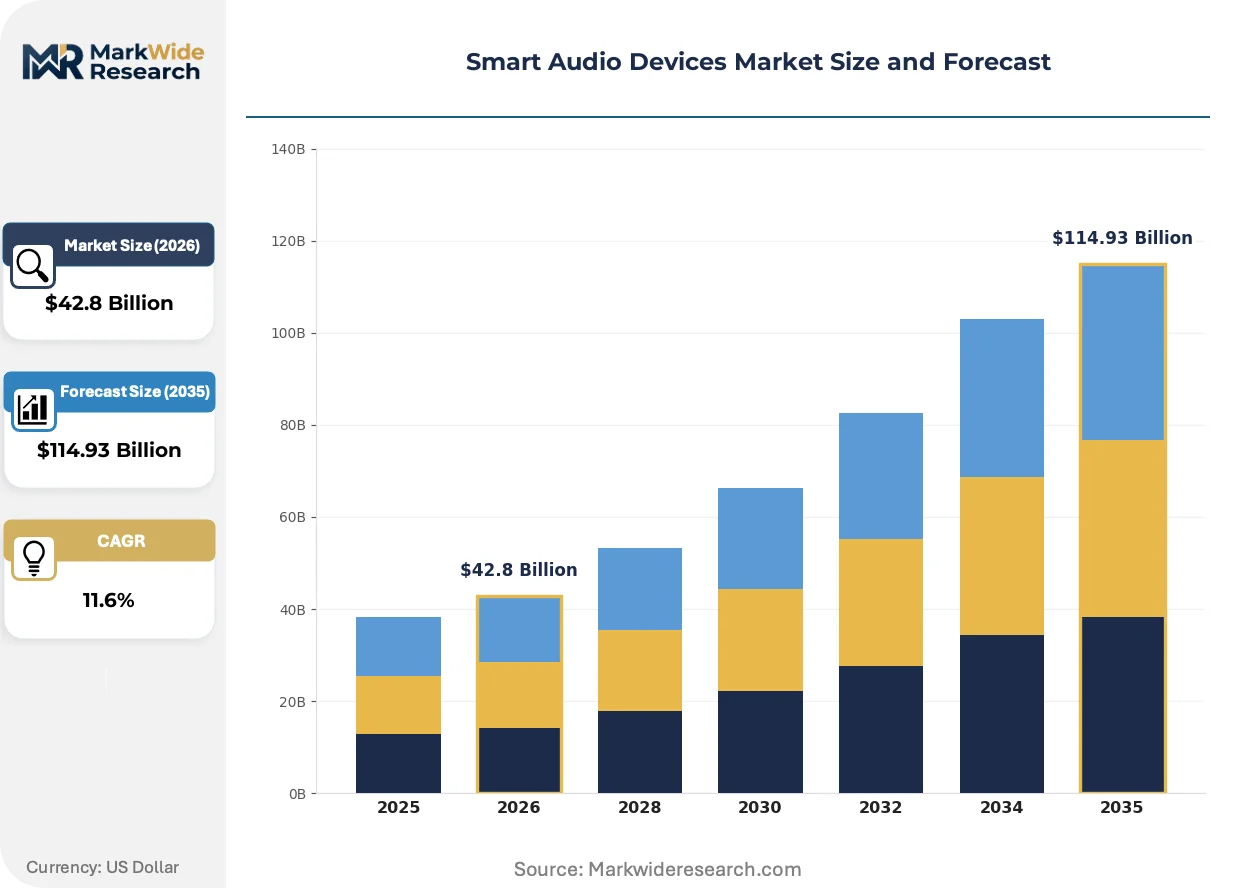
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $114.93 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
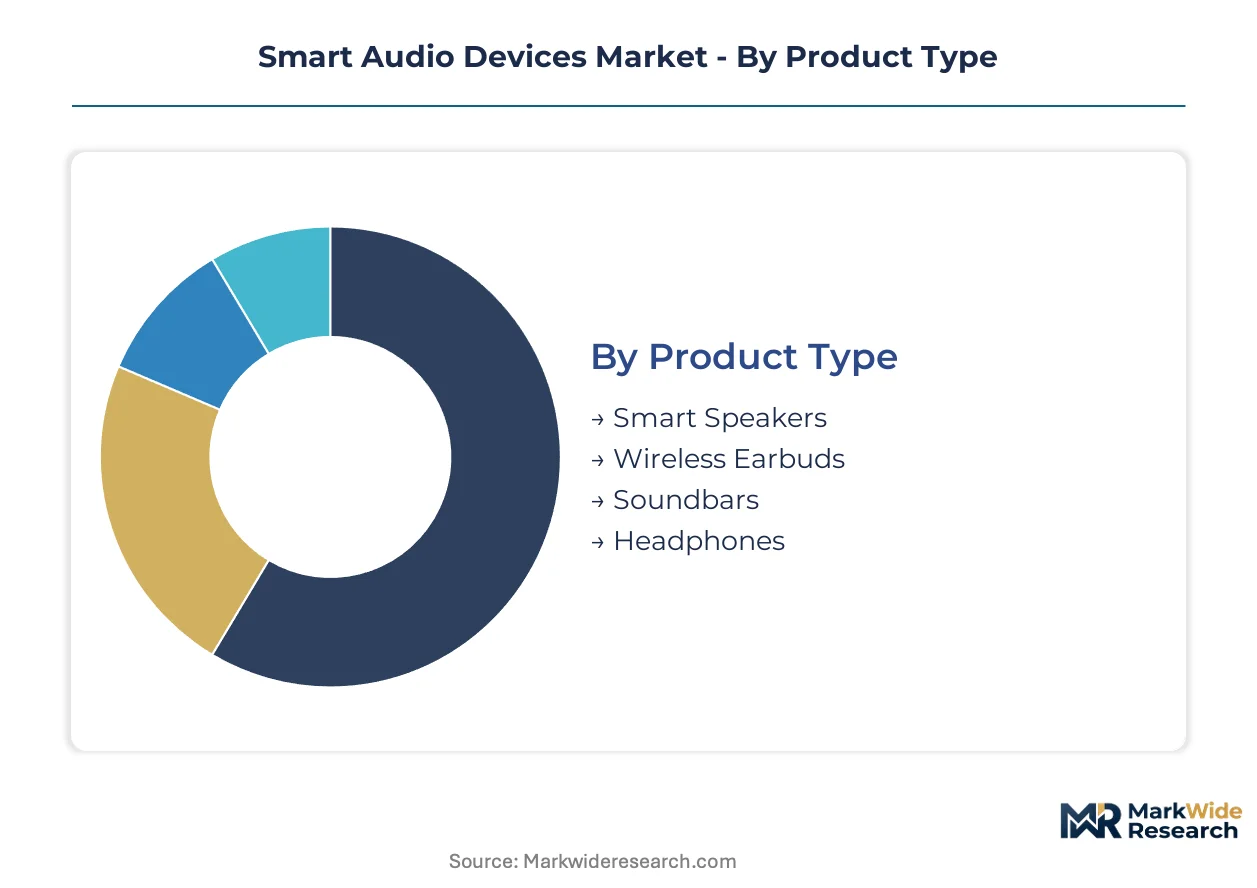
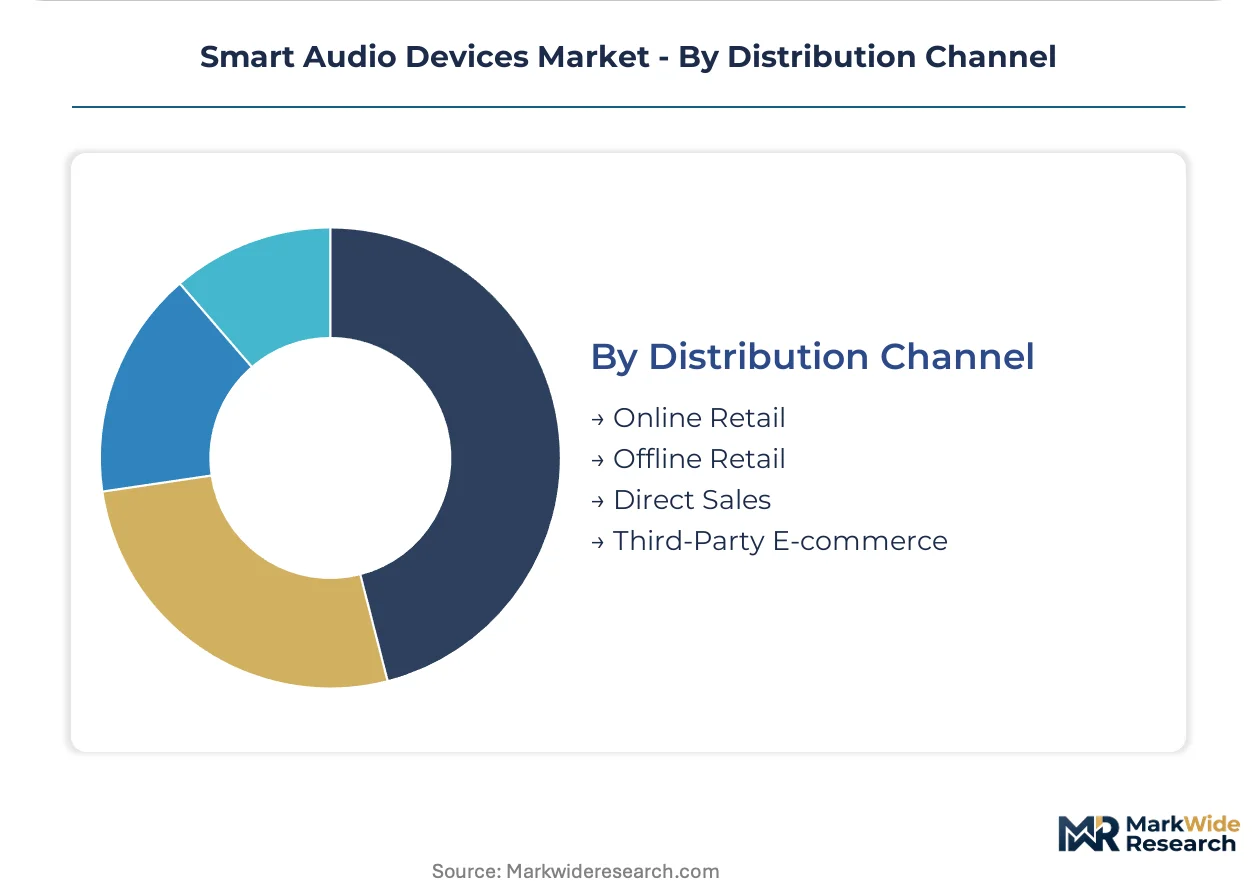
| Segmentation | Product Type: Smart Speakers, Wireless Earbuds, Soundbars, Headphones Technology: Voice Recognition, Bluetooth, Wi-Fi, NFC End User: Households, Businesses, Educational Institutions, Content Creators Distribution Channel: Online Retail, Offline Retail, Direct Sales, Third-Party E-commerce |
| Companies Covered | Apple, Sony, Amazon, Samsung, Anker, Sonos, Bose, Ultimate Ears, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Audio Devices Market Strategic Shifts & Innovations
A fundamental shift toward hyper-personalized and context-aware audio is underway, moving beyond simple command-and-response interactions. This evolution is driven by the convergence of sensor fusion, on-device AI, and new hardware form factors like wireless earbuds.
Edge AI processing, using dedicated neural processing units within the device itself, enables local analysis of voice commands. This technology is seeing rapid adoption in premium wireless earbuds and next-generation smart speakers to reduce reliance on cloud connectivity. The result is a system where control over user data and core assistant functionality is decentralizing from the cloud to the individual device.
The European Union's AI Act introduces a risk-based framework for artificial intelligence systems, classifying voice assistants used in smart audio devices. This regulation compels manufacturers to increase transparency in data usage and algorithm training, directly impacting software development cycles. Vendors targeting the European market are now re-architecting their platforms to comply with these new transparency and risk-mitigation requirements.
Consumer expectation is shifting toward audio devices functioning seamlessly across multiple environments, from home to car to personal use. This disrupts the single-device purchase model, favoring the acquisition of bundled product ecosystems that offer continuous audio experiences. This trend is most pronounced in mature markets like the United States, where brand loyalty is tied to software ecosystem stickiness.
Smart Audio Devices Market Segmentation
Understanding the distinct segments within the smart audio devices market illuminates specific opportunities and challenges for manufacturers. Each category of devices, technology, user, and distribution channel presents unique commercial dynamics and regulatory considerations. Strategic differentiation across these segments is critical for market success and sustained growth.
Product Type:
Smart audio device product types must adhere to various regional electronic and wireless certifications, including FCC rules in the United States and CE marking requirements in Europe.
- Wireless Earbuds:These compact, untethered audio devices integrate advanced sensors and edge AI for personalized sound and hands-free assistant access. Demand is concentrating in mobile consumer segments across North America and Asia-Pacific, driven by convenience and active lifestyle integration.
- Smart Speakers:These stationary devices serve as central hubs for smart home ecosystems, offering voice control over various connected appliances. Adoption is highest in United States households, where consumers prioritize integrated home automation and seamless digital assistant interaction.
- Soundbars:These elongated speaker systems enhance television audio and often include integrated smart assistant capabilities for home entertainment setups.
- Headphones:This category encompasses over-ear and on-ear smart audio solutions, offering high-fidelity sound and voice assistant integration for personal listening.
Smart Speakers sits at the top of the volume ranking, with Wireless Earbuds climbing the fastest.
Technology:
The underlying technologies enable distinct functionalities and user experiences across smart audio devices, influencing processing power and connectivity requirements.
- Voice Recognition:This core technology processes spoken commands and translates them into actionable instructions for the device, relying on sophisticated natural language processing algorithms. Demand for advanced voice recognition is concentrating in premium smart speakers and earbuds, driven by the need for seamless, low-latency user interaction.
- Wi-Fi:Providing high-bandwidth connectivity, Wi-Fi enables multi-room audio streaming, over-the-air updates, and robust integration within smart home networks. Its application is critical for devices acting as central control hubs, particularly in European and North American households.
- Bluetooth:This short-range wireless technology facilitates direct pairing with smartphones and other devices, offering widespread compatibility and energy efficiency for portable audio.
- NFC:Near Field Communication offers rapid, proximity-based pairing for smart audio devices, simplifying initial setup and secure connections for specific applications.
Voice Recognition technology commands premium pricing due to its advanced AI processing requirements, while Bluetooth offers cost-effective connectivity.
End User:
Different end-user segments exhibit varied purchasing behaviors and specific requirements for smart audio solutions, impacting product design and feature sets.
- Households:This segment represents the largest adopter, utilizing smart audio devices for entertainment, smart home control, and personal assistance in domestic environments. Demand is concentrated in developed markets like the United States and Germany, where smart home ecosystem penetration is high.
- Businesses:Enterprises are increasingly deploying smart audio solutions for conference room systems, ambient background music, and interactive customer service applications. Adoption is gaining traction in corporate offices and hospitality sectors across Europe, driven by efficiency and enhanced user experience.
- Educational Institutions:Schools and universities integrate smart audio devices for interactive learning, language instruction, and campus-wide communication systems.
- Content Creators:Professionals in media and entertainment utilize specialized smart audio devices for recording, mixing, and monitoring high-quality audio productions.
Household demand drives significant scale in smart audio device production, whereas Business applications require specialized supply chains for integration services.
Distribution Channel:
Distribution channels vary significantly in their operational costs and reach, influencing the final pricing of smart audio devices and consumer accessibility.
- Online Retail:This channel includes major e-commerce platforms and brand-specific web stores, offering broad product selection, competitive pricing, and direct-to-consumer convenience. Demand is concentrating in digitally-native consumer demographics across the United States and China, driven by convenience and extensive product reviews.
- Offline Retail:Comprising electronics stores, department stores, and specialized audio shops, this channel provides hands-on product demonstrations and immediate purchase options. It remains critical for consumers in Europe and Japan who prefer physical interaction before making purchase decisions.
- Direct Sales:Manufacturers sell directly to consumers or businesses through their own channels, enabling greater control over branding and customer relationships.
- Third-Party E-commerce:This channel involves sales through online marketplaces that host multiple vendors, expanding reach for smaller brands and niche products.
Online Retail represents a mature and efficient channel for consumer electronics, while Direct Sales is gaining traction for premium brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's technological innovation drives significant demand for smart audio devices, particularly for integration within smart home ecosystems. Regional adoption patterns reflect varying consumer preferences for voice assistants and connected living. Growth is propelled by expanding smart home integration and advanced voice recognition across diverse markets.
United States
The United States market demonstrates high consumer appetite for connected home automation, positioning smart audio devices as central control hubs. Manufacturers must comply with FCC rules on radio frequency emissions for market access. Seattle and Cupertino serve as key centers for R&D and platform development, influencing product innovation.
Germany
Germany demonstrates robust adoption of smart audio devices for integrated home automation and emerging business applications. Adherence to CE marking requirements and the EU AI Act is mandatory for vendors operating in this market. Berlin's vibrant tech scene fosters AI development, while Munich explores automotive integration for audio solutions.
China
China's vast consumer base, characterized by digitally-native demographics, fuels demand for smart audio devices. Compliance with GB standards for electronic safety and power consumption is crucial for market entry. Shenzhen remains a global hub for hardware manufacturing, and Beijing drives significant AI research for voice recognition technologies.
Japan
Japanese consumers prioritize high-fidelity audio experiences and personal listening devices, driving demand for premium smart audio products. Manufacturers must adhere to JIS standards for electronic products to ensure quality and safety. Tokyo serves as a major center for consumer electronics R&D, with Osaka contributing to audio component manufacturing.
India
India represents a high-growth market for smart audio devices, particularly with adaptation of voice recognition models for diverse languages. BIS standards for electronic goods provide a regulatory framework for product quality. Bengaluru's strong software development ecosystem supports AI localization efforts, and Chennai contributes to electronics assembly.
Smart Audio Devices Market Key Industry Players
Strategic partnerships dominate the current landscape, especially among technology providers seeking to expand their smart home ecosystems. The market exhibits a tiered structure, with a few dominant players alongside numerous niche specialists. This competitive environment is fragmented across product types and regional preferences, creating distinct competitive arenas. Companies engage in portfolio diversification and technology licensing to expand their reach and enhance device functionality.
Within the integrated ecosystem archetype, Apple and Amazon represent powerful forces. Apple, a California-based technology giant, exemplifies deep software-hardware integration across its audio product range. Amazon, a Seattle-headquartered e-commerce and cloud services firm, anchors the entry-level smart speaker segment through its Alexa platform. Sonos, a Santa Barbara-based audio specialist, occupies a premium position focusing on high-fidelity multi-room audio experiences for discerning consumers.
| Leading Market Players |
|---|
| Apple |
| Sony |
| Amazon |
| Samsung |
| Anker |
| Sonos |
| Bose |
| Ultimate Ears |
| Others |
Cost & Logistics Intelligence
Edge AI processing, enabling local voice command analysis, simultaneously reshapes cost economics by demanding specialized neural processing units and influences supply concentration towards regions capable of advanced chip manufacturing.
Pricing Analysis
Input-cost pass-through directly impacts consumer pricing in the smart audio device market. Pricing stratifies across premium, standard, and economy tiers, reflecting differing levels of advanced AI processing and brand premium. Processor cost volatility creates margin pressure, particularly in the entry-level segment, leading to pricing softness. Households, especially those seeking basic smart speaker functionality, remain the most price-sensitive consumer segment.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China, India, and Japan underpins the smart audio device supply chain. This chain draws from specialized processors and wireless transceivers as critical components. Geopolitical trade friction for wireless component sourcing represents a structural supply chain risk. Downstream distribution runs predominantly through multi-channel models, with online retail dominating consumer electronics sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, where the significant R&D investment required for EU AI Act compliance in Europe contrasts with less stringent regulatory environments elsewhere.
For Market Incumbents: Lock in existing customer bases through enhanced software-hardware integration across product ecosystems. Incumbents should strategically invest in R&D for compliant algorithm development to mitigate data privacy concerns and navigate evolving AI governance frameworks. Deepening software ecosystem stickiness helps defend against fragmented ecosystem threats. Prioritize investments in advanced voice recognition to maintain a premium competitive edge.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for new entrants specializing in privacy-by-design solutions. Target enterprise applications, such as smart conferencing systems and ambient audio for hospitality, which require specialized integration services. Focus on emerging markets like India and Brazil by adapting voice recognition models for diverse languages and dialects. Go-to-market strategies should emphasize on-device AI processing capabilities.
For Investors and Strategic Acquirers: Valuations sit cheapest among smaller firms specializing in specific components or niche software solutions for smart audio devices. The long-term viability of this market hinges on continued smart home integration and expanding enterprise adoption. Watch the adoption rate of the Matter protocol as a key inflection indicator for seamless interoperability across diverse platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch on-device AI earbuds | Addresses privacy concerns and reduces latency for premium users. |
| Integrate Matter protocol | Enhances interoperability across diverse smart home ecosystems. |
| Form strategic partnership for voice recognition localization | Unlocks high-growth markets like India and Brazil. |
| Acquire enterprise audio solutions specialist | Expands revenue streams beyond household consumer segments. |
| Diversify manufacturing footprint to Southeast Asia | Mitigates geopolitical supply chain risks for critical components. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform the Smart Audio Devices Market analysis. Primary research involved discussions with R&D directors, product managers, supply chain leads, and marketing executives. Secondary validation drew from regulatory filings such as FCC, CE, and GB standards, alongside industry reports and technology patent databases, employing both bottom-up and top-down triangulation.
The segment-weighting approach underpinned the forecast framework, modeling dimensions including product type, technology, end user, distribution channel, and regional regulatory adherence. Compound annual growth rates were derived from historical trends, market drivers, and expert projections. Key forecast inputs included advancements in voice recognition algorithms and the expanding penetration of smart home ecosystems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of geopolitical trade friction affecting component sourcing. These forecasts reflect assumptions regarding the evolving landscape of AI governance frameworks. Material deviation in regulatory triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Phones Market
Consumer Electronics
Ereader Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Smart Connected Speaker Market