
 Headphones Market | 2026-2036
Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Headphones Market Outlook
Subscription-based hardware leasing and asset-light financing models are reshaping how audio equipment reaches consumers, lowering upfront barriers for premium-tier purchases. Sony Corporation leverages its vertically integrated sensor and semiconductor divisions to sustain proprietary noise-canceling chipsets. Bose Corporation anchors its competitive position through direct-to-consumer channel control and acoustic R&D laboratories in the United States. Samsung Electronics competes by extending Galaxy ecosystem lock-in across its wireless earbud and headphone portfolios.
Headphones are electroacoustic transducers worn on or around the head that convert electrical audio signals into sound waves, typically specified by frequency response ranges, impedance ratings, and driver diameters that determine tonal accuracy and output power. Their primary commercial purpose spans personal entertainment, professional audio monitoring, gaming communication, and hearing protection in industrial environments. Over-ear and noise-canceling variants command the dominant share of value pools as audiophiles and frequent travelers prioritize isolation and soundstage depth. Wireless Bluetooth connectivity leads volume growth as codec improvements such as aptX Lossless and LC3 reduce the fidelity gap with wired alternatives.
The Federal Communications Commission governs radio frequency emissions for wireless headphone transmitters in the United States, while the CE marking framework and REACH substance restrictions shape product compliance across European markets. China's State Administration for Market Regulation enforces GB standards for electronic audio equipment safety and electromagnetic compatibility. Stakeholders must monitor evolving interoperability mandates and battery recycling directives that will determine which connectivity architectures and material choices secure long-term market access.
Market Dynamics
Bluetooth LE Audio and Auracast broadcast standards are fragmenting legacy wireless protocols while forcing chipset architecture redesigns across the entire supply base.
Growth Catalysts
- Esports Broadcasting Infrastructure:Professional tournament leagues in the United States and China mandate low-latency audio gear, pulling high-refresh-rate headphone SKUs into competitive gaming venues.
- REACH Substance Compliance:European chemical restrictions on hazardous materials are accelerating biobased plastic adoption in earcup housings and headband assemblies.
- LC3 Codec Deployment:Next-generation lossy compression algorithms are halving power consumption for wireless streams, extending battery life in active noise-canceling configurations.
Market Restraints
- Rare Earth Magnet Concentration:Neodymium driver magnet supply chains cluster in Chinese processing facilities, exposing manufacturers to export quota volatility.
- RF Spectrum Licensing Friction:FCC Part 15 rules on unlicensed 2.4 GHz emissions create certification bottlenecks for simultaneous multi-device pairing features.
- Smartphone Jack Elimination Backlash:USB-C audio adapter dongles retain a stubborn replacement market, slowing full wireless conversion among price-sensitive consumer segments.
Strategic Opportunities
- Auracast Public Venue Rollout:Hearing assistance mandates in German transit hubs and airports are creating certified installation demand for broadcast audio receivers.
- Industrial Hearing Protection Convergence:OSHA-compliant communication headsets are absorbing two-way radio and Bluetooth streaming into single units for construction and manufacturing floors.
- Subscription Hardware Financing:Asset-light leasing programs through direct-to-consumer channels are reducing upfront purchase barriers for premium over-ear models.
Industry Challenges
- Acoustic Engineering Talent Scarcity:DSP firmware development and psychoacoustic tuning expertise concentrates in a handful of semiconductor and audio R&D clusters.
- Multi-Protocol Certification Timelines:Simultaneous Bluetooth, LE Audio, and proprietary low-latency gaming mode qualifications extend product launch windows.
- Legacy Codec Interoperability:Maintaining backward compatibility with SBC and AAC while optimizing for LC3 and aptX Lossless fragments firmware validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Headphones Market |
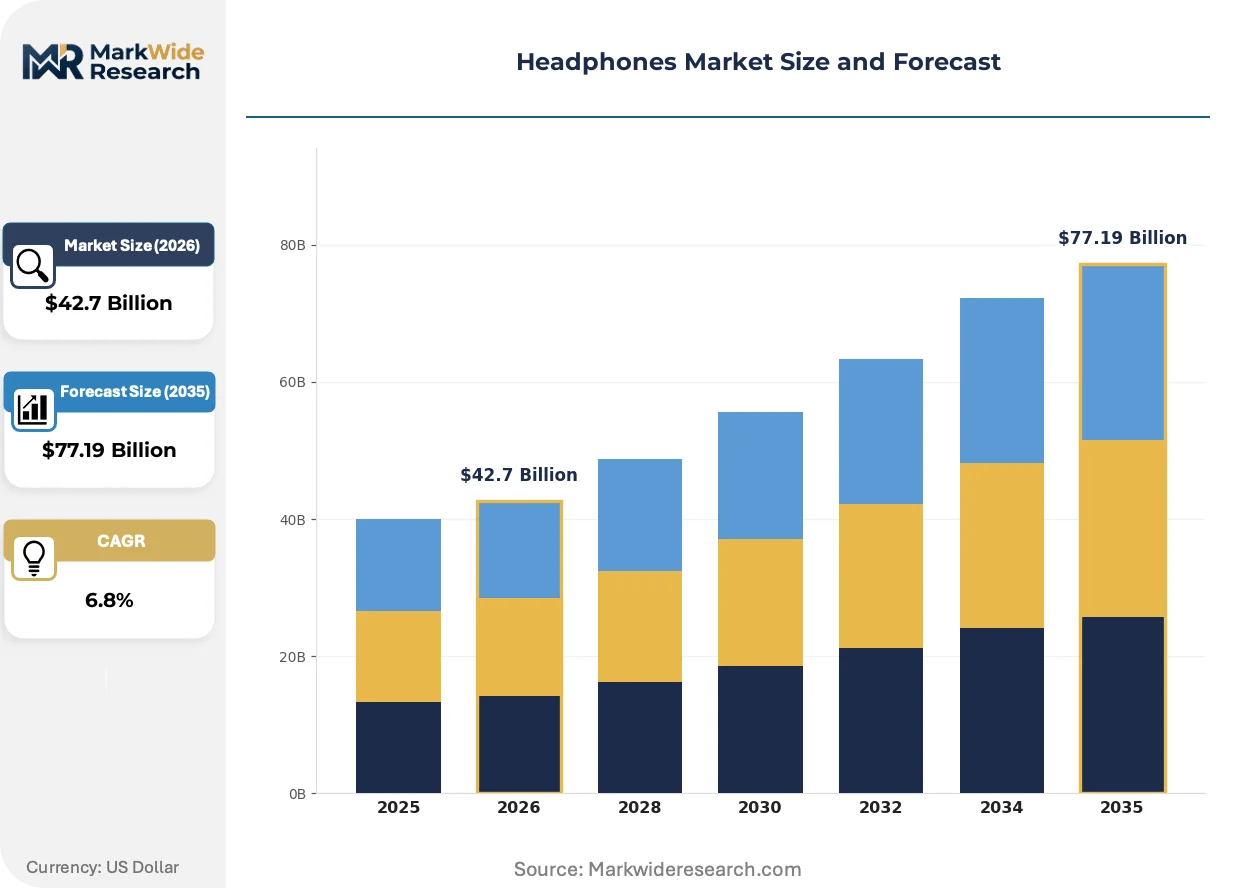
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ear, On-Ear, Over-Ear, Noise-Canceling Connectivity: Wired, Wireless, Bluetooth, NFC Target Audience: Professional Musicians, Gamers, Casual Users, Audiophiles Price Range: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Apple Inc., Sony Corporation, Samsung Electronics, Bose Corporation, Sennheiser Electronic GmbH & Co. KG, Skullcandy Inc., Harman International, JVC Kenwood Corporation, Audio-Technica Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Headphones Market Strategic Shifts
Auracast broadcast architecture and on-device machine learning are compressing traditional hardware differentiation while opening entirely new audio distribution channels.
Spatial audio rendering with head-tracking sensors is hybridizing cinematic soundstage reproduction into gaming and music consumption. Audiophile enthusiasts and immersive entertainment platforms are adopting six-degrees-of-freedom tracking at accelerating rates. This convergence is collapsing the boundary between professional monitoring equipment and consumer entertainment gear.
REACH substance restrictions and impending EU battery recycling directives are forcing material disclosure and end-of-life collection infrastructure investments. Manufacturers must redesign acoustic damping foams and lithium-polymer cell housings to satisfy extended producer responsibility frameworks. Premium over-ear and true wireless categories face the steepest compliance cost escalations.
Enterprise procurement of communication headsets is consolidating through IT department-managed device programs rather than individual employee purchases. Unified communications platforms and hybrid work policies are displacing consumer retail channels for knowledge-worker segments. This shift concentrates most visibly in United States and German corporate technology refresh cycles.
Headphones Market Segmentation
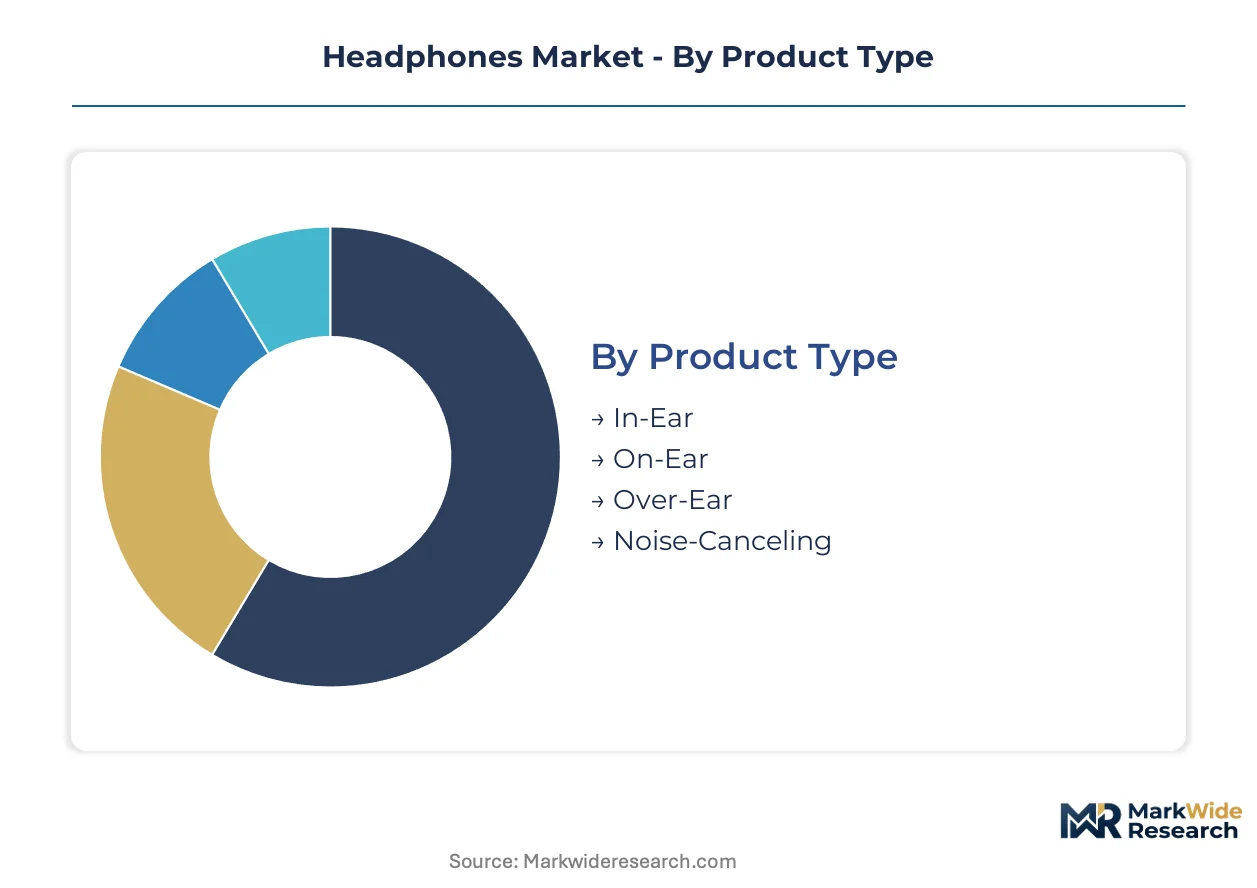
Headphone manufacturers align product architectures with distinct acoustic requirements, connectivity standards, and price elasticity profiles. Each segmentation dimension reveals divergent margin structures and supply chain configurations that shape competitive positioning.
Product Type:
Cost tier differentiation separates mass-market disposable units from precision-engineered monitoring equipment.
- Over-Ear:Large driver enclosures (40-50mm) deliver extended bass response and soundstage depth. Professional studios in Germany and the United States specify these for critical mixing applications where isolation determines output quality.
- Noise-Canceling:Hybrid feedforward-feedback microphone arrays process ambient sound through dedicated DSP chipsets. Business travelers across Chinese high-speed rail corridors and transatlantic routes drive replacement cycles as battery endurance improves.
- In-Ear:Balanced armature and dynamic driver hybrids occupy minimal physical volume. Fitness enthusiasts and mobile commuters in urban India favor sweat-resistant IP ratings.
- On-Ear:Supra-aural clamping force balances portability with acoustic seal. Secondary markets in Southeast Asia absorb previous-generation inventory.
Over-Ear holds installed capacity. Noise-Canceling is rotating up the share rankings.
Connectivity:
Application context determines whether latency tolerance or convenience dominates purchase decisions.
- Bluetooth:LE Audio and Auracast protocols enable broadcast reception without device pairing. Public venue mandates in German transit systems are certifying compatible receiver implementations.
- Wireless:Proprietary 2.4 GHz dongles deliver sub-20ms latency for esports tournament play. Competitive gaming leagues in the United States mandate these specifications.
- Wired:Analog 3.5mm and USB-C digital connections persist in professional audio monitoring. Recording engineers in Japan maintain demand for zero-latency tracking.
- NFC:Tap-to-pair functionality simplifies device handoffs in enterprise headset deployments. Corporate IT departments in the United States specify these for unified communications rollouts.
Bluetooth commands volume leadership. Wireless is climbing the fastest among gaming-specialized SKUs.
Target Audience:
Customer type segmentation aligns acoustic tuning, industrial design, and channel strategy with usage intensity.
- Audiophiles:Planar magnetic and electrostatic driver technologies prioritize transient response over efficiency. Enthusiast communities in Germany and Japan sustain boutique manufacturing at premium price points.
- Gamers:Spatial audio rendering with head-tracking sensors integrates with six-degrees-of-freedom game engines. Chinese and United States esports venues standardize on low-latency wireless configurations.
- Professional Musicians:Flat frequency response curves enable accurate monitoring during recording and live performance. Studio complexes in Los Angeles and Nashville specify reference-grade closed-back designs.
- Casual Users:Convenience features including multipoint pairing and voice assistant integration dominate purchase criteria. Mass-market retail channels in India and Brazil move highest unit volumes.
Audiophiles anchor premium pricing power. Gamers are gaining share fastest through tournament infrastructure investment.
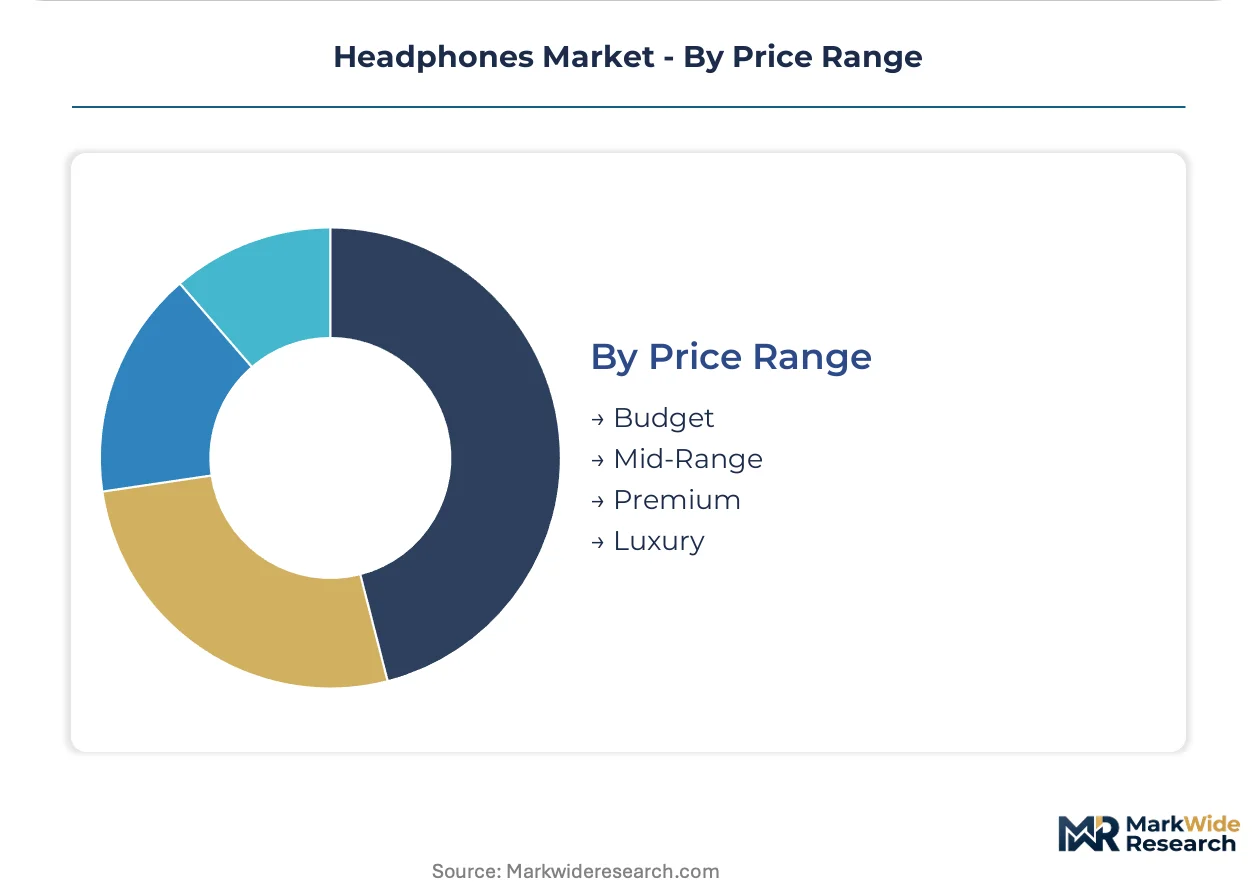
Price Range:
Margin structure concentrates in tiers where material costs scale sub-linearly with retail price.
- Premium:Active noise cancellation, premium materials, and extended warranty programs justify three-figure price points. Frequent flyers in the United States and Germany sustain replacement demand.
- Luxury:Exotic material selections including titanium, carbon fiber, and hand-finished wood enclosures target collector markets. Limited distribution through flagship retail in Tokyo and Milan preserves exclusivity.
- Mid-Range:Hybrid active noise cancellation and multi-codec Bluetooth support deliver flagship-adjacent features. Price-sensitive professionals in China and South Korea upgrade from budget tiers.
- Budget:Commodity dynamic drivers and plastic construction prioritize unit economics. Emerging market expansion in Southeast Asia and Africa absorbs manufacturing overcapacity.
Premium captures the steepest expansion trajectory. Mid-Range holds the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in audio equipment reveal concentrated manufacturing in East Asia offsetting premium consumption in Western markets. The United States, China, Germany, Japan, and South Korea collectively anchor both supply chains and demand absorption for advanced headphone systems.
United States
Professional gaming leagues and enterprise IT refresh cycles drive premium wireless adoption. The FCC governs 2.4 GHz unlicensed emissions under Part 15 rules, creating certification requirements for multi-device pairing features. Los Angeles and Nashville studio complexes sustain demand for reference-grade monitoring equipment used in recording and mixing workflows.
China
Domestic esports venues and high-speed rail corridors propel noise-canceling replacement cycles. The State Administration for Market Regulation enforces GB standards for electronic audio safety and electromagnetic compatibility. Shenzhen and Dongguan manufacturing clusters handle final assembly for global brands while domestic brands capture mid-tier consumer segments.
Germany
Audiophile communities and hearing assistance mandates in transit infrastructure sustain premium-tier demand. REACH substance restrictions and CE marking frameworks shape material selection for earcup housings. Berlin acoustic R&D laboratories and Munich audio engineering clusters concentrate psychoacoustic tuning expertise for European markets.
Japan
Recording engineers and planar magnetic enthusiasts maintain demand for zero-latency wired monitoring. METI oversees industrial standards coordination while JIS specifications govern product safety. Tokyo flagship retail channels distribute limited-edition collector models targeting luxury-tier buyers.
South Korea
Galaxy ecosystem lock-in and price-sensitive professional upgrades drive wireless earbud volume. The Ministry of Trade, Industry and Energy supports semiconductor and display integration into audio systems. Seoul Capital Area technology campuses develop low-power codec implementations for extended battery endurance.
Headphones Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying drivers, chipsets, and acoustic materials. The vendor base organizes into three tiers: multinational electronics conglomerates with captive semiconductor divisions, dedicated audio houses with century-long acoustic heritage, and contract manufacturers serving private-label brands. Consolidation pressure intensifies as codec licensing and RF certification costs rise. Dominant competitive moves include backward integration into driver magnet supply and direct-to-consumer channel bypass of traditional retail.
Within the platform-integrator tier, Apple Inc. and Samsung Electronics exemplify ecosystem-lock-in strategies that bundle audio hardware with operating system software. Sony Corporation occupies a position bridging component and system tiers through captive noise-canceling chipset production. Sennheiser Electronic GmbH & Co. KG represents the dedicated audio house archetype with heritage positioning in professional monitoring segments. Bose Corporation anchors the direct-to-consumer vector with acoustic R&D concentration in the United States.
| Leading Market Players |
|---|
| Apple Inc. |
| Sony Corporation |
| Samsung Electronics |
| Bose Corporation |
| Sennheiser Electronic GmbH & Co. KG |
| Skullcandy Inc. |
| Harman International |
| JVC Kenwood Corporation |
| Audio-Technica Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shenzhen and Dongguan assembly clusters compresses margins for contract manufacturers while concentrating pricing power with brands that control acoustic IP and direct-to-consumer channels. This utilization dynamic forces suppliers into consignment inventory arrangements and accelerates backward integration into driver magnet supply among tier-one vendors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize component costs across volatile rare earth markets. Price differentiation separates CE-certified professional monitoring tiers from uncertified consumer goods based on driver matching precision and extended warranty programs. Cost compression in budget tiers intensifies because Chinese contract manufacturers absorb excess capacity through private-label arrangements. Enterprise IT departments exhibit lowest price sensitivity due to unified communications platform standardization, while Southeast Asian retail channels face acute margin pressure from unbranded import competition.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare earth processing facilities, Malaysian downstream separation plants, and Australian mining operations. Acoustic damping foams hinge on Japanese petrochemical derivatives and German engineered polymer formulations. Single-source vulnerability concentrates in neodymium oxide refining capacity, exposing driver manufacturers to export quota volatility. Distribution runs through brand-controlled direct-to-consumer platforms, enterprise IT procurement channels, and mass-market retail chains in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Headphones sit in early-cycle expansion as Auracast broadcast infrastructure mandates in German transit systems and hearing assistance regulations create certified receiver demand that outpaces current supply capacity.
For Market Incumbents: Entrench ecosystem lock-in through proprietary low-latency gaming protocols and captive noise-canceling chipset production that emerging entrants cannot replicate without semiconductor fab access. Defend against white-label erosion by controlling acoustic R&D clusters in Berlin and Los Angeles where DSP firmware talent concentrates. Prioritize certification investment for LE Audio and Auracast compliance to capture public venue installation contracts.
For New Entrants and Emerging Players: Establish a beachhead in industrial hearing protection convergence by integrating OSHA-compliant two-way radio with Bluetooth streaming for construction and manufacturing floors. Target hearing assistance receiver implementations in German and Japanese transit infrastructure where certification barriers filter out consumer-grade competition. Deploy subscription hardware financing through direct-to-consumer channels to bypass retail margin extraction.
For Investors and Strategic Acquirers: Long-term, this sits as a component-capture play because acoustic engineering talent scarcity and multi-protocol certification timelines create durable moats around DSP firmware and driver manufacturing specialists. Acquisition candidates include boutique planar magnetic houses in Japan and Germany with heritage positioning among audiophile communities. Monitor LC3 codec deployment rates across Samsung and Apple flagship releases as the inflection signal for wireless fidelity parity with wired alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Auracast Certification Investment | Captures German transit hub mandates and hearing assistance infrastructure spend. |
| Backward Integration into Driver Magnets | Reduces exposure to Chinese rare earth export quota volatility for neodymium supply. |
| Direct-to-Consumer Channel Expansion | Bypasses retail margin extraction while capturing subscription financing recurring revenue. |
| Spatial Audio Platform Integration | Locks in six-degrees-of-freedom head-tracking compatibility with Unreal and Unity engines. |
| Biobased Material Transition | Satisfies REACH substance restrictions and EU battery recycling directives for market access. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with audio hardware product managers, acoustic R&D directors, enterprise IT procurement officers, and contract manufacturing executives; and secondary validation through customs trade records, FCC equipment authorization databases, REACH substance registration filings, and SEC 10-K disclosures from listed electronics conglomerates. Bottom-up unit shipment estimates triangulated against top-down consumer electronics spending data across the analysis window.
Forecast inputs incorporated product type segmentation by driver architecture, connectivity standard adoption curves, price tier elasticity differentials, and regional regulatory cluster alignment. CAGRs were derived from installed base replacement cycles, esports venue buildout trajectories, and Auracast infrastructure deployment schedules. The modeling period captured LE Audio protocol transition dynamics and LC3 codec power consumption improvements that reshape wireless battery endurance assumptions.
Stress conditions across neodymium magnet supply disruption, FCC Part 15 certification delays, and REACH substance restriction expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Bluetooth protocol migration rates and enterprise headset refresh cycles. Cross-checking against NPD Group retail audit data and IHS Markit consumer electronics production estimates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
4K Television Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Sports Electronics Market