
 Ultra HD Action Camera Market | 2026-2036
Ultra HD Action Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra HD Action Camera Market Insights
4K-and-above resolution tiers is reorganizing competitive dynamics across the Ultra HD Action Camera landscape. GoPro Inc. anchors its position through backward integration into custom image processors and proprietary stabilization firmware. Sony Corporation leverages its semiconductor heritage to dominate sensor supply for premium-tier devices. SZ DJI Technology Co. Ltd. competes by extending its drone-native imaging expertise into standalone action camera formats with integrated gimbal systems.
An ultra HD action camera captures video at resolutions of 3840 x 2160 pixels or higher, typically employing CMOS sensors with high dynamic range processing, electronic image stabilization, and ruggedized enclosures rated for submersion, shock, and temperature extremes; these devices serve professional videographers, extreme sports participants, and digital content creators requiring broadcast-quality footage in mobile, hazardous, or unconventional shooting environments. Wearable cameras lead volume shipments due to chest-mount and helmet-integrated adoption across cycling and motorsport communities, while 360-degree capture represents the fastest-growing technology segment as immersive content formats gain traction on streaming platforms. Drone cameras command premium positioning through aerial-specific stabilization and telemetry integration, though mounted cameras retain stable demand within automotive and industrial inspection applications.
FCC certification requirements govern wireless transmission protocols for US-market devices, while CE marking under the EU Radio Equipment Directive shapes product design for European distribution; Japan's METI energy-efficiency standards additionally influence processor selection and battery architecture decisions. China's GB standards for electronic product safety and SAMR quality supervision create compliance thresholds that favor established manufacturers with in-house testing laboratories. Stakeholders must monitor evolving data privacy frameworks governing cloud-connected cameras and biometric-adjacent footage storage as regulatory scope expands beyond traditional hardware safety into software governance and cross-border content transfer protocols.
Market Dynamics
Social media monetization infrastructure is compressing purchase cycles for Ultra HD Action Cameras, as content creators now treat these devices as revenue-generating capital equipment rather than discretionary electronics.
Growth Catalysts
- Streaming platform penetration:YouTube Shorts and TikTok creator funds in the United States, China, and Japan are converting viewership metrics into direct equipment subsidies, accelerating hardware refresh rates among professional vloggers.
- Waterproof certification mandates:IP68 enclosure standards are becoming baseline expectations for retail distribution, pushing manufacturers to redesign thermal management systems around sealed architectures.
- Drone-to-handheld migration:Aerial imaging expertise from unmanned aerial vehicle manufacturers is transferring into standalone camera stabilization, expanding addressable markets beyond traditional action sports demographics.
Market Restraints
- CMOS sensor supply concentration:Premium-tier image sensor fabrication clusters in Japan and South Korea create single-source dependencies that amplify lead time volatility during semiconductor allocation cycles.
- FCC certification friction:United States wireless transmission protocol approvals add four to six months to product launch timelines, compressing effective selling seasons for seasonal hardware releases.
- Smartphone substitution pressure:Computational photography advances in Apple and Samsung flagship devices are eroding casual user segments that previously represented entry-level volume anchors.
Strategic Opportunities
- Industrial inspection verticals:Wind turbine and pipeline maintenance contractors in Germany and Texas are adopting helmet-mounted 4K cameras for remote expert consultation, creating enterprise procurement channels distinct from retail.
- EU Green Deal alignment:Battery replaceability mandates and repairability scoring under incoming ecodesign frameworks favor modular camera architectures over sealed disposable designs.
- Live commerce integration:Chinese e-commerce platforms are embedding real-time streaming capabilities directly into camera firmware, enabling direct-to-consumer monetization without post-production workflows.
Industry Challenges
- Image processing talent scarcity:Firmware engineers capable of optimizing electronic stabilization algorithms for sub-watt power envelopes command premium compensation that strains mid-tier manufacturer R&D budgets.
- Multi-regional certification stacking:Simultaneous FCC, CE marking, and METI compliance requires parallel testing tracks that extend validation costs and compress margin structures for multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra HD Action Camera Market |
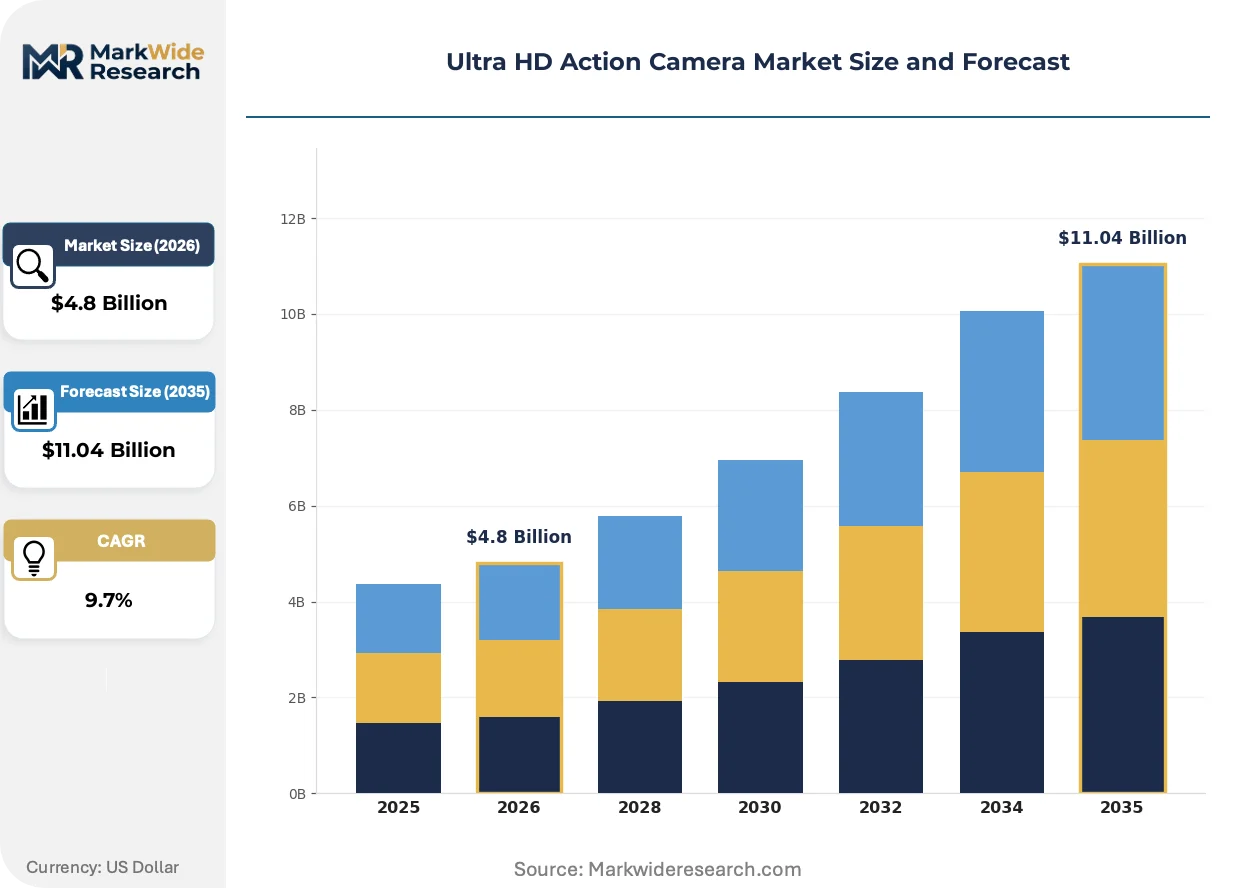
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Cameras, Drone Cameras, Mounted Cameras, Action Camcorders Technology: Optical Image Stabilization, Digital Zoom, 360-Degree Capture, Waterproof Technology End User: Content Creators, Extreme Sports Enthusiasts, Travelers, Professional Videographers Distribution Channel: Online Retail, Specialty Stores, Electronics Chains, Direct Sales |
| Companies Covered | GoPro Inc., SZ DJI Technology Co. Ltd., Sony Corporation, Insta360, Garmin Ltd., Panasonic Corporation, Nikon Corporation, SJCAM Limited, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra HD Action Camera Market Trends and Innovations
Computational imaging pipelines are migrating from post-production software into camera-native hardware, enabling real-time HDR stacking and noise reduction that previously required desktop workstations.
360-degree capture modules with dual spherical lenses are displacing traditional single-sensor action cameras in motorsport and cycling applications, as immersive content formats gain algorithmic preference on Meta and ByteDance distribution platforms. Professional creators in the United States and Japan are adopting these devices at replacement rates exceeding prior generation cycles, compressing average ownership duration from thirty-six to eighteen months.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility thresholds for wearable transmitters, forcing antenna redesigns that trade transmission range for enclosure miniaturization. Manufacturers serving European distribution channels are absorbing additional testing cycles that delay product introductions by one full quarter relative to other markets.
Content creators are unbundling hardware purchases from accessory ecosystems, selecting body-mount and helmet-attachment systems from third-party specialists rather than manufacturer-native bundles. This procurement fragmentation is most pronounced in China, where live-streaming influencers source rigs from Shenzhen component markets while importing camera cores through parallel distribution channels.
Ultra HD Action Camera Market Segmentation
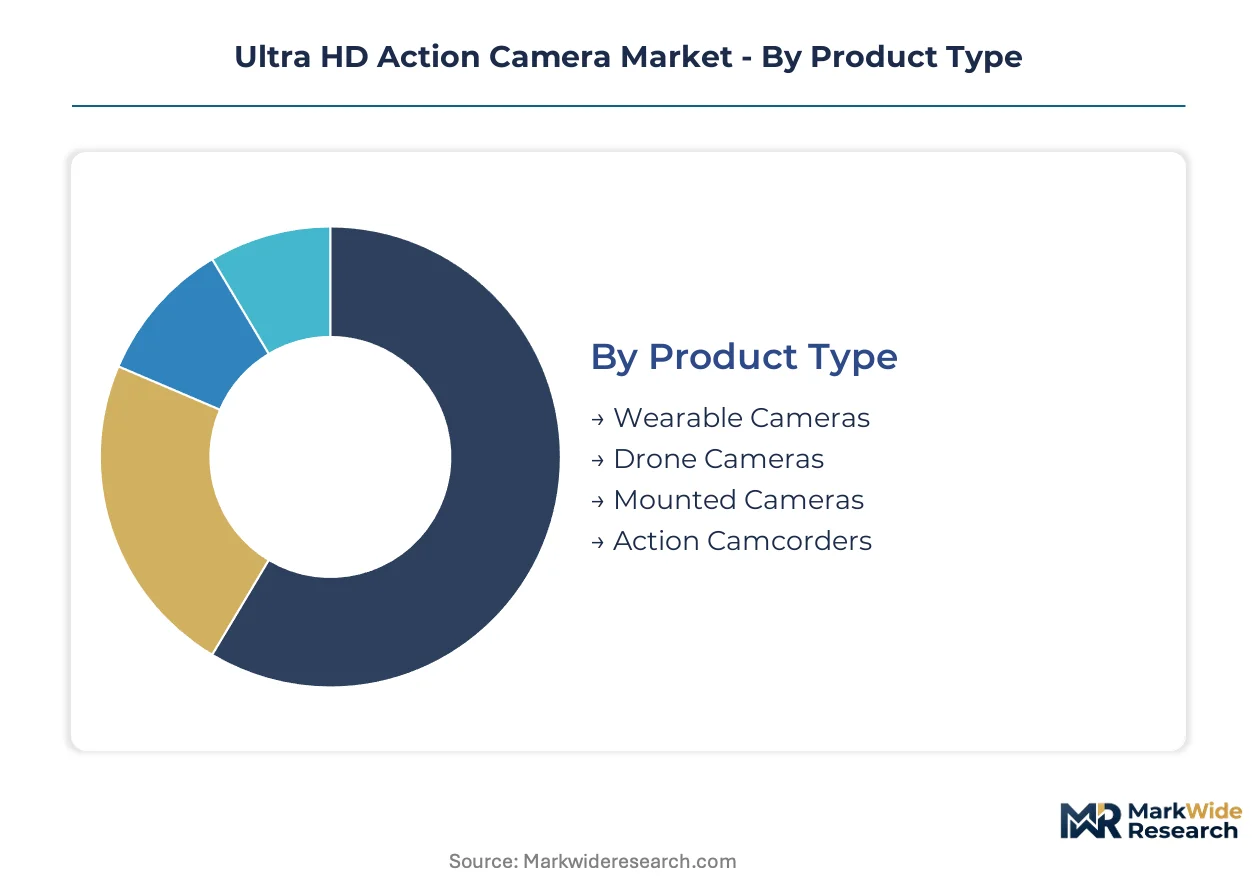
Ultra HD Action Camera purchasing patterns fragment sharply across use cases, with professional workflows demanding broadcast-grade stabilization while casual users prioritize waterproof durability and social media connectivity. Manufacturers must architect distinct product lines for each segment cluster, as technical specifications and price tolerances diverge by more than threefold between entry-level travelers and commercial content creators.
Product Type:
Wearable cameras dominate domestic consumption in the United States, Japan, and China, while drone cameras and mounted variants serve export-intensive industrial applications across Germany and Texas energy corridors.
- Wearable Cameras:Chest-mount and helmet-integrated form factors employ gyroscopic stabilization and sub-100g enclosures for cycling and motorsport communities. Demand concentrates in the United States and Japan where outdoor recreation infrastructure supports year-round capture activities, though FCC certification timelines delay seasonal product launches by four to six months.
- Drone Cameras:Aerial-specific modules integrate telemetry protocols and gimbal systems inherited from unmanned aerial vehicle engineering. Procurement clusters among wind turbine contractors in Germany and pipeline inspectors in Texas who require remote expert consultation capabilities, creating enterprise channels distinct from retail distribution.
- Mounted Cameras:Automotive dash configurations and industrial inspection rigs prioritize thermal tolerance and vibration resistance over weight minimization.
- Action Camcorders:Handheld form factors with integrated viewfinders serve vloggers requiring immediate playback verification without smartphone tethering.
Wearable cameras hold the largest share; momentum sits with drone cameras as industrial inspection verticals expand procurement.
Technology:
Cost-tier stratification separates premium-tier 360-degree and waterproof modules from standard optical stabilization and digital zoom configurations that anchor volume shipments.
- 360-Degree Capture:Dual spherical lens arrays enable immersive content formats gaining algorithmic preference on Meta and ByteDance distribution platforms. Professional creators in the United States and Japan adopt these devices at replacement rates compressing average ownership duration from thirty-six to eighteen months, driven by social media monetization infrastructure.
- Waterproof Technology:IP68 enclosure ratings have become baseline retail expectations, forcing thermal management redesigns around sealed architectures. China's GB standards and Japan's METI energy-efficiency requirements create compliance thresholds that favor established manufacturers with in-house testing laboratories.
- Optical Image Stabilization:Lens-shift mechanisms dominate mid-tier devices where computational alternatives drain battery budgets.
- Digital Zoom:Sensor-cropping algorithms serve price-sensitive segments without mechanical complexity premiums.
Waterproof technology anchors volume; 360-degree capture climbs the fastest as immersive formats reshape creator equipment refresh cycles.
End User:
Application maturity varies dramatically, with professional videographers and content creators driving premium-tier innovation while travelers and extreme sports enthusiasts sustain replacement demand for ruggedized baseline configurations.
- Content Creators:YouTube Shorts and TikTok creator funds in the United States, China, and Japan convert viewership metrics into direct equipment subsidies. This demographic treats Ultra HD Action Cameras as revenue-generating capital equipment rather than discretionary electronics, accelerating hardware refresh rates.
- Extreme Sports Enthusiasts:Helmet-integrated capture demands impact-rated enclosures and sub-zero operational tolerance for alpine and aquatic disciplines. Procurement concentrates in Japan's ski infrastructure and coastal United States surfing communities where seasonal selling windows compress effective launch timelines.
- Travelers:Compact form factors and dual-battery architectures prioritize airline carry-on compliance and all-day capture without charging access.
- Professional Videographers:Broadcast-quality output requirements drive LOG color profile and external microphone input specifications.
Content creators command premium positioning; extreme sports enthusiasts provide the steadiest replacement demand through seasonal equipment wear.
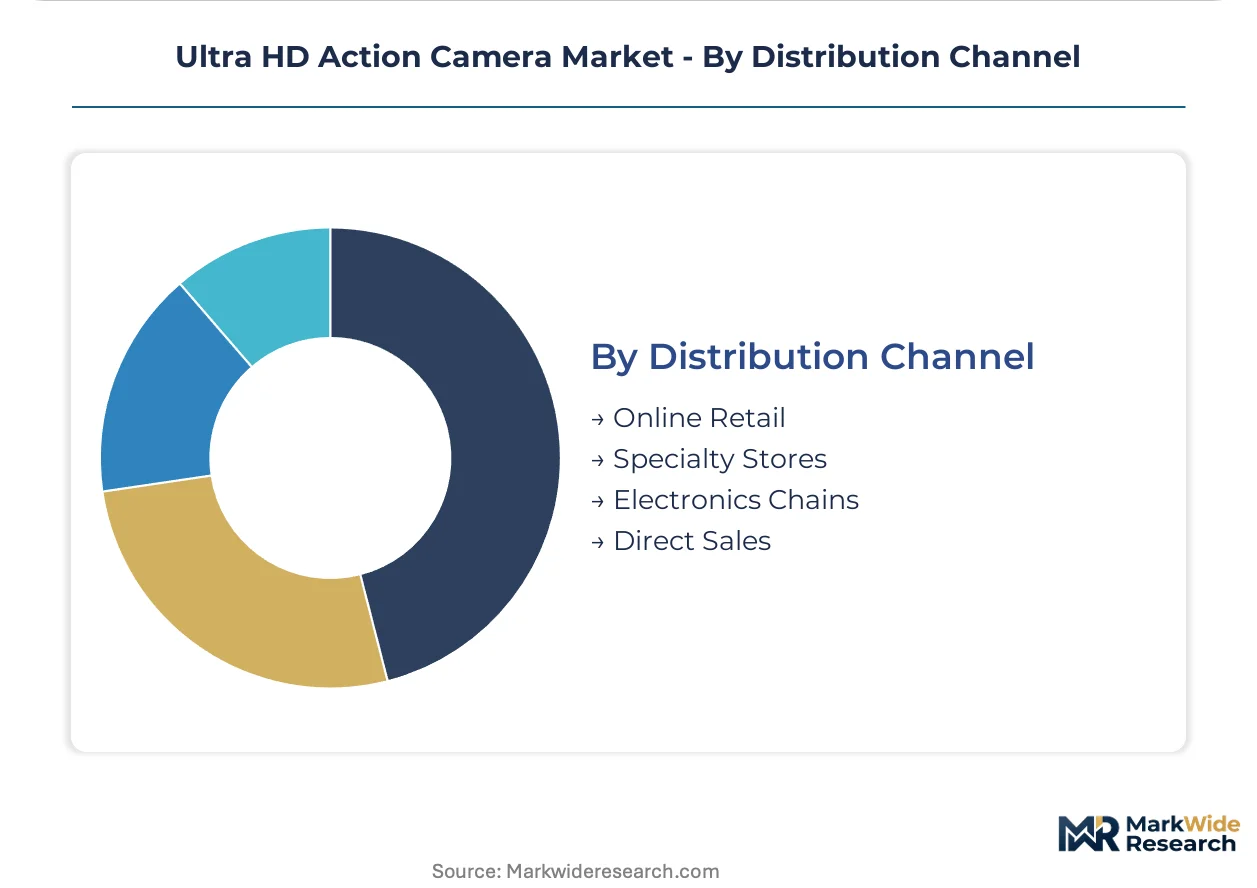
Distribution Channel:
Customer-type bifurcation separates enterprise procurement through direct sales and specialty stores from consumer volume flowing through online retail and electronics chains.
- Online Retail:Chinese e-commerce platforms embed real-time streaming capabilities directly into camera firmware, enabling direct-to-consumer monetization without post-production workflows. Parallel distribution channels allow live-streaming influencers to source rigs from Shenzhen component markets while importing camera cores separately.
- Specialty Stores:Hands-on demonstration environments serve extreme sports communities requiring fit verification for helmet and chest-mount compatibility. These channels concentrate in Japan's outdoor retail corridors and United States coastal recreation hubs.
- Electronics Chains:Big-box retail placement drives casual traveler segment awareness through seasonal promotional cycles.
- Direct Sales:Enterprise contracts with wind turbine and pipeline maintenance operators bypass retail markup through manufacturer-native account management.
Online retail captures the greatest volume; specialty stores gain share fastest as fit-critical wearable applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Image sensor fabrication clusters in Japan and South Korea concentrate critical component supply, while final assembly and brand headquarters distribute across consumer electronics corridors in the United States, China, and Germany. Regulatory certification requirements fragment launch timelines, with FCC protocols in the United States, CE marking in Europe, and METI standards in Japan creating parallel compliance tracks that shape regional product availability.
United States
YouTube Shorts and TikTok creator funds convert viewership metrics into direct equipment subsidies, accelerating hardware refresh cycles among professional vloggers in Los Angeles and New York content production corridors. FCC wireless transmission protocol approvals add four to six months to product launch timelines, compressing effective selling seasons for seasonal hardware releases. Austin and San Francisco anchor drone-to-handheld migration engineering, transferring aerial imaging expertise into standalone camera stabilization systems.
China
Shenzhen component markets supply third-party body-mount and helmet-attachment systems as live-streaming influencers unbundle hardware from accessory ecosystems through parallel distribution channels. GB standards for electronic product safety and SAMR quality supervision create compliance thresholds that favor established manufacturers with in-house testing laboratories. Pearl River Delta assembly clusters dominate volume production, with DJI Technology extending drone-native imaging expertise into standalone action camera formats.
Japan
Tokyo and Osaka outdoor retail corridors concentrate specialty store distribution where extreme sports communities require hands-on fit verification for helmet and chest-mount compatibility. METI energy-efficiency standards influence processor selection and battery architecture decisions, favoring low-power electronic stabilization algorithms. Sony Corporation leverages semiconductor heritage to dominate premium-tier image sensor supply, with Nagoya engineering clusters optimizing CMOS fabrication for high dynamic range processing.
Germany
Wind turbine contractors in Hamburg and pipeline maintenance operators in the Ruhr industrial belt adopt helmet-mounted 4K cameras for remote expert consultation, creating enterprise procurement channels distinct from retail distribution. EU Green Deal battery replaceability mandates and repairability scoring under incoming ecodesign frameworks favor modular camera architectures over sealed disposable designs. Munich and Stuttgart engineering clusters drive industrial inspection vertical adoption, with CE marking under the Radio Equipment Directive tightening electromagnetic compatibility thresholds for wearable transmitters.
South Korea
Seoul semiconductor fabrication facilities supply premium-tier CMOS sensors to global camera manufacturers, creating single-source dependencies that amplify lead time volatility during allocation cycles. National industrial policy supports advanced packaging and image processing chip development, with Pangyo and Suwon clusters specializing in high-dynamic-range sensor architectures. Domestic demand from extreme sports communities in Gangwon Province ski infrastructure sustains replacement demand for impact-rated enclosures with sub-zero operational tolerance.
Ultra HD Action Camera Market Competitive Landscape
Concentration sits with diversified consumer electronics conglomerates and specialized imaging technology developers, with mid-tier manufacturers facing margin compression from certification cost stacking and R&D talent scarcity. Three archetypes dominate: semiconductor-heritage sensor suppliers, drone-to-handheld migration specialists, and action-native wearable camera incumbents. Competitive moves center on backward integration into custom image processors and strategic partnerships for gimbal system licensing.
Within the sensor-supplier archetype, Sony Corporation exemplifies semiconductor heritage positioning through captive CMOS fabrication capabilities. SZ DJI Technology Co. Ltd. represents the drone-to-handheld migration pattern, occupying a position where unmanned aerial vehicle engineering transfers into standalone stabilization systems. GoPro Inc. anchors the action-native wearable camera tier, sitting within a category defined by proprietary stabilization firmware and helmet-integrated form factor specialization.
| Leading Market Players |
|---|
| GoPro Inc. |
| SZ DJI Technology Co. Ltd. |
| Sony Corporation |
| Insta360 |
| Garmin Ltd. |
| Panasonic Corporation |
| Nikon Corporation |
| SJCAM Limited |
| Olympus Corporation |
| Others |
Pricing and Supply Chain Analysis
CMOS sensor fabrication migration from legacy nodes to advanced stacked architectures is redrawing supply geography toward Japan and South Korea while compressing pricing power for mid-tier camera assemblers dependent on merchant sensor procurement.
Pricing Analysis
FCC certification dictates the pricing tier structure across the Ultra HD Action Camera landscape, with IP68 waterproof rating and METI energy-efficiency compliance creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade and volume scale, with enterprise procurement channels for industrial inspection commanding premiums over retail consumer segments. Cost compression in the economy tier is intensifying because smartphone computational photography erodes casual user demand. Content creators exhibit the least price sensitivity due to social media monetization treating hardware as capital equipment, while travelers show highest elasticity to price movements.
Supply Chain Analysis
Inventory cycles for CMOS sensors and image processors now stretch eighteen to twenty-four months, forcing camera manufacturers to pre-commit wafer starts before final demand crystallization. Supply concentrates in Japan for premium-tier sensor fabrication, South Korea for advanced packaging, and China for final assembly and accessory ecosystems. Raw material dependencies center on silicon wafers, rare-earth magnet components for gimbal motors, and lithium-ion cell architectures. Single-source vulnerability in Japanese CMOS fabrication amplifies lead time volatility during semiconductor allocation cycles. Distribution runs through online retail platforms for consumer volume and direct sales contracts for enterprise procurement in Germany and Texas industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as social media monetization infrastructure converts content creation from hobbyist activity to revenue-generating profession, accelerating equipment refresh rates beyond traditional consumer electronics replacement patterns.
For Market Incumbents: Fortify backward integration into custom image processors to escape merchant sensor pricing volatility, while deepening proprietary stabilization firmware moats against drone-to-handheld migration entrants. Secure in-house testing laboratories to absorb GB standards and SAMR compliance costs that disadvantage mid-tier competitors. Channel control through specialty store partnerships in Japan and United States coastal recreation hubs preserves fit-critical demonstration advantages against pure online retail erosion.
For New Entrants and Emerging Players: Differentiate on live commerce integration by embedding real-time streaming capabilities directly into camera firmware for Chinese e-commerce platform native monetization. Target industrial inspection verticals in Germany and Texas where enterprise procurement channels remain underdeveloped by action-native incumbents. Pursue modular camera architectures aligned with EU Green Deal battery replaceability mandates as a regulatory-first go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-heritage sensor suppliers and drone-to-handheld migration specialists with captive stabilization engineering, as these archetypes capture value chain positioning that pure assembly players cannot replicate. Long-term viability favors entities with in-house fabrication or unmanned aerial vehicle engineering lineage over brand-dependent marketers vulnerable to component cost squeezes. Watch 360-degree capture adoption rates among United States and Japanese professional creators as the inflection signal for immersive format platform algorithm shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Custom Image Processors | GoPro and Sony reduce merchant chip dependency while optimizing sub-watt stabilization algorithms. |
| Drone-to-Handheld Engineering Transfer | DJI leverages aerial gimbal expertise to capture standalone camera share beyond traditional action sports. |
| EU Green Deal Modular Architecture Alignment | Repairability scoring favors battery-replaceable designs over sealed disposable competitors in Germany. |
| Live Commerce Firmware Integration | Chinese e-commerce platforms embed real-time streaming to bypass post-production workflow friction. |
| Industrial Inspection Vertical Expansion | Wind turbine contractors in Hamburg adopt helmet-mounted 4K for remote expert consultation procurement. |
Research Methodology
Cross-validation between primary interviews with content creator equipment managers, semiconductor procurement leads at camera manufacturers, and specialty store operators anchors the qualitative findings against secondary validation from FCC equipment authorization databases, METI energy-efficiency filings, and GB standards compliance records. Bottom-up triangulation aggregates segment-level demand patterns across wearable, drone, and mounted camera form factors, while top-down reconciliation tests aggregate figures against customs trade data and regional electronics production indices.
Sensitivity analysis across the projection horizon varies social media monetization infrastructure penetration rates and smartphone computational photography substitution thresholds to bound forecast uncertainty. The analytical framework segments by product type, technology tier, end-user archetype, and distribution channel, with additional modeling of regional regulatory cluster effects. CAGRs derive from fitted growth curves calibrated to historical replacement cycle compression and platform algorithm preference shifts toward immersive formats.
Decision-makers should treat outputs as directional under assumptions of sustained streaming platform creator fund expansion and stable semiconductor allocation cycles; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Headphones Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Pet Cameras Market