
 Global Dry Yeast Market | 2026-2036
Global Dry Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dry Yeast Market Foresight
Multi-source procurement for fermentation cultures is restructuring supply relationships across the Global Dry Yeast Market. Lesaffre leverages its vertically integrated strain development and regional production networks to sustain supply security for industrial bakers. Angel Yeast anchors Asia-Pacific volume through aggressive capacity expansion in specialty yeast extracts. Lallemand Inc. differentiates via biotechnology-grade yeast platforms serving pharmaceutical and nutraceutical contract manufacturers.
Dry yeast comprises dehydrated Saccharomyces cerevisiae cells preserved through controlled air-drying or fluidized-bed drying to achieve moisture levels below 8%, enabling ambient storage and extended shelf stability for leavening, fermentation, and nutritional applications. Active dry yeast and instant yeast command the largest volume positions, with instant yeast capturing accelerated growth in commercial baking due to its direct-mix compatibility and reduced hydration requirements. Organic dry yeast represents the fastest-expanding product category as food processors reformulate clean-label portfolios to meet retailer sustainability specifications.
FDA food safety standards, the EU Green Deal sustainability framework, and China's GB standards for food-grade yeast collectively govern strain approval, labeling claims, and carbon intensity disclosures across major production jurisdictions. EFSA novel food assessments and REACH chemical safety protocols further constrain market entry for genetically modified or engineered yeast variants in European applications. Stakeholders must monitor evolving strain registration pathways and carbon border adjustment mechanisms to preserve market access and avoid stranded inventory in premium segments.
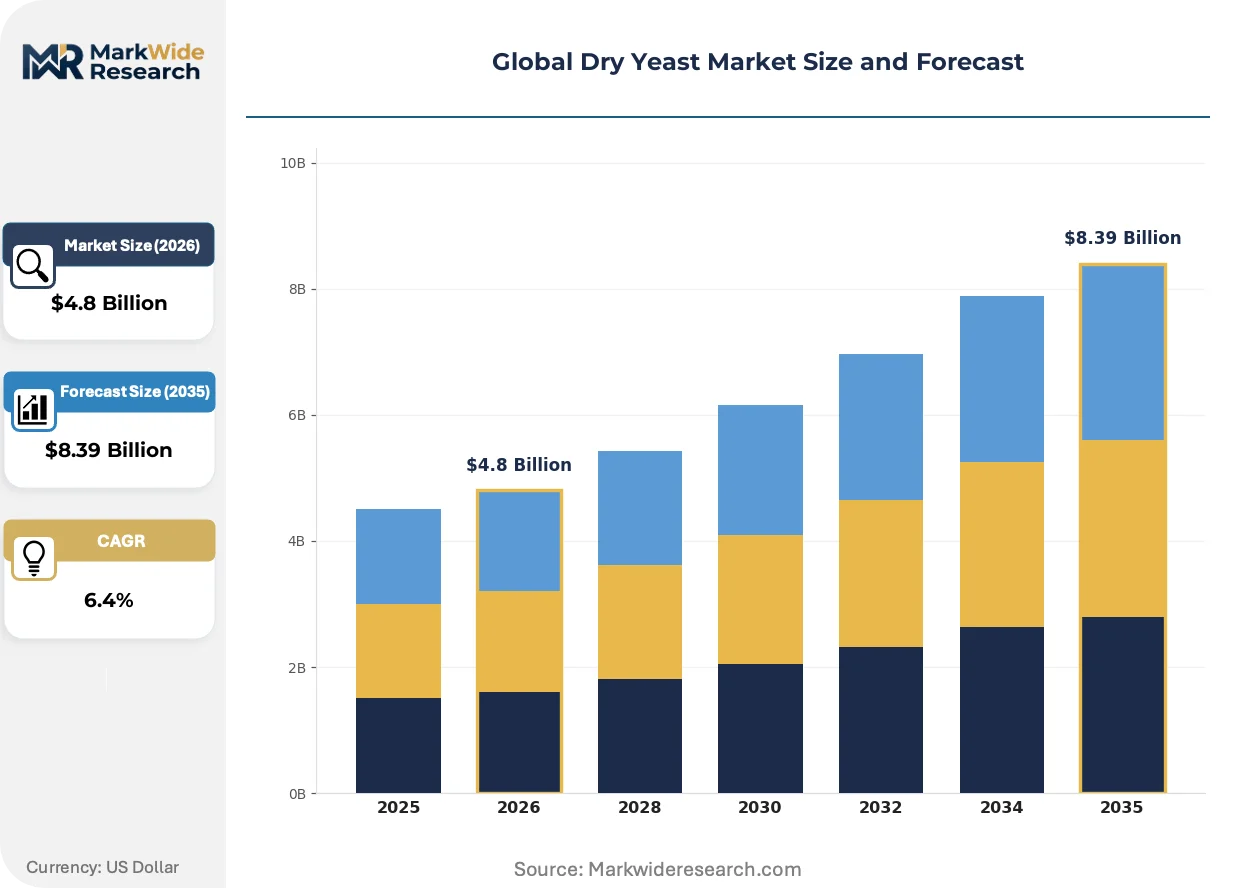
Market Dynamics
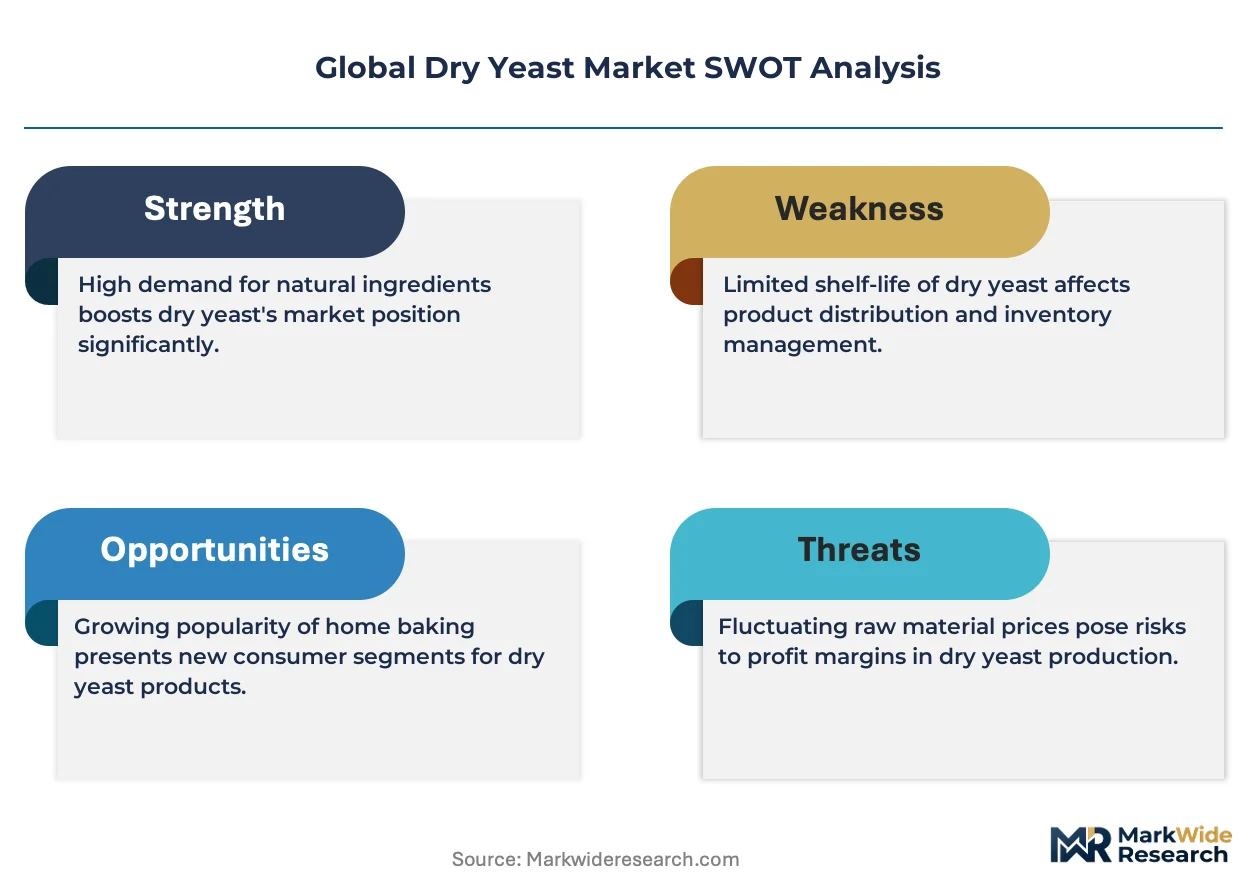
Industrial bakers' procurement of instant yeast formats is compressing proofing cycles and energy costs, while the EU Green Deal's carbon intensity mandates force strain developers toward organic certification and lower-footprint fermentation infrastructure.
Growth Catalysts
- EU Green Deal sustainability mandates:Carbon disclosure requirements for food-grade yeast imports are accelerating organic strain development and renewable energy adoption in European production facilities.
- Craft brewing revival in Germany:Precision fermentation investments across Bavaria and Baden-Württemberg are expanding yeast consumption for both beverage and biotechnology applications.
- Instant yeast direct-mix compatibility:Commercial bakeries in France and Italy are eliminating pre-hydration steps, cutting labor costs and line downtime in high-throughput operations.
Market Restraints
- Molasses supply volatility:Sugar beet harvest fluctuations in Ukraine and Russia constrain primary feedstock availability for European yeast manufacturers.
- EFSA novel food assessments:Strain registration timelines for genetically modified variants extend 18-36 months, blocking rapid biotechnology market entry.
- Active dry yeast substitution:Some artisan bakeries retain preference for traditional rehydration protocols despite instant yeast efficiency gains.
Strategic Opportunities
- India FSSAI clean-label enforcement:Organic dry yeast demand from packaged bread manufacturers is outpacing domestic supply, creating import substitution openings.
- Pharmaceutical contract manufacturing:Biotechnology-grade yeast platforms for recombinant protein production represent underpenetrated white space in North American nutraceutical supply chains.
- China dual carbon goals:Provincial renewable energy mandates in Shandong and Hubei are incentivizing low-carbon fermentation facility upgrades with state subsidy support.
Industry Challenges
- Strain development talent scarcity:Molecular biologists with Saccharomyces cerevisiae metabolic engineering expertise command premium compensation, constraining R&D expansion at mid-scale producers.
- Legacy drying equipment integration:Fluidized-bed system upgrades require 24-36 month capital deployment cycles, delaying moisture-control precision improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dry Yeast Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Instant Yeast, Rapid-Rise Yeast, Organic Dry Yeast Application: Baking, Brewing, Animal Feed, Biotechnology End Use Industry: Food Processing, Beverage Production, Agriculture, Pharmaceutical Manufacturing Packaging Type: Vacuum Pack, Foil Bag, Plastic Container, Bulk Packaging |
| Companies Covered | Lallemand Inc., Pakmaya, Lesaffre, Chr. Hansen Holding A/S, Kerry Group, AB Mauri, Red Star Yeast, Associated British Foods, Angel Yeast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dry Yeast Market Shifts & Advancements
Precision fermentation and carbon accounting technologies are actively restructuring how yeast strains are developed, validated, and procured across food and biotechnology end-uses.
Continuous fermentation monitoring systems with real-time metabolite sensing are rewriting process economics for industrial-scale yeast production. Large-scale bioethanol and brewing facilities in Brazil and the United States are deploying these platforms to compress batch-to-batch variability and reduce off-spec product rates. The structural consequence is a shift toward data-driven strain selection contracts that penalize suppliers for deviation from specified fermentation kinetics.
REACH chemical safety protocols and EFSA carbon footprint disclosure requirements are tightening documentation burdens for yeast extract imports into European pharmaceutical and food applications. Manufacturers must now submit full lifecycle assessments covering agricultural feedstock through spray-drying energy inputs. Biotechnology-grade suppliers serving German and Swiss contract manufacturers are responding by segregating production lines and pursuing ISO 14001 certification to preempt audit failures.
Bakeries are consolidating supplier relationships around single-source instant yeast contracts with embedded technical service support, displacing fragmented multi-brand procurement. This concentration is most visible in France's industrial bread sector, where Les Mousquetaires and Carrefour's private-label suppliers now mandate dedicated fermentation scientists from yeast partners. The shift compresses switching flexibility but secures strain consistency and regulatory documentation continuity.
Global Dry Yeast Market Segmentation
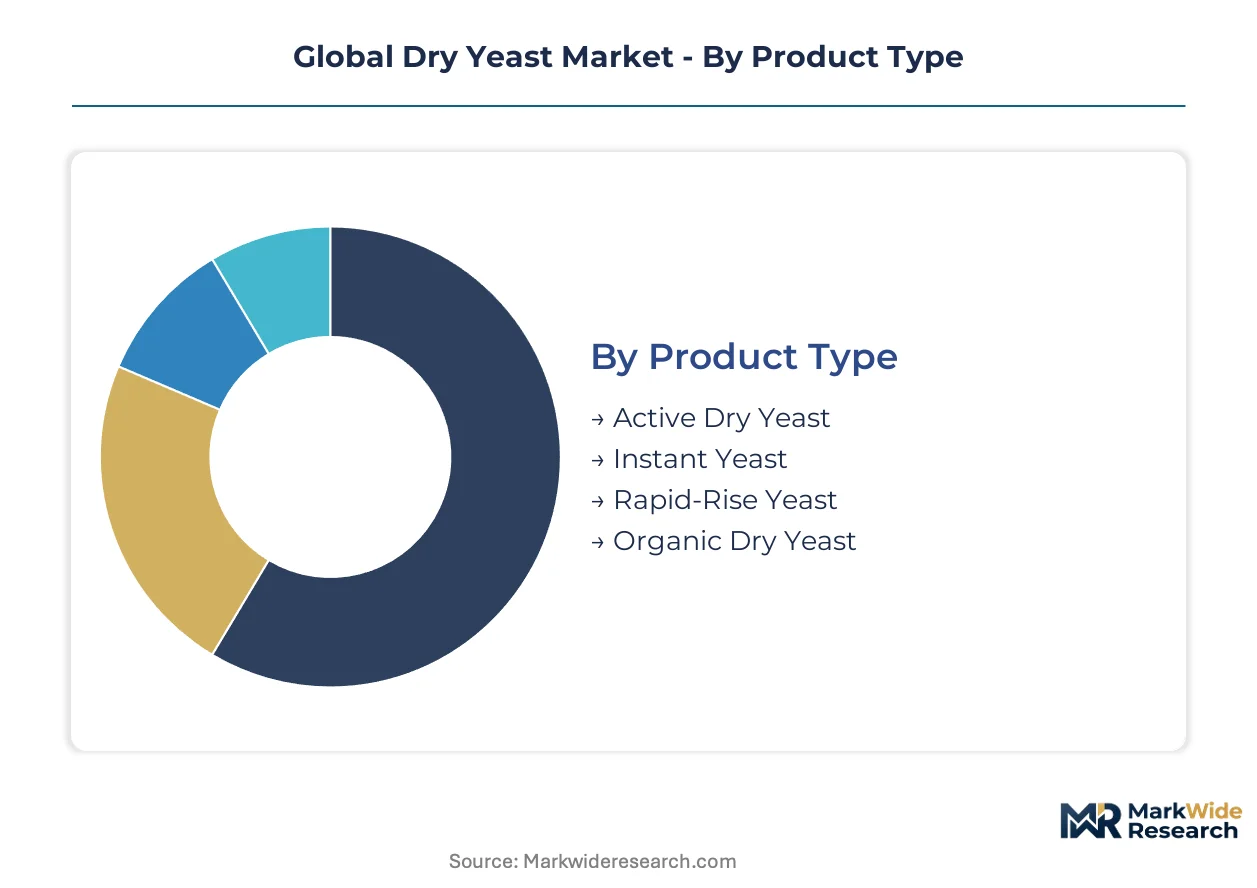
Dry yeast segmentation reveals how production technology, regulatory compliance, and end-use performance requirements partition value across distinct supply tiers. Manufacturers configure strain development, drying infrastructure, and certification pathways differently for each segment, creating specialized competitive arenas.
Product Type:
Standardization dominates commodity formats while specialty variants command premium positioning through certification and strain proprietary claims.
- Active Dry Yeast:Granular Saccharomyces cerevisiae with 92-94% solids content requires 10-15 minute rehydration in warm water before incorporation. Industrial bakeries in France and Italy maintain procurement contracts for this format where fermentation timing precision outweighs labor cost considerations.
- Instant Yeast:Finely milled particles with enhanced osmotolerance enable direct dry blending with flour, eliminating proofing stages entirely. Commercial bread manufacturers in Germany and the United States are consolidating procurement around this format to compress energy-intensive warming cycles and reduce line downtime.
- Rapid-Rise Yeast:Accelerated fermentation kinetics suit home baking and small-scale foodservice operations with constrained proofing space.
- Organic Dry Yeast:Strains propagated on certified organic molasses with full chain-of-custody documentation meet EU Green Deal carbon disclosure requirements and retailer clean-label mandates.
Most installed capacity flows through Instant Yeast. Expansion is steepest in Organic Dry Yeast.
Application:
Volume concentration in mature uses contrasts with biotechnology's emerging margin profile.
- Baking:Leavening applications in industrial and artisan bread production consume the largest volume share, with procurement patterns shifting toward just-in-time delivery contracts with embedded technical service support.
- Brewing:Craft brewery revival across Bavaria and Baden-Württemberg is expanding demand for specialty ale and lager strains with documented fermentation kinetics and flavor compound profiles.
- Animal Feed:Nutritional yeast and yeast cell wall products for gut health formulations in poultry and aquaculture operations.
- Biotechnology:Recombinant protein production and precision fermentation platforms represent the fastest-climbing trajectory, with German and Swiss contract manufacturers requiring biotechnology-grade documentation and ISO 14001-certified production lines.
Revenue concentration sits with Baking. Biotechnology commands the steepest margin expansion trajectory.
End Use Industry:
Regulatory stringency escalates from food through pharmaceutical applications, fragmenting supplier qualification requirements.
- Food Processing:Packaged bread, pastry, and savory product manufacturers in India and Brazil are scaling procurement of instant formats under FSSAI and ANVISA enforcement of clean-label standards.
- Beverage Production:Large-scale bioethanol facilities in Brazil and the United States deploy continuous fermentation monitoring systems with real-time metabolite sensing to compress batch-to-batch variability.
- Agriculture:Probiotic and nutritional supplement applications for livestock and aquaculture feed formulations.
- Pharmaceutical Manufacturing:Recombinant protein and enzyme production platforms require segregated production lines, full lifecycle carbon assessments, and REACH-compliant documentation for European market access.
Procurement scale peaks in Food Processing. Documentation burden intensifies most sharply in Pharmaceutical Manufacturing.
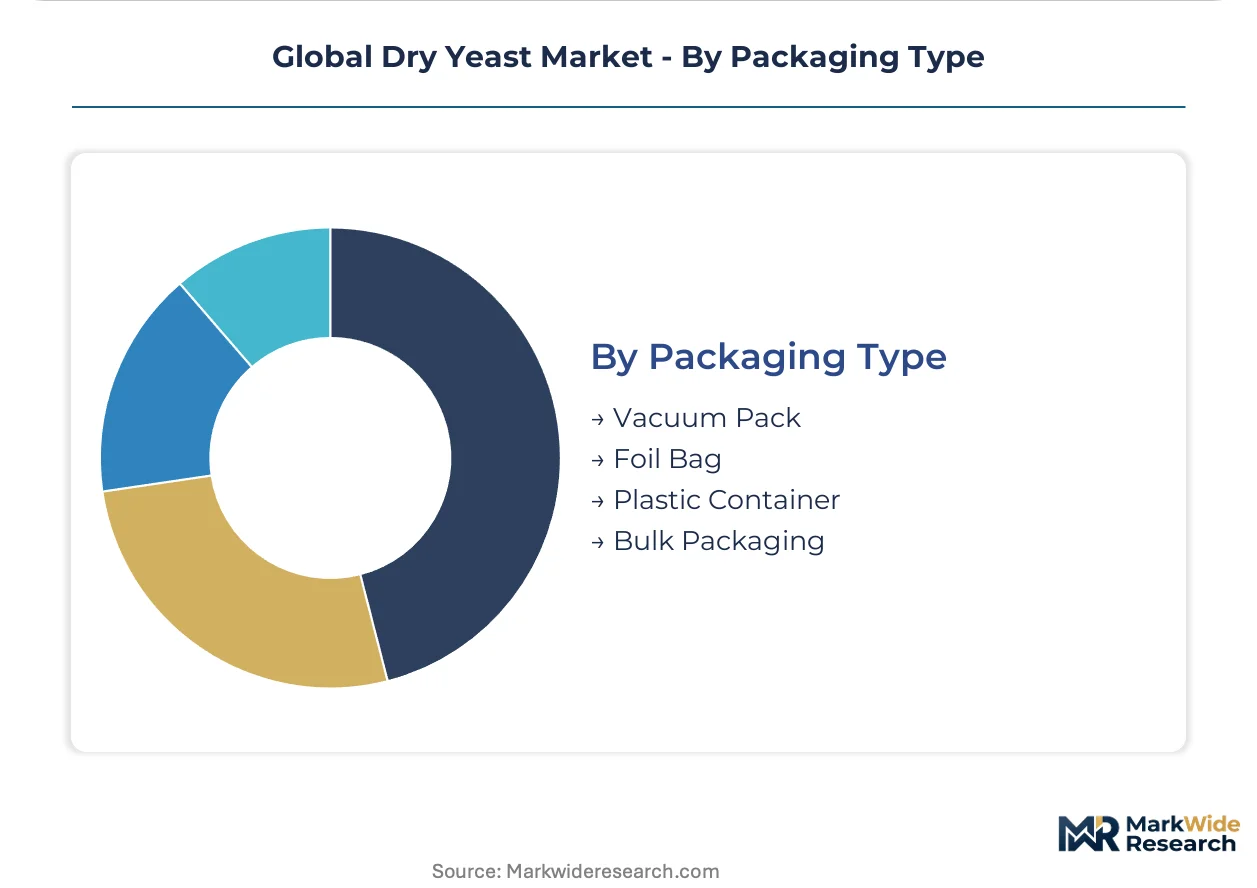
Packaging Type:
Shelf stability requirements and distribution economics determine format selection across ambient and controlled-temperature supply chains.
- Vacuum Pack:Oxygen-excluded barrier films extend ambient shelf stability to 24 months, dominating retail and foodservice channels where inventory turnover varies.
- Foil Bag:Multi-layer metallized laminates provide moisture and light protection for mid-scale industrial users with moderate throughput.
- Plastic Container:Rigid packaging with resealable closures targets home baking segments and small commercial operations.
- Bulk Packaging:Supersacks and tote systems for high-volume industrial bakeries and brewing facilities with dedicated strain storage and handling infrastructure.
Unit economics favor Vacuum Pack at retail. Bulk Packaging captures the greatest volume throughput in industrial channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting dry yeast production toward jurisdictions with lower carbon-accounting compliance costs while EU Green Deal enforcement tightens strain documentation requirements. Manufacturers are relocating fermentation capacity to exploit feedstock availability gaps and renewable energy subsidies.
United States
Large-scale bioethanol facilities in Iowa and Nebraska deploy continuous fermentation monitoring systems with real-time metabolite sensing to compress batch-to-batch variability. EPA renewable fuel standards mandate documented fermentation kinetics for bioethanol yeast strains. Chicago-area industrial bakeries consolidate procurement around instant yeast contracts with embedded technical service support.
Germany
Precision fermentation investments across Bavaria and Baden-Württemberg expand yeast consumption for both beverage and biotechnology applications. EU Green Deal carbon disclosure requirements accelerate organic strain development and renewable energy adoption in European production facilities. Munich's craft brewing revival drives specialty ale and lager strain procurement with documented flavor compound profiles.
China
Provincial renewable energy mandates in Shandong and Hubei incentivize low-carbon fermentation facility upgrades with state subsidy support. GB standards for food-grade yeast govern strain approval and labeling claims across domestic production. Yangtze River Delta yeast extract manufacturers pursue ISO 14001 certification to preempt European audit failures.
India
FSSAI clean-label enforcement drives organic dry yeast demand from packaged bread manufacturers outpacing domestic supply. Maharashtra and Gujarat industrial bakeries scale procurement of instant formats under tightened food safety protocols. Bangalore-based precision fermentation startups target recombinant protein production gaps in pharmaceutical contract manufacturing.
Brazil
Sugarcane molasses availability anchors feedstock security for Latin American yeast manufacturers serving bioethanol and baking applications. ANVISA enforcement of clean-label standards accelerates organic strain adoption in packaged bread manufacturing. São Paulo-state industrial bakeries eliminate pre-hydration steps through instant yeast direct-mix compatibility.
Global Dry Yeast Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-grade specialization and carbon-certified production lines. The vendor base stratifies across three capability tiers: multinational strain developers with vertically integrated fermentation networks, regional specialists capturing feedstock-proximate cost advantages, and biotechnology-grade platforms serving pharmaceutical contract manufacturers. Competitive positioning hinges on strain proprietary claims, regulatory documentation continuity, and embedded technical service contracts. Capacity expansion and strategic partnerships dominate capital deployment, with fluidized-bed drying upgrades and precision fermentation licensing agreements structuring recent transactions.
Within the multinational tier, Lesaffre and Lallemand Inc. exemplify divergent specialization vectors. Lesaffre anchors European supply security through vertically integrated strain development and regional production networks. Lallemand Inc. occupies a position in biotechnology-grade yeast platforms serving pharmaceutical and nutraceutical contract manufacturers. Angel Yeast represents the Asia-Pacific volume anchor through aggressive capacity expansion in specialty yeast extracts.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Pakmaya |
| Lesaffre |
| Chr. Hansen Holding A/S |
| Kerry Group |
| AB Mauri |
| Red Star Yeast |
| Associated British Foods |
| Angel Yeast |
| Others |
Supply & Pricing Matrix
Fluidized-bed drying upgrades across German and Chinese production facilities are compressing moisture-control precision costs while concentrating procurement power among buyers with multi-year technical service contracts. This production-method transition simultaneously reduces energy inputs per kilogram and locks in supplier switching costs through embedded fermentation scientist support.
Pricing Analysis
Distributor margins on organic dry yeast absorb certification documentation burdens that direct-to-industrial contracts bypass entirely. Three-tier pricing structure across premium, standard, and economy levels separates biotechnology-grade ISO 14001-certified strains from commodity instant formats and artisan active dry variants. Cost compression in standard tiers is intensifying because Brazilian and Indian bakers are consolidating procurement around single-source contracts. Small-scale foodservice operators exhibit highest price sensitivity; pharmaceutical contract manufacturers show least sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Dual-sourcing requirements from Munich-area industrial bakeries mandate qualification of at least two strain suppliers with matched fermentation kinetics documentation. Geographic supply concentration centers on Germany, China, and Brazil, with each jurisdiction anchoring distinct certification tiers. Raw material flows draw from Ukrainian and Russian sugar beet molasses, Indian sugarcane derivatives, and Brazilian ethanol co-product streams. Single-source vulnerability sits with precision fermentation talent pools in Bavaria and Baden-Württemberg. Distribution runs through regional fermentation scientists embedded at buyer facilities rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Dry Yeast Market functions as a stable compounder anchored by irreplaceable leavening demand in industrial bread production that resists substitution across economic cycles.
For Market Incumbents: To counter biotechnology-grade specialization by pharmaceutical-focused entrants, Lesaffre and Lallemand Inc. should deepen captive supply of organic molasses through backward integration into Ukrainian and Brazilian agricultural networks. Certification investment in EU Green Deal carbon disclosure protocols preserves premium segment access against emerging Asian competitors. For New Entrants and Emerging Players: Launch via direct technical service contracts with Maharashtra and Gujarat industrial bakeries where FSSAI clean-label enforcement has outpaced domestic organic supply. White-space targets include recombinant protein production for Bangalore precision fermentation startups and carbon-certified strain development for Shandong provincial subsidy capture. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional producers with feedstock-proximate cost advantages but lacking biotechnology-grade documentation capabilities. Long-term viability framing favors acquisition targets with ISO 14001-certified production lines and existing European pharmaceutical customer relationships. The signal to watch is EFSA novel food assessment timeline compression for genetically modified strain variants.| Strategic Initiative | Industry Significance |
|---|---|
| Fluidized-Bed Drying Upgrade | Reduces moisture variability below 8% for extended ambient shelf stability. |
| Organic Certification Investment | Secures EU Green Deal compliance and retailer clean-label procurement mandates. |
| Precision Fermentation Licensing | Expands biotechnology-grade platform access for recombinant protein production. |
| Embedded Technical Service Contracts | Locks in industrial bakery relationships through dedicated fermentation scientist support. |
| Backward Integration into Molasses Supply | Anchors feedstock security against Ukrainian harvest volatility and Russian supply disruptions. |
Research Methodology
Bottom-up baking and biotechnology application modeling reconciled against top-down strain production capacity tracking forms the analytical core. Primary interviews with industrial bakery procurement directors, precision fermentation R&D leads, pharmaceutical contract manufacturing quality officers, and molasses supply traders combined with secondary validation from EU EFSA novel food assessment filings, FDA food safety standard updates, Chinese GB standards documentation, and Brazilian ANVISA clean-label enforcement records. Triangulation across these sources reconciles volume estimates with producer-reported capacity utilization.
Input-output matrices map strain development investment through drying infrastructure deployment to end-use consumption across product type, application, and packaging format dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Industry-specific forecast inputs include molasses feedstock price indices and EU carbon border adjustment mechanism implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA novel food assessment timeline extensions or Ukrainian sugar beet harvest collapses. Deviation in EU Green Deal carbon intensity enforcement thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Baobab Ingredient Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
United Kingdom Protein Market
Ingredients
South America Protein Market
Ingredients
Barley Flake Market
Ingredients
Seaweed Derivatives Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Amylase Market
Ingredients
Tapioca Market
Ingredients
Organic Pastry Flour Market
Ingredients
Fruit Powder Market
Ingredients
Oat Ingredients Market
Ingredients
North America Fats and Oils Market