
 Farm Implements Market | 2026-2036
Farm Implements Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Implements Market Analysis
The EU Green Deal is decoupling agricultural subsidy eligibility from intensive tillage practices, redirecting capital toward reduced-disturbance implements across European arable operations. Deere & Company leverages its precision agriculture platform to anchor premium positioning in North American row-crop segments. CNH Industrial sustains manufacturing scale through integrated driveline production in Italy and Brazil. AGCO Corporation differentiates via Fendt's variable-track technology leadership in high-horsepower European markets.
Farm implements comprise mechanically powered or trailed equipment designed for soil preparation, planting, cultivation, and harvesting, typically featuring hardened alloy steel cutting edges and hydraulic depth control to achieve specified working tolerances within agricultural field conditions. Their primary commercial purpose centers on expanding operational throughput while reducing per-hectare labor inputs across mechanized farming systems. Harvesters capture the largest value share among product types due to capital intensity and replacement cycles tied to grain commodity margins. Precision agriculture technology segments expand fastest as ISOBUS-compatible implements and real-time yield mapping retrofit existing tractor fleets. Conventional technology remains structurally dominant in emerging markets where total cost of ownership governs procurement decisions.
The EPA enforces Tier 4 Final emissions standards that shape engine-tractor-implement integration requirements in US markets, while the EU F-Gas Regulation constrains refrigerant choices in climate-controlled transport linked to harvest logistics. India's CEA and state agricultural departments coordinate subsidized hiring centers that standardize implement specifications across fragmented landholdings. Stakeholders must monitor how carbon border adjustment mechanisms and soil carbon certification programs recalibrate equipment depreciation schedules and financing terms.
Market Dynamics
Precision agriculture platforms are modularizing implement connectivity, forcing manufacturers to choose between proprietary ecosystem lock-in and ISOBUS interoperability standards that commoditize hardware margins.
Growth Catalysts
- EU Green Deal subsidy reform:Decoupling payments from tillage intensity redirects capital toward reduced-disturbance implements across European arable operations.
- Brazilian commercial farm expansion:Large-scale operators in Mato Grosso and Goiás states are mechanizing acreage under tighter environmental compliance mandates.
- India CEA hiring center scale-up:State agricultural departments are standardizing implement specifications through subsidized rental facilities in the wheat-rice belt.
Market Restraints
- Hardened alloy steel input volatility:Cutting edge material costs fluctuate with nickel and boron supply concentration in Indonesian and Russian mining operations.
- Tier 4 Final integration complexity:EPA emissions standards force engine-tractor-implement architectural coordination that extends development cycles for US-market equipment.
- Used equipment substitution:Refurbished harvester availability from North American fleet rotations competes with new capital sales in Eastern European markets.
Strategic Opportunities
- Soil carbon certification programs:Emerging verification frameworks in Australia and Canada create financing-linked equipment depreciation schedules for conservation tillage tools.
- Real-time yield mapping retrofit:ISOBUS-compatible sensor packages penetrate existing tractor fleets without full platform replacement.
- Telematics-enabled rental channels:Usage-based contracting models reduce total cost of ownership barriers for smallholder access in fragmented landholding structures.
Industry Challenges
- ISOBUS firmware integration:Legacy controller area network protocols conflict with unified communication standards across mixed-vendor fleets.
- Hydraulic depth calibration skill gaps:Field service technician shortages delay precision implement commissioning in remote growing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Implements Market |
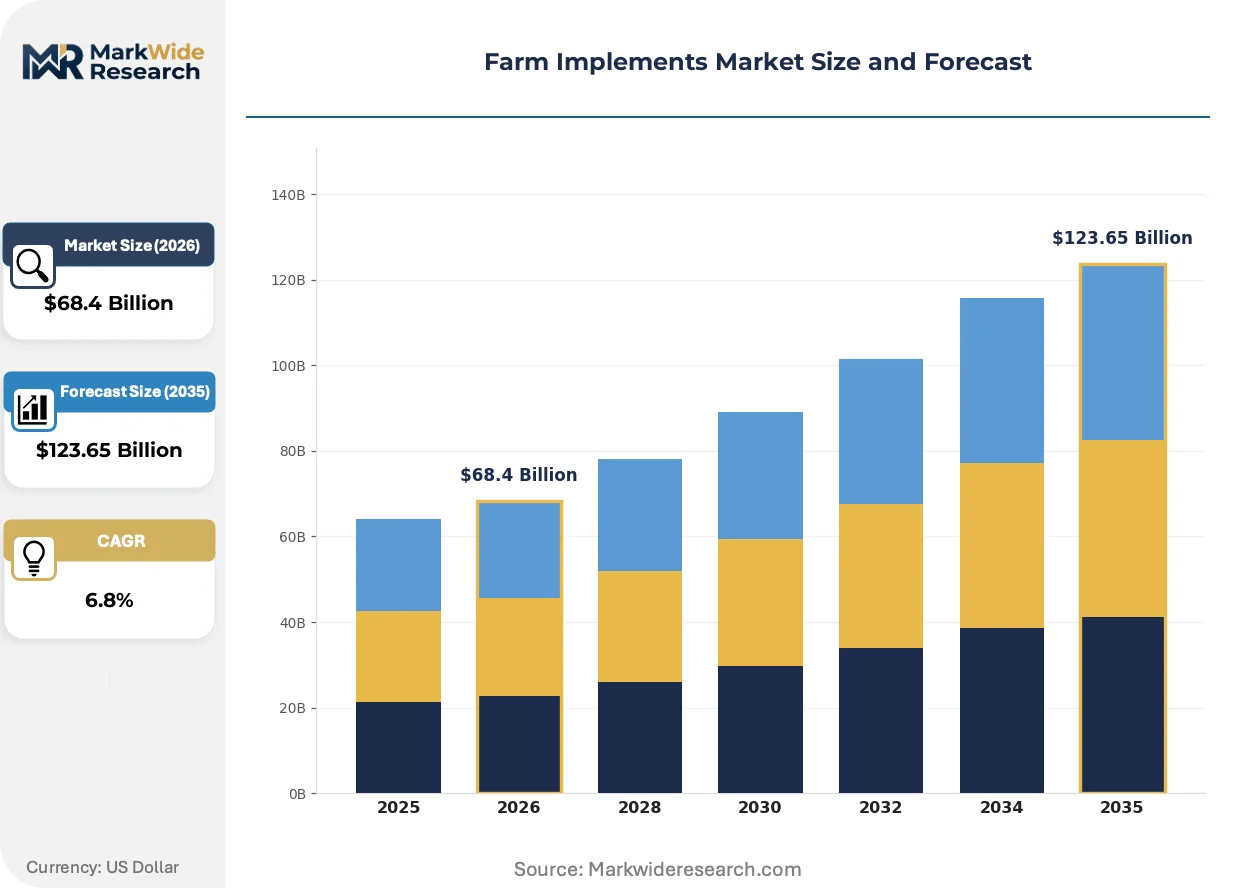
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tillers, Plows, Harvesters, Seeder Technology: Conventional, Precision Agriculture, Autonomous, Digital End User: Farms, Contractors, Agricultural Cooperatives, Government Agencies Distribution Channel: Direct Sales, Retailers, Online Platforms, Distributors |
| Companies Covered | Deere & Company, CNH Industrial, AGCO Corporation, CLAAS KGaA mbH, Kubota Corporation, Mahindra & Mahindra Limited, SDF S.p.A., Kuhn Group, Alamo Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Implements Market Emerging Trajectories
Implement architecture is fragmenting between closed precision ecosystems and open interoperability standards, with connectivity choices now determining long-term parts revenue and customer switching costs.
Electro-hydraulic implement control systems are modularizing precision agriculture hardware, enabling plug-and-play sensor integration across tractor brands. Large-scale row-crop operators in the US Corn Belt are retrofitting existing fleets with ISOBUS-compatible toolbars at accelerating pace. This modularity is compressing equipment replacement cycles while expanding aftermarket software subscription attach rates.
The EU F-Gas Regulation constrains refrigerant selections in climate-controlled grain transport and harvest logistics infrastructure. Equipment manufacturers must revalidate thermal management systems across refrigerated trailer and combine harvester cab specifications. European arable contractors face compliance-driven equipment refresh timelines that accelerate capital deployment into compliant fleets.
Smallholder cooperatives in India are aggregating demand through state-subsidized hiring centers that specify standardized implement widths and hitch configurations. Equipment lessors are unbundling maintenance from capital costs through hourly-use contracts. This procurement restructuring concentrates specification-setting power with agricultural department procurement officers rather than individual farm owners.
Farm Implements Market Segmentation
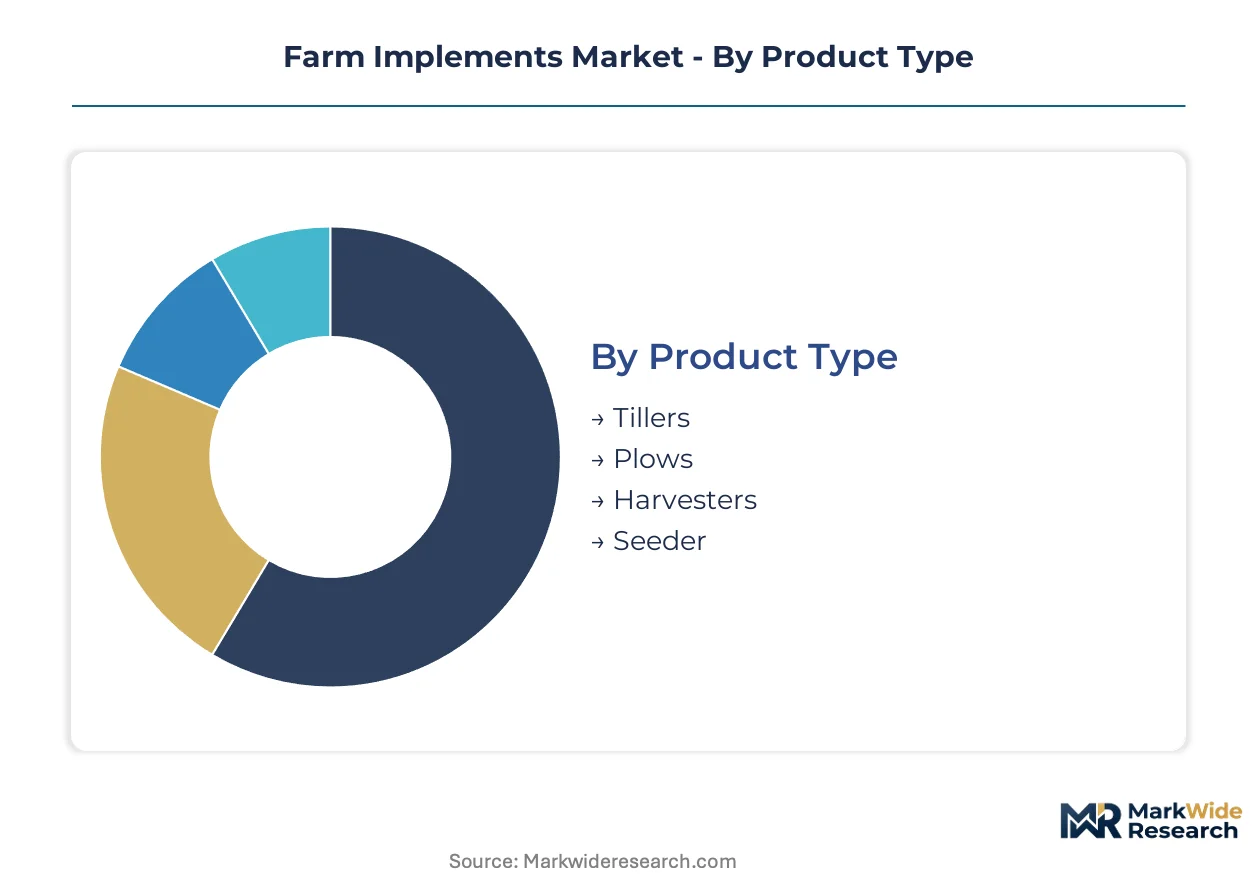
Farm implements serve divergent operational scales from smallholder cooperatives to commercial arable contractors, requiring equipment specifications that match labor availability, field sizes, and subsidy eligibility rules. Segmentation reveals how technology tiers and procurement channels stratify across mechanization maturity levels.
Product Type:
Capital intensity and replacement cycles separate buyers seeking long-life soil preparation tools from those prioritizing seasonal throughput maximization.
- Harvesters:Self-propelled combines and forage harvesters integrate threshing, cleaning, and grain handling in single-pass systems. Demand clusters in Brazil's Mato Grosso soy belt and the US Corn Belt where 24-hour harvest windows justify premium capital deployment.
- Plows:Moldboard and disc plows feature hardened alloy steel cutting edges rated for abrasive soil conditions. EU Green Deal subsidy reform is redirecting procurement toward reduced-disturbance variants across French and German arable operations.
- Tillers:Rotary and power tillers address seedbed preparation in fragmented landholdings. India's CEA-subsidized hiring centers standardize compact tiller specifications for wheat-rice belt smallholders.
- Seeder:Precision seeding equipment with hydraulic depth control achieves uniform emergence in variable moisture conditions. No-till drill adoption is climbing fastest in Australian conservation agriculture programs.
Volume sits with harvesters; growth tilts toward precision seeders.
Technology:
Marginal cost per hectare and operator skill requirements determine whether buyers retrofit existing fleets or adopt integrated platforms.
- Precision Agriculture:ISOBUS-compatible implements with real-time yield mapping and variable-rate application retrofit onto standard tractor hydraulic systems. US Corn Belt operators are retrofitting toolbars at accelerating pace to compress replacement cycles.
- Conventional:Mechanically controlled implements without sensor integration dominate procurement in emerging markets where total cost of ownership governs capital decisions. Brazilian commercial farms in Goiás state still specify conventional plows for primary tillage operations.
- Autonomous:GPS-guided tractors with implement-mounted perception systems enable unmanned field operations during extended working windows. Regulatory frameworks in Australia and Canada are piloting liability protocols for unsupervised machinery.
- Digital:Cloud-connected implements transmit agronomic data to farm management software platforms. European arable contractors face EU F-Gas Regulation compliance timelines that accelerate digital fleet monitoring adoption.
Conventional systems still dominate unit shipments; precision agriculture platforms are gaining share fastest.
End User:
Balance sheet capacity and subsidy access shape whether procurement concentrates capital ownership or spreads equipment via rental structures.
- Farms:Owner-operators prioritize depreciation schedules matched to commodity price cycles. Large-scale Brazilian operators in Mato Grosso mechanize acreage under tighter environmental compliance mandates.
- Contractors:Custom hire businesses require rapid implement swap capability across diverse crop rotations. EU arable contractors face equipment refresh timelines driven by F-Gas refrigerant compliance.
- Agricultural Cooperatives:Member-owned entities aggregate purchasing power for seasonal equipment peaks. Indian smallholder cooperatives are aggregating demand through state-subsidized hiring centers.
- Government Agencies:Public procurement officers set standardized specifications for rental facility networks. India's state agricultural departments specify implement widths and hitch configurations for CEA hiring centers.
Farms account for the largest installed base; government agency procurement is expanding most quickly.
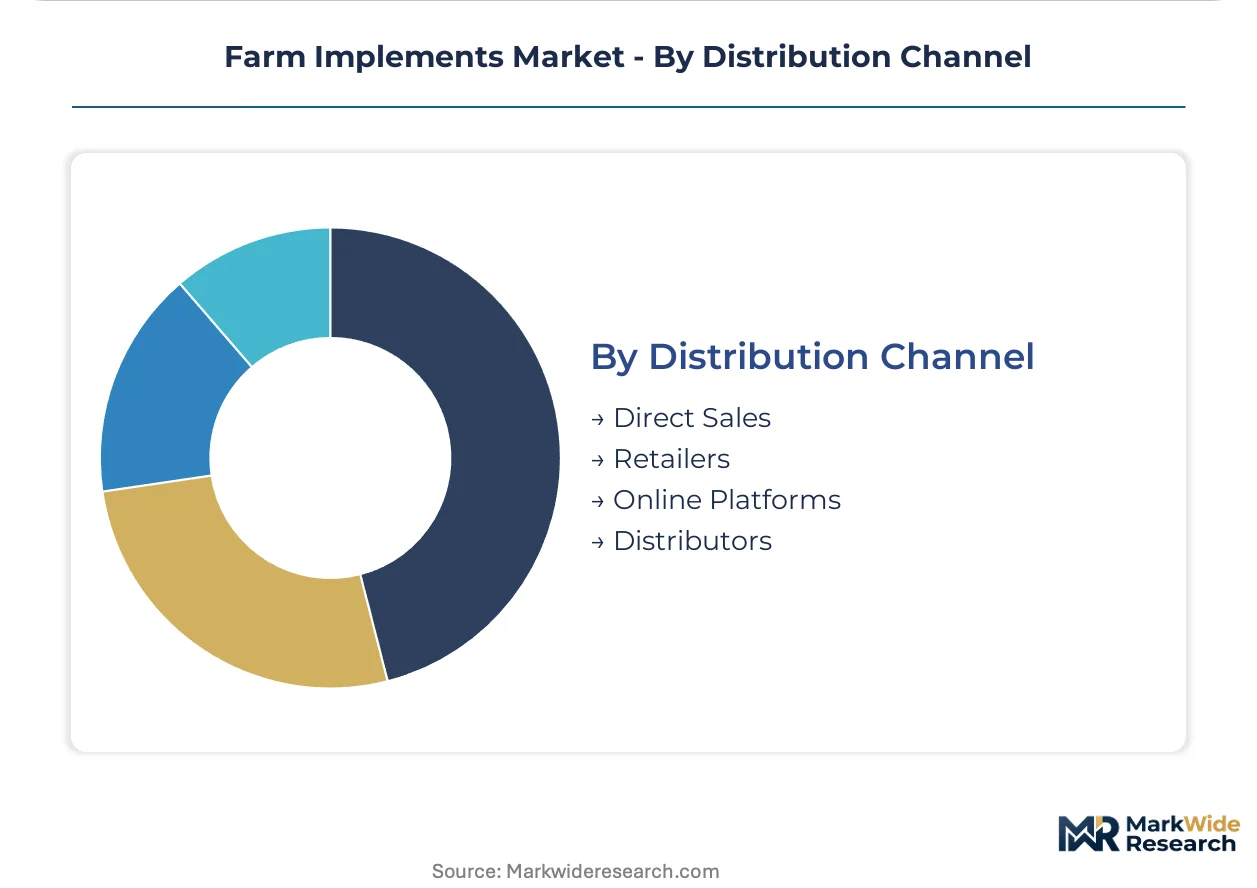
Distribution Channel:
Service integration requirements and financing availability determine whether buyers transact directly with manufacturers or through intermediary networks.
- Distributors:Regional stocking dealers provide field service technician networks for hydraulic depth calibration and warranty claims. Eastern European markets rely on distributor networks for refurbished harvester availability.
- Direct Sales:Manufacturer-owned sales engineers configure integrated tractor-implement systems for large fleet operators. Deere and CNH Industrial deploy direct teams for North American row-crop accounts.
- Retailers:Agricultural supply stores stock consumable wear parts and compact implements for immediate replacement needs. India's rural retail channels supply tiller blades and plow shares in wheat-rice belt districts.
- Online Platforms:Digital marketplaces enable price transparency and specification comparison for standard implements. Telematics-enabled rental channels are emerging for usage-based contracting models.
Distributors handle the highest transaction volume; online platforms are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in Germany and Italy while consumption surges across Brazil and India. The United States maintains integrated production for precision agriculture platforms. Regulatory divergence between EPA Tier 4 Final and EU Green Deal subsidy rules fragments equipment specification requirements.
United States
Large-scale row-crop operators in the Corn Belt drive demand for high-horsepower harvesters and precision seeding equipment. The EPA enforces Tier 4 Final emissions standards that force engine-tractor-implement architectural coordination. Deere & Company anchors its precision agriculture platform development in Illinois and Iowa field service networks.
Brazil
Commercial farms in Mato Grosso and Goiás states mechanize soy and corn acreage under tighter environmental compliance mandates. ANVISA and federal environmental agencies coordinate equipment certification with deforestation monitoring requirements. Regional manufacturing clusters in São Paulo state supply conventional tillage implements for domestic and Mercosur markets.
Germany
EU Green Deal subsidy reform redirects capital toward reduced-disturbance implements across Bavarian and North Rhine-Westphalian arable operations. The F-Gas Regulation constrains refrigerant choices in climate-controlled harvest logistics. CLAAS KGaA mbH maintains driveline integration facilities in Harsewinkel serving European contractor fleets.
India
State governments scale rental hiring centers for wheat-rice belt smallholders in Punjab, Haryana, and Uttar Pradesh. The CEA coordinates subsidized procurement that standardizes compact tiller and power weeder specifications. Mahindra & Mahindra Limited fabricates implements at Maharashtra plants for domestic distribution and African export markets.
Italy
Specialized manufacturers in Emilia-Romagna and Lombardy produce precision seeders and vineyard equipment for Mediterranean cropping systems. REACH compliance and CE marking requirements govern hydraulic system certifications. SDF S.p.A. and Kuhn Group anchor European tillage and hay tool production in the Po Valley industrial corridor.
Farm Implements Market Vendor Landscape
The competitive structure tilts toward diversified machinery conglomerates with captive distribution networks. Tier 1 players integrate precision agriculture software with implement hardware to lock in recurring revenue streams. Mid-tier specialists compete on regional service density and crop-specific tooling expertise. Dominant competitive moves include ISOBUS interoperability certification races and telematics-enabled rental channel partnerships.
Within the diversified machinery tier, Deere & Company and CNH Industrial occupy positions defined by precision agriculture platform integration and manufacturing scale across multiple continents. AGCO Corporation exemplifies the premium-tier European specialist archetype through Fendt-brand positioning. Among Asia-Pacific fabricators, Kubota Corporation and Mahindra & Mahindra Limited represent scale-driven regional champions with emerging export ambitions.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO Corporation |
| CLAAS KGaA mbH |
| Kubota Corporation |
| Mahindra & Mahindra Limited |
| SDF S.p.A. |
| Kuhn Group |
| Alamo Group Inc. |
| Others |
Supply Flow & Price Mechanics
Electro-hydraulic implement control systems are modularizing precision agriculture hardware, simultaneously compressing equipment replacement cycles and concentrating specification-setting power with large fleet operators who can amortize connectivity investments across multiple tractor brands. This technology transition feeds back into supply chain restructuring as manufacturers reallocate capacity toward ISOBUS-compatible controller production and away from mechanically controlled legacy lines.
Pricing Analysis
Margin tightening in precision agriculture tiers reflects the commoditization pressure from open interoperability standards that erode proprietary ecosystem premiums. Three-tier pricing structure across premium, standard, and economy levels separates ISOBUS-certified precision platforms from conventional mechanically controlled implements and refurbished harvester alternatives. Cost-down pressure on conventional equipment accelerates because Brazilian and Indian procurement officers prioritize total cost of ownership metrics over technology bundling. Smallholder cooperatives accessing state-subsidized hiring centers exhibit highest price sensitivity; large-scale Mato Grosso operators demonstrate lowest sensitivity due to depreciation schedule optimization against commodity price cycles.
Supply Chain Analysis
Dual-sourcing requirements for hardened alloy steel cutting edges now mandate supplier qualification across Indonesian nickel operations and Russian boron mining regions to mitigate concentration risk. Manufacturing draws from Germany, Italy, and Brazil for final assembly, with precision controller fabrication anchored in Taiwan and South Korea. Supply chain risk centers on logistics chokepoints affecting hydraulic system component delivery from Emilia-Romagna clusters to Mercosur assembly plants. Distribution runs through regional stocking dealers who maintain field service technician networks for warranty calibration and aftermarket parts fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The farm implements sector is navigating a technology-transition phase where ISOBUS interoperability standards are displacing proprietary precision ecosystems as the dominant connectivity architecture. This shift reconfigures competitive moats from hardware integration toward software subscription attach rates and telematics-enabled service contracts.
For Market Incumbents: Deploy precision agriculture platform lock-in strategies to defend against open-standard commoditization. Anchor recurring revenue through real-time yield mapping software subscriptions that retrofit onto mixed-vendor fleets. Deepen backward integration into electro-hydraulic controller production to preserve margin on ISOBUS-compatible implement sales. Channel control through captive dealer networks for Tier 4 Final compliance calibration services protects against independent service provider encroachment.
For New Entrants and Emerging Players: Launch via telematics-enabled rental channels that unbundle maintenance from capital costs for smallholder cooperatives in India's wheat-rice belt. Target government agency procurement officers who specify standardized implement widths for CEA-subsidized hiring centers as the most penetrable buyer archetype. White-space exists in soil carbon certification-linked equipment financing for Australian and Canadian conservation tillage programs. Direct-to-cooperative sales models bypass established distributor networks that incumbent conglomerates control.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision agriculture software specialists with ISOBUS certification assets and established retrofit installation networks. Long-term viability over the projection horizon favors targets with telematics subscription revenue exceeding hardware replacement cycle dependency. Acquisition target archetype: mid-tier regional manufacturers with crop-specific tooling expertise and underserved service density in Eastern European or Southeast Asian markets. Watch carbon border adjustment mechanism implementation timelines as the inflection signal that would accelerate conservation tillage equipment depreciation schedule revisions and associated financing product demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISOBUS Interoperability Certification | Opens precision agriculture retrofit sales across Deere, CNH Industrial, and AGCO tractor fleets without platform replacement. |
| Telematics-Enabled Rental Channel Partnership | Reduces total cost of ownership barriers for Indian smallholder cooperatives accessing CEA-subsidized hiring centers. |
| Backward Integration into Controller Production | Secures margin on electro-hydraulic implement systems as hardware commoditization accelerates under open standards. |
| Soil Carbon Certification Program Alignment | Links equipment depreciation schedules to emerging Australian and Canadian conservation agriculture verification frameworks. |
| Tier 4 Final Compliance Service Network Expansion | Captures EPA-mandated engine-tractor-implement calibration demand from US Corn Belt fleet operators. |
Methodological Framework
Document review covered customs and trade data from Brazil and India, EU Green Deal implementation guidance, EPA Tier 4 Final technical documentation, and SEC filings from diversified machinery conglomerates, complemented by interviews with precision agriculture platform engineers, agricultural cooperative procurement managers, CEA hiring center operators, OEM aftermarket service heads, and Brazilian commercial farm operations directors. Secondary validation drew from ANVISA equipment certification records, F-Gas Regulation compliance databases, and Mahindra & Mahindra distribution network disclosures. Bottom-up equipment shipment analysis triangulated against top-down agricultural mechanization expenditure estimates across the analysis window.
Cross-referencing historical replacement cycle patterns with panel input from fleet operators and contractor associations shaped the analytical framework. Segmentation modeling incorporated product type, technology tier, end-user archetype, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from installed base growth projections, commodity price cycle correlation analysis, and subsidy program budget trajectories. Industry-specific forecast inputs included ISOBUS adoption penetration curves and soil carbon certification program rollout timelines.
Commodity price volatility, subsidy program budget reallocations, and carbon border adjustment mechanism implementation delays are the dominant revision risks that could materially alter equipment procurement trajectories. Deviation in nickel and boron supply concentration from Indonesian and Russian mining operations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Farm Tire Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Smart Rice Transplanter Market