
 Bean Harvester Market | 2026-2036
Bean Harvester Market Size, Share, and Industry Trends Forecast 2026-2036
Bean Harvester Market Insights
The gap between premium automated systems and commodity mechanized harvesters is broadening as OEMs layer GPS navigation and smart sensors onto flagship platforms while entry lines strip features to hit price points. Grimme Gruppe leverages its European manufacturing base to sustain precision engineering margins on multi-crop configurations. Oxbo International Corporation anchors North American demand through deep dealership networks in pulse-growing regions. Weremczuk Agromachines differentiates by specializing in compact units tailored to Eastern European smallholder plot sizes.
A bean harvester is a purpose-built agricultural machine that threshes, cleans, and collects dry beans through a combination of cutter bars, shakers, and air separation systems operating at ground speeds of four to eight kilometers per hour. Mechanized harvesters with hydraulic systems remain the volume backbone across commercial farms, though margin pools are migrating toward automated systems integrating electric drives and real-time loss monitoring via smart sensors. The technology dimension reveals GPS navigation as the fastest-adopting layer, driven by contractor fleets seeking row-traceability for precision agriculture compliance.
EPA Tier 4 Final regulations in the United States and EU Stage V emission frameworks in Europe are forcing diesel engine redesigns and accelerating electric drive pilot programs. Brazil's national agricultural regulator and India's Central Pollution Control Board are tightening localized emission and safety certifications, raising compliance costs for imported equipment. Stakeholders must monitor how rapidly evolving battery energy density and rural charging infrastructure reshape the total cost of ownership calculus for fleet replacement decisions.
Market Dynamics
Electrified drivetrain architectures are forcing diesel-dependent OEMs to redesign power systems while commercial farms in Brazil compress replacement cycles to secure harvest capacity during narrowing seasonal windows.
Growth Catalysts
- EPA Tier 4 Final mandates:US emission regulations are accelerating electric drive pilot programs among OEMs seeking compliance through zero-emission alternatives.
- Contractor fleet GPS adoption:Precision agriculture compliance requirements are pulling row-traceability systems into mainstream equipment specifications.
- Brazil's Cerrado concentration:Large-scale soybean and dry bean operations are consolidating demand around high-capacity self-propelled machines.
Market Restraints
- Battery energy density limitations:Current lithium-ion configurations cannot sustain full-day harvesting cycles without mid-day charging interruptions.
- Rural charging infrastructure gaps:Grid extension lags in agricultural corridors of Brazil's interior and India's northern plains.
- Import certification costs:Brazil's national agricultural regulator and India's Central Pollution Control Board are layering localized safety and emission testing requirements.
Strategic Opportunities
- Eastern European smallholder plots:Compact unit configurations tailored to sub-50 hectare operations remain underserved by standard commercial platforms.
- Real-time loss monitoring convergence:Smart sensor integration with telematics is automating yield optimization feedback loops for precision agriculture compliance.
- EU Stage V framework:European emission standards are creating regulatory tailwinds for electric drive retrofits and new platform development.
Industry Challenges
- Hydraulic technician scarcity:Maintenance networks lack trained personnel for hybrid electric-hydraulic system diagnostics.
- Legacy fleet integration friction:GPS navigation retrofits face compatibility barriers with 10-15 year old mechanical control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bean Harvester Market |
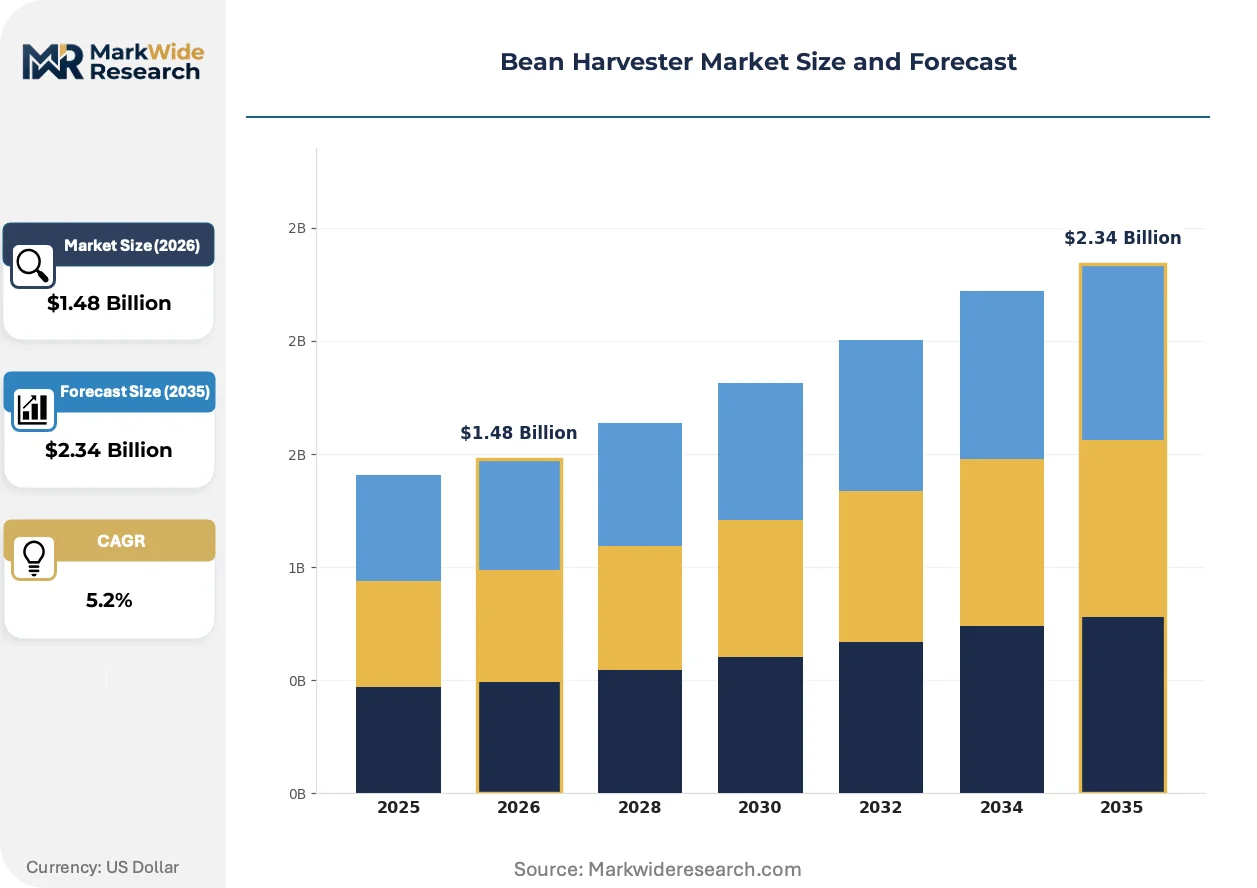
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.34 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Harvesters, Mechanized Harvesters, Automated Systems, Multi-Crop Harvesters End User: Smallholder Farmers, Commercial Farms, Co-operatives, Agricultural Contractors Technology: Hydraulic Systems, Electric Drives, GPS Navigation, Smart Sensors Distribution Channel: Direct Sales, Online Retail, Dealerships, Agricultural Shows |
| Companies Covered | Oxbo International Corporation, Ploeger Oxbo Group, Grimme Gruppe, ASA-LIFT, Fontana Macchine S.r.l., Hanseo Precision, Weremczuk Agromachines, ITN Group, Atelier 3T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bean Harvester Market Trends and Innovations
Smart sensor layers are compressing the performance gap between flagship automated platforms and stripped entry-level machines, while regulatory emission frameworks force parallel development tracks across diesel optimization and electric transition.
Real-time loss monitoring via optical sensors and acoustic signature analysis is automating threshing parameter adjustments during field operation. Large contractor fleets in Brazil's Mato Grosso and Goiás states are adopting these systems at the fastest clip. The technology is automating yield recovery rates that previously required manual operator intervention every 15-20 minutes.
EPA Tier 4 Final regulations in the United States are mandating diesel particulate filter and selective catalytic reduction systems that add weight and complexity to self-propelled platforms. OEM engineering teams are splitting R&D budgets between compliance-optimized diesel architectures and battery-electric prototypes. The US market is responding with extended equipment financing terms to absorb upfront cost premiums.
After-sales service unbundling is fragmenting traditional dealer revenue models as fleet operators source hydraulic components and sensor modules through direct manufacturer portals. North American pulse-growing regions are seeing the fastest channel disintermediation. Equipment buyers in Canada's prairie provinces and the US northern tier are negotiating stripped maintenance contracts that exclude proprietary electronic diagnostics.
Bean Harvester Market Segmentation
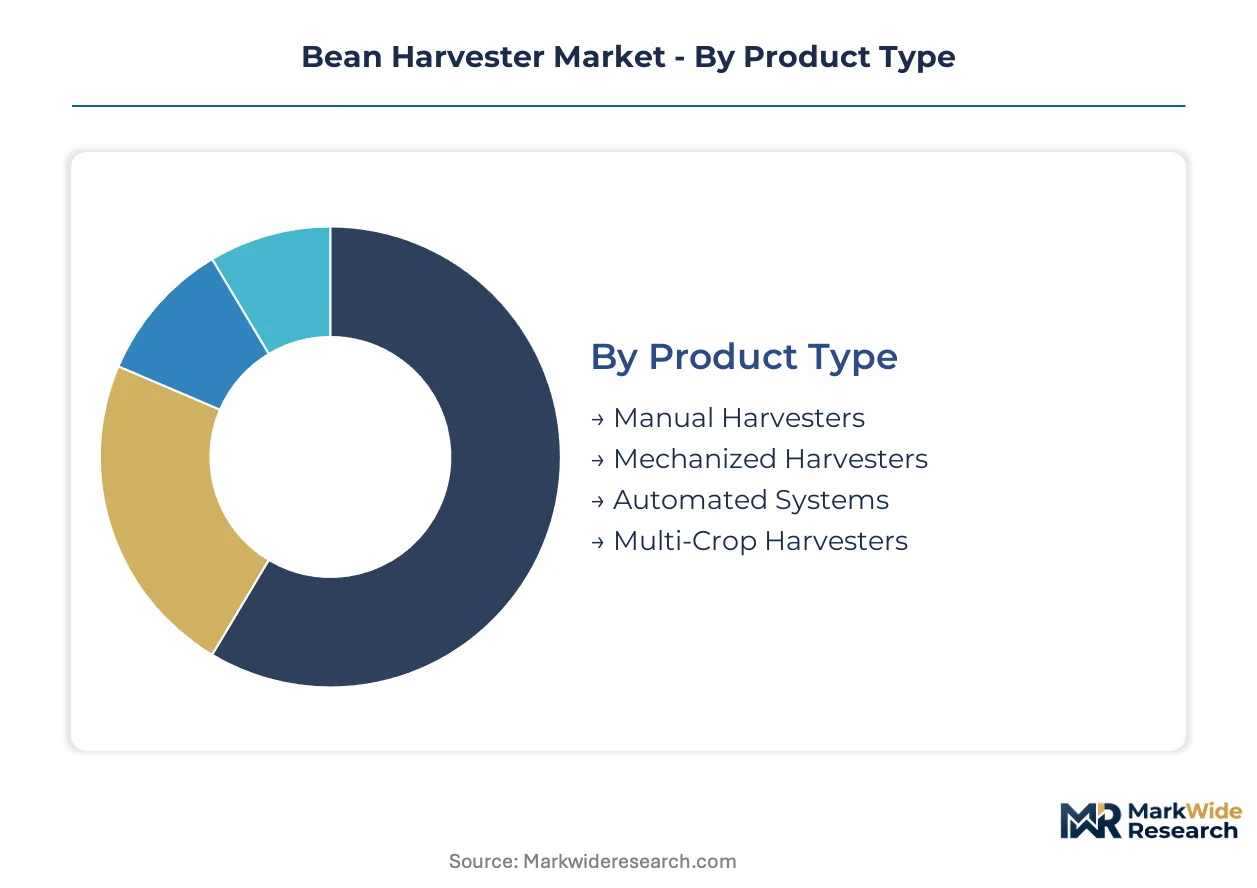
Bean harvester segmentation reveals how technology tiers, operator scale, and procurement channels fragment demand across radically different farm economics. Equipment specifications diverge sharply between Brazil's thousand-hectare operations and Eastern European smallholders, forcing OEMs to maintain parallel product architectures.
Product Type:
Mechanization intensity separates commodity grain regions from specialty crop zones, with powertrain architecture as the primary cost differentiator.
- Mechanized Harvesters:Diesel-hydraulic platforms dominate commercial acreage through proven threshing reliability and established service networks. Brazil's Mato Grosso contractors specify these units for 16-hour daily duty cycles during compressed harvest windows.
- Automated Systems:Electric drivetrains with integrated GPS guidance and real-time loss monitoring command premium positioning. EPA Tier 4 Final compliance costs accelerate fleet interest in zero-emission alternatives for California's Central Valley and EU Stage V corridors.
- Manual Harvesters:Hand-operated cutter bars persist in hillside terrain and organic certification programs where mechanized compaction risks crop damage.
- Multi-Crop Harvesters:Modular header configurations adapt between dry beans, soybeans, and small grains for diversified rotation schemes.
Mature deployment sits with mechanized harvesters. Newer deployment is concentrated in automated systems.
End User:
Farm scale determines equipment specification, financing access, and technology adoption velocity across procurement decisions.
- Commercial Farms:Self-propelled platforms with 12-meter cutter bars and grain tank capacities exceeding 10,000 liters anchor fleet specifications. Brazil's Cerrado consolidation drives replacement cycles toward 3-5 year intervals to secure harvest capacity.
- Agricultural Contractors:GPS-enabled row-traceability systems satisfy precision agriculture compliance mandates from grain elevators and export certification bodies. Mato Grosso and Goiás fleets adopt real-time loss monitoring at the fastest clip.
- Co-operatives:Shared ownership models spread capital burden across member farms, though scheduling conflicts emerge during synchronous regional maturity.
- Smallholder Farmers:Sub-50 hectare operations in Eastern Europe and India's northern plains rely on compact tractor-mounted units or manual methods.
Volume concentrates with commercial farms. Technology migration accelerates among agricultural contractors.
Technology:
Powertrain architecture and sensor integration define performance tiers and regulatory compliance pathways.
- GPS Navigation:RTK-corrected guidance enables sub-2.5 centimeter row-traceability for precision agriculture compliance. Contractor fleets in Brazil and the US Midwest specify these systems as baseline equipment.
- Electric Drives:Battery-electric prototypes from OEM engineering programs target EPA Tier 4 Final and EU Stage V emission frameworks. Current lithium-ion configurations face range limitations for full-day harvesting cycles.
- Hydraulic Systems:Proven lift, steering, and threshing mechanisms remain the volume backbone across commercial platforms.
- Smart Sensors:Optical and acoustic loss detection automates threshing parameter adjustments without operator intervention.
Installed base dominance rests with hydraulic systems. Steepest expansion trajectory belongs to GPS navigation.
Distribution Channel:
Procurement channel selection reflects equipment complexity, financing requirements, and aftermarket service dependencies.
- Dealerships:Full-service networks dominate commercial farm and contractor procurement through bundled financing, warranty coverage, and seasonal maintenance scheduling. Oxbo International Corporation anchors North American pulse regions through this channel.
- Direct Sales:Large fleet operators negotiate manufacturer-direct contracts for standardized equipment specifications across multi-state operations.
- Agricultural Shows:Demo events in Brazil's Ribeirão Preto and India's Punjab concentrate seasonal purchasing decisions with immediate delivery terms.
- Online Retail:Spare parts and consumable procurement migrates to manufacturer portals, though complete machine sales remain minimal.
Transaction volume flows through dealerships. Channel disintermediation pressure mounts in direct sales and online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ribeirão Preto anchors the world's most concentrated bean harvester demand corridor, with contractor fleets in São Paulo state's northern reaches compressing replacement cycles to secure harvest capacity during narrowing seasonal windows.
United States
California's Central Valley and the northern tier of Midwestern pulse-growing regions drive specification demand for EPA Tier 4 Final-compliant platforms. The Environmental Protection Agency's emission mandates accelerate electric drive pilot programs among OEM engineering teams. Equipment financing terms extend to absorb upfront cost premiums in Iowa and Minnesota contractor networks.
Brazil
Mato Grosso and Goiás states consolidate demand around high-capacity self-propelled machines with 12-meter cutter bars. ANVISA, Brazil's national health regulator, and the national agricultural regulator tighten localized safety certifications for imported equipment. Ribeirão Preto's machinery corridor hosts the densest contractor fleet concentration, with real-time loss monitoring adoption accelerating fastest among these operators.
Germany
EU Stage V emission frameworks force parallel development tracks across diesel optimization and electric transition for machinery serving Eastern European export markets. The European Commission's F-Gas Regulation and machinery directives reshape powertrain architecture requirements. Baden-Württemberg's precision engineering clusters sustain multi-crop configuration margins for OEMs targeting diversified rotation schemes.
India
Punjab and Haryana's northern plains concentrate demand for compact tractor-mounted units suited to sub-50 hectare smallholder operations. The Central Pollution Control Board layers localized emission testing requirements on imported agricultural equipment. Agricultural shows in Ludhiana concentrate seasonal purchasing decisions with immediate delivery terms for domestic fabricators.
Poland
Eastern European smallholder plot sizes below 50 hectares sustain demand for compact unit configurations underserved by standard commercial platforms. EU machinery directives and national agricultural safety standards raise compliance costs for Western European imports. Weremczuk Agromachines anchors regional supply from its Polish manufacturing base, specializing in plot-size-appropriate specifications.
Bean Harvester Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration intensity, with automated systems commanding positioning premiums while mechanized platforms compete on service network density and financing terms. The vendor base stratifies into three tiers: flagship platform specialists layering GPS navigation and smart sensors, multi-crop configuration generalists sustaining engineering margins through modular header systems, and compact unit fabricators targeting smallholder economics. Consolidation pressure concentrates among mid-scale European specialists seeking scale to fund electrification R&D. Geographic expansion into Brazil's Cerrado and channel disintermediation through direct manufacturer portals represent the dominant competitive moves reshaping traditional dealership revenue models.
Among European manufacturing specialists, Grimme Gruppe and ASA-LIFT exemplify the precision-engineering archetype, with German and Danish origins respectively signaling multi-crop configuration capabilities. Weremczuk Agromachines occupies the compact-specialist position, its Polish base anchoring Eastern European smallholder demand. Oxbo International Corporation represents the North American dealership-network archetype, with its corporate structure indicating deep service infrastructure in pulse-growing regions. These three players illustrate how geographic origin and company structure map to distinct strategic positioning vectors without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Oxbo International Corporation |
| Ploeger Oxbo Group |
| Grimme Gruppe |
| ASA-LIFT |
| Fontana Macchine S.r.l. |
| Hanseo Precision |
| Weremczuk Agromachines |
| ITN Group |
| Atelier 3T |
| Others |
Pricing and Supply Chain Analysis
Captive production of precision-engineered cutter bars and hydraulic threshing modules anchors supply positioning for flagship OEMs, while outsourced sensor integration and battery pack procurement compress margins for mid-tier assemblers competing on price.
Pricing Analysis
Throughput-based pricing tied to hectares-per-hour performance anchors equipment valuation, with GPS-enabled contractor fleets in Brazil's Mato Grosso paying premiums for sub-2.5 centimeter row-traceability. Price differentiation separates EPA Tier 4 Final-compliant platforms from stripped entry lines lacking real-time loss monitoring. Cost compression in the mid-tier intensifies because Brazilian and Indian regulators layer localized safety certifications on imported equipment. Smallholder farmers in Poland and India's northern plains exhibit highest price sensitivity, while California Central Valley contractors show lowest sensitivity due to precision agriculture compliance mandates.
Supply Chain Analysis
Refurbishment flows for 10-15 year old mechanical control architectures create secondary parts markets, while remanufactured hydraulic systems extend fleet life in Eastern European co-operatives. Manufacturing concentrates in Germany, Poland, and Brazil, with precision engineering clusters in Baden-Württemberg feeding multi-crop header exports. Supply chains draw from lithium-ion cell producers, high-strength steel fabricators, and optical sensor specialists. Single-source vulnerability sits with RTK-corrected GPS module suppliers serving contractor traceability requirements. Distribution runs through full-service dealership networks in North American pulse regions and Ribeirão Preto machinery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as OEMs pursue captive supply of electric drivetrain components to escape battery pack margin extraction and secure harvest capacity during narrowing seasonal windows.
For Market Incumbents: Anchor service network density in Brazil's Cerrado and North American pulse regions against channel disintermediation pressure from direct manufacturer portals. Invest in backward integration into precision cutter bar production to defend margins from commodity steel price volatility. Prioritize EPA Tier 4 Final and EU Stage V certification pipelines to maintain fleet access in regulated corridors. For New Entrants and Emerging Players: The price-point gap between premium automated systems and stripped mechanized harvesters opens white-space in compact tractor-mounted units for Eastern European sub-50 hectare plots. India's northern plains present the most penetrable geography given Central Pollution Control Board certification barriers that favor domestic fabrication partnerships. Pursue agricultural show demo events in Ludhiana and Ribeirão Preto for immediate delivery terms. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale European specialists seeking scale to fund electrification R&D programs. Long-term viability favors OEMs with parallel diesel optimization and battery-electric development tracks across the analysis window. Target acquisition archetypes include compact-specialist fabricators with Polish or Eastern European manufacturing bases. Monitor lithium-ion energy density breakthroughs and rural charging infrastructure buildout as inflection indicators for fleet replacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drivetrain Development | Battery-electric prototypes target EPA Tier 4 Final and EU Stage V compliance pathways. |
| Precision Sensor Integration | Optical loss detection automates threshing adjustments for Mato Grosso contractor fleets. |
| Compact Unit Specialization | Sub-50 hectare configurations capture Eastern European smallholder demand underserved by standard platforms. |
| Dealership Network Expansion | Full-service coverage anchors procurement in North American pulse-growing regions against disintermediation. |
| Multi-Crop Header Modularity | Modular configurations adapt between dry beans, soybeans, and small grains for diversified rotations. |
Research Methodology
Trade association filings, customs and import records, and agricultural machinery registration databases formed the secondary backbone for this study. Primary interviews with fleet maintenance directors, OEM procurement teams, aftermarket service heads, and agricultural contractor operators were combined with secondary validation. Bottom-up triangulation across equipment shipment data and top-down cross-checks against regional acreage statistics anchored volume estimates.
Historical trendline analysis of replacement cycle compression and technology adoption curves informed the projection framework across the analysis window. Segmentation modeling captured product type tiers, operator scale categories, powertrain architectures, and regional regulatory clusters. CAGRs were derived from fitted growth curves applied to baseline equipment stock and fleet expansion patterns. Forecast inputs incorporated EPA Tier 4 Final compliance timelines and Brazil's ANVISA certification trajectory.
Inputs from OEM engineering disclosures and national agricultural regulator filings were available through the study window; gaps in real-time fleet utilization telemetry introduce uncertainty bands around replacement timing assumptions. Forecasts reflect documented assumptions regarding battery energy density evolution and rural grid extension rates. Practitioners should monitor lithium-ion range improvements and charging infrastructure buildout in Brazil's interior for early signals of electric drivetrain adoption inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Electric Pruning Shears Market