
 Indoor Farming Equipment Market | 2026-2036
Indoor Farming Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Farming Equipment Market Foresight
The Netherlands is reshaping competitive dynamics in indoor farming equipment through concentrated greenhouse technology clusters and export-oriented manufacturing. AeroFarms sustains technology leadership in aeroponic system design with intensive R&D programs. Plenty Unlimited Inc. anchors large-scale vertical farm deployments across multiple North American metropolitan markets. Sananbio dominates LED grow light module production with integrated hardware-software platforms.
Indoor farming equipment encompasses climate-controlled systems, nutrient delivery infrastructure, artificial lighting arrays, and automation hardware engineered to cultivate crops within enclosed environments independent of external weather conditions. These systems typically operate within precise temperature ranges of 18-24°C, humidity bands of 50-70%, and photosynthetic photon flux densities exceeding 200 μmol/m²/s to optimize plant metabolic rates. Hydroponic systems capture the largest installed base among product categories due to proven commercial viability across leafy green operations. LED Lighting technology commands the fastest expansion trajectory as spectral tunability and energy efficiency improvements reduce operational expenditure profiles. Automation Solutions concentrate margin pools through recurring software licensing and predictive maintenance contracts tied to sensor networks.
The EPA regulates agricultural runoff and water recycling standards that directly influence closed-loop system design requirements in the United States. REACH compliance in Europe restricts certain substrate materials and nutrient formulations, compelling equipment manufacturers to reformulate component specifications. China's dual carbon goals and GB standards for agricultural facility energy consumption are redirecting domestic procurement toward low-power LED configurations and heat-recovery ventilation modules. Stakeholders must monitor evolving carbon accounting methodologies for controlled-environment production as these frameworks begin influencing insurance pricing and retail procurement criteria.
Market Dynamics
Capital deployment in indoor farming equipment is compressing around spectral-tunable LED architectures and closed-loop water systems as buyers prioritize opex reduction over upfront hardware costs. The EU Green Deal agricultural sustainability mandates are accelerating this preference shift across commercial greenhouse operators.
Growth Catalysts
- EU Green Deal agricultural mandates:These sustainability requirements are compelling Dutch and German greenhouse operators to retrofit climate-controlled systems with heat-recovery ventilation and water recycling infrastructure.
- China's dual carbon goals:GB standards for agricultural facility energy consumption are redirecting domestic procurement toward low-power LED configurations and modular ventilation systems.
- Aeroponic nutrient delivery:This precision irrigation technology is expanding installed capacity as leafy green producers seek yield density advantages over hydroponic baselines.
Market Restraints
- Phosphor and rare-earth input costs:LED grow light manufacturing faces raw material price volatility concentrated in Chinese mining and processing supply chains.
- REACH substrate restrictions:European chemical compliance is compelling equipment manufacturers to reformulate nutrient formulations and growing media, extending R&D cycles.
- Technical limitation in spectral optimization:Crop-specific light recipes remain empirically derived rather than biologically modeled, slowing adoption in fruiting and flowering applications.
Strategic Opportunities
- Underpenetrated Middle Eastern markets:Saudi Arabia and UAE food security initiatives are creating demand for containerized vertical farming systems in arid climates.
- Regulatory tailwind from US IRA agricultural provisions:Tax incentives for energy-efficient controlled-environment agriculture are lowering effective capex thresholds for domestic growers.
- Convergence of computer vision and climate control:Sensor-fusion platforms integrating spectral imaging with HVAC automation are opening recurring software licensing revenue pools.
Industry Challenges
- Controls engineering talent scarcity:Integration of PLC programming, plant biology, and data analytics expertise remains concentrated in Netherlands and California technology clusters.
- Capex intensity of facility retrofits:Existing greenhouse operators face stranded asset risk when upgrading to fully automated nutrient and lighting systems.
- Certification timeline fragmentation:UL, CE, and China Compulsory Certification requirements for electrical and horticultural equipment vary significantly, complicating product platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Farming Equipment Market |
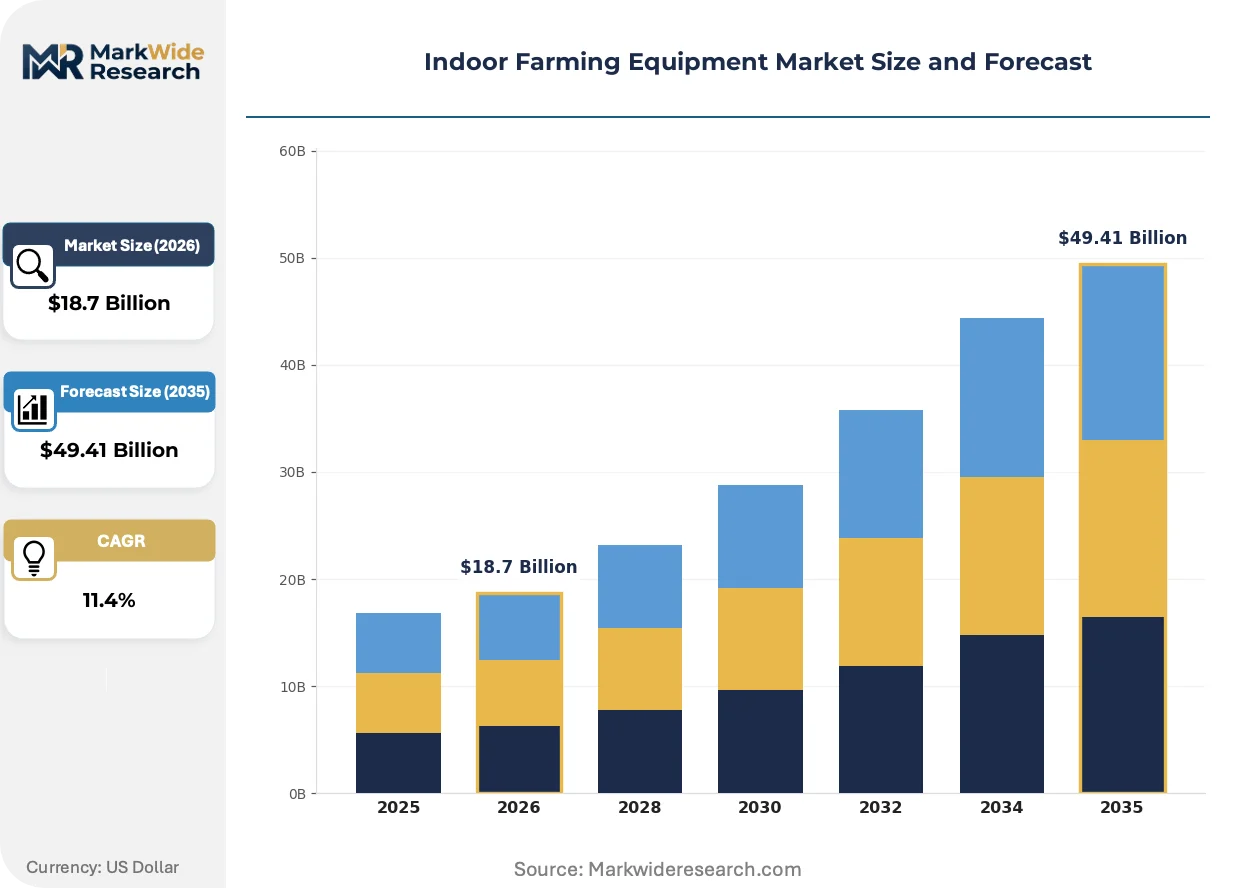
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponic Systems, Aeroponic Systems, Vertical Farms, Grow Lights Technology: LED Lighting, Climate Control, Nutrient Delivery, Automation Solutions End User: Commercial Growers, Research Institutions, Home Gardeners, Urban Farmers Application: Vegetable Production, Fruit Production, Ornamental Plants, Herbs |
| Companies Covered | 80 Acres Farms, YesHealth Group, AeroFarms, 4D Bios Co., Ltd., Sananbio, Bowery Farming, CubicFarm Systems, Elevate Farms, Plenty Unlimited Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Farming Equipment Market Shifts & Advancements
Equipment architecture is pivoting from standalone hardware sales toward integrated hardware-software platforms with predictive maintenance and spectral recipe libraries. This shift is compressing traditional equipment margins while expanding recurring revenue pools.
Spectral-tunable LED arrays are migrating from fixed-spectrum high-pressure sodium replacements to dynamic full-spectrum systems with real-time dimming protocols. Large-scale vertical farm operators in North American metropolitan markets are adopting these systems to optimize photomorphogenic responses across crop growth stages. The technology is migrating from premium-tier installations toward mid-scale commercial greenhouse retrofits as module costs decline.
EPA agricultural runoff regulations and water recycling standards are tightening closed-loop system design requirements in the United States. Equipment manufacturers must now engineer nutrient recovery and zero-discharge capabilities into baseline system specifications. Hydroponic and aeroponic system categories face the most stringent compliance timelines, with California and Florida operators leading adaptation.
Metropolitan grocery retailers are contracting directly with vertical farm operators for year-round leafy green supply, bypassing traditional wholesale produce distribution channels. This disintermediation is concentrating buyer power among a small number of national retail chains. The pattern is most visible in United States and Japanese urban markets where land scarcity and food miles reduction carry premium pricing power.
Indoor Farming Equipment Market Segmentation
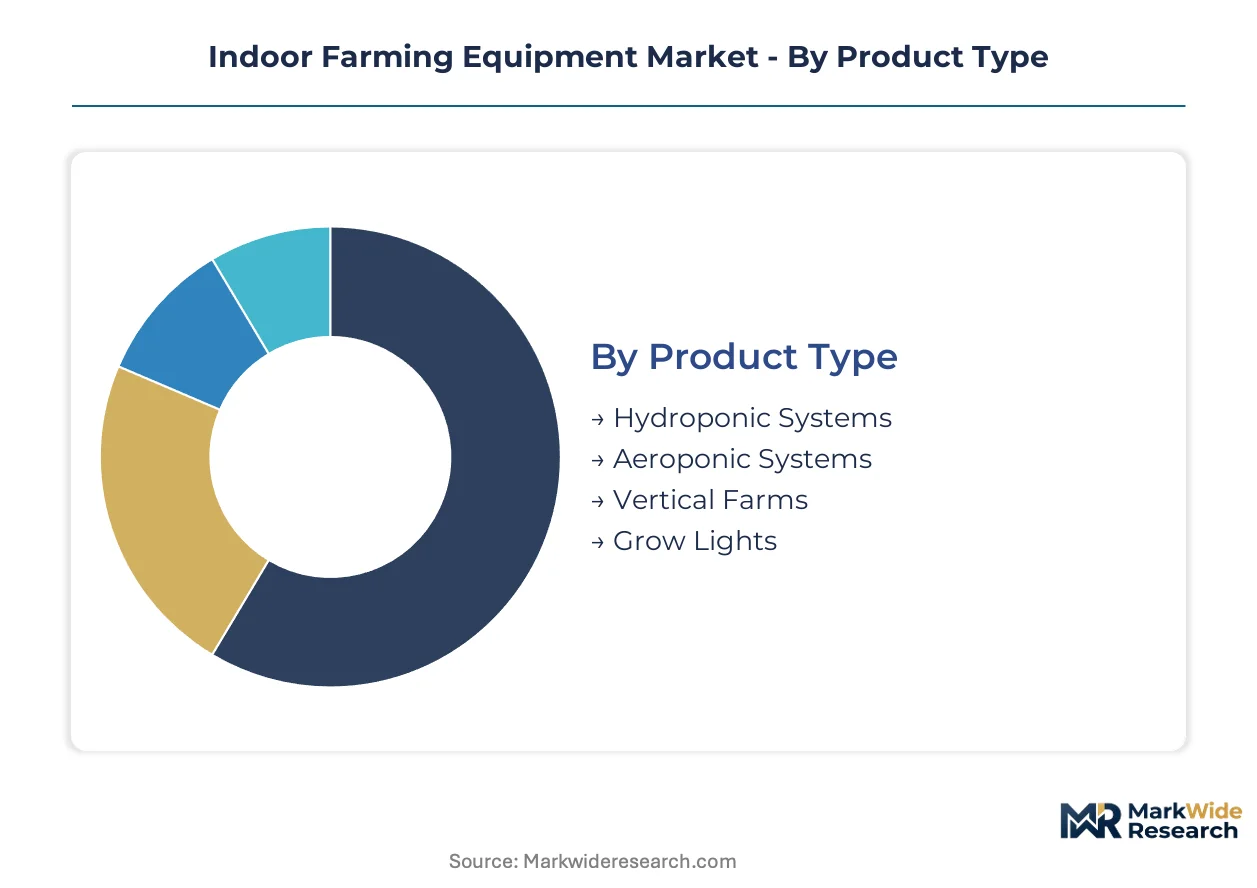
Equipment segmentation in controlled-environment agriculture reflects divergent capital intensity requirements across crop categories and operator scales. Buyers select configurations based on opex reduction priorities, spectral control needs, and regulatory compliance burdens specific to their geography.
Product Type:
Use-case spectrum spans from research-scale modular units to metropolitan vertical farms serving grocery retail contracts.
- Hydroponic Systems:Substrate-based nutrient delivery platforms dominate commercial leafy green operations with proven yield consistency. Demand concentrates among Dutch and Spanish greenhouse operators retrofitting for EU Green Deal water recycling mandates.
- Aeroponic Systems:Mist-based root irrigation achieves highest yield density per square meter through precise oxygenation control. Deployment accelerates in North American metropolitan vertical farms where real estate costs force maximum spatial efficiency.
- Vertical Farms:Stacked cultivation architectures integrate lighting, HVAC, and automation in purpose-built facilities. Containerized variants gain traction in Saudi Arabia and UAE food security programs.
- Grow Lights:Spectral-tunable LED modules replace legacy high-pressure sodium installations across commercial greenhouse retrofits. Chinese manufacturing clusters drive module cost compression.
Established volume favors Hydroponic Systems; emerging adoption favors Aeroponic Systems.
Technology:
Cost tier stratification separates premium integrated platforms from component-level procurement.
- LED Lighting:Phosphor-converted and chip-on-board architectures deliver photosynthetic photon flux densities exceeding 200 μmol/m²/s with dimming protocols. California and Florida operators lead EPA-compliant closed-loop retrofits.
- Climate Control:Heat-recovery ventilation and precision humidity management reduce HVAC energy draw. Dutch greenhouse clusters prioritize these systems for carbon accounting compliance.
- Nutrient Delivery:Closed-loop recirculation with real-time EC/pH monitoring minimizes water consumption. REACH restrictions compel European manufacturers to reformulate substrate materials.
- Automation Solutions:Sensor-fusion platforms with predictive maintenance contracts generate recurring software revenue. Integration requires scarce controls engineering talent concentrated in Netherlands and California.
Margin concentration sits with Automation Solutions; steepest expansion trajectory belongs to LED Lighting.
End User:
Customer type determines procurement scale and service intensity requirements.
- Commercial Growers:Large-scale operators contract directly with metropolitan grocery retailers for year-round supply. These buyers prioritize opex reduction over upfront hardware costs.
- Research Institutions:Universities and agricultural extension services drive spectral recipe development for crop-specific optimization. Their procurement supports empirical validation of biologically modeled light protocols.
- Home Gardeners:Compact countertop and cabinet systems serve hobbyist cultivation with minimal technical support requirements. Distribution runs through e-commerce and specialty retail channels.
- Urban Farmers:Small commercial operators in land-scarce cities balance yield targets against facility lease structures. Tokyo and Singapore host dense clusters of these mid-scale deployments.
Procurement volume concentrates with Commercial Growers; technology validation depends on Research Institutions.
Application:
Maturity gradient separates scientifically validated crop categories from experimentally expanding ones.
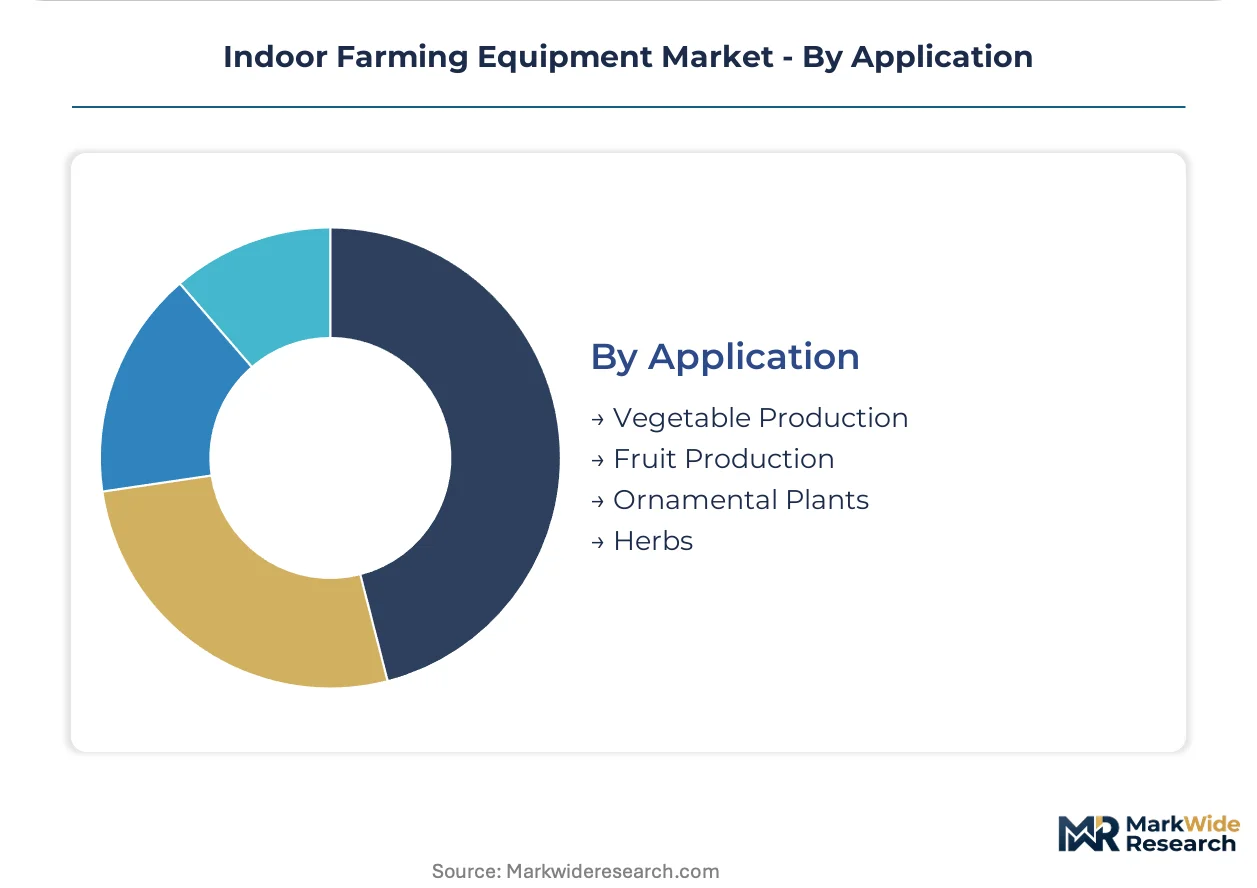
- Vegetable Production:Leafy greens and brassicas dominate installed capacity with established photoperiod protocols. Dutch and Chinese operators capture economies of scale in lettuce and spinach supply.
- Fruit Production:Tomato and strawberry cultivation in controlled environments requires precise VPD management and pollination assistance. Technical limitation in spectral optimization slows adoption versus vegetable baselines.
- Ornamental Plants:Floriculture applications leverage photomorphogenic control for flowering timing and color intensity. Japanese metropolitan markets sustain premium pricing for year-round ornamental supply.
- Herbs:Basil, cilantro, and specialty culinary varieties suit compact vertical farm footprints with rapid harvest cycles. UAE and Saudi Arabia import substitution programs target this category.
Proven commercial viability anchors Vegetable Production; experimental expansion characterizes Fruit Production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Dutch dominance in greenhouse technology exports. California's Central Valley water conveyance systems anchor US vertical farm clustering. China's high-speed rail network connects LED manufacturing hubs to agricultural provinces.
United States
Metropolitan grocery contracts and IRA agricultural tax incentives drive equipment procurement. EPA agricultural runoff standards compel closed-loop water recycling retrofits. California's Salinas Valley and New York's Hudson Valley host dense vertical farm clusters serving retail supply chains.
China
Dual carbon goals and food security mandates redirect capital toward low-power LED configurations. GB standards for agricultural facility energy consumption regulate procurement specifications. Yangtze River Delta manufacturing clusters supply spectral-tunable modules to domestic greenhouse operators.
Netherlands
EU Green Deal sustainability mandates accelerate climate-controlled system retrofits. REACH chemical compliance restricts substrate materials in nutrient delivery systems. Westland greenhouse technology corridor exports integrated automation platforms to German and Belgian operators.
Saudi Arabia
Food security initiatives and arid-climate constraints create demand for containerized vertical systems. The national food security strategy prioritizes import substitution in leafy green categories. Riyadh and NEOM host pilot deployments of fully automated nutrient delivery infrastructure.
Japan
Land scarcity and premium retail pricing sustain metropolitan vertical farm economics. METI agricultural technology subsidies support spectral recipe development for domestic crop varieties. Tokyo and Osaka metropolitan areas concentrate mid-scale urban farming operations.
Indoor Farming Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in LED and climate hardware. The vendor base stratifies between turnkey vertical farm operators and modular equipment suppliers. Three archetypes dominate: spectral-tunable lighting manufacturers, integrated automation platforms, and aeroponic system designers. Consolidation pressure concentrates in automation software licensing; geographic expansion drives capacity deployment in Middle Eastern markets.
Among US-based platform operators, Plenty Unlimited Inc. and AeroFarms occupy positions in the metropolitan supply chain tier. Chinese LED specialists including Sananbio exemplify the component manufacturing archetype. These named entities anchor competitive dynamics without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| 80 Acres Farms |
| YesHealth Group |
| AeroFarms |
| 4D Bios Co., Ltd. |
| Sananbio |
| Bowery Farming |
| CubicFarm Systems |
| Elevate Farms |
| Plenty Unlimited Inc. |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's cold-chain infrastructure cost dynamics amplify pricing power for Dutch greenhouse technology exporters while compressing margins for component importers dependent on Asian LED manufacturing clusters. This corridor's freight cost volatility feeds directly into three-tier pricing stratification across equipment tiers and buyer volume bands.
Pricing Analysis
Volume-discount tiering separates metropolitan vertical farm operators securing project-based bundled pricing from mid-scale greenhouse retrofits procuring component-level hardware. Price differentiation hinges on UL/CE certification grade and after-sales service bundling. Cost compression in standard-tier LED modules is intensifying because Chinese manufacturing overcapacity. Commercial growers with direct grocery retail contracts exhibit lowest price sensitivity; urban farmers in Tokyo and Singapore face highest budget constraints.
Supply Chain Analysis
Extended payment terms from Dutch automation platform vendors now stretch 90-120 days, reflecting working capital pressure from rare-earth phosphor cost volatility. Geographic supply concentration centers on China for LED chip-on-board modules, the Netherlands for integrated climate control systems, and the United States for sensor-fusion automation software. Raw material dependencies include yttrium and cerium phosphors, aluminum substrate materials, and precision HVAC compressors. Single-source vulnerability in Chinese rare-earth processing feeds tariff exposure into European and North American procurement. Distribution runs through OEM-direct contracts for large-scale deployments and specialized horticultural distributors for retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indoor farming equipment sits in early-cycle expansion as EU Green Deal retrofit mandates and IRA agricultural tax incentives accelerate penetration beyond early-adopter vertical farms into mainstream greenhouse operations.
For Market Incumbents: Entrench technology leadership through captive supply of spectral-tunable LED modules and predictive maintenance software licensing. Deepen backward integration into phosphor-converted chip manufacturing to offset rare-earth cost volatility. Defend against modular equipment suppliers by embedding climate control and nutrient delivery into unified platforms with multi-year service contracts.
For New Entrants and Emerging Players: Establish a beachhead in containerized vertical farming systems for Saudi Arabian and UAE food security programs. Target mid-scale urban farmers in Tokyo and Singapore with compact automation solutions requiring minimal on-site engineering support. Pursue partnership-led go-to-market models with metropolitan grocery retailers seeking captive supply agreements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming agricultural automation divisions. Long-term viability favors platform integrators with recurring software revenue over pure hardware manufacturers. Monitor EPA agricultural runoff enforcement timelines and carbon accounting methodology adoption as inflection signals for closed-loop system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectral Recipe Library Expansion | Proprietary light protocols differentiate platform integrators from commodity LED suppliers in lettuce and spinach operations. |
| Heat-Recovery Ventilation Integration | Dutch greenhouse operators prioritize these systems for EU Green Deal carbon accounting compliance. |
| Predictive Maintenance Contract Scaling | Recurring software revenue pools from sensor-fusion platforms attract investor interest beyond hardware margins. |
| Rare-Earth Supply Diversification | Phosphor sourcing outside Chinese mining clusters reduces tariff exposure and input cost volatility. |
| Containerized System Deployment | Saudi Arabia's national food security strategy creates demand for fully automated nutrient delivery in arid climates. |
Research Methodology
Desk research of SEC filings from controlled-environment agriculture operators, EPA regulatory dockets, EU Green Deal implementation documents, and Chinese GB standards databases preceded structured interviews with vertical farm operations directors, greenhouse technology procurement managers, LED module manufacturing executives, and climate control systems engineers. Primary fieldwork validated equipment deployment timelines and opex reduction priorities across commercial grower segments. Secondary sources included customs trade data for horticultural equipment imports and patent filings for aeroponic irrigation technologies. Bottom-up unit economics modeling triangulated against top-down market sizing from capital deployment tracking.
Assumptions held fixed across the modeling period include EU Green Deal regulatory timelines, Chinese dual carbon goal enforcement intensity, and IRA agricultural provision renewal probability. Variables included LED module cost decline curves, rare-earth price volatility bands, and metropolitan grocery retailer contract expansion rates. Segmentation dimensions encompassed product type, technology tier, end-user scale, and crop application maturity. CAGRs derived from equipment shipment volumes weighted by average selling price trajectories across premium and standard configuration tiers. Industry-specific inputs included photosynthetic photon flux density adoption thresholds and closed-loop water recycling compliance deadlines.
Sensitivities concentrate around EPA agricultural runoff standard enforcement acceleration, REACH substrate restriction expansion, and Chinese export license tightening for rare-earth processed materials. Forecasts reflect documented assumptions on regulatory timeline adherence and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Farm Tire Market