
 Lawn Aerators Market | 2026-2036
Lawn Aerators Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Aerators Market Foresight
The capital-intensity divergence between high-volume OEMs and niche fabricators is unwinding competitive stability in lawn aerator manufacturing. Bluebird leverages its established dealer network to sustain aftermarket parts revenue across North America. Agri-Fab specializes in tow-behind attachments for residential riding mowers, occupying a defensible price tier below commercial-grade equipment. Greenworks anchors its position with battery-electric platforms that bypass small-engine emissions compliance costs entirely.
A lawn aerator is a soil-perforation implement that extracts cylindrical plugs or drives spikes into turf to alleviate compaction and improve root-zone gas exchange; core depth typically ranges from two to four inches depending on tine geometry and soil density. The device serves groundskeeping professionals and homeowners seeking to restore permeability to high-traffic grass surfaces. Gas-powered aerators still dominate rental fleets and municipal contracts where runtime demands exceed current battery endurance, though electric variants are capturing residential and golf-course segments where noise ordinances restrict operating hours. Tow-behind models attached to garden tractors lead the residential category by capital efficiency, while walk-behind and stand-on units command premium placement among commercial landscapers facing labor productivity targets.
EPA Phase 3 small spark-ignition engine standards and California Air Resources Board zero-emission equipment mandates are forcing gasoline-powered aerator redesigns or platform abandonment in regulated jurisdictions. OSHA noise exposure limits influence machine specification for daytime commercial operation, particularly near schools and healthcare facilities. Stakeholders must monitor battery energy density trajectories and regional incentive structures for landscape electrification to time capital commitments across mixed-fleet transitions.
Market Dynamics
EPA Phase 3 small spark-ignition engine standards and California Air Resources Board zero-emission mandates are forcing gasoline-powered aerator redesigns or platform abandonment across the United States, compressing product development timelines and reallocating R&D budgets toward battery-electric architectures.
Growth Catalysts
- CARB Zero-Emission Mandates:California's 2024 requirement for zero-emission landscape equipment creates guaranteed demand pull for battery-electric aerators, with other states adopting similar frameworks.
- Golf Course Maintenance Contracts:Private and municipal golf facilities are replacing aging aerator fleets on 5-7 year cycles, generating predictable replacement revenue for equipment vendors.
- Lithium-Ion Cell Cost Curves:Falling battery pack prices enable price-competitive electric walk-behind units that match gasoline runtime for residential and light-commercial applications.
Market Restraints
- Steel and Aluminum Input Volatility:Tine assemblies and frame components face commodity price swings that compress fabricator margins on fixed-price municipal contracts.
- Small-Engine Supply Concentration:Three Japanese and US suppliers dominate commercial-grade gasoline powertrains, creating vulnerability for OEMs without dual-source strategies.
- Battery Energy Density Limits:Current lithium-ion chemistry cannot sustain 8+ hour runtime demands for large tow-behind aerators used in highway median and airport turf maintenance.
Strategic Opportunities
- Texas and Florida Suburban Expansion:Rapid residential development in these states creates new lawn service demand and equipment procurement from regional landscaping franchises.
- Telematics-Enabled Fleet Management:Integration of GPS tracking and usage analytics allows rental companies to offer outcome-based pricing tied to actual soil perforation acreage.
- USDA Conservation Reserve Program Incentives:Federal cost-share funding for soil health improvement on agricultural margins creates adjacent demand for compact tractor-mounted aerators.
Industry Challenges
- Small-Engine Technician Scarcity:Declining vocational training programs for two-stroke and four-stroke engine repair complicate service network expansion for mixed-fleet dealers.
- UL 2580 Battery Certification Timelines:Third-party safety validation for high-voltage traction systems adds 8-14 months to product launch schedules, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Aerators Market |
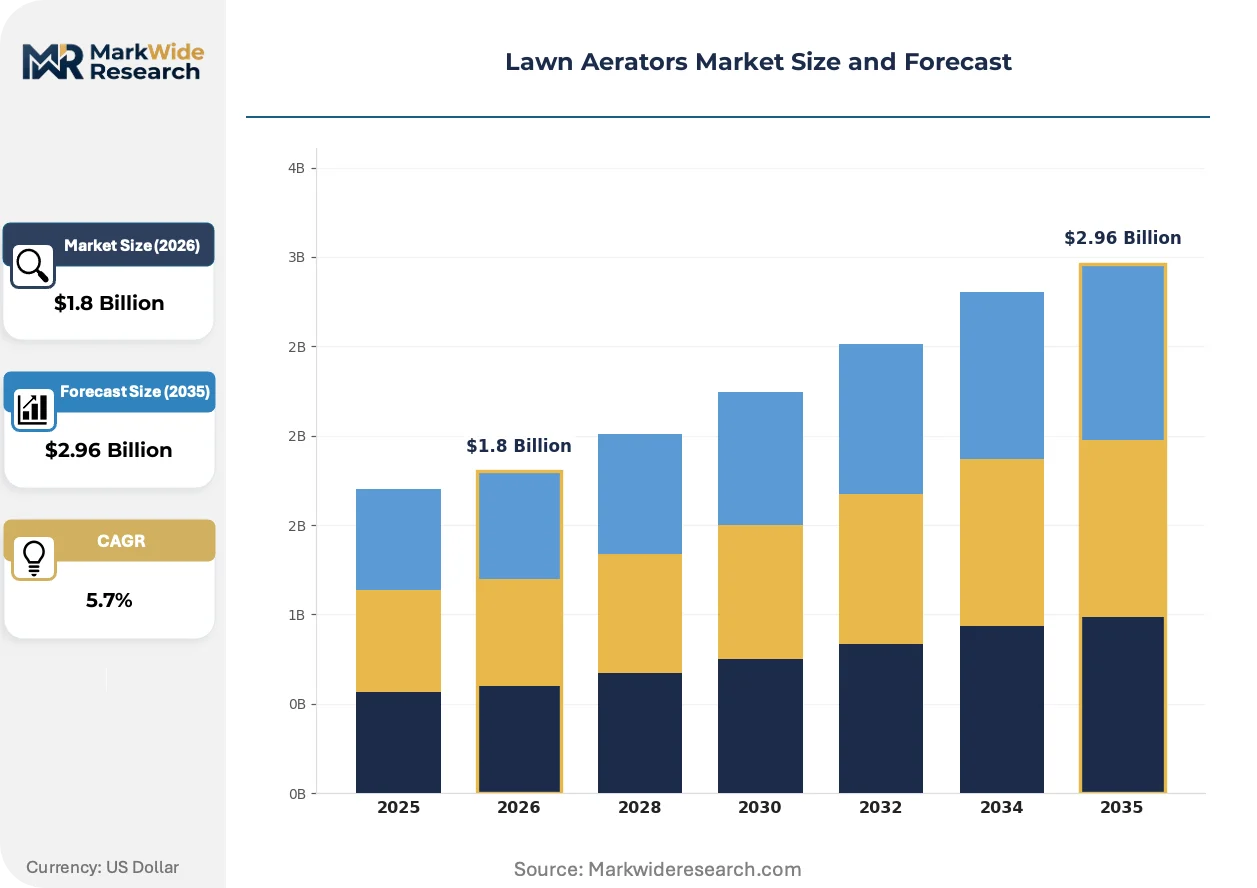
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Aerators, Electric Aerators, Gas-Powered Aerators, Tow-Behind Aerators End User: Residential Users, Commercial Landscapers, Golf Courses, Sports Facilities Technology: Piercing, Plugging, Spiking, Hollow Tine Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Wholesalers |
| Companies Covered | Bluebird, Z Turf Equipment, Agri-Fab, Westinghouse, Bobcat, Brinly, Yard Butler, Greenworks, Billy Goat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Aerators Market Shifts & Advancements
Equipment electrification is rewriting competitive positioning across power classes, while regulatory fragmentation between federal and state jurisdictions forces parallel product development tracks. These shifts are compressing traditional technology adoption cycles.
Brushless DC motor systems paired with lithium iron phosphate battery packs are supplanting small gasoline engines in walk-behind and stand-on aerator categories. Commercial landscapers serving noise-restricted zones are adopting these platforms within 18-24 month replacement windows. This transition is compressing aftermarket parts revenue for legacy engine suppliers while opening subscription-based battery service models.
California Air Resources Board zero-emission equipment mandates and EPA Phase 3 small spark-ignition standards are tightening exhaust and evaporative emissions requirements simultaneously. Gasoline-powered aerator OEMs face parallel compliance investments or portfolio rationalization decisions. Municipal procurement departments in Los Angeles, San Diego, and Sacramento are now specifying electric-only fleets, forcing rental channel inventory reconfiguration.
Landscape service franchises are consolidating equipment procurement through national fleet management agreements, displacing decentralized dealer relationships. Regional landscaping chains in Texas, Arizona, and Colorado are centralizing specification authority at corporate headquarters. This concentration is most visible in the Sun Belt states where private equity-backed platform rollups are achieving scale.
Lawn Aerators Market Segmentation
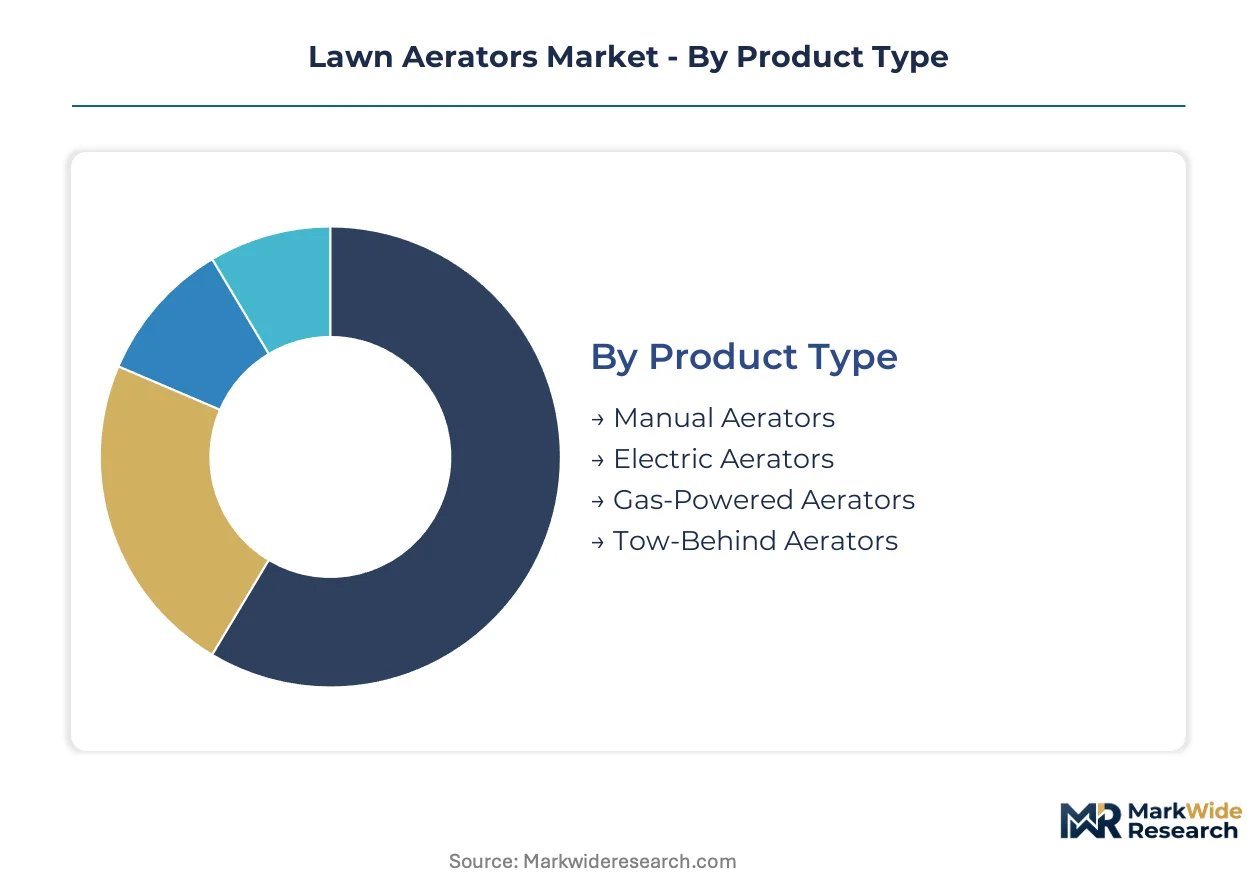
Equipment specification diverges sharply between residential maintenance and commercial groundskeeping contracts. Segmentation reveals how powertrain choices and tine geometries align with runtime demands, noise restrictions, and capital recovery timelines across customer tiers.
Product Type:
Domestic production concentrates in gas-powered and tow-behind categories for the US rental channel, while electric platforms draw heavily on Asian battery cell imports for cost-competitive residential SKUs.
- Manual Aerators:Handheld spike or plug tools with fixed tine spacing, typically 2-4 inch penetration depth. Demand clusters in urban California municipalities where CARB zero-emission mandates prohibit engine-powered equipment for small maintenance crews; limited runtime constraints favor human-powered solutions for patch repairs and verge strips.
- Electric Aerators:Corded and battery-powered walk-behind units using brushless DC motors. Momentum concentrates in Sun Belt residential markets where noise ordinances restrict early-morning operation; falling lithium-ion pack costs enable price parity with entry gasoline models for sub-10,000 square foot properties.
- Gas-Powered Aerators:Commercial-grade Honda, Briggs & Stratton, or Kawasaki engines driving reciprocating or drum tine mechanisms. Still dominates municipal highway median and airport contracts where 8+ hour runtime demands exceed current battery endurance; EPA Phase 3 compliance costs are compressing margin on fixed-price fleet renewals.
- Tow-Behind Aerators:Hitch-mounted drum assemblies for garden tractors and compact utility vehicles. Golf courses and sports turf managers specify these for acre-scale perforation; steel tine durability and replaceable spoon designs support 5-7 year replacement cycles under intensive use.
Gas-powered aerators hold the largest share; momentum sits with electric platforms in noise-restricted jurisdictions.
End User:
Procurement authority is consolidating through national landscape service franchises, displacing decentralized dealer relationships that historically served fragmented residential demand.
- Residential Users:Homeowners maintaining 0.25-2 acre properties, primarily purchasing walk-behind electric or manual tools. Demand flows through Home Depot, Lowe's, and Amazon channels with seasonal concentration in March-May; battery-electric preference is climbing fastest in California, New York, and Massachusetts where state-level electrification incentives apply.
- Commercial Landscapers:Regional service franchises and independent operators with 10-50 unit fleets. These buyers prioritize stand-on aerator productivity metrics—acres per hour and operator fatigue reduction; national procurement agreements with BrightView, TruGreen, and Weed Man are centralizing specification authority at corporate headquarters.
- Golf Courses:Private clubs and municipal facilities replacing aerator fleets on predictable 5-7 year cycles. Superintendent specifications favor tow-behind and large walk-behind units with precise depth control; USGA turfgrass research recommendations drive tine geometry preferences toward 0.5-0.75 inch diameter hollow cores.
- Sports Facilities:School districts, university athletic departments, and professional stadium grounds crews. These operators face OSHA noise exposure limits for daytime maintenance near occupied buildings; electric platform adoption is expanding most quickly in this segment to comply with daytime decibel restrictions.
Commercial landscapers generate the highest equipment turnover velocity; golf courses provide the most predictable replacement revenue.
Technology:
Core extraction method determines soil disruption intensity and recovery timeline, with selection driven by turfgrass species and traffic load tolerance.
- Piercing:Solid tine penetration without core removal, creating narrow fracture channels. Kentucky bluegrass and fine fescue lawns on clay-heavy soils favor this method for minimal surface disruption; demand concentrates in Midwest residential markets with heavy clay content.
- Plugging:Hollow tine extraction of 2-4 inch soil cores, the standard for high-traffic athletic turf. Golf course superintendents specify plugging for bentgrass and bermudagrass greens where thatch accumulation and compaction demand aggressive remediation; core removal accelerates gas exchange but requires post-aeration cleanup labor.
- Spiking:Star or knife blade penetration creating shallow slits rather than cylindrical holes. Sports field managers use spiking for mid-season maintenance on sand-based rootzones where deep disruption would compromise playability; this method sees seasonal demand spikes in advance of playoff schedules.
- Hollow Tine:Precision-machined steel tubes extracting uniform cores with minimal surrounding soil disturbance. Premium golf and stadium turf specifications require hollow tine for consistent hole diameter and depth; tine metallurgy and replaceable spoon designs differentiate equipment price tiers.
Plugging dominates commercial revenue; hollow tine commands premium placement in elite turf maintenance.
Distribution Channel:
Inventory allocation shifts toward direct and wholesale channels as fleet procurement consolidates, while retail and online serve fragmented residential replacement demand.
- Retail Stores:Home Depot, Lowe's, and regional farm supply chains stocking consumer-grade electric and manual aerators. These outlets capture seasonal walk-in demand with limited sales associate technical expertise; inventory turns concentrate in pre-spring reset periods.
- Online Platforms:Amazon, manufacturer DTC sites, and specialty equipment portals. Residential buyers research specifications and compare battery runtime claims digitally; free shipping thresholds and return policies drive platform selection over price alone.
- Direct Sales:Manufacturer field representatives negotiating fleet specifications with national landscaping franchises and municipal procurement departments. John Deere, Toro, and Exmark deploy direct sales teams for contracts exceeding 25 units; these relationships bypass dealer margin and enable customized warranty terms.
- Wholesalers:Regional distributors supplying independent rental yards and dealer networks. United Rentals, Sunbelt, and Herc Rentals source through wholesale channels for fleet standardization; these intermediaries provide parts inventory and technician training that manufacturers cannot scale directly.
Wholesalers and direct sales together capture the majority of commercial volume; online platforms are expanding share fastest in residential battery-electric categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida command pricing premiums for commercial-grade equipment, while Midwest fabricators compete on volume-driven residential SKUs. This asymmetry shapes inventory allocation and margin capture across North American distribution channels.
United States
California's CARB zero-emission mandate for 2024 landscape equipment creates guaranteed demand pull for battery-electric walk-behind units. EPA Phase 3 small spark-ignition standards force gasoline-powered redesigns or abandonment in regulated jurisdictions. Los Angeles and San Diego municipal procurement departments now specify electric-only aerator fleets, compressing rental channel inventory cycles.
Canada
Ontario and British Columbia golf facilities replace aerator fleets on predictable 5-7 year cycles, generating stable replacement revenue for equipment vendors. Health Canada's PMRA regulates pesticide application timing, indirectly concentrating aerator demand into narrow seasonal windows. The Greater Toronto Area anchors commercial landscaping procurement for national franchise operations.
Germany
Baden-Württemberg and Bavaria sports turf managers specify precision hollow-tine equipment for Bundesliga football pitch maintenance. REACH chemical regulations restrict soil amendment products, amplifying mechanical aeration as the preferred compaction remedy. Stuttgart's industrial machinery cluster supports component sourcing for premium tine metallurgy.
United Kingdom
England's Golf Union research recommendations drive superintendent specifications toward precise core extraction equipment for links and parkland courses. The Environment Agency's water quality regulations restrict fertilizer runoff, increasing aeration frequency as a nutrient management substitute. The Southeast England corridor concentrates groundskeeping contractor procurement authority.
Australia
New South Wales and Victoria municipal councils face drought-response water restrictions that elevate soil permeability investments. The Australian Pesticides and Veterinary Medicines Authority regulates turf chemical inputs, shifting maintenance budgets toward mechanical remediation. Sydney's sports precinct procurement coordinates fleet specifications across multiple stadium and training ground contracts.
Lawn Aerators Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across powertrain categories. The vendor base separates into three strategic clusters: established outdoor power equipment brands with dealer network scale, specialty turf machinery fabricators with precision engineering focus, and battery-electric platform specialists leveraging cell cost curves. Consolidation pressure concentrates among gasoline-powered incumbents facing dual regulatory compliance investments. Dominant competitive moves include portfolio rationalization between engine architectures and geographic expansion through rental channel partnerships.
Among North American equipment specialists, Bluebird and Billy Goat occupy positions within the commercial-grade gasoline platform tier, while Greenworks anchors the battery-electric specialist archetype. Agri-Fab exemplifies the attachment-focused fabricator serving residential riding mower compatibility. These three companies represent distinct strategic postures: legacy engine supply chain leverage, emissions-compliant electric architecture, and capital-efficient tow-behind specialization respectively.
| Leading Market Players |
|---|
| Bluebird |
| Z Turf Equipment |
| Agri-Fab |
| Westinghouse |
| Bobcat |
| Brinly |
| Yard Butler |
| Greenworks |
| Billy Goat |
| Others |
Supply & Pricing Matrix
Battery cell chemistry substitution for small gasoline engines simultaneously relocates supply geography toward Asian manufacturing clusters and compresses pricing premiums on electric walk-behind units. This displacement redraws cost structures across powertrain tiers while EPA Phase 3 compliance investments inflate landed costs for legacy gasoline platforms.
Pricing Analysis
The customization-premium spread separates configured-to-order hollow-tine assemblies from standard drum configurations, with golf course specifications commanding substantial markups for precision metallurgy. Pricing stratifies across premium, standard, and economy tiers based on tine geometry complexity and runtime architecture. Cost compression in entry-level electric SKUs is intensifying because lithium-ion pack prices continue declining. Residential buyers through retail channels exhibit highest price sensitivity, while municipal procurement departments prioritize total cost of ownership over unit price.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production for battery-electric aerator platforms, while Japan and the United States retain gasoline engine supply concentration. Tine assemblies draw from domestic steel fabrication, and brushless DC motors source from Taiwanese electronics suppliers. Single-source vulnerability concentrates in commercial-grade powertrain procurement from Honda, Briggs & Stratton, and Kawasaki. Distribution runs through wholesale intermediaries serving rental fleets and direct sales teams negotiating national landscaping franchise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lawn aerators market sits at an early-cycle expansion story as battery-electric penetration accelerates through CARB-mandated fleet replacements and falling cell costs enable price-competitive alternatives.
For Market Incumbents: Secure dual-source battery cell agreements to insulate against supply concentration risk in Asian manufacturing. Prioritize UL 2580 certification investment to compress product launch timelines and capture municipal electric-fleet specifications ahead of competitors. Defensive positioning requires backward integration into tine metallurgy to protect margin against steel input volatility. For New Entrants and Emerging Players: Lead with battery-electric walk-behind units targeting Texas and Florida suburban landscaping franchises where fleet procurement is consolidating but electrification penetration remains nascent. White-space opportunity concentrates in telematics-enabled rental fleet management where outcome-based pricing models remain underdeveloped. Go-to-market execution should emphasize direct sales relationships with regional landscaping chains bypassing established dealer networks. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors battery-electric platform specialists with certified traction systems and established municipal procurement relationships. Long-term viability across the next decade hinges on positioning ahead of state-level zero-emission mandate proliferation beyond California. Acquisition target archetype includes electric powertrain fabricators with UL-certified battery packs and rental channel placement. The signal to watch is state-level regulatory adoption timelines for landscape equipment electrification.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Certification | UL 2580 validation accelerates municipal procurement eligibility in CARB-regulated jurisdictions. |
| Dual-Source Cell Procurement | Supply diversification from China and South Korea reduces single-source vulnerability for electric SKUs. |
| Telematics Fleet Integration | GPS-enabled usage analytics enable outcome-based rental pricing tied to actual acreage perforated. |
| Tine Metallurgy Backward Integration | In-house steel component production insulates margin against commodity price volatility on fixed contracts. |
| Rental Channel Partnership Expansion | United Rentals and Sunbelt fleet standardization agreements lock in multi-year volume commitments. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with equipment procurement managers at national landscaping franchises, golf course superintendents, municipal fleet directors, and rental company operations heads; and secondary validation through EPA regulatory filings, CARB mandate documentation, SEC equipment manufacturer disclosures, and trade customs data on battery cell imports. Bottom-up unit economics triangulated against top-down market sizing across powertrain categories and end-user segments.
Across the analysis window, forecasts model equipment replacement cycles, regulatory compliance timelines, and battery cost curve trajectories. Segmentation dimensions include powertrain architecture, product type classification, end-user procurement authority, and regional regulatory cluster. CAGRs derive from installed base turnover velocity and electrification penetration assumptions. Industry-specific inputs incorporate golf course fleet replacement scheduling and municipal contract renewal patterns.
Forecasts assume regulatory continuity in EPA Phase 3 and CARB zero-emission regimes; material policy shifts would require re-modeling adoption timelines and powertrain mix assumptions. Specific risks that could revise projections include accelerated state-level electrification mandates, battery energy density breakthroughs extending runtime thresholds, or prolonged small-engine technician scarcity compressing gasoline platform service network viability. Recalibration cycles align with material shifts in regulatory adoption timelines and battery chemistry cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Green Beans Harvester Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Global Precision Harvesting Market