
 Spreads and Toppings Packaging Market | 2026-2036
Spreads and Toppings Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spreads and Toppings Packaging Market Outlook
The premium-commodity split in spreads and toppings packaging is rebalancing as artisanal brands demand high-barrier films with extended shelf-life performance while private-label buyers prioritize cost-efficient mono-material structures. Amcor Plc leverages its global flexible film footprint to serve both tiers simultaneously. Berry Global Group anchors North American rigid container supply for peanut butter and preserves. Mondi Plc specializes in recyclable paper-based barrier solutions that target sustainability-driven European retailers.
Spreads and toppings packaging encompasses primary and secondary containment systems engineered to protect viscous food products from oxygen ingress, moisture loss, and microbial contamination, typically employing multilayer coextruded films with ethylene vinyl alcohol barrier layers or glass jars with hermetic metal closures to achieve shelf stability. Flexible packaging leads volume in single-serve condiment sachets and stand-up pouches for nut butters, where lightweighting and logistics efficiency concentrate margin pools. Rigid containers remain structurally entrenched in retail jam and honey segments where consumer preference for resealability and premium shelf presence sustains glass and plastic jar demand. Closure innovation across twist-off and snap-on formats is accelerating as brands seek differentiation through dispensing convenience and tamper evidence.
FDA food-contact substance notifications govern barrier adhesive and coating approvals for US-bound flexible packaging, while EU REACH and F-Gas Regulation constrain fluorinated barrier chemistries and propellant use in aerosolized toppings. BIS packaging standards in India mandate specific migration limits for plastic containers used in edible oil-based spreads, shaping export compliance burdens for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return scheme expansions that will force material redesign decisions ahead of regulatory enforcement timelines.
Market Dynamics
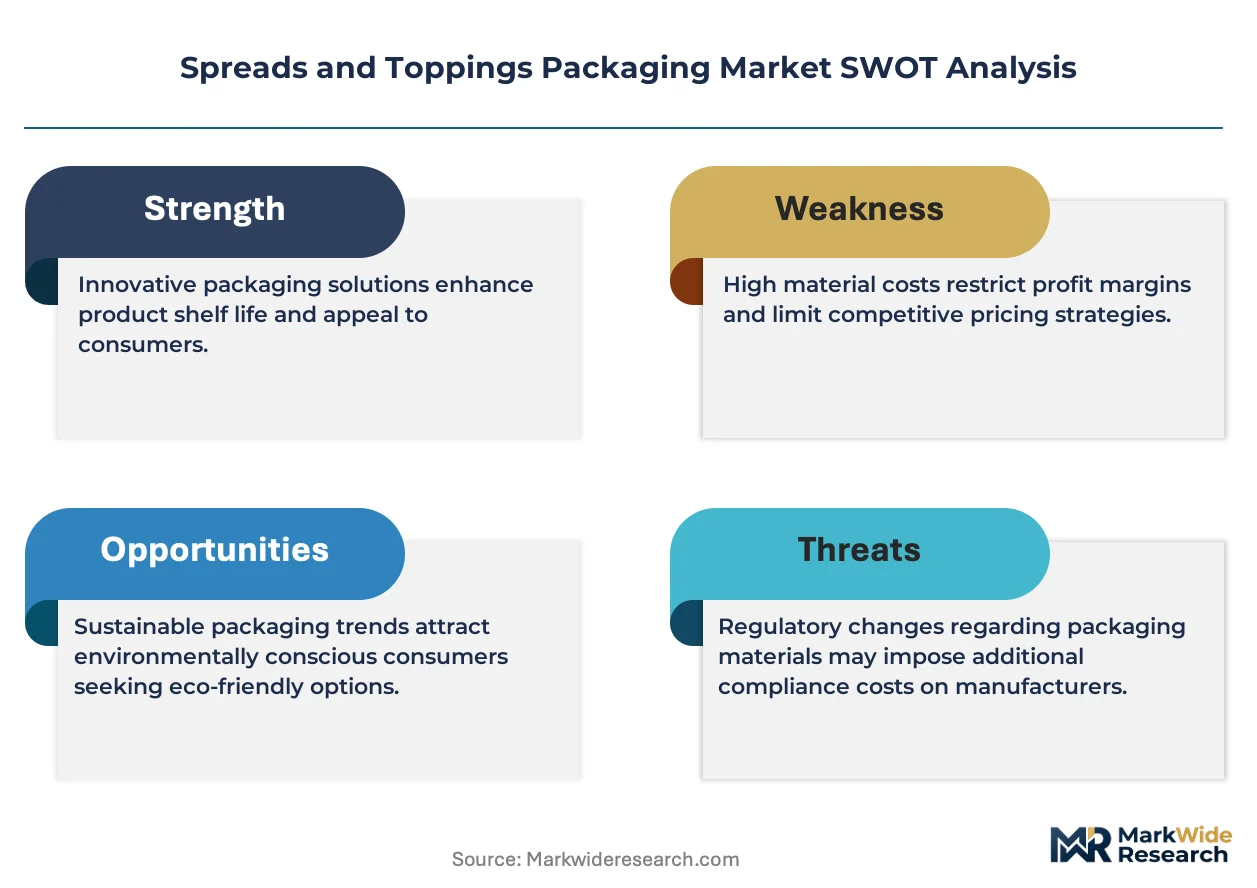
Material compliance timelines are compressing design cycles as FDA food-contact substance notifications and EU single-use plastics directives force simultaneous reformulation of barrier adhesives and substrate selection, squeezing suppliers who must certify multilayer structures before enforcement deadlines.
Growth Catalysts
- EU Single-Use Plastics Directive:Bans on expanded polystyrene containers are redirecting condiment packaging toward recyclable paper-based barriers, creating compliant substrate demand.
- Portion-controlled formats:Foodservice operators are adopting single-serve sachets and mini-pots for condiments, driving flexible packaging volume in institutional channels.
- Germany private-label concentration:Discounter chains are consolidating flexible pouch procurement for store-brand nut butters, anchoring regional converter capacity.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Barrier resin production clusters in Northeast Asia, exposing converters to freight volatility and tariff exposure.
- Fluorinated chemistry constraints:EU F-Gas Regulation and REACH restrictions on per- and polyfluoroalkyl substances are eliminating high-performance grease-resistant coatings without drop-in replacements.
- Glass jar weight penalties:Rigid container logistics costs scale with fuel prices, disadvantaging heavy-format preserves against lightweight flexible alternatives.
Strategic Opportunities
- Deposit-return scheme expansion:EU member states are mandating packaging collection infrastructure, creating closed-loop material recovery revenue streams for compliant mono-material designs.
- Aerosolized toppings segment:Whipped cream and dessert spray formats remain underpenetrated in South Asian markets, offering first-mover positioning for compatible valve-and-bag systems.
- Digital printing convergence:Variable-data inkjet on flexible films enables micro-batch customization for artisanal brands, collapsing minimum order quantities.
Industry Challenges
- Migration testing bottlenecks:FDA notification review timelines for novel barrier adhesives extend 12-18 months, delaying product launches.
- Mono-material performance gaps:Recyclable polyethylene structures struggle to match multilayer shelf-life for oxygen-sensitive nut butters, requiring formulation compromise.
- Legacy equipment retrofit costs:Converters face capital outlays for seal-bar and forming-plate modifications to run thinner gauge films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spreads and Toppings Packaging Market |
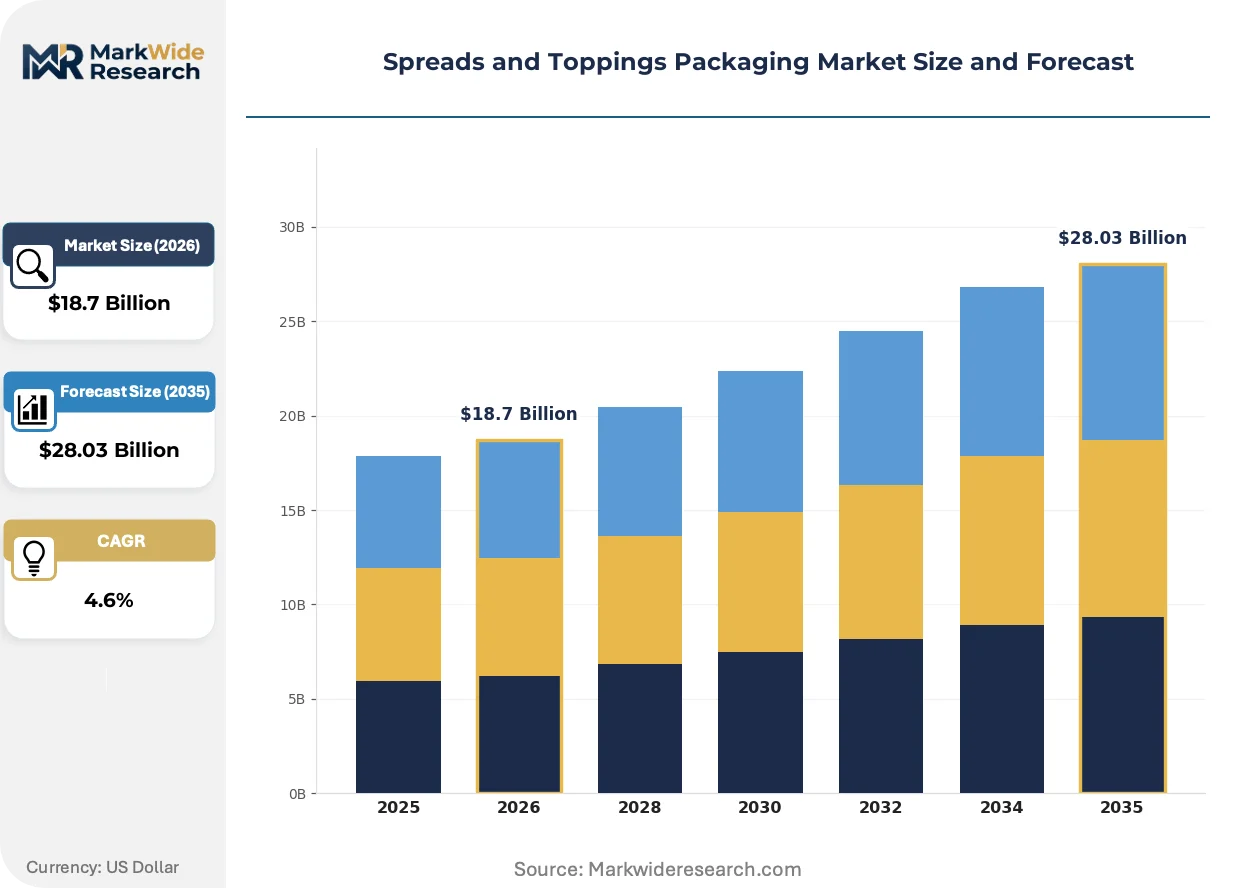
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Containers, Jars, Sachets Material: Plastic, Glass, Aluminum, Paper Closure Type: Cap, Twist-off, Snap-on, Stand-up Pouch End User: Residential, Food Service, Retail, Industrial |
| Companies Covered | Amcor Plc, Berry Global Group, Mondi Plc, Sealed Air Corporation, Constantia Flexibles, Clondalkin Group, Wipak, Scholle IPN, Ropak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spreads and Toppings Packaging Market Strategic Shifts
Active and intelligent packaging functionalities are migrating from premium pharmaceuticals into food contact, with oxygen-scavenging films and freshness indicators now technically feasible for mid-market spreads. Three developments are restructuring competitive capability requirements.
High-barrier mono-material polyethylene is electrifying sustainable packaging roadmaps by delivering extended shelf-life without adhesive lamination. European retailers are mandating its adoption for private-label nut butters, compressing multilayer flexible film demand and forcing converters to requalify seal integrity at reduced caliper weights.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon propellants in aerosolized dessert toppings, compelling valve manufacturers to engineer compressed gas alternatives. Metal can and bag-on-valve suppliers serving the whipped cream segment are accelerating compatibility testing with nitrous oxide replacements ahead of 2030 prohibition timelines.
Foodservice procurement consolidation is compressing supplier rosters as institutional buyers centralize condiment purchasing through group purchasing organizations. Distributor private-label penetration is displacing branded portion-control sachets in US healthcare and education channels, rewarding converters with scale-advantaged filling lines and national distribution footprints.
Spreads and Toppings Packaging Market Segmentation
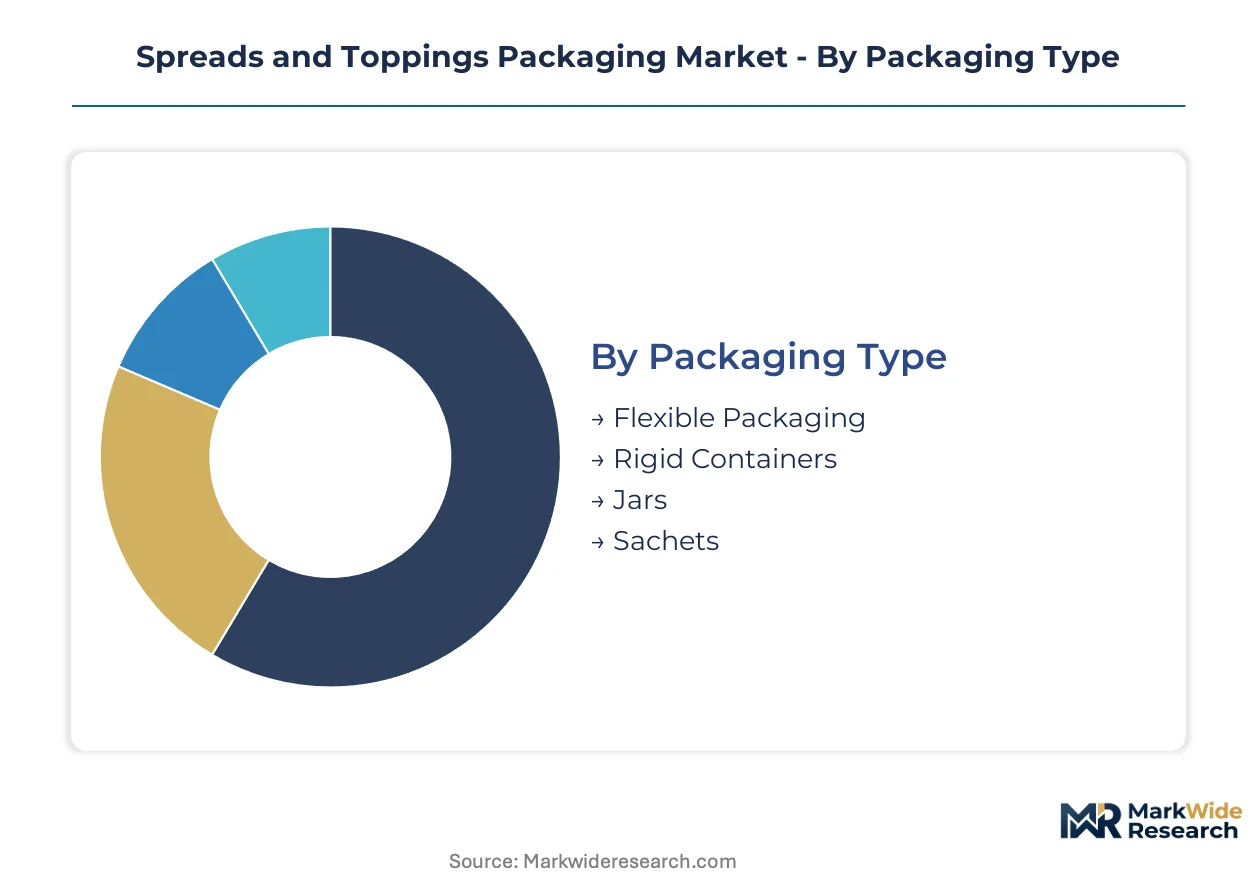
Segmentation in spreads and toppings packaging reveals how viscosity, oxygen sensitivity, and dispensing convenience fragment procurement priorities across customer tiers. Material selection and format specifications diverge sharply between retail shelf-stable jams and foodservice single-serve condiments.
Packaging Type:
Upgrade cycles in this category track sustainability mandates and logistics cost pressures rather than obsolescence, with converters retiring multilayer equipment for mono-material lines ahead of regulatory deadlines.
- Flexible Packaging:Multilayer coextruded films with EVOH barrier layers dominate nut butter pouches and condiment sachets, achieving shelf stability at one-third the logistics weight of rigid alternatives. Demand concentrates in Germany's private-label discounter chains, where lightweighting directly reduces per-unit freight costs across dense European distribution networks.
- Rigid Containers:Injection-molded polypropylene and polyethylene terephthalate jars preserve resealability for high-viscosity preserves, with hermetic induction seals replacing metal lug closures in cost-optimized SKUs. North American peanut butter manufacturers anchor regional blow-molding capacity, though glass weight penalties are forcing partial substitution in export-oriented production.
- Jars:Traditional wide-mouth glass formats retain premium positioning in artisanal honey and fruit preserves, where consumer tactile preference sustains higher unit costs despite logistics disadvantages.
- Sachets:Three-side-seal and four-side-seal pouch configurations serve institutional condiment dispensing, with portion-controlled 10-20 gram formats displacing bulk pump systems in healthcare and education channels.
Flexible packaging sits at the top of the volume ranking, with sachets climbing the fastest as foodservice procurement consolidates through group purchasing organizations.
Material:
Cost tiers in substrate selection separate premium barrier performance from compliance-driven mono-material redesign, with mid-market brands caught between shelf-life requirements and recyclability mandates.
- Plastic:High-density polyethylene and polypropylene structures enable hot-fill processing for pasteurized spreads, with nucleating agents improving clarity for retail shelf appeal. European retailers are mandating mono-material polyethylene for private-label nut butters, forcing adhesive lamination out of certified recyclable streams.
- Glass:Amber and flint soda-lime containers provide inert contact surfaces for acidic fruit preserves, though EU packaging and packaging waste regulations are accelerating lightweighting programs to reduce material intensity per unit.
- Aluminum:Drawn and ironed two-piece cans serve aerosolized whipped cream and dessert toppings, with F-Gas Regulation phase-downs compelling valve compatibility testing with compressed gas propellant alternatives.
- Paper:Barrier-coated kraft and molded fiber formats are capturing condiment sachet demand as EU single-use plastics bans eliminate expanded polystyrene alternatives, though grease resistance remains technically constrained without fluorinated chemistries.
Plastic commands the dominant volume position, with paper gaining share fastest as regulatory prohibitions reshape substrate eligibility.
Closure Type:
Application-specific dispensing requirements determine closure selection, with tamper evidence and reseal functionality driving specification divergence between retail and institutional channels.
- Cap:Continuous-thread polypropylene closures with induction foil liners provide hermetic seals for retail condiment jars, with linerless designs reducing material cost in private-label SKUs.
- Twist-off:Vacuum lug closures enable home-canning compatibility for premium preserves, though torque consistency challenges complicate high-speed filling line integration.
- Snap-on:Press-fit polypropylene lids serve single-serve condiment cups in foodservice, where one-time use eliminates reseal requirements and enables thinner-wall construction.
- Stand-up Pouch:Fitment-equipped spouted pouches with tamper-evident breakaway caps are penetrating nut butter and squeezable honey segments, combining flexible logistics with controlled dispensing precision.
Cap formats lead absolute volume, with stand-up pouch configurations expanding most quickly as brands seek differentiation through dispensing convenience.
End User:
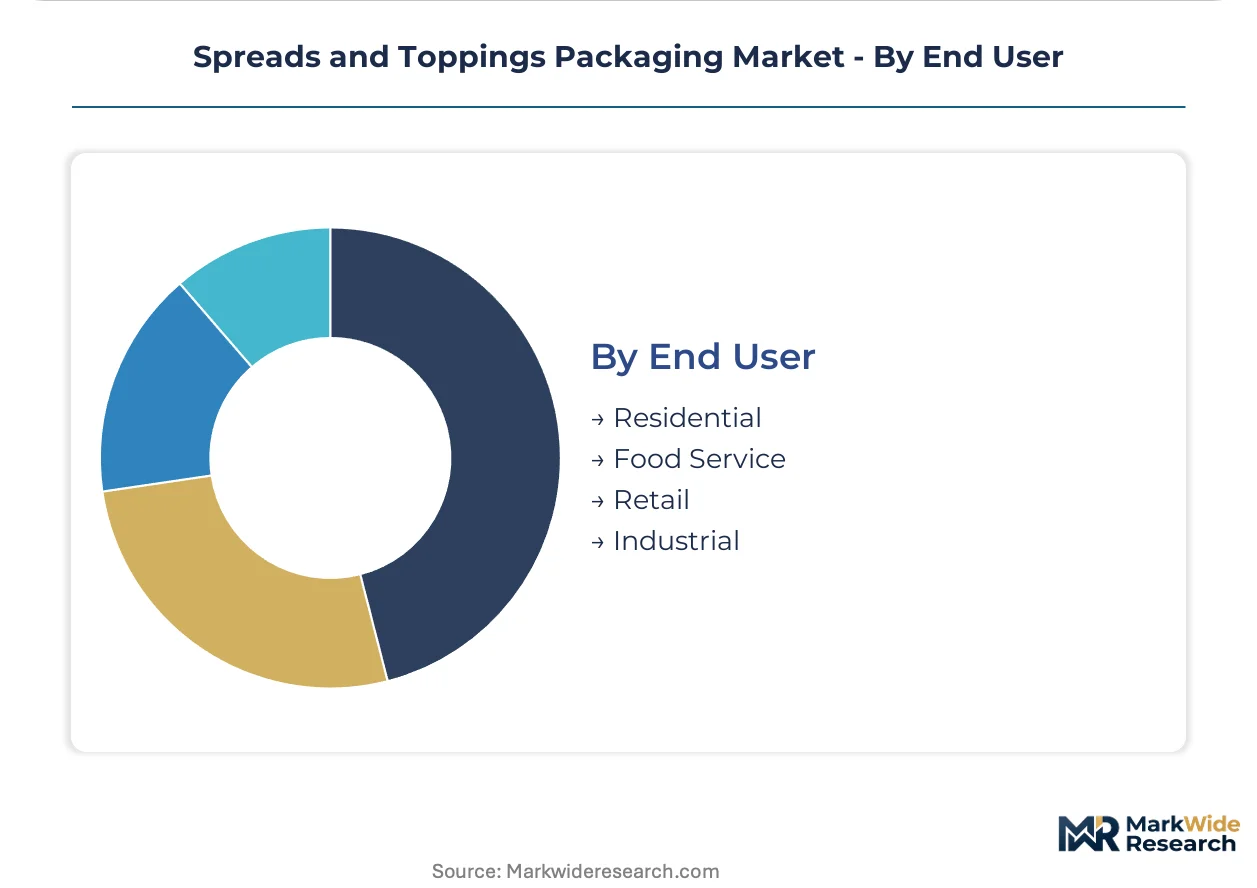
Customer type fragmentation reflects divergent procurement economics, with institutional buyers prioritizing total cost of ownership and residential consumers responding to shelf presence and reseal convenience.
- Residential:Individual consumers purchase retail-format jars and pouches through grocery and e-commerce channels, with subscription models for artisanal nut butters driving premium flexible packaging demand.
- Food Service:Restaurants, cafeterias, and catering operations procure portion-controlled sachets and bulk pump dispensers through distributor networks, where private-label penetration is displacing branded condiments.
- Retail:Supermarket and hypermarket private-label programs concentrate flexible pouch procurement for store-brand spreads, with discounter chains in Germany anchoring regional converter capacity through volume commitments.
- Industrial:Food manufacturers source intermediate bulk containers and aseptic bag-in-box systems for further processing into finished consumer goods, with oxygen barrier specifications varying by end-product shelf-life requirements.
Retail channels dominate current volume, with food service climbing fastest as procurement centralization through group purchasing organizations compresses supplier rosters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled converter workforces in Germany's Rhine-Ruhr and North Rhine-Westphalia industrial corridors anchor European flexible packaging capacity for nut butter and condiment applications.
Germany
Private-label discounter chains concentrate flexible pouch procurement for store-brand spreads, driving converter investment in mono-material polyethylene lines. EU Single-Use Plastics Directive enforcement redirects substrate selection toward recyclable paper-based barriers. The Rhine-Ruhr metropolitan region hosts specialized coextrusion facilities serving pan-European retail distribution networks.
United States
North American peanut butter manufacturers anchor regional blow-molding demand for rigid polypropylene jars with hermetic induction seals. FDA food-contact substance notifications govern barrier adhesive approvals, extending certification timelines for multilayer structures. Chicago-area converter clusters supply foodservice portion-control sachets to institutional buyers through distributor networks.
India
Rising consumption of edible oil-based spreads drives plastic container demand in Maharashtra and Gujarat processing hubs. BIS packaging standards mandate specific migration limits for food-contact plastics, shaping export compliance burdens for multinational suppliers. The Mumbai-Pune industrial corridor concentrates injection-molding capacity for retail-format preserves and condiments.
China
Domestic nut butter brands expand stand-up pouch adoption for e-commerce subscription models, leveraging lightweight logistics for last-mile delivery efficiency. GB standards for food-contact materials constrain additive formulations in multilayer films. The Yangtze River Delta manufacturing belt supplies barrier film substrates to regional flexible packaging converters.
Brazil
Foodservice channel growth in São Paulo and Rio de Janeiro metro areas drives single-serve condiment sachet volume. ANVISA food-contact regulations align with Mercosur technical standards for plastic migration limits. The São Paulo state industrial zone hosts South America's largest flexible packaging converter capacity for institutional condiment applications.
Spreads and Toppings Packaging Market Competitive Environment
Top-tier vendors anchor global flexible film supply, while mid-scale regional converters serve private-label procurement consolidation. The market structure splits between multinational material science platforms and specialized European paper-based barrier developers. Three archetypes dominate: integrated resin-to-film producers, rigid container specialists with blow-molding scale, and sustainability-focused substrate innovators. Competitive moves concentrate on mono-material line conversions ahead of regulatory deadlines and strategic partnerships with foodservice distributors seeking national filling capacity.
Within the integrated multinational tier, Amcor Plc and Berry Global Group exemplify divergent strategic positions. Amcor leverages global coextrusion footprint to serve both premium artisanal brands and cost-optimized private-label tiers simultaneously. Berry anchors North American rigid container supply through injection and blow-molding scale for high-viscosity spreads. Mondi Plc occupies a distinct position among European-based specialists, representing the paper-based barrier archetype targeting retailer sustainability mandates.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Group |
| Mondi Plc |
| Sealed Air Corporation |
| Constantia Flexibles |
| Clondalkin Group |
| Wipak |
| Scholle IPN |
| Ropak |
| Others |
Value Chain & Pricing Dynamics
Ethylene vinyl alcohol resin indices in Northeast Asia cascade directly into converter cost structures, forcing tiered pricing stratification across premium barrier laminates and cost-optimized mono-material alternatives as procurement teams rebalance shelf-life performance against recyclability mandates.
Pricing Analysis
Bundled converter services encompassing barrier certification and migration testing command premiums over unbundled substrate-only supply. Three-tier pricing structure across premium artisanal, standard retail, and economy private-label levels reflects EVOH content and FDA notification status. Pricing pressure stems from EU Single-Use Plastics Directive compliance deadlines accelerating mono-material line conversions. Private-label discounter chains in Germany exhibit highest price sensitivity, while premium nut butter subscription brands tolerate elevated per-unit costs for extended oxygen barrier performance.
Supply Chain Analysis
EU packaging waste regulations and emerging domestic-content preferences in India are reshaping sourcing patterns for multinational converters. Barrier resin production clusters in Japan, South Korea, and China feed regional film extrusion capacity. Raw material dependencies center on ethylene vinyl alcohol copolymers, polypropylene homopolymers, and metallized polyethylene terephthalate substrates. Single-source vulnerability concentrates in EVOH supply given limited global producers. Distribution runs through foodservice distributor networks and retail private-label procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phase-downs and extended producer responsibility frameworks continuously reshape material specifications and demand patterns.
For Market Incumbents: Anchor North American rigid container capacity through blow-molding scale investments while accelerating mono-material polyethylene line qualifications for European private-label compliance. Defend against specialty paper-based barrier entrants by securing retailer sustainability partnership exclusivity. Prioritize FDA food-contact notification pipeline expansion to maintain multilayer flexibility for oxygen-sensitive nut butter segments. For New Entrants and Emerging Players: Foodservice group purchasing organizations represent the most penetrable channel anchor for portion-controlled sachet volume. Target South Asian aerosolized toppings segments where compressed gas valve compatibility gaps persist. Pursue digital printing convergence for artisanal brand micro-batch customization as the primary go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with European paper-based barrier specialists possessing retailer sustainability mandate alignment. Five-to-ten-year viability hinges on deposit-return scheme infrastructure capture and closed-loop material recovery economics. Monitor EU member state implementation timelines for packaging collection mandates as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Conversion | EU Single-Use Plastics Directive compliance secures retailer procurement eligibility ahead of enforcement deadlines. |
| Barrier Certification Investment | FDA notification pipeline acceleration reduces 12-18 month approval delays for novel adhesive formulations. |
| Foodservice Distributor Partnership | Group purchasing organization alignment captures institutional condiment volume in healthcare and education channels. |
| Compressed Gas Valve Development | F-Gas Regulation phase-down compatibility positions aerosolized topping suppliers for 2030 prohibition timelines. |
| Digital Printing Integration | Variable-data inkjet capability collapses minimum order quantities for artisanal brand micro-batch requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged flexible packaging converters, foodservice procurement directors at group purchasing organizations, retail private-label category managers, and regulatory affairs specialists at barrier resin manufacturers. Secondary validation drew from FDA food-contact substance notification databases, EU REACH registration dossiers, BIS packaging standard publications, and trade flow data for ethylene vinyl alcohol copolymers. Bottom-up volume modeling triangulated against top-down market sizing across substrate types.
Comparable historical periods anchored the projection framework to pre-pandemic baseline demand patterns and post-regulatory-announcement supply responses. Segmentation dimensions spanned packaging format, material substrate, closure type, and end-user channel across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating EVOH price volatility and logistics cost indices. Industry-specific inputs included EU member state transposition timelines for extended producer responsibility and foodservice procurement consolidation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluorinated chemistry substitution breakthroughs and deposit-return scheme infrastructure buildout pace. Assumptions reflect current regulatory enforcement calendars and converter capacity expansion announcements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Cake Box Market