
 Account-Based Direct Mail Software Market | 2026-2036
Account-Based Direct Mail Software Market Size, Share, and Industry Trends Forecast 2026-2036
Account-Based Direct Mail Software Market Outlook
AI-driven personalization engines are recalibrating cost structures in account-based direct mail as predictive content generation replaces manual creative workflows. Demandbase leverages deep CRM integration to anchor enterprise deployments across Fortune 500 technology accounts. Terminus sustains competitive positioning through proprietary intent-data layering that connects digital signals to physical mail triggers. Sendoso controls the gifting-and-mail hybrid segment, occupying a defensible niche where dimensional mailers outperform flat postcard campaigns.
Account-based direct mail software orchestrates targeted physical mail campaigns triggered by account-level digital intent signals, typically integrating with CRM and marketing automation stacks via REST APIs or native connectors that synchronize prospect data in near-real time. The platform's core industrial purpose centers on converting anonymous B2B engagement into attributable pipeline by bridging online behavior with offline tactile touchpoints. Cloud-based delivery models dominate current deployments due to faster implementation cycles and lower infrastructure overhead, while personalization engines capture disproportionate R&D investment as buyers prioritize dynamic content assembly over static template libraries. API integration capabilities increasingly determine vendor selection, since marketing operations teams require seamless bi-directional data flows between direct mail platforms and existing martech ecosystems.
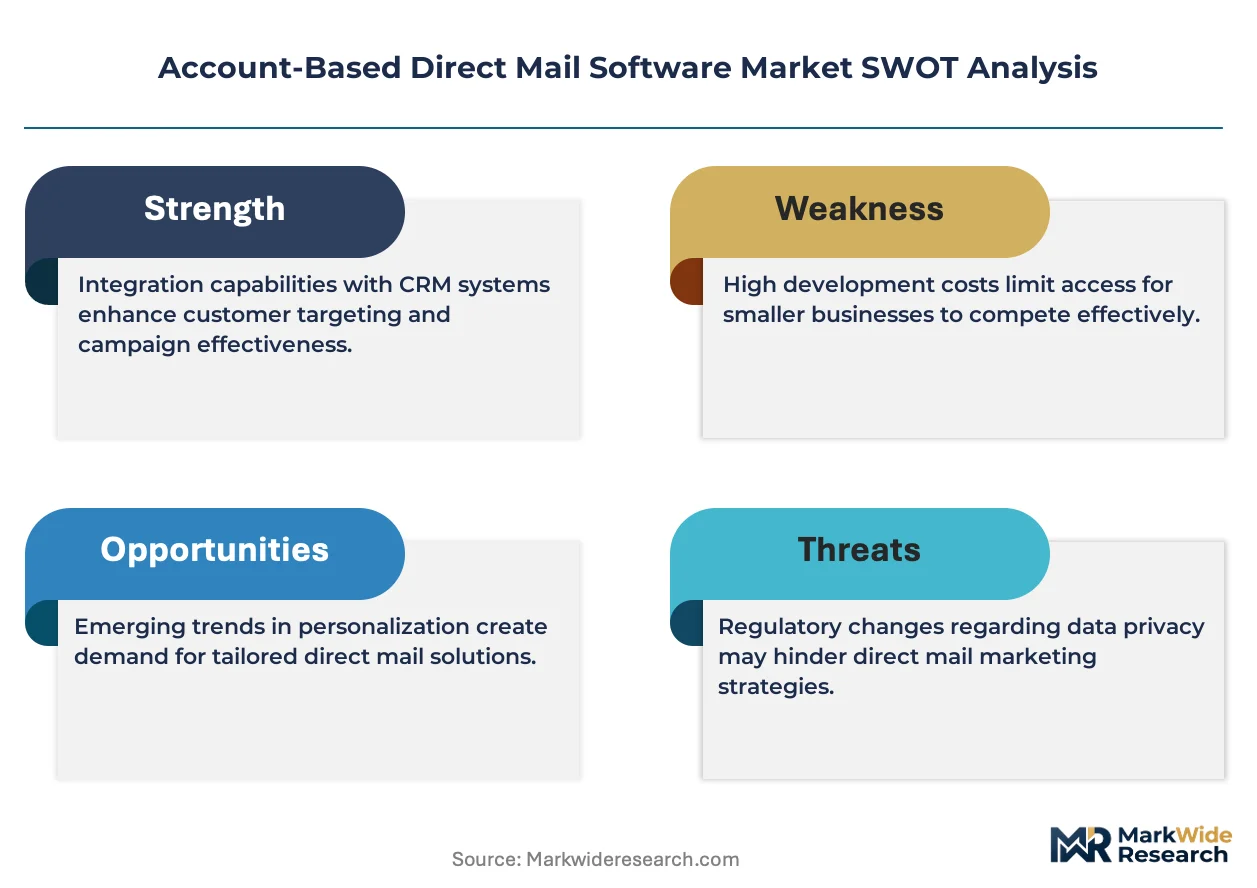
The EU AI Act imposes transparency obligations on automated content generation used in European direct mail campaigns, compelling vendors to document algorithmic decision-making for personalized offers. In the United States, the FTC's truth-in-advertising standards and state-level privacy statutes such as CCPA shape data handling practices for prospect lists and attribution tracking. HIPAA constrains how healthcare-focused direct mail vendors process protected health information when targeting hospital procurement committees or clinical decision-makers. Stakeholders must monitor evolving AI disclosure mandates and cross-border data transfer restrictions to preserve campaign execution capabilities without compliance friction.
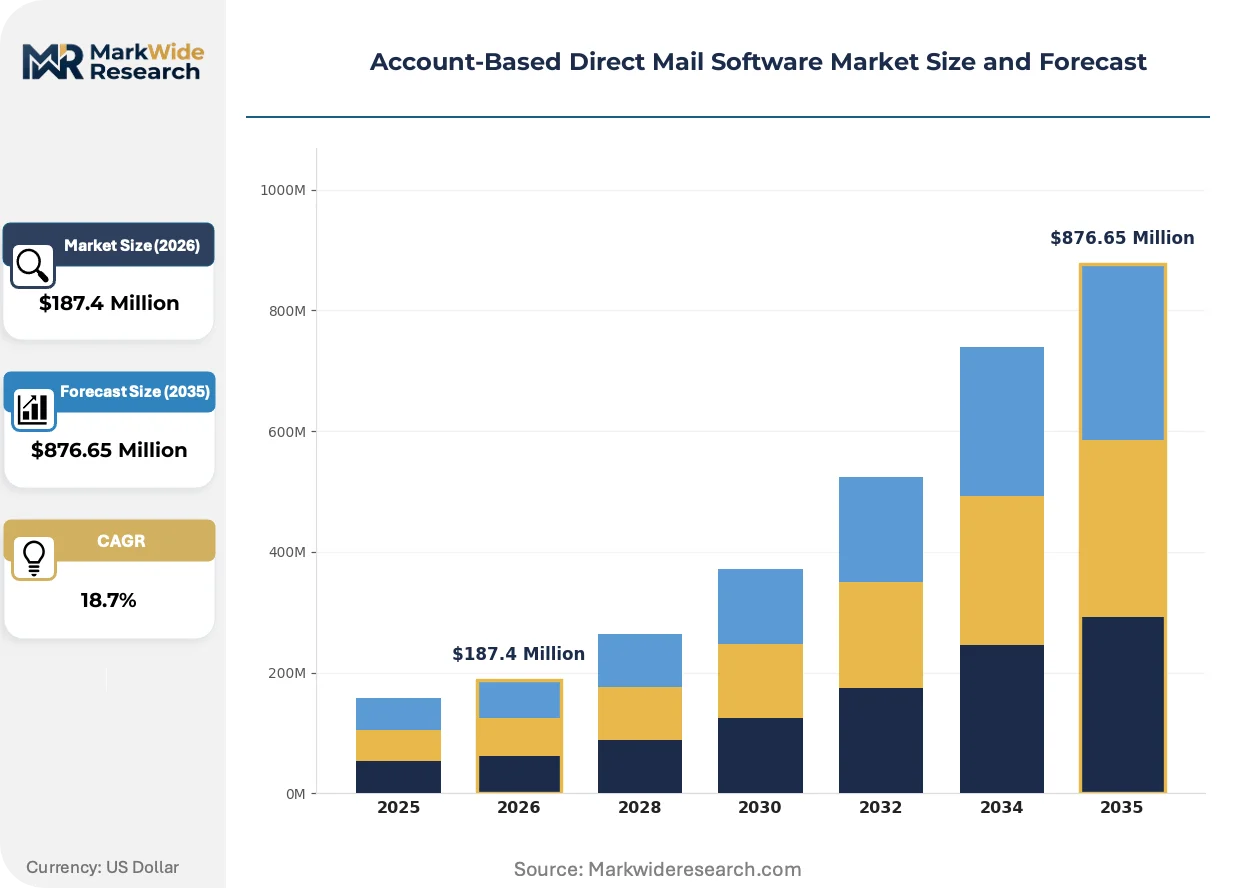
Market Dynamics
AI-powered personalization engines are compressing creative production cycles from weeks to hours, forcing vendors to restructure service margins around automation rather than manual design labor. The EU AI Act's transparency mandates and HIPAA's data handling constraints in healthcare are simultaneously expanding compliance infrastructure costs while creating vendor differentiation through certified workflows.
Growth Catalysts
- EU AI Act disclosure requirements:Automated content generation systems must document algorithmic decision-making, creating demand for audit-ready direct mail platforms in European financial services and healthcare.
- Financial services procurement committees:Enterprise buyers in banking and insurance are expanding physical mail budgets as dimensional mailers demonstrate higher meeting conversion rates than digital-only sequences.
- REST API standardization:Bi-directional CRM synchronization capabilities are becoming table stakes, with marketing operations teams prioritizing vendors offering native Salesforce and HubSpot connectors.
Market Restraints
- Paper and postage cost volatility:Input cost swings in pulp commodities and USPS rate adjustments compress margins for flat postcard campaigns that cannot absorb price shocks through premium positioning.
- Vendor concentration in cloud infrastructure:AWS and Azure dominance in direct mail platform hosting creates single-supplier risk for campaign execution continuity during regional outages.
- Static template libraries:Legacy content repositories lacking dynamic assembly capabilities face displacement by predictive generation engines, stranding sunk development costs.
Strategic Opportunities
- German mid-market manufacturing:Industrial automation and precision engineering clusters show underpenetrated demand for account-based physical touchpoints supporting long sales cycles.
- Healthcare procurement targeting:Hospital committee decision-making processes present emerging application white space where HIPAA-compliant dimensional mailers can bypass digital gatekeepers.
- AI-physical convergence:Predictive content generation combined with variable data printing creates personalization depth previously requiring manual creative teams.
Industry Challenges
- Marketing operations talent scarcity:Professionals capable of orchestrating bi-directional API flows between direct mail platforms and martech stacks command premium compensation, constraining vendor implementation capacity.
- CCPA and state privacy patchwork:California's data handling requirements and emerging state statutes create compliance timeline fragmentation, forcing multi-jurisdictional campaign architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Account-Based Direct Mail Software Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automation Software, Data Management Tools, Personalization Engines, Analytics Platforms Delivery Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Marketing Agencies, E-Commerce Businesses, Financial Services, Healthcare Providers Integration Level: API Integration, CRM Integration, Third-Party Tools, Custom Integrations |
| Companies Covered | Demandbase, Terminus, Sendoso, Gundir, Postalytics, Reachdesk, RollWorks, SeQuel Response, Postal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Account-Based Direct Mail Software Market Strategic Shifts
Predictive content generation and automated fulfillment orchestration are compressing the gap between digital intent signals and physical mail delivery, reshaping how enterprise marketing teams attribute pipeline to offline channels.
Variable data printing integrated with real-time CRM triggers is consolidating campaign production around single-platform workflows that eliminate manual list exports and creative handoffs. Fortune 500 technology buyers are adopting these systems fastest, demanding sub-48-hour execution windows from intent spike to mailbox delivery. The technology is consolidating vendor market positions around those offering end-to-end automation rather than point solutions requiring manual intervention.
The EU AI Act's algorithmic transparency obligations are forcing direct mail vendors serving European accounts to document automated decision-making in personalized offer generation. Industrial consequence includes mandatory audit trails for content variation logic and recipient selection criteria. Financial services campaigns targeting EU prospects face the steepest compliance burden, with vendors responding through dedicated European data residency and explainable AI documentation modules.
Enterprise procurement teams are unbundling creative services from platform subscriptions, shifting toward self-service content assembly with vendor support limited to technical integration. The agency retainer model for direct mail creative is losing share to usage-based SaaS pricing with dynamic template libraries. This pattern is most visible in United States technology and healthcare verticals where marketing operations teams possess sufficient technical depth to manage campaign architecture internally.
Account-Based Direct Mail Software Market Segmentation
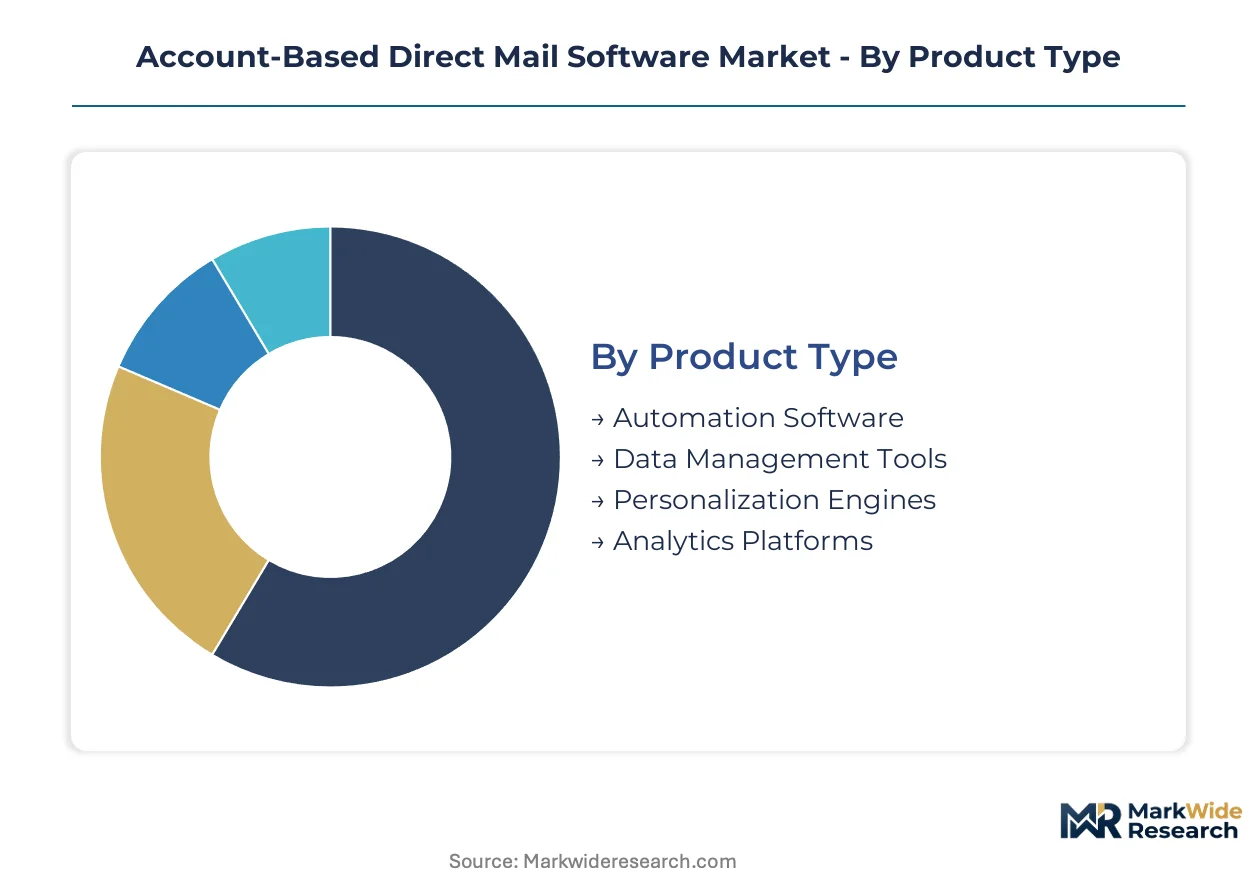
Account-based direct mail software segments by functional layer, revealing where buyers allocate budget between automation infrastructure and intelligence capabilities. Deployment choices reflect organizational martech maturity and regulatory exposure.
Product Type:
Volume deployments favor automation utilities, while premium positioning concentrates in intelligence layers that compress creative cycles.
- Automation Software:Orchestrates trigger-based campaign execution, list synchronization, and fulfillment routing through REST API endpoints. Demand concentrates in United States technology verticals where marketing operations teams require sub-48-hour intent-to-mailbox execution windows.
- Personalization Engines:Deploys predictive content generation and dynamic variable data assembly to replace manual creative workflows. Financial services procurement committees in North America allocate disproportionate budget here as dimensional mailers demonstrate superior meeting conversion rates against static templates.
- Data Management Tools:Govern prospect list hygiene, deduplication, and compliance-scoped data residency for cross-border campaigns.
- Analytics Platforms:Attribute pipeline contribution through multi-touch sequence tracking and offline-to-online conversion mapping.
Mature deployment sits with Automation Software. Newer deployment is concentrated in Personalization Engines.
Delivery Model:
Cloud-native architectures dominate procurement cycles, though regulated verticals retain on-premises footprints for data sovereignty.
- Cloud-Based:Delivers browser-accessible campaign management with automatic infrastructure scaling and vendor-managed security patching. United States healthcare providers favor this model for HIPAA-scoped deployments where Business Associate Agreements streamline compliance documentation.
- SaaS:Bundles subscription pricing with usage-based fulfillment orchestration and native CRM connectors. European financial services under EU AI Act transparency mandates demand this delivery mode for audit-ready algorithmic documentation.
- On-Premises:Retains physical infrastructure control for air-gapped environments and classified procurement workflows.
- Hybrid:Segregates sensitive prospect data on local servers while pushing creative rendering to cloud compute.
Cloud-Based delivery captures the steepest expansion trajectory as implementation timelines compress from quarters to weeks.
End User:
Customer type determines integration complexity and content personalization depth requirements.
- Financial Services:Deploys dimensional mailers to procurement committees with strict audit trail requirements for algorithmic content selection. German banking clusters show emerging demand as relationship managers seek tactile differentiation in saturated digital channels.
- Marketing Agencies:Manages multi-client campaign architectures through white-labeled platform instances with segregated data tenancy.
- Healthcare Providers:Targets hospital procurement committees with HIPAA-compliant physical touchpoints that bypass digital gatekeepers.
- E-Commerce Businesses:Activates account-based sequences for high-value B2B accounts within otherwise transactional operations.
Financial Services anchors current revenue concentration. Healthcare Providers are climbing the fastest as procurement targeting white space opens.
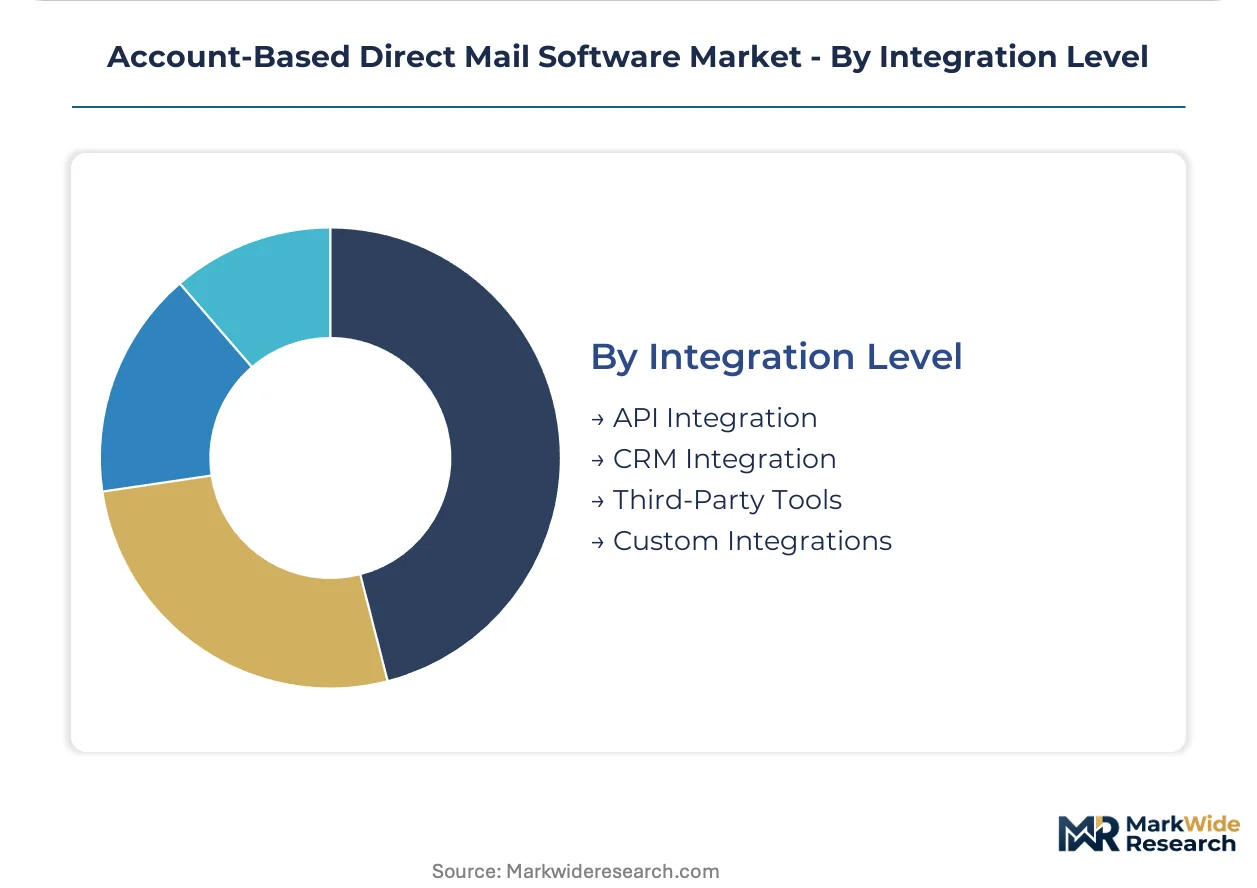
Integration Level:
Bi-directional data flow capabilities increasingly determine vendor selection and implementation success.
- API Integration:Enables custom webhook architectures and event-driven campaign triggers beyond native connector libraries.
- CRM Integration:Synchronizes prospect records, opportunity stages, and engagement history through native Salesforce and HubSpot connectors. United States enterprise technology buyers treat this as non-negotiable table stakes.
- Third-Party Tools:Bridges intent data platforms, ABM orchestration layers, and marketing automation stacks.
- Custom Integrations:Addresses legacy ERP connections and proprietary data warehouses through professional services engagements.
CRM Integration represents the most mature deployment pattern. API Integration is gaining share fastest as technical marketing operations teams seek flexibility beyond vendor-native connectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise technology buyers in the United States command the largest share of account-based direct mail software procurement, driven by integrated CRM-to-physical-mail workflows and compressed intent-to-mailbox execution timelines. Financial services clusters in Germany and healthcare procurement networks in the United Kingdom are accelerating adoption as dimensional mailers demonstrate superior conversion rates against saturated digital channels.
United States
Fortune 500 technology accounts and financial services procurement committees dominate deployment volumes, with marketing operations teams demanding sub-48-hour execution windows from intent spike to mailbox delivery. The FTC's truth-in-advertising standards and state-level CCPA privacy statutes shape data handling practices for prospect lists and attribution tracking. Silicon Valley and New York Metro clusters anchor premium-tier adoption, where bi-directional Salesforce and HubSpot integration capabilities determine vendor selection.
Germany
Industrial automation and precision engineering clusters in Bavaria and Baden-Württemberg show underpenetrated demand for account-based physical touchpoints supporting long sales cycles in manufacturing procurement. The EU AI Act imposes transparency obligations on automated content generation, compelling vendors to document algorithmic decision-making for personalized offers. Frankfurt banking clusters are expanding dimensional mailer budgets as relationship managers seek tactile differentiation.
United Kingdom
Healthcare providers targeting hospital procurement committees represent the fastest-climbing vertical, with HIPAA-equivalent NHS data governance frameworks constraining how vendors process patient-adjacent targeting data. GDPR and emerging UK data protection statutes create compliance timeline fragmentation for cross-border campaign architecture. London's fintech corridor sustains enterprise deployment density, though procurement teams are unbundling creative services from platform subscriptions.
Japan
Marketing operations teams in Tokyo and Osaka are adopting cloud-native delivery models for faster implementation cycles, though on-premises retention persists in regulated verticals requiring data sovereignty. METI's digital transformation incentives accelerate martech stack modernization, creating pull-through demand for API-integrated direct mail orchestration. Manufacturing keiretsu procurement networks in Nagoya present emerging application white space for dimensional mailers bypassing traditional gatekeepers.
Australia
New South Wales and Victoria-based enterprise buyers prioritize SaaS delivery models with usage-based fulfillment orchestration, reflecting marketing operations team preferences for self-service content assembly. The TGA's therapeutic goods advertising codes and state-level privacy frameworks constrain healthcare-focused direct mail targeting of clinical decision-makers. Sydney's financial services corridor anchors regional demand, with bi-directional CRM synchronization treated as non-negotiable table stakes.
Account-Based Direct Mail Software Market Competitive Environment
Branded specialists and contract fulfillment providers split share differently across segments, with cloud-native platform vendors capturing premium positioning through end-to-end automation while point solution providers face margin compression from manual workflow displacement. The vendor base concentrates around three strategic archetypes: CRM-anchored enterprise suites, intent-data-layering specialists, and gifting-mail hybrid operators. Competitive moves center on API ecosystem expansion and European data residency certification to capture EU AI Act compliance budgets.
Within the CRM-anchored enterprise tier, Demandbase and Terminus exemplify positioning through deep platform integration and proprietary intent-data architectures respectively. Sendoso occupies a defensible niche in the gifting-and-mail hybrid segment where dimensional mailers outperform flat postcard campaigns. These three vendors represent the dominant competitive anchors against which procurement teams evaluate bi-directional synchronization capabilities and sub-48-hour execution reliability.
| Leading Market Players |
|---|
| Demandbase |
| Terminus |
| Sendoso |
| Gundir |
| Postalytics |
| Reachdesk |
| RollWorks |
| SeQuel Response |
| Postal |
| Others |
Value Chain & Pricing Dynamics
EU AI Act transparency mandates gate qualified supplier status and premium-tier pricing access for account-based direct mail platforms serving European financial services. Vendors lacking algorithmic audit documentation face exclusion from procurement cycles, compressing margins for non-compliant players while certified providers capture pricing power.
Pricing Analysis
Volume deployments favor flat postcard automation utilities with thin margins, while premium positioning concentrates in personalization engines where dimensional mailer campaigns command substantial markups. Price differentiation hinges on API integration depth and HIPAA compliance certification for healthcare verticals. Cost compression in commodity postcard tiers is intensifying because paper and postage volatility cannot be passed through to price-sensitive mid-market buyers. Marketing agencies exhibit highest price sensitivity due to multi-client cost allocation pressures, whereas Fortune 500 technology accounts prioritize execution speed over unit economics.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts viable cloud infrastructure partners to established hyperscalers, concentrating platform hosting dependencies. Supply concentrates in the United States for CRM-anchored software development, Germany for precision printing equipment, and China for variable data printing hardware components. Raw material dependencies span pulp commodities for dimensional substrates, cloud compute capacity from AWS and Azure, and intent-data licensing from specialized providers. Single-supplier vulnerability in cloud infrastructure creates campaign execution continuity risk during regional outages. Distribution runs through direct vendor sales teams for enterprise accounts and value-added resellers serving mid-market marketing operations teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around automation-native platforms as manual workflow displacement eliminates point-solution providers. AI-powered personalization engines are forcing weaker players toward acquisition or exit.
For Market Incumbents: Hedge against margin erosion in static template libraries by deepening API ecosystem partnerships with Salesforce and HubSpot. Acquire intent-data layering capabilities to defend against Terminus-style positioning, while investing in European data residency infrastructure to capture EU AI Act compliance budgets from Frankfurt banking clusters. For New Entrants and Emerging Players: Predictive content generation capabilities offer technology-first wedge opportunity against legacy creative service bundles. German mid-market manufacturing presents most penetrable geography with underpenetrated account-based physical touchpoint demand. Pursue white-label platform partnerships with regional marketing agencies lacking technical integration depth. For Investors and Strategic Acquirers: First-mover HIPAA certification among direct mail vendors is the leading indicator that healthcare procurement targeting white space is maturing toward platform consolidation. Long-term viability favors vendors with end-to-end automation rather than creative service dependencies. Monitor AWS and Azure regional outage frequency as inflection signal for infrastructure diversification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Native Salesforce and HubSpot connectors determine vendor selection for United States enterprise technology buyers. |
| European Data Residency Certification | EU AI Act compliance budgets from Frankfurt banking clusters require algorithmic audit documentation modules. |
| HIPAA-Compliant Workflow Development | Hospital procurement committee targeting opens dimensional mailer white space bypassing digital gatekeepers. |
| Predictive Content Generation Investment | Dynamic variable data assembly displaces manual creative workflows and compresses production cycles. |
| Intent-Data Layering Acquisition | Proprietary signal architectures connect digital engagement spikes to physical mail triggers for attribution. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across marketing operations directors, CRM integration specialists, direct mail platform engineers, healthcare procurement managers, and financial services relationship leads. SEC 10-K disclosures from publicly traded martech vendors, EU AI Act implementation guidance, FTC truth-in-advertising enforcement records, and USPS postage rate filings provided quantitative scaffolding. Bottom-up deployment estimates triangulated against top-down addressable market calculations.
Granularity-level modeling tracked cloud versus on-premises delivery modes, automation software versus personalization engine functional layers, and API integration depth across deployment segments. CAGRs derived from logistic adoption curves fitted to enterprise technology buyer penetration patterns, financial services procurement committee budget allocations, and healthcare provider dimensional mailer pilot expansions. Pricing trajectories incorporated paper commodity volatility indices and cloud infrastructure cost trends.
Several conditions sit outside the modeled scope, including vendor-specific patent litigation outcomes, USPS operational restructuring scenarios, and hyperscaler pricing regime shifts. Forecasts reflect assumptions regarding sustained REST API standardization and stable HIPAA enforcement intensity. A model refresh is warranted upon material change in EU AI Act audit requirement stringency or AWS regional outage frequency thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Business Management Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Yacht Management Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
Vending Software Market
Software & Services
Fiber Simulation Software Market
Software & Services
Global Open Source Services Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Global CMMS Software Market
Software & Services
Mobile Application Development Market
Software & Services
Automotive Customization Software Market
Software & Services
Business Analytics Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Pet Tracking Software Market
Software & Services
Semiconductor Fabrication Software Market