
 Marketing Automation Software Market | 2026-2036
Marketing Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Marketing Automation Software Market Outlook
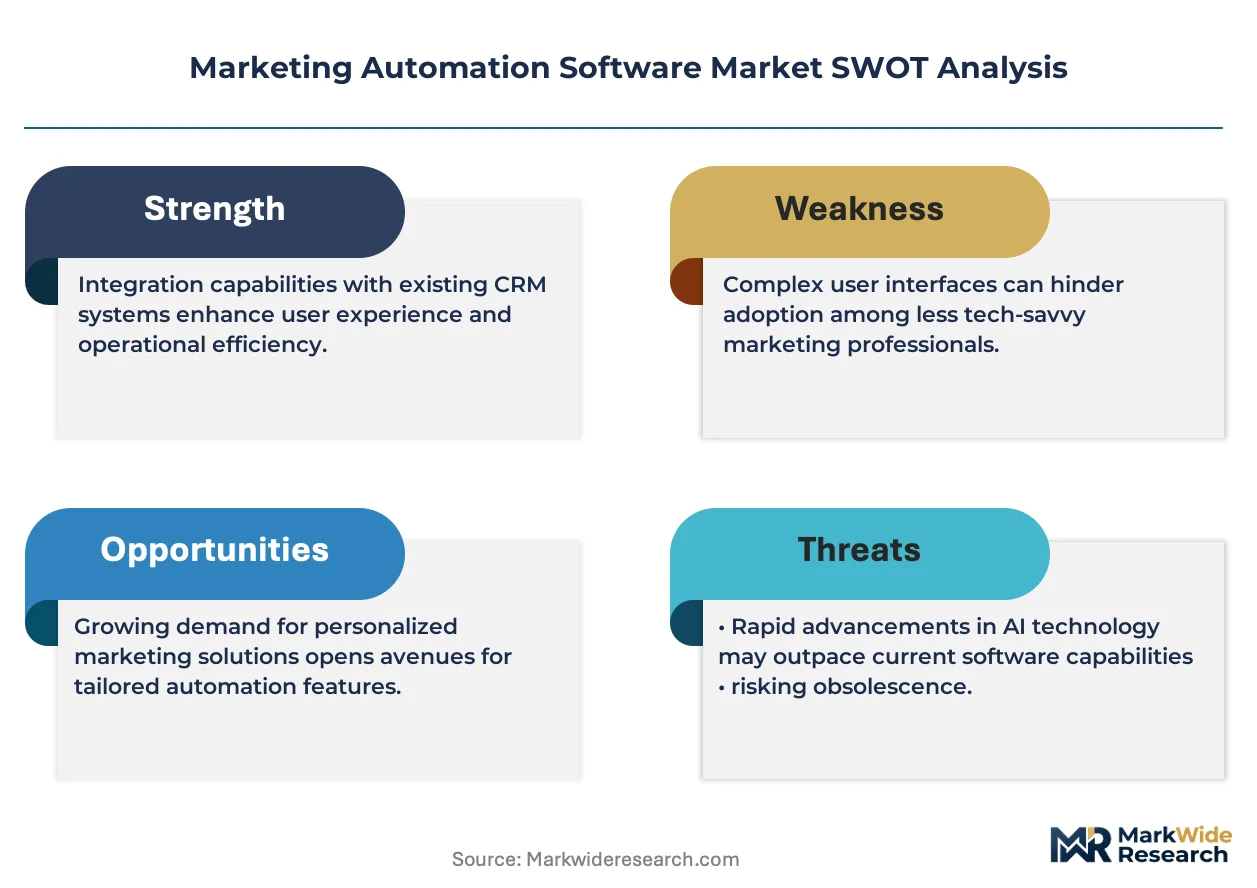
Cloud infrastructure is expanding as the foundational substrate for marketing automation delivery, displacing legacy on-premise installations across mid-market buyers. HubSpot leverages a freemium-to-paid conversion engine that anchors its dominance in SME onboarding funnels. Adobe Marketo Engage competes through deep CRM integration capabilities that sustain enterprise retention rates. Klaviyo specializes in e-commerce data ingestion, occupying a defensible position among direct-to-consumer merchants.
Marketing automation software comprises programmable platforms that orchestrate multi-channel campaign execution, lead scoring, and behavioral trigger management through API-connected data pipelines. These systems process customer interaction events in real time to deliver personalized content across email, SMS, and web properties. Cloud-based deployment leads the solution architecture, with SaaS delivery capturing the fastest expansion as vendors eliminate client-side infrastructure burdens. Email marketing and lead management represent mature margin pools, while CRM integration commands premium pricing due to enterprise system complexity. Analytics functionality within feature sets is accelerating fastest as attribution modeling becomes a procurement priority.
The EU AI Act and GDPR impose algorithmic transparency and consent-management obligations on vendors operating in European jurisdictions, directly shaping product roadmap priorities for compliance engineering. In the United States, the FTC's Section 5 authority over deceptive practices influences how platforms represent AI-powered personalization capabilities to end users. Stakeholders must monitor evolving cross-border data localization requirements as determinants of deployment architecture and market access strategy.
Market Dynamics
Real-time behavioral data pipelines are compressing campaign deployment cycles from weeks to hours, forcing vendors to rearchitect core infrastructure around stream processing rather than batch workflows.
Growth Catalysts
- EU AI Act compliance engineering:The regulation mandates algorithmic transparency for automated decision-making tools, creating procurement pull for vendors with built-in explainability dashboards among European enterprises.
- E-commerce platform expansion:Direct-to-consumer merchants are embedding marketing automation natively into checkout flows, triggering demand for API-first architectures that ingest transactional signals instantly.
- SME SaaS onboarding:Freemium conversion funnels are lowering activation barriers, with self-service workflows capturing mid-market buyers previously priced out of enterprise-tier deployments.
Market Restraints
- Cross-border data localization:Fragmented sovereignty requirements across Germany, France, and the Netherlands force redundant infrastructure investments, elevating total cost of ownership for multi-national deployments.
- Technical talent scarcity:Shortages in machine learning operations engineers constrain vendor roadmap velocity, particularly for real-time personalization engine development.
- Legacy CRM integration friction:Proprietary data schemas in incumbent enterprise systems create switching costs that slow displacement of installed-base vendors.
Strategic Opportunities
- Underpenetrated LATAM markets:Brazil and Mexico exhibit low automation maturity among mid-market retailers, presenting first-mover advantages for localized payment-integrated platforms.
- SMS-channel convergence:The merging of messaging automation with conversational commerce interfaces opens white space for vendors bundling transactional and promotional workflows.
- CSRD disclosure mandates:The EU directive requires marketing carbon footprint reporting, creating demand for sustainability analytics modules that track campaign-level environmental impact.
Industry Challenges
- Attribution modeling complexity:Cross-device identity resolution failures degrade ROI measurement accuracy, eroding client trust in platform-reported performance metrics.
- Consent fatigue management:Repeated GDPR opt-in prompts degrade list quality, forcing investment in preference center infrastructure that preserves engagement without regulatory exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marketing Automation Software Market |
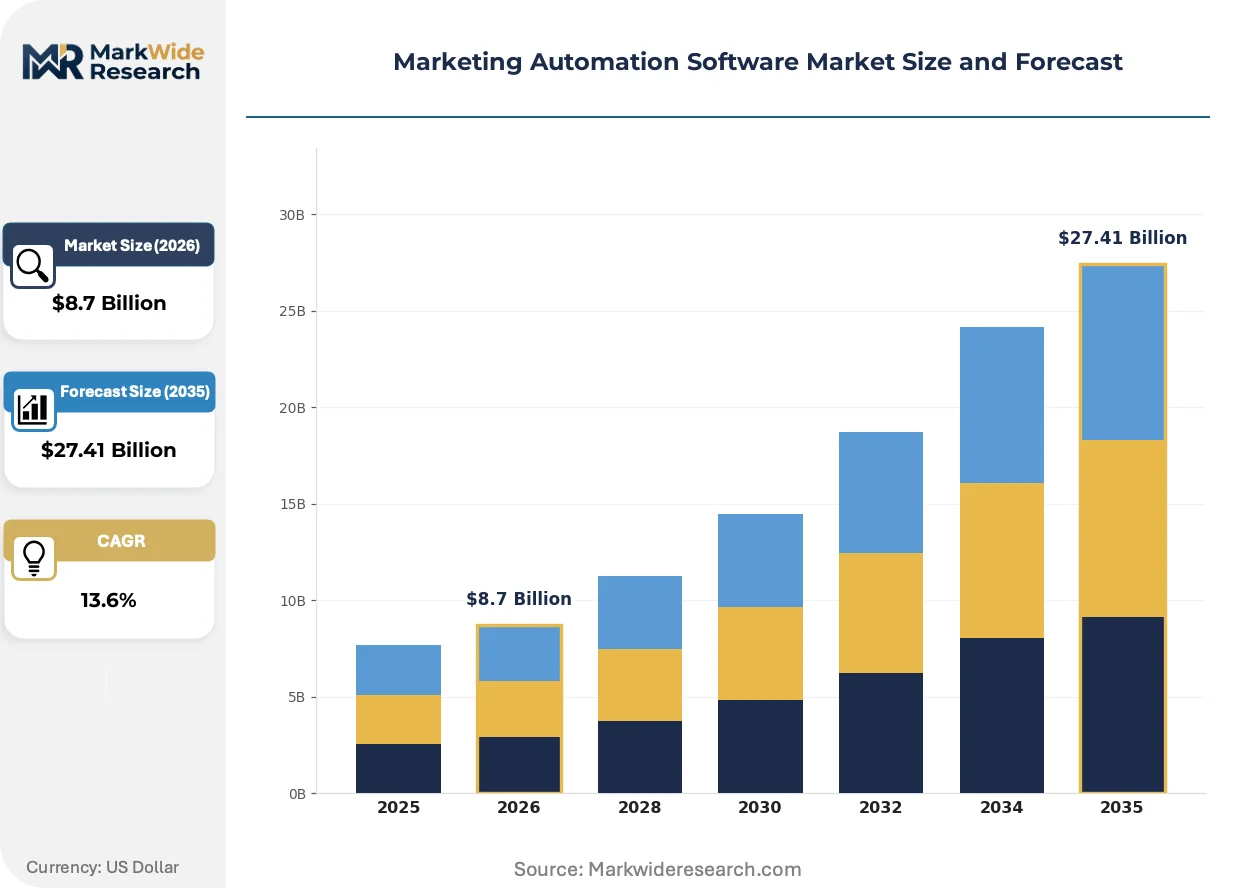
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Agencies, E-Commerce Solution: Email Marketing, Lead Management, Campaign Management, CRM Integration Feature: Analytics, Personalization, Automation, A/B Testing |
| Companies Covered | Brevo, Zapier, HubSpot, Oracle Eloqua, Omnisend, ActiveCampaign, Klaviyo, Adobe Marketo Engage, Mailchimp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marketing Automation Software Market Strategic Shifts
Generative content systems are rewiring how campaigns are assembled, shifting creative production from human-led workflows to algorithmically generated variants tested at scale.
Predictive send-time optimization is automating the matching of message delivery to individual recipient activity patterns. E-commerce merchants deploying these tools report engagement lift without manual segmentation labor. The technology is automating the elimination of blanket broadcast scheduling that treated all subscribers identically.
The EU AI Act's risk-tier classification system imposes documentation burdens on high-risk automated profiling applications. Vendors must now maintain technical files demonstrating human oversight mechanisms. European financial services and healthcare marketing teams are delaying deployments pending legal review of algorithmic decision boundaries.
Subscription-based pricing models are displacing seat-licensed arrangements as the dominant commercial structure. Mid-market buyers prefer consumption-aligned contracts that scale with contact database growth rather than fixed user counts. This shift is most visible among US SaaS-native companies replacing incumbent enterprise agreements.
Marketing Automation Software Market Segmentation
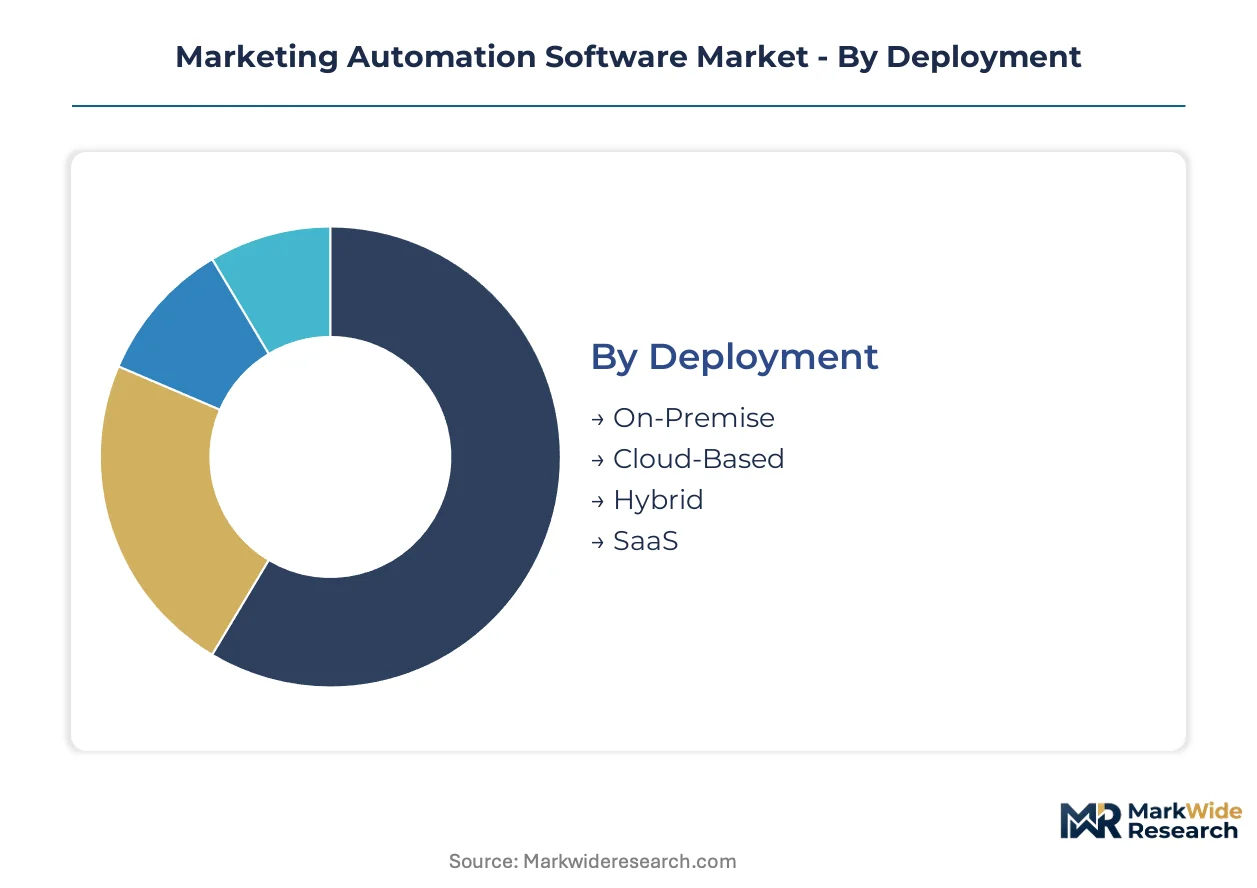
Segmentation in marketing automation software reveals distinct procurement patterns across infrastructure preferences, organizational scale, and functional priorities. Vendors configure pricing architectures and feature bundles differently for each slice, creating tiered margin pools that reward specialization over horizontal coverage.
Deployment:
Cloud-based delivery commands volume leadership while hybrid architectures capture premium pricing from regulated sectors.
- Cloud-Based:Multi-tenant SaaS architectures eliminate client-side infrastructure burdens through API-connected orchestration layers. Demand concentrates among US mid-market retailers and direct-to-consumer merchants seeking rapid activation without capital expenditure. The FTC's Section 5 oversight shapes how vendors represent uptime guarantees and data handling practices to these buyers.
- SaaS:Subscription-native delivery models embed automatic feature updates and elastic scaling into commercial terms. European financial services procurement teams favor these arrangements for EU AI Act compliance documentation, which vendors must maintain as technical files demonstrating algorithmic transparency.
- On-Premise:Single-tenant installations persist in German automotive and French aerospace supply chains where data residency mandates override cloud economics.
- Hybrid:Split architectures separating sensitive customer data on-premise while pushing campaign execution to cloud nodes attract healthcare marketing teams under HIPAA jurisdiction.
Mature deployment sits with On-Premise. Newer deployment is concentrated in SaaS.
End User:
Organizational scale determines feature complexity thresholds and integration depth requirements.
- Large Enterprises:Global marketing operations demand real-time behavioral data pipelines connecting CRM, ERP, and proprietary data lakes. Procurement in the United States prioritizes Adobe and Salesforce ecosystem compatibility over standalone best-of-breed capabilities.
- E-Commerce:Direct-to-consumer merchants require instantaneous transactional signal ingestion from checkout flows into trigger-based messaging sequences. Klaviyo and similar specialists dominate this segment through Shopify and WooCommerce native integrations.
- SMEs:Self-service onboarding with freemium conversion funnels lowers activation barriers for marketing teams under ten employees.
- Agencies:Multi-tenant management consoles enabling client segregation and white-label reporting support account-based pricing models.
Revenue concentration favors Large Enterprises. Steepest expansion trajectory belongs to E-Commerce.
Solution:
Functional modules compete for platform centrality based on integration dependencies and margin sustainability.
- CRM Integration:Bidirectional synchronization between marketing automation and customer record systems commands premium pricing due to enterprise system complexity. Salesforce and Microsoft Dynamics connectors represent mandatory table stakes for US enterprise procurement evaluations.
- Email Marketing:Programmable send-time optimization and deliverability infrastructure form mature margin pools with established vendor consolidation. GDPR consent fatigue has degraded list quality, forcing investment in preference center architecture.
- Lead Management:Scoring algorithms and nurture sequence builders attract B2B technology vendors with extended sales cycles.
- Campaign Management:Cross-channel orchestration across email, SMS, and web properties demands real-time stream processing rather than batch workflows.
Margin stability sits with Email Marketing. Capability investment concentrates in CRM Integration.
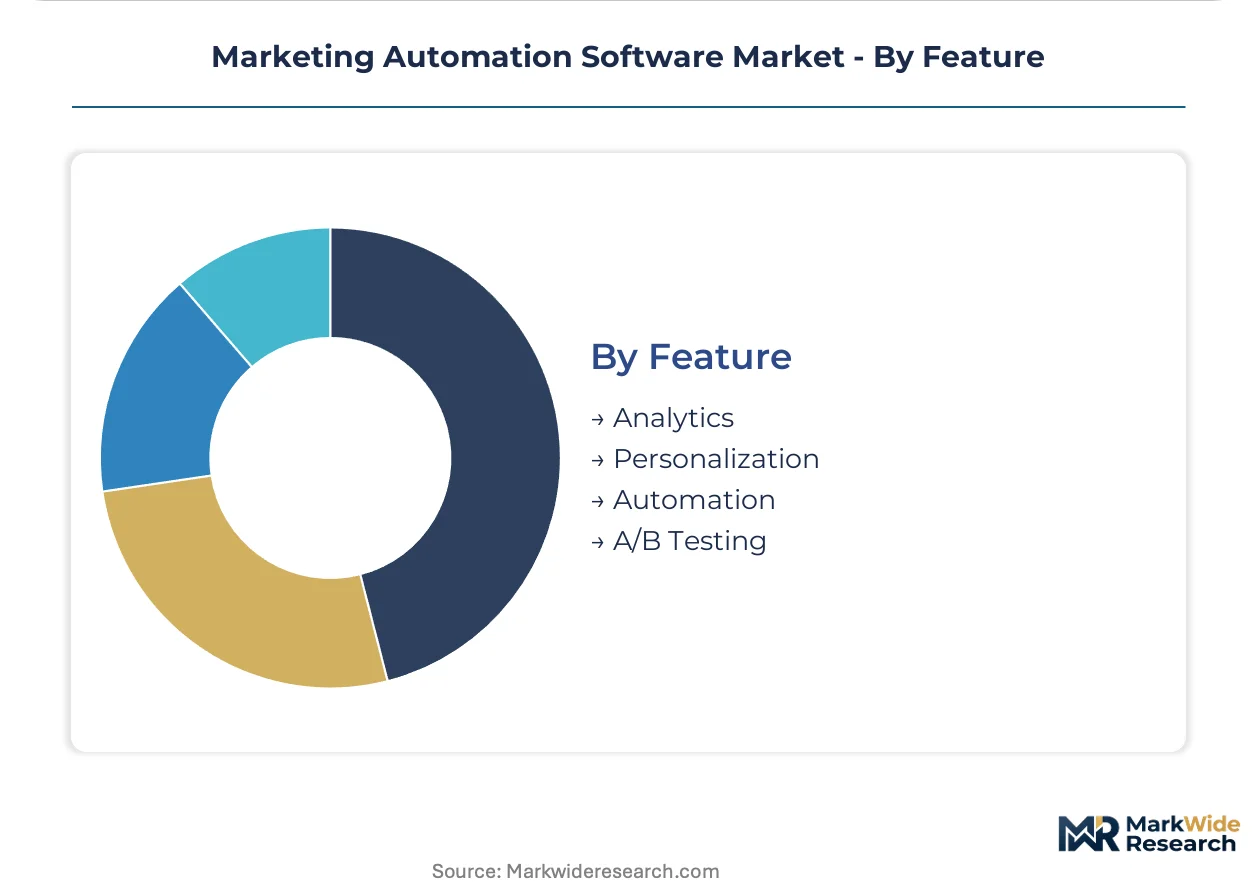
Feature:
Technical sophistication tiers separate commodity functionality from differentiated platform value.
- Analytics:Attribution modeling and cross-device identity resolution are accelerating fastest as procurement priorities, though measurement accuracy erosion from cookie deprecation creates client trust challenges. Vendors investing in probabilistic matching and media mix modeling capture evaluation shortlists.
- Personalization:Generative content systems now assemble campaign variants algorithmically, shifting creative production from human-led workflows to machine-scale testing. EU AI Act risk-tier classifications impose documentation burdens on high-risk automated profiling applications.
- Automation:Visual workflow builders with conditional branching remain standard across all vendor tiers.
- A/B Testing:Multi-armed bandit algorithms for dynamic traffic allocation differentiate advanced platforms from basic split-test tooling.
Commoditization pressure sits with Automation. Differentiation investment flows to Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software demand concentrates in jurisdictions offering R&D tax credits and digital infrastructure incentives. The United States leads SaaS procurement volume through Section 174 R&D expenditure treatment. European compliance costs reshape vendor go-to-market economics.
United States
FTC Section 5 enforcement shapes how vendors represent AI-powered personalization capabilities to enterprise buyers. The agency's deceptive practices authority constrains marketing claims around automated decision-making tools. Silicon Valley and Boston anchor venture-backed automation startups targeting mid-market retailers with freemium conversion engines.
Germany
Data localization mandates in automotive supply chains sustain on-premise installation demand despite cloud economics. KBA transportation data regulations intersect with marketing automation for mobility services. Stuttgart and Munich host industrial marketing teams requiring hybrid architectures separating sensitive customer data from campaign execution nodes.
United Kingdom
Financial services procurement prioritizes explainability dashboards ahead of algorithmic transparency requirements. The Financial Conduct Authority's operational resilience rules influence marketing system uptime specifications. London's fintech marketing clusters drive demand for real-time behavioral data pipelines connecting transactional signals to trigger-based messaging.
France
CNIL consent-management enforcement degrades email list quality, forcing investment in preference center infrastructure. ANSM pharmaceutical marketing rules constrain automated profiling in healthcare segments. Parisian luxury houses deploy personalization engines for clienteling workflows, navigating EU AI Act risk-tier classifications for high-risk automated profiling.
Japan
METI digital transformation subsidies accelerate SME SaaS adoption among traditional retailers. Personal Information Protection Commission guidelines shape cross-border data transfer architectures for multinational deployments. Tokyo's direct-to-consumer merchant ecosystem demands API-first platforms ingesting transactional signals from e-commerce checkout flows.
Marketing Automation Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with SaaS-native vendors capturing mid-market volume while legacy enterprise suites retain installed-base relationships. The vendor landscape organizes around three strategic archetypes: freemium conversion engines, API-first commerce specialists, and ecosystem-integrated enterprise platforms. Consolidation pressure concentrates among mid-tier players lacking vertical specialization or distribution density. Dominant competitive moves include strategic partnerships with e-commerce platforms and geographic expansion through localized payment integrations.
Within the freemium conversion tier, HubSpot and ActiveCampaign exemplify self-service onboarding models that reduce customer acquisition costs for sub-ten-employee marketing teams. Klaviyo anchors the API-first commerce specialist archetype, occupying a defensible position among direct-to-consumer merchants requiring instantaneous transactional signal ingestion. Adobe Marketo Engage sits within the ecosystem-integrated enterprise platform category, representing deep CRM synchronization capabilities that sustain retention among global marketing operations with complex system interdependencies.
| Leading Market Players |
|---|
| Brevo |
| Zapier |
| HubSpot |
| Oracle Eloqua |
| Omnisend |
| ActiveCampaign |
| Klaviyo |
| Adobe Marketo Engage |
| Mailchimp |
| Others |
Value Chain & Pricing Dynamics
SaaS-native freemium tiers diverge sharply from enterprise contract bundles, compressing mid-market margins while inflating premium pricing for CRM-integrated suites. This bifurcation manifests in cloud infrastructure concentration among US hyperscalers and API-first architectures that eliminate client-side hardware dependencies.
Pricing Analysis
Volume concentrates in self-serve subscription tiers while margin pools in enterprise CRM-integrated deployments. SaaS consumption-based contracts displace seat-licensed arrangements, with mid-market buyers preferring elastic scaling tied to contact database growth. Price differentiation hinges on integration complexity and EU AI Act compliance documentation. Pricing pressure stems from freemium conversion funnel economics eroding activation costs. SMEs exhibit highest price sensitivity; global marketing operations with proprietary data lakes show lowest.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate qualification across AWS, Microsoft Azure, and Google Cloud Platform to ensure failover resilience. Geographic supply concentration centers on US West Coast hyperscale regions, Irish and Frankfurt data centers for EU data residency, and Singapore nodes for Asia-Pacific latency optimization. Raw material dependencies include GPU compute clusters, solid-state storage arrays, and fiber-optic interconnects. Supply chain risk concentrates in single-source vulnerability for specialized machine learning accelerators. Distribution runs through direct vendor sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration races dominate competitive dynamics as vendors pursue upstream control over data pipeline infrastructure and downstream embedding into e-commerce checkout flows.
For Market Incumbents: To counter freemium-native entrants capturing SME onboarding funnels, deepen API ecosystem partnerships with Shopify and WooCommerce while accelerating EU AI Act compliance engineering to sustain European enterprise retention. For New Entrants and Emerging Players: Begin with underpenetrated LATAM mid-market retailers in Brazil and Mexico, offering localized payment-integrated platforms with Portuguese and Spanish language support to bypass saturated North American competition. For Investors and Strategic Acquirers: Re-rating potential sits with API-first commerce specialists given e-commerce platform expansion catalysts and SMS-channel convergence tailwinds; watch for inflection in direct-to-consumer merchant automation spend as signal of category maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Shopify and WooCommerce embedding captures transactional signal ingestion for direct-to-consumer merchants. |
| EU AI Act Compliance Engineering | Explainability dashboards and technical documentation files unlock European financial services procurement evaluations. |
| Strategic Partnership | Hyperscaler co-sell agreements with AWS and Azure accelerate enterprise sales cycle velocity. |
| Geographic Expansion | Localized payment integrations in Brazil and Mexico exploit low automation maturity among mid-market retailers. |
| Acquisition of Specialist Firm | Predictive send-time optimization engines add algorithmic differentiation to commodity email infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with marketing operations directors, SaaS procurement officers, platform engineers, and channel integration specialists. Bottom-up and top-down triangulation validated segment-level estimates against hyperscaler revenue disclosures, e-commerce platform partner ecosystem data, and EU AI Act implementation guidance documents.
Granularity-level modeling deployed deployment mode, organization size, vertical specialization, and integration complexity as core segmentation dimensions across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating real-time behavioral data pipeline penetration rates and freemium-to-paid conversion benchmarks. Forecast inputs included e-commerce merchant growth trajectories and CSRD disclosure mandate implementation timelines.
Underlying measurement precision varies by segment; cloud-based SaaS deployments carry tighter precision than hybrid architectures given disclosure transparency. Forecasts reflect assumptions around EU AI Act enforcement intensity and cross-border data localization trajectory. Deviation in FTC Section 5 enforcement against AI-powered personalization claims would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global AI Writing Assistant Software Market
Software & Services
Preschool Education Software Market
Software & Services
DevOps Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Public Financial Management Software Market
Software & Services
Data Conversion Services Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Animation Design Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Lead Mining Software Market
Software & Services
Live Chat Software Market