
 Captioning and Subtitling Solutions Market | 2026-2036
Captioning and Subtitling Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Captioning and Subtitling Solutions Market Outlook
The buyer base for captioning and subtitling solutions is broadening beyond traditional broadcasters to encompass enterprise learning departments, streaming platforms, and government agencies. VITAC sustains long-standing relationships with major US television networks through its broadcast specialization. Rev leverages a hybrid model combining freelance human captioners with automated workflows to serve price-sensitive segments. Verbit differentiates through AI-powered speech recognition tuned for domain-specific terminology in legal and educational contexts.
Captioning and subtitling solutions encompass software platforms and services that generate, edit, time-code, and deliver text overlays synchronized with audiovisual content, typically processing speech-to-text conversion with frame-level accuracy within 40-millisecond tolerances for broadcast compliance. These systems serve the fundamental commercial purpose of ensuring content accessibility for deaf and hard-of-hearing audiences while enabling cross-lingual distribution for media globalization. Live Captioning commands premium pricing due to real-time latency requirements and specialized stenographer or AI-resourced infrastructure, whereas Cloud-Based delivery modes are capturing the fastest expansion as media workflows migrate from on-premises hardware to elastic, API-driven architectures. AI-Powered technology segments attract disproportionate R&D investment as automatic speech recognition engines improve accuracy across accented and noisy audio environments.
The FCC mandates closed captioning quality standards for US broadcast and cable programming, while the European Accessibility Act requires streaming services and public broadcasters to meet comparable thresholds across EU member states. The World Wide Web Consortium's WCAG guidelines further shape product specifications by establishing perceivability criteria for online video content. Stakeholders must monitor regulatory divergence between jurisdictions as compliance automation becomes a primary vendor selection criterion rather than a secondary feature.
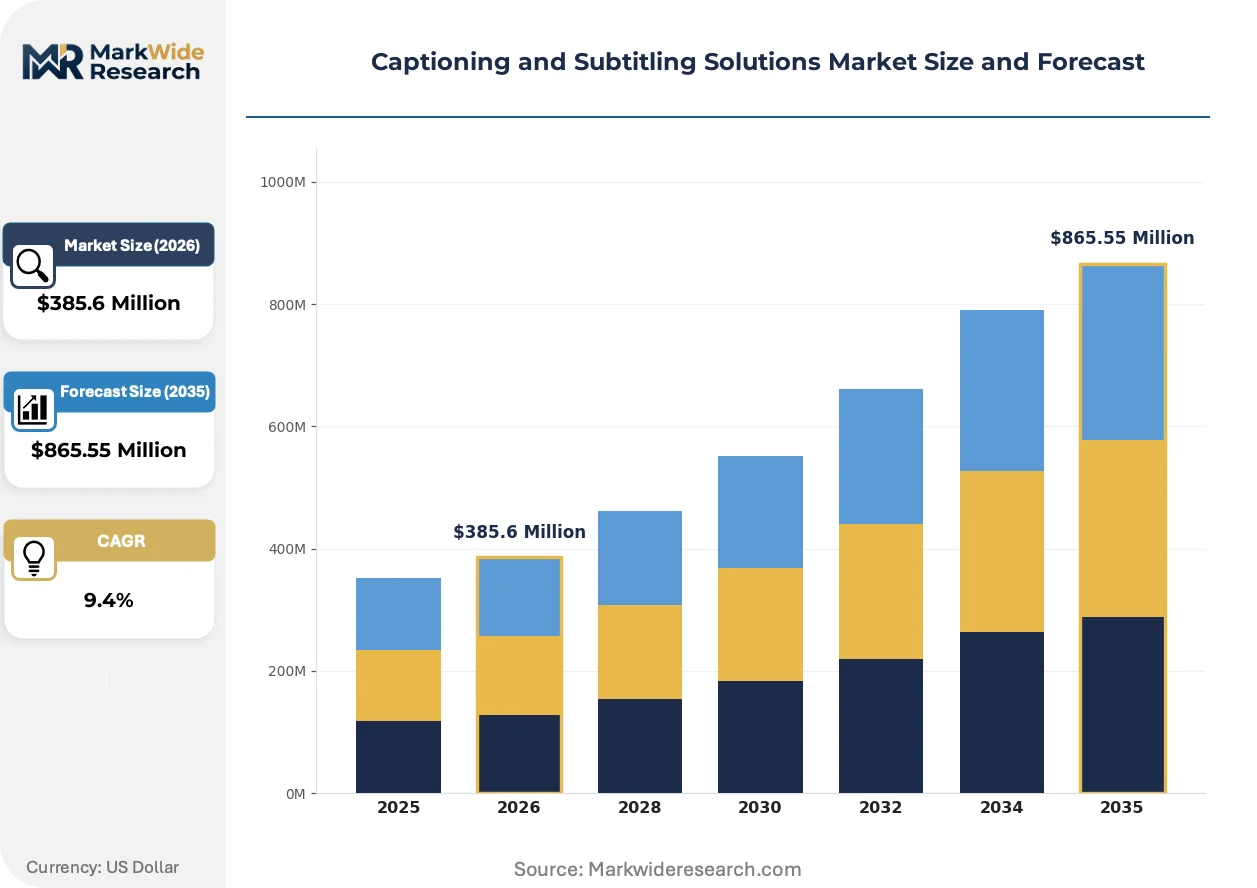
Market Dynamics
Streaming platforms are compressing production timelines while expanding multilingual content libraries, forcing captioning workflows to shift from batch post-production toward real-time API-driven pipelines that integrate directly with content management systems.
Growth Catalysts
- FCC Closed Captioning Quality Standards:The United States mandates accuracy thresholds for broadcast and online video distributors, compelling distributors to upgrade from legacy captioning tools toward automated quality assurance systems.
- Enterprise Learning Expansion:Corporate training departments now require scalable subtitling for video-based learning modules, creating steady demand outside traditional broadcast verticals.
- AI Speech Recognition Advancement:Automatic speech recognition engines now process accented and noisy audio with improved accuracy, reducing human-in-the-loop dependency for pre-recorded content workflows.
Market Restraints
- Live Captioning Infrastructure Costs:Real-time latency requirements demand specialized stenographer networks or GPU-intensive AI inference clusters, compressing margins for mid-tier service providers.
- Supply Concentration in North America:The majority of specialized captioning talent and broadcast compliance expertise clusters in the United States, creating geographic dependency for quality-sensitive buyers.
- Legacy Hardware Integration Friction:On-premises broadcast infrastructure in established media organizations resists cloud-native API architectures, slowing workflow migration timelines.
Strategic Opportunities
- European Accessibility Act Implementation:Streaming services and public broadcasters across EU member states must meet captioning thresholds by 2025, creating compliance-driven procurement cycles for automated solutions.
- Podcast and Audio-First Platforms:Spotify and similar platforms now transcribe spoken-word content for searchability and accessibility, opening adjacent demand from pure-audio creators.
- Neural Machine Translation Convergence:Integration of ASR engines with NMT models enables single-vendor delivery of multilingual subtitles, collapsing the traditional handoff between transcription and translation vendors.
Industry Challenges
- Domain-Specific Terminology Tuning:Legal, medical, and technical content requires custom acoustic and language models, extending deployment timelines and demanding specialized linguist partnerships.
- Frame-Level Synchronization Precision:Broadcast compliance mandates 40-millisecond tolerances for caption timing, forcing vendors to maintain expensive quality assurance layers even as automation scales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Captioning and Subtitling Solutions Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Captioning, Offline Captioning, Subtitling Services, Translation Services Delivery Mode: On-Premises, Cloud-Based, Hybrid, Mobile Application End User: Broadcasters, Educational Institutions, Enterprises, Media Companies Technology: AI-Powered, Manual Captioning, Automatic Speech Recognition, Video Editing Integration |
| Companies Covered | 3Play Media, VITAC, Adobe Inc., Captionmax, Verbit, Telestream, Inc., Rev, CaptionHub, AI-Media, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Captioning and Subtitling Solutions Market Strategic Shifts
Workflow architectures are fragmenting from monolithic platforms toward composable API stacks, allowing buyers to assemble best-of-breed transcription, timing, translation, and delivery components rather than accepting bundled suites.
Cloud-native captioning infrastructure is modularizing the traditional post-production pipeline. Media organizations now mix automated speech recognition engines from specialized vendors with human quality assurance layers through containerized microservices. This architecture lets broadcasters swap underlying ASR providers without disrupting downstream timing and formatting workflows, compressing vendor lock-in and accelerating price competition among engine suppliers.
The European Accessibility Act now mandates perceivability standards for streaming services and public broadcasters across EU member states. This regulatory pressure forces platform operators to embed automated captioning into content ingestion pipelines rather than treating accessibility as a post-upload add-on. Video-on-demand services in Germany, France, and Italy are responding by pre-emptively captioning entire back catalogs to avoid compliance penalties during enforcement windows.
Buyer procurement patterns are fragmenting from annual enterprise contracts toward consumption-based API pricing. Mid-sized production houses and independent creators now access broadcast-grade captioning through metered cloud services rather than maintaining minimum commitments with traditional vendors. This shift is most visible in the United States, where YouTube creators and podcast networks purchase transcription credits through developer portals rather than negotiating service agreements.
Captioning and Subtitling Solutions Market Segmentation
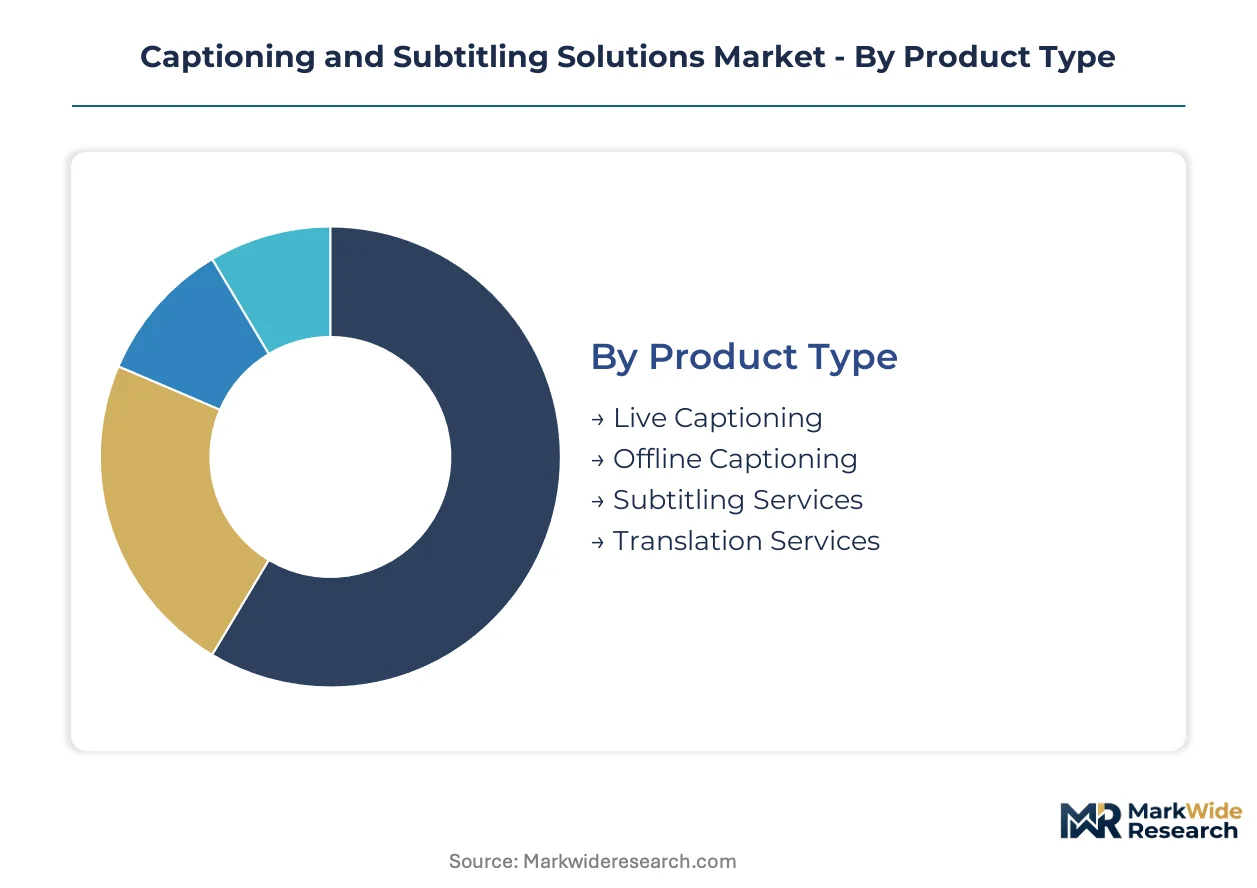
Segmentation in the captioning and subtitling market reveals how workflow requirements diverge across real-time versus batch processing, cloud migration stages, and compliance-sensitive buyer profiles. Technology choices and delivery architectures determine vendor selection criteria more than price alone.
Product Type:
Product type segmentation tracks the fundamental workflow dichotomy between synchronous live production and asynchronous post-production, with service layers adding translation complexity.
- Live Captioning:Real-time text generation synchronized to broadcast or streaming feeds demands sub-5-second latency through stenographer networks or GPU-accelerated inference clusters. US television networks and sports streaming platforms drive procurement, with FCC quality mandates forcing redundancy investments.
- Offline Captioning:Batch processing of pre-recorded content permits human quality assurance loops and acoustic model customization for domain-specific terminology. Educational publishers and enterprise training departments concentrate demand as video learning modules scale.
- Subtitling Services:Time-coded text overlay production for multilingual distribution, typically following transcription completion.
- Translation Services:Linguistic adaptation of source captions into target languages, often bundled with cultural localization.
Offline Captioning leads on scale; Live Captioning leads on momentum.
Delivery Mode:
Deployment architecture segmentation exposes the infrastructure transition from capital-intensive hardware to metered cloud consumption reshaping buyer economics.
- Cloud-Based:Elastic API-driven infrastructure enables consumption-based pricing and direct CMS integration, collapsing procurement cycles from enterprise negotiations to developer portal sign-ups. Mid-sized production houses and independent creators favor this model for back-catalog captioning without minimum commitments.
- Hybrid:Split architectures preserve on-premises quality assurance layers while pushing transcription inference to cloud ASR engines. Established broadcasters with legacy SDI infrastructure adopt this pattern to phase migration risk.
- On-Premises:Dedicated hardware deployments for high-security environments or broadcast facilities with strict air-gapping requirements.
- Mobile Application:Native iOS and Android captioning tools serving field journalists and social media creators requiring immediate upload workflows.
Cloud-Based deployments are climbing the fastest; Hybrid architectures retain the largest installed base among tier-one broadcasters.
End User:
Buyer type segmentation captures demand diffusion beyond traditional media into compliance-driven institutional verticals with distinct procurement rhythms.
- Broadcasters:Television networks and cable operators face the most stringent regulatory scrutiny, with FCC caption quality standards mandating 99% accuracy thresholds and 40-millisecond synchronization tolerances. Capital budgets support premium vendor relationships and dedicated integration engineering.
- Enterprises:Corporate learning departments and internal communications teams require scalable subtitling for video-based training, with procurement favoring SaaS subscriptions over service contracts. Accessibility litigation risk in the US drives ADA-compliant captioning investments.
- Educational Institutions:Universities and K-12 districts caption lecture recordings and MOOC content, often under Office for Civil Rights enforcement timelines.
- Media Companies:Streaming platforms and production studios balancing volume throughput with localization speed for international release windows.
Broadcasters dominate current vendor revenue; Enterprises are gaining share fastest as video-first internal communications expand.
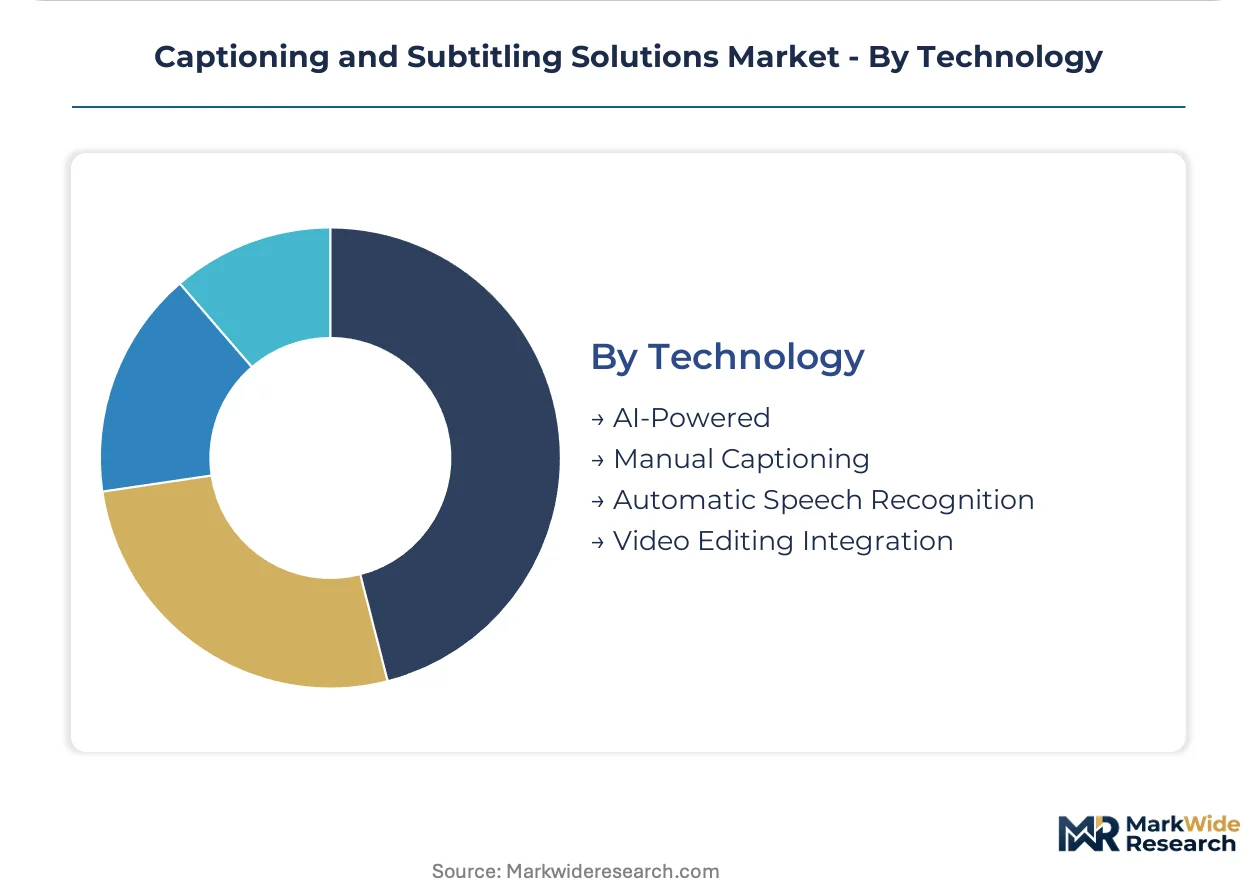
Technology:
Technology segmentation tracks the automation frontier where speech recognition accuracy improvements are compressing human-in-the-loop dependency for pre-recorded workflows.
- AI-Powered:Neural ASR engines with domain-specific fine-tuning for accented speech, noisy environments, and technical terminology attract disproportionate R&D investment. Legal and medical verticals demand custom acoustic models extending deployment timelines.
- Automatic Speech Recognition:General-purpose transcription engines serving as the baseline automation layer, with accuracy gaps filled by human post-editing.
- Manual Captioning:Human stenographer or respeaker workflows retaining dominance for live broadcast and premium content where error tolerance approaches zero.
- Video Editing Integration:Plugin architectures embedding caption timing and formatting within Adobe Premiere, DaVinci Resolve, and Avid Media Composer timelines.
Manual Captioning retains the highest accuracy premiums; AI-Powered solutions are expanding most quickly as engine performance crosses commercial viability thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest share of captioning procurement due to FCC mandates and broadcast infrastructure density, while Germany is accelerating compliance investments ahead of European Accessibility Act enforcement timelines.
United States
Television networks and streaming platforms drive sustained demand for live and offline captioning workflows. The FCC mandates 99% accuracy thresholds and 40-millisecond synchronization tolerances for broadcast and cable distributors. Los Angeles and New York anchor the highest concentration of post-production houses integrating automated captioning into content pipelines.
Germany
Public broadcasters ARD and ZDF are preemptively captioning back catalogs to meet 2025 accessibility deadlines. The European Accessibility Act requires streaming services to achieve comparable perceivability standards across EU member states. Berlin and Munich host the densest clusters of localization studios adopting API-driven subtitling architectures.
United Kingdom
BBC and commercial broadcasters are expanding captioning for on-demand platforms under Ofcom enforcement. The UK's accessibility regulations align with WCAG 2.1 guidelines for online video content. London's Soho district concentrates post-production vendors serving international streaming clients.
France
France Télévisions and private streamers are automating subtitle generation for multilingual distribution. The country's national audiovisual regulator enforces caption quality standards for broadcast and digital platforms. Paris and Lyon house specialized localization agencies integrating neural machine translation with transcription workflows.
Japan
NHK and commercial broadcasters are captioning live programming for aging demographics and accessibility compliance. METI guidelines encourage universal design adoption across media distribution channels. Tokyo's Shibuya and Roppongi districts cluster subtitling vendors serving anime and gaming content exporters.
Captioning and Subtitling Solutions Market Competitive Environment
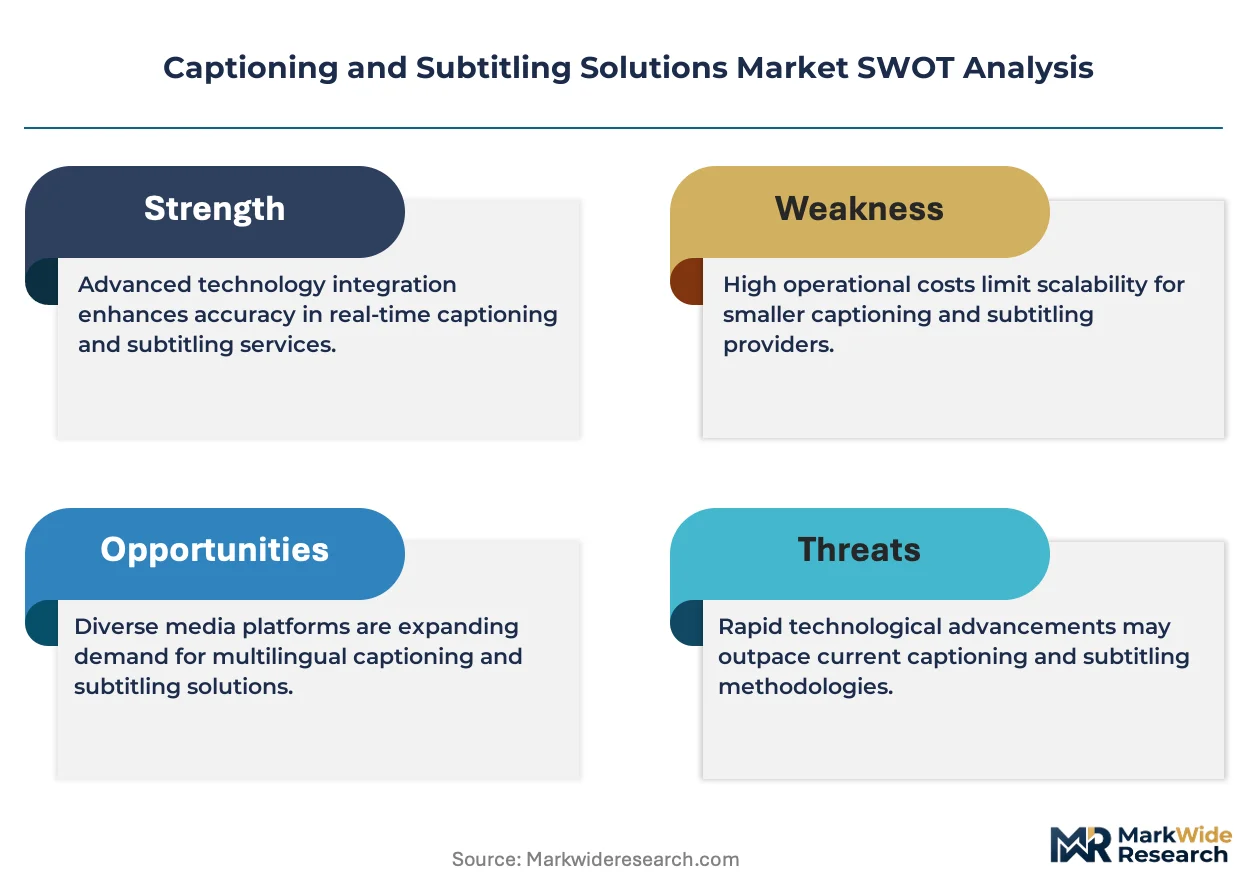
United States producers anchor the premium service tier; European specialists hold compliance-driven segments. The vendor base separates into broadcast-centric incumbents, AI-native challengers, and hybrid human-machine platforms. Strategic moves concentrate on API unbundling and geographic expansion into EU compliance markets.
Within the broadcast-specialist tier, VITAC and Captionmax exemplify long-standing network relationships built on FCC compliance expertise. Verbit occupies a position among AI-native entrants targeting domain-specific verticals. Rev sits within the hybrid-model archetype, combining freelance human captioners with automated workflows to serve price-sensitive creator segments.
| Leading Market Players |
|---|
| 3Play Media |
| VITAC |
| Adobe Inc. |
| Captionmax |
| Verbit |
| Telestream, Inc. |
| Rev |
| CaptionHub |
| AI-Media |
| Others |
Value Chain & Pricing Dynamics
FCC closed captioning quality standards gate both qualified supply and premium-tier pricing access, as broadcast compliance expertise concentrates among vendors meeting 99% accuracy thresholds and 40-millisecond synchronization tolerances. Buyers seeking FCC-certified workflows face constrained vendor pools, while price-sensitive segments migrate toward API-driven consumption models that trade certification depth for cost accessibility.
Pricing Analysis
Capacity additions in cloud-based ASR infrastructure are reshaping price floors for pre-recorded content workflows, compressing margins for mid-tier service providers while live captioning retains premium positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by compliance certification and latency requirements, with enterprise learning departments exhibiting highest price sensitivity and broadcast networks least. Pricing pressure stems from freelance marketplace models and metered API consumption displacing annual enterprise contracts.
Supply Chain Analysis
Specialized stenographer talent supply rests on United States-based training pipelines and broadcast certification programs, with secondary concentration in United Kingdom and Germany. GPU clusters for real-time inference, acoustic model training datasets, and domain-specific linguist networks constitute critical input dependencies. Single-source vulnerability runs through concentrated stenographer networks for live broadcast workflows. Distribution runs through direct vendor relationships with tier-one broadcasters and developer portal APIs for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in captioning and subtitling solutions hinges on AI speech recognition advancement compressing human-in-the-loop costs for pre-recorded workflows while compliance mandates sustain premium pricing for live broadcast tiers.
For Market Incumbents: Deploy API unbundling strategies to defend against AI-native challengers fragmenting the post-production pipeline. Incumbent broadcast specialists should deepen domain-specific acoustic model investments in legal and educational verticals where terminology tuning creates switching costs. Channel control through direct CMS integrations with major streaming platforms preserves relationship density against freelance marketplace entrants. For New Entrants and Emerging Players: Podcast and audio-first platforms represent the most penetrable white-space target, as Spotify and similar services transcribe spoken-word content for searchability with limited incumbent presence. European Accessibility Act compliance deadlines create procurement urgency among EU streaming services lacking caption infrastructure. Developer portal go-to-market angles bypass lengthy enterprise sales cycles that favor established broadcast vendors. For Investors and Strategic Acquirers: Roll-up economics work for hybrid human-machine captioning platforms because fragmented freelance talent pools and regional compliance expertise resist pure automation. Target acquisition archetypes include domain-specialized ASR vendors with legal or medical acoustic models and EU-based subtitling studios with European Accessibility Act implementation experience. Watch neural machine translation convergence with ASR engines as the inflection signal collapsing transcription-translation vendor handoffs.| Strategic Initiative | Industry Significance |
|---|---|
| API Platform Integration | Direct CMS embedding with Netflix and Disney+ accelerates workflow adoption across streaming verticals. |
| Domain-Specific ASR Acquisition | Purchase of legal or medical acoustic model specialists extends moats beyond general-purpose transcription. |
| European Accessibility Act Compliance Buildout | Preemptive captioning infrastructure positions vendors for 2025 enforcement procurement cycles in Germany and France. |
| Neural Machine Translation Convergence | Single-vendor multilingual subtitle delivery collapses traditional handoff friction between transcription and translation stages. |
| Freelance Marketplace Optimization | Hybrid human-machine quality assurance layers scale throughput without sacrificing broadcast-grade accuracy thresholds. |
Study Parameters
Direct dialogue with broadcast engineering directors, streaming platform localization managers, enterprise learning procurement officers, and FCC compliance consultants anchored qualitative findings, cross-referenced against FCC filing databases, SEC 10-K disclosures from listed media technology vendors, European Accessibility Act implementation guidance, and WCAG 2.1 technical specifications. Bottom-up demand modeling from individual buyer segments triangulated against top-down market sizing from media production expenditure data.
Segment-level value outputs across product type, delivery mode, end user, and technology dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from regression analysis against historical captioning procurement patterns, streaming content library expansion rates, and AI speech recognition accuracy improvement curves. Forecast inputs incorporated FCC enforcement intensity metrics and EU member state accessibility implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI speech recognition breakthroughs displacing human stenographer networks and regulatory divergence between FCC and European Accessibility Act enforcement postures. Forecasts reflect documented assumptions on technology adoption curves and compliance deadline adherence. ASR accuracy inflection points, freelance marketplace penetration rates, and streaming platform localization budget allocations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Farm Management Software Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Digital Twin Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Business As a Service Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Account Based Marketing Market