
 Digital Library Software Market | 2026-2036
Digital Library Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Library Software Market Outlook
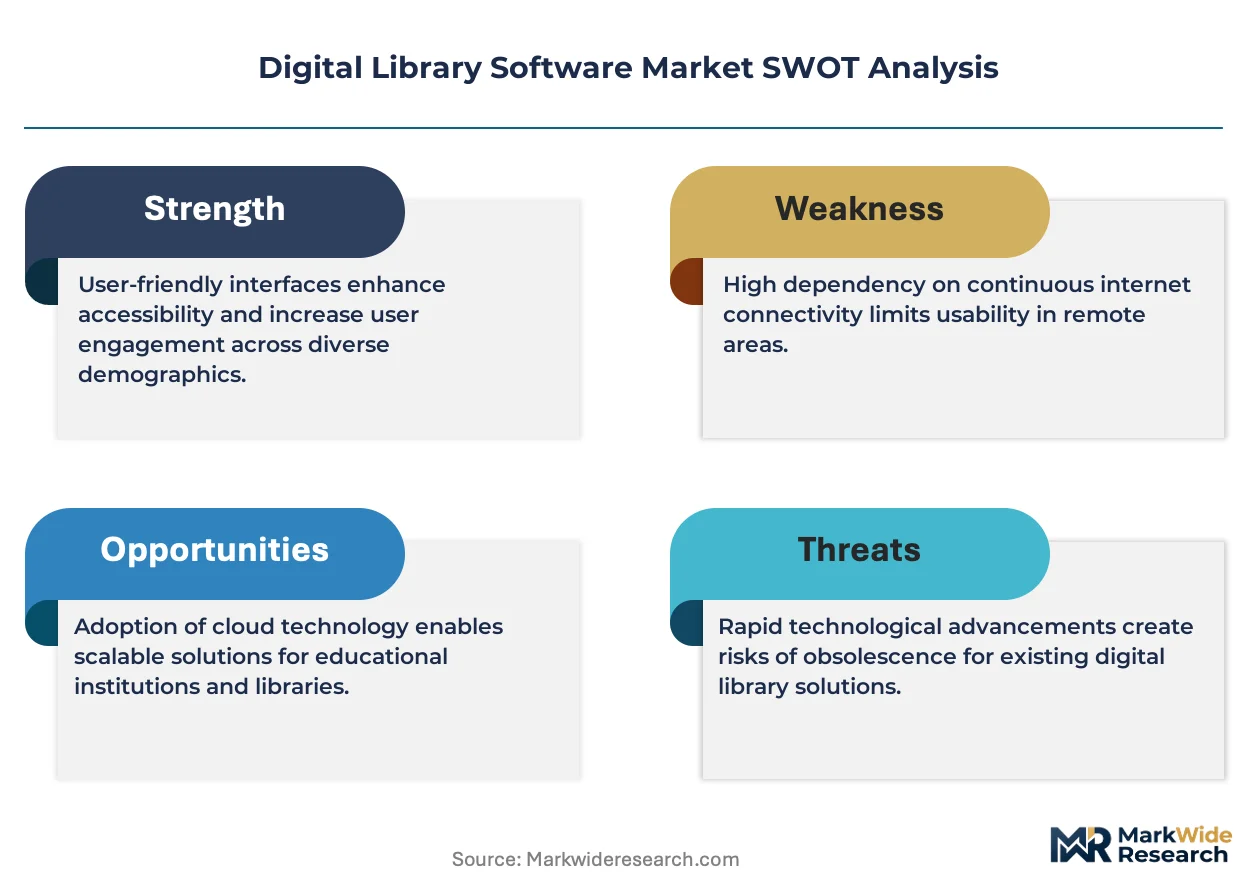
Subscription-based service delivery is consolidating as the dominant commercial model across the digital library software landscape. Ex Libris leverages its Alma platform to anchor recurring revenue streams in research library networks. SirsiDynix competes through embedded analytics modules that extend customer lifetime value. Koha differentiates by sustaining open-source flexibility while offering commercial support tiers.
Digital library software encompasses integrated systems for cataloging, discovery, lending, and digital asset preservation, typically built on MARC21 or BIBFRAME metadata standards with REST API architectures for interoperability. Cloud-based deployment leads segment adoption as institutions retire on-premise server farms, while hybrid configurations capture margin pools from organizations with legacy infrastructure dependencies. Academic institutions represent the most concentrated customer type, though public libraries are shifting fastest toward freemium entry points.
FDA guidelines on electronic records management, GDPR data residency mandates from European regulators, and ISO 27001 certification requirements collectively elevate compliance costs for cross-border platform providers. The EU AI Act introduces additional algorithmic transparency obligations for automated recommendation engines in library discovery layers. Stakeholders must monitor how interoperability standards evolve between national library consortia and commercial platform vendors.
Market Dynamics
Cloud-native platform migration is compressing deployment cycles as academic institutions dismantle on-premise server infrastructure, forcing vendors to rearchitect around containerized microservices and API-first interoperability standards.
Growth Catalysts
- GDPR data residency mandates:European universities are procuring EU-sovereign cloud instances, accelerating vendor certification investments and creating procurement urgency around compliant hosting architectures.
- BIBFRAME metadata transition:National library consortia in Germany and Japan are funding linked-data migration projects, expanding addressable market for standards-compliant discovery layers.
- Research data management integration:Academic institutions are consolidating library systems with institutional repositories, pulling digital asset preservation modules into core procurement decisions.
Market Restraints
- ISO 27001 certification costs:Cross-border platform providers face elevated compliance expenditure for information security management systems, compressing margins on mid-tier contracts.
- Legacy MARC21 lock-in:Decades of cataloging investment in traditional metadata standards create technical debt friction during standards migration, slowing replacement cycles.
- Hybrid deployment complexity:Organizations with mainframe dependencies require parallel infrastructure support, fragmenting vendor development resources across divergent architecture paths.
Strategic Opportunities
- EU AI Act algorithmic transparency:Automated recommendation engines in discovery layers face new disclosure obligations, creating compliance service revenue streams for advisory vendors.
- Public library freemium entry:Municipal systems with constrained budgets are adopting open-source cores with commercial support tiers, expanding addressable base beyond research institutions.
- AI-powered semantic search:Natural language processing capabilities are converging with traditional cataloging workflows, enabling premium pricing for intelligent discovery modules.
Industry Challenges
- BIBFRAME expertise scarcity:Linked-data implementation requires specialized metadata librarians and ontology engineers, constraining rollout velocity for standards-transition projects.
- Interoperability certification delays:National consortia maintain divergent API specifications, forcing vendors into redundant compliance testing across German, Japanese, and US library networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Library Software Market |
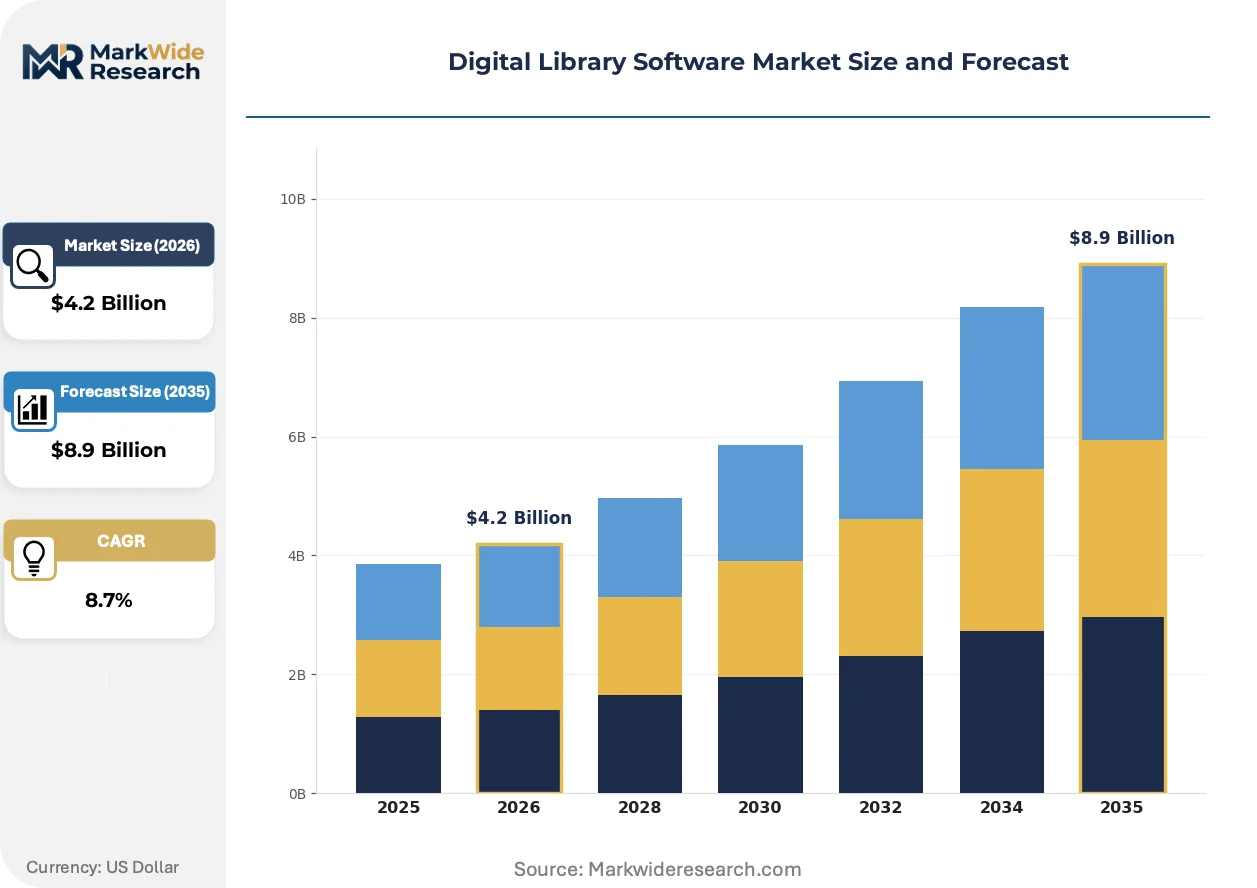
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Mobile Customer Type: Academic Institutions, Public Libraries, Corporations, Government Agencies Service Type: Subscription, One-time Purchase, Freemium, Licensing Feature: Digital Rights Management, Search Functionality, User Analytics, Content Management |
| Companies Covered | Alexandria Software, Mandarin Library Automation, SirsiDynix, Atriuum, Koha, Ex Libris, Book Systems, Polaris Library Systems, Follett Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Library Software Market Strategic Shifts
Artificial intelligence capabilities are embedding throughout discovery and preservation workflows, while regulatory pressure on automated systems intensifies transparency requirements across procurement jurisdictions.
Semantic enrichment engines are converging with traditional cataloging infrastructure to transform metadata processing. Research libraries in Germany and Japan are piloting machine-learning classification tools that auto-generate subject headings from unstructured digital assets. This compression of manual indexing labor is converging with cost pressures on technical services staffing, enabling vendors to reposition discovery platforms as workforce augmentation tools rather than pure infrastructure plays.
The EU AI Act introduces explicit algorithmic transparency obligations for automated recommendation systems operating in library discovery layers. Platform providers must now document training data provenance and decision logic for content suggestion engines. Academic institutions in France and Germany are inserting AI governance clauses into procurement specifications, forcing vendors to dedicate engineering resources to explainability features ahead of competitive differentiation.
Subscription contracting is displacing perpetual license arrangements across research library networks. Consortia purchasing managers are negotiating usage-based tiers that scale with institutional repository growth rather than fixed seat counts. This behavioral shift is most visible in US and UK academic systems, where shared services organizations are consolidating vendor relationships to extract volume commitments in exchange for pricing predictability.
Digital Library Software Market Segmentation
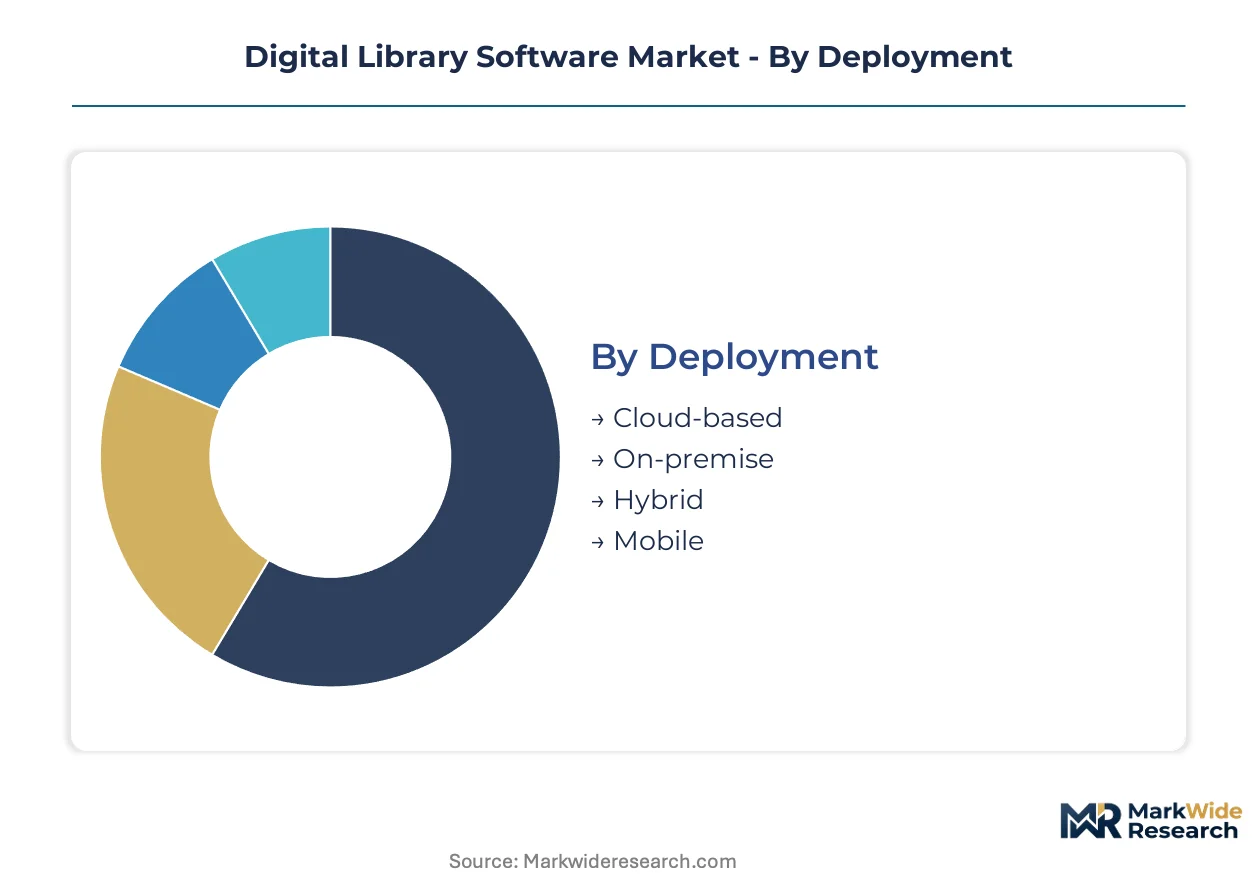
Digital library software procurement patterns diverge sharply across deployment architectures, customer budgets, and compliance requirements. Understanding these segment boundaries enables vendors to align R&D investments with institutional purchasing cycles and regulatory constraints.
Deployment:
Cloud-native architectures dominate new procurement as institutions dismantle legacy server infrastructure.
- Cloud-based:Containerized microservices with REST API architectures enable elastic scaling for consortia networks. German and Japanese national library modernization programs are channeling procurement toward EU-sovereign and domestic cloud instances to satisfy GDPR data residency mandates.
- On-premise:Dedicated hardware installations persist where air-gapped security or mainframe integration is mandatory. US research libraries with classified collections maintain on-premise deployments to satisfy federal information handling requirements.
- Hybrid:Parallel infrastructure supports organizations transitioning from legacy systems while preserving specialized local processing capabilities.
- Mobile:Responsive web and native application layers extend discovery interfaces to patron devices without full platform replacement.
Cloud-based deployments lead on scale; mobile extensions lead on momentum as patron access patterns shift.
Customer Type:
Budget cycles and compliance obligations create distinct purchasing behaviors across institutional categories.
- Academic Institutions:Research universities drive premium module adoption for institutional repository integration and research data management workflows. Procurement concentrates in Germany, the United States, and Japan where national funding agencies prioritize infrastructure modernization.
- Public Libraries:Municipal systems with constrained capital budgets are shifting fastest toward freemium entry points and subscription tiers that scale with collection growth rather than fixed seat licensing.
- Corporations:Enterprise knowledge management teams deploy discovery layers for competitive intelligence and regulatory document archives.
- Government Agencies:National archives and legislative libraries require FedRAMP or equivalent certification for sensitive record preservation.
Academic institutions anchor revenue concentration; public libraries are expanding most quickly as municipal digitization accelerates.
Service Type:
Commercial models are compressing toward recurring revenue structures that align vendor incentives with long-term customer success.
- Subscription:Usage-based tiers scale with institutional repository growth and discovery transaction volumes. Consortia purchasing managers in the US and UK are negotiating multi-year commitments to extract pricing predictability.
- One-time Purchase:Perpetual licenses with maintenance add-ons persist in organizations with capital budget cycles and internal IT capacity for platform management.
- Freemium:Open-source cores with commercial support tiers expand addressable markets to budget-constrained municipal systems.
- Licensing:Enterprise agreements bundle multiple modules with customization rights for large-scale deployments.
Subscription contracts dominate new revenue; freemium conversion rates determine long-term market expansion.
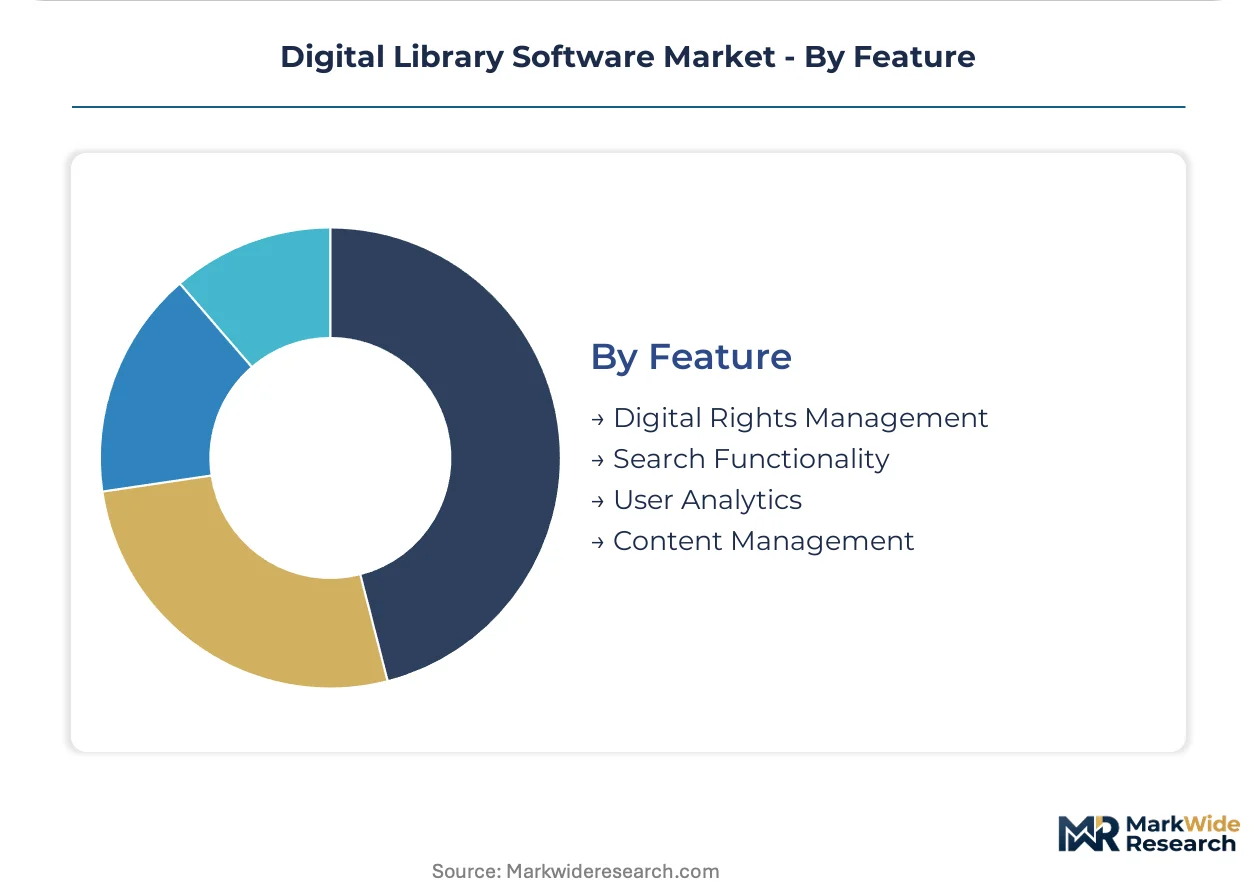
Feature:
Functional modules are converging around AI-augmented workflows that compress manual technical services labor.
- Digital Rights Management:Access control frameworks enforce publisher licensing terms and embargo periods for electronic resources. Integration with institutional single sign-on systems is becoming mandatory in consortia procurement specifications.
- Search Functionality:Semantic enrichment engines and natural language processing capabilities are repositioning discovery platforms as workforce augmentation tools. The EU AI Act is introducing algorithmic transparency obligations for automated recommendation engines.
- User Analytics:Privacy-preserving usage metrics inform collection development decisions while navigating GDPR constraints on personal data processing.
- Content Management:Digital asset preservation modules handle format migration and fixity verification for long-term institutional memory.
Search functionality commands premium pricing; user analytics faces the steepest regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan are outpacing the United States in BIBFRAME-linked data migration timelines, while all three markets are channeling national infrastructure budgets toward cloud-native library modernization.
United States
Research universities are consolidating procurement through shared services organizations to extract volume commitments from vendors. FedRAMP certification requirements shape vendor selection for libraries handling classified collections. The Greater Boston and San Francisco Bay Area clusters anchor demand for institutional repository integration modules.
Germany
National library consortia are funding linked-data migration projects that expand addressable market for standards-compliant discovery layers. GDPR data residency mandates from CNIL-equivalent state regulators accelerate EU-sovereign cloud procurement. The Bavarian academic network around Munich drives premium module adoption for research data management workflows.
Japan
METI infrastructure grants are modernizing national library networks toward BIBFRAME metadata standards. JIS certification requirements intersect with ISO 27001 for cross-border platform providers serving academic institutions. The Kanto region around Tokyo concentrates procurement for digital asset preservation modules.
United Kingdom
Consortia purchasing managers are negotiating multi-year subscription commitments to secure pricing predictability. CSRD sustainability disclosure rules are entering procurement specifications for vendor selection. The Golden Triangle of Oxford, Cambridge, and London anchors premium-tier adoption of AI-augmented discovery layers.
France
Academic institutions are inserting AI governance clauses into procurement specifications following EU AI Act implementation. CNIL oversight of algorithmic transparency shapes vendor engineering priorities for recommendation engines. The Paris-Saclay university cluster drives demand for semantic enrichment and workforce augmentation tools.
Digital Library Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium pricing in research library networks while open-source distributors capture municipal budgets. The vendor base organizes around three archetypes: cloud-native suite providers, heritage on-premise incumbents with hybrid migration roadmaps, and community-supported open-source cores with commercial support tiers. Dominant competitive moves include API-first interoperability certification and consortia-level volume contracting.
Within the integrated platform tier, Ex Libris and SirsiDynix exemplify cloud-native suite providers anchoring recurring revenue in research institutions, while Koha occupies a position representing the open-source archetype with commercial support tier conversion. These three companies collectively illustrate how subscription contracting is displacing perpetual licenses across procurement patterns.
| Leading Market Players |
|---|
| Alexandria Software |
| Mandarin Library Automation |
| SirsiDynix |
| Atriuum |
| Koha |
| Ex Libris |
| Book Systems |
| Polaris Library Systems |
| Follett Software |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification costs flow from compliance auditors through vendor engineering budgets into subscription pricing tiers, compressing margins for cross-border platform providers while concentrating procurement power among consortia with volume leverage.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for BIBFRAME-compliant discovery modules as national library modernization programs expand the addressable base. Subscription contracts with usage-based tiers now dominate, with price differentiation resting on GDPR certification grade and institutional repository scale. Pricing pressure stems from open-source alternatives capturing municipal budgets. Public libraries exhibit highest price sensitivity; research universities with federal funding show lowest.
Supply Chain Analysis
Single-source vulnerability sits with EU-sovereign cloud infrastructure providers serving German academic networks under GDPR data residency mandates. Software development draws from engineering talent pools in the United States, Germany, and India. Supply chain risk centers on regulatory restriction as the EU AI Act imposes algorithmic transparency obligations. Distribution runs through consortia purchasing managers negotiating multi-year volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital library software hinges on automation compressing manual cataloging labor and premium-tier AI modules capturing research institution budgets.
For Market Incumbents: Lock in consortia relationships through API-first interoperability certification before open-source alternatives mature. Invest in explainability engineering for EU AI Act compliance as a defensive moat. Capture backward integration into cloud infrastructure to reduce third-party hosting costs. For New Entrants and Emerging Players: Freemium distribution channels offer the lowest-friction entry point into municipal public library systems with constrained capital budgets. Target mid-tier academic institutions in Japan where METI infrastructure grants reduce procurement friction. Lead with semantic search modules that demonstrate immediate workforce augmentation value. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 27001 certification costs disproportionately burden mid-tier vendors without consortia scale. Long-term viability favors platforms with institutional repository integration depth over pure-play discovery layers. Watch BIBFRAME migration velocity in Germany as an inflection indicator for standards-compliant vendor valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating library systems with institutional repositories captures research data management budgets. |
| Geographic Expansion | EU-sovereign cloud instances unlock German procurement channels under GDPR residency mandates. |
| Strategic Partnership | Consortia volume contracts with shared services organizations secure pricing predictability and lock-in. |
| Product Launch | AI-powered semantic search modules command premium positioning in workforce augmentation narratives. |
| Acquisition of Specialist Firm | BIBFRAME ontology engineering talent accelerates linked-data migration project delivery timelines. |
Study Parameters
Multiple input streams — vendor procurement documentation, consortia purchasing records, regulatory filing analysis — were reconciled to construct market estimates. Primary interviews with library systems directors, university procurement officers, platform engineers, and metadata specialists informed demand-side validation. Secondary sources included SEC filings from publicly traded vendors, EU AI Act implementation guidance, and national library modernization program disclosures. Bottom-up deployment counts and top-down IT budget allocations were cross-referenced for triangulation.
Segmentation outputs across deployment architecture, customer type, service model, and feature module were reconciled against vendor revenue disclosures and consortia contract values. CAGRs were derived from modeled adoption curves for cloud-native platforms and BIBFRAME transition timelines. Forecast inputs incorporated GDPR enforcement intensity, EU AI Act compliance cost assumptions, and academic research funding trajectories in Germany, the United States, and Japan.
The model assumes a particular technology adoption path; alternative pathways for on-premise persistence in classified collection environments would alter the outlook. Forecasts reflect assumptions about interoperability standard convergence and regulatory enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Device As a Service (Daas) Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Asia-Pacific Data Monetization Market