
 Water Level and Storage Monitoring Software Market | 2026-2036
Water Level and Storage Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Water Level and Storage Monitoring Software Market Analytics
Subscription-based telemetry analytics is restructuring how vendors monetize water monitoring platforms. Emerson Electric Co. leverages its automation heritage to anchor long-term service contracts across municipal water districts. Siemens competes through integrated IoT architectures that extend hardware lifecycles with predictive maintenance modules. Badger Meter, Inc. specializes in ultrasonic flow instrumentation paired with cloud-native dashboards for smaller utility operators.
Water level and storage monitoring software encompasses sensor-integrated platforms that measure volumetric capacity, pressure differentials, and flow rates across reservoirs, tanks, and distribution networks using telemetry protocols such as Modbus and LoRaWAN; these systems enable operators to prevent overflow events, optimize pumping schedules, and maintain regulatory discharge limits. Cloud-Based deployment dominates product type configurations by reducing capital expenditure for mid-sized water utilities while Hybrid architectures capture margin pools from industrial clients requiring localized data sovereignty. IoT sensor networks lead technology adoption where battery-powered submersible probes transmit at fifteen-minute intervals to edge gateways.
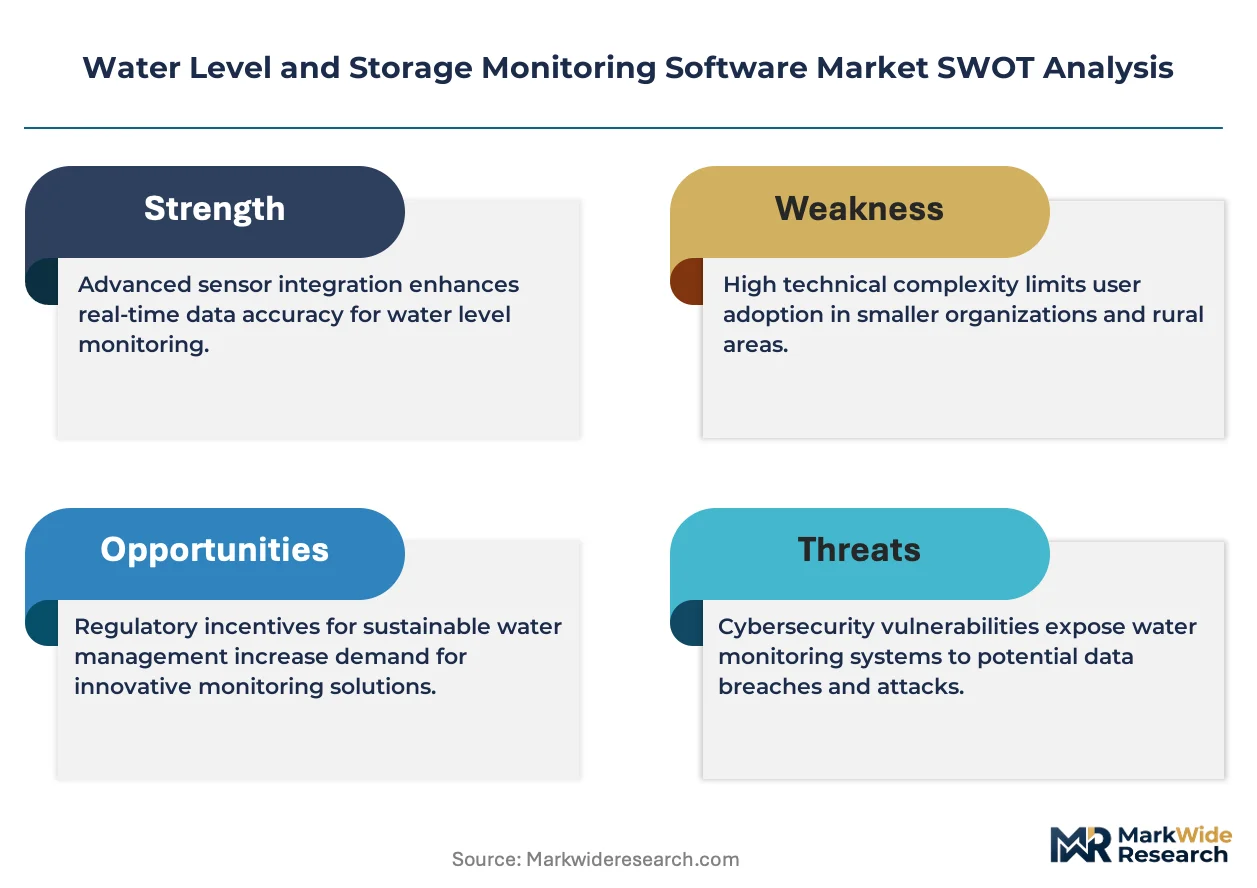
The EPA enforces Safe Drinking Water Act amendments that mandate continuous contaminant and level reporting, compelling utilities to upgrade legacy SCADA interfaces. The EU Water Framework Directive and REACH standards from ECHA impose chemical discharge monitoring that software platforms must integrate with laboratory information management systems. Stakeholders should evaluate how emerging cybersecurity frameworks for critical water infrastructure will reshape procurement criteria and vendor certification requirements.
Market Dynamics
Subscription telemetry models are restructuring vendor economics across water utilities, converting upfront hardware sales into recurring revenue streams anchored by predictive maintenance obligations and regulatory compliance guarantees.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Continuous contaminant and level reporting mandates force utilities to replace legacy SCADA interfaces with integrated monitoring platforms.
- LoRaWAN telemetry protocols:Battery-powered submersible probes transmitting at fifteen-minute intervals enable cost-effective sensor networks for mid-sized reservoir operators.
- German dam infrastructure replacement cycles:Aging concrete structures drive demand for digitized volumetric monitoring systems with predictive failure analytics.
Market Restraints
- Semiconductor supply concentration:Edge gateway chip fabrication concentrates in East Asian foundries, creating procurement bottlenecks for telemetry hardware manufacturers.
- EU REACH chemical discharge standards:Laboratory information management system integration requirements extend software certification timelines by twelve to eighteen months.
- Technical limitation of sub-15cm accuracy:Ultrasonic flow instrumentation struggles with turbulent reservoir conditions, restricting deployment in high-velocity intake zones.
Strategic Opportunities
- Cloud-native dashboards for smaller utilities:Mid-sized municipal operators seek reduced capital expenditure through software-as-a-service deployment models.
- EU Water Framework Directive tightening:Real-time discharge limit enforcement creates procurement windows for integrated compliance platforms.
- Edge-to-cloud architecture convergence:Hybrid deployments combining localized data sovereignty with remote analytics capture industrial client margin pools.
Industry Challenges
- Cybersecurity certification complexity:Emerging critical infrastructure protection frameworks reshape vendor qualification requirements for water utility procurement.
- SCADA integration friction:Legacy Modbus protocol systems resist seamless API connectivity with modern IoT platforms, demanding costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Level and Storage Monitoring Software Market |
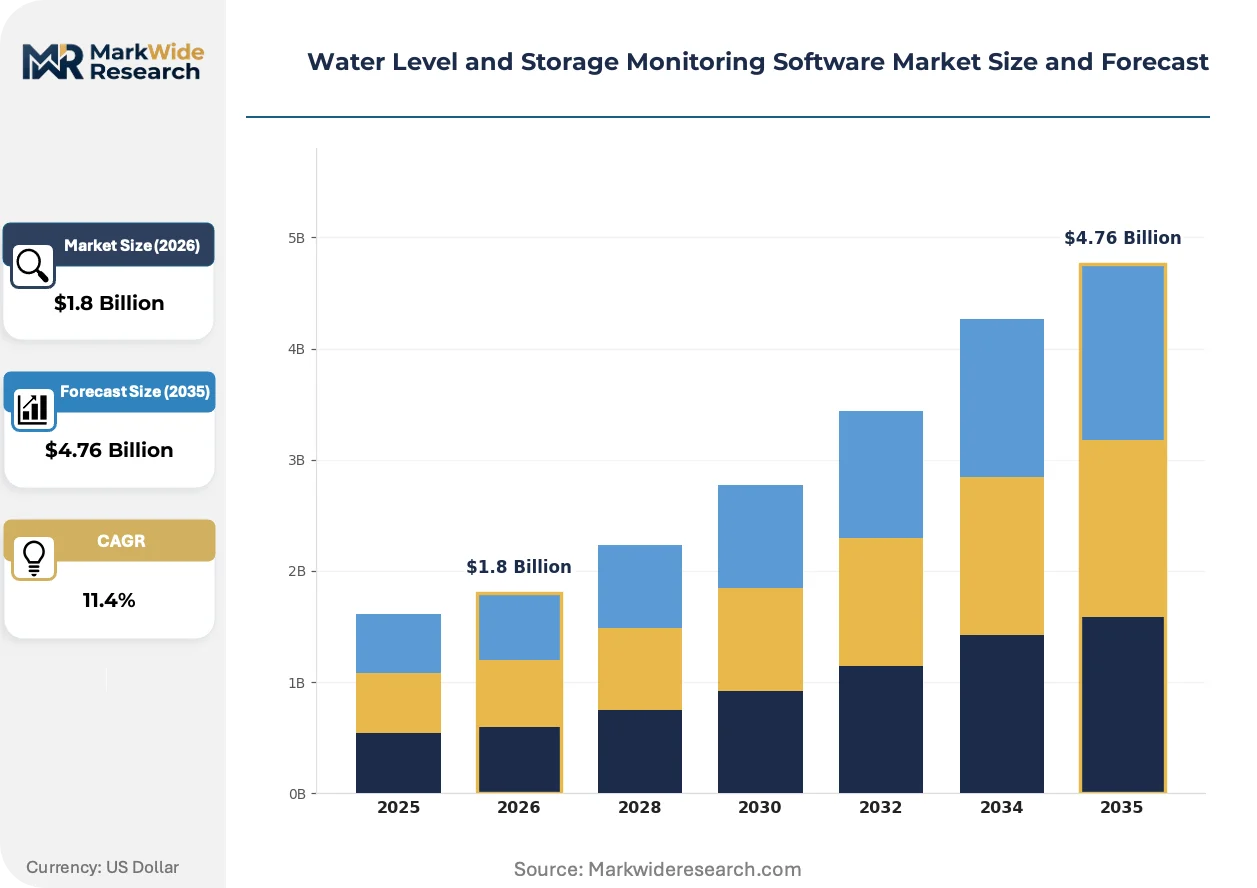
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile Technology: Sensors, IoT, Cloud Computing, Data Analytics End User: Agriculture, Water Utilities, Industrial, Environmental Agencies Deployment Model: Public Cloud, Private Cloud, Community Cloud, Edge Computing |
| Companies Covered | Emerson Electric Co., Siemens, Honeywell International Inc., ABB Group, Schneider Electric, IBM Corporation, Endress+Hauser AG, KROHNE Group, Badger Meter, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Level and Storage Monitoring Software Market Evolving Landscape
Digital twin architectures are compressing reservoir management cycles by simulating overflow scenarios and optimizing pumping schedules before physical deployment.
Edge computing gateways are integrating machine learning inference directly at reservoir sites, processing pressure differential data without cloud transmission latency. Large-scale agricultural irrigation districts in California and Texas are deploying these units at three times the rate of municipal utilities. This architecture is integrating predictive maintenance modules that extend ultrasonic probe lifecycles by automating calibration scheduling.
The EU Cybersecurity Act mandates IEC 62443 certification for critical water infrastructure software, compelling vendors to reengineer authentication protocols and encrypted telemetry channels. Industrial facility operators face twelve-month recertification cycles that freeze procurement decisions. German chemical manufacturers with captive water treatment plants are absorbing these costs faster than fragmented municipal districts.
After-sales service unbundling separates hardware warranties from analytics subscriptions, allowing utilities to mix vendor components. Smaller operators in the United States increasingly procure sensors from Badger Meter while sourcing cloud dashboards from specialized software houses. This pattern concentrates in the Southwest where water scarcity accelerates monitoring investment regardless of vendor integration depth.
Water Level and Storage Monitoring Software Market Segmentation
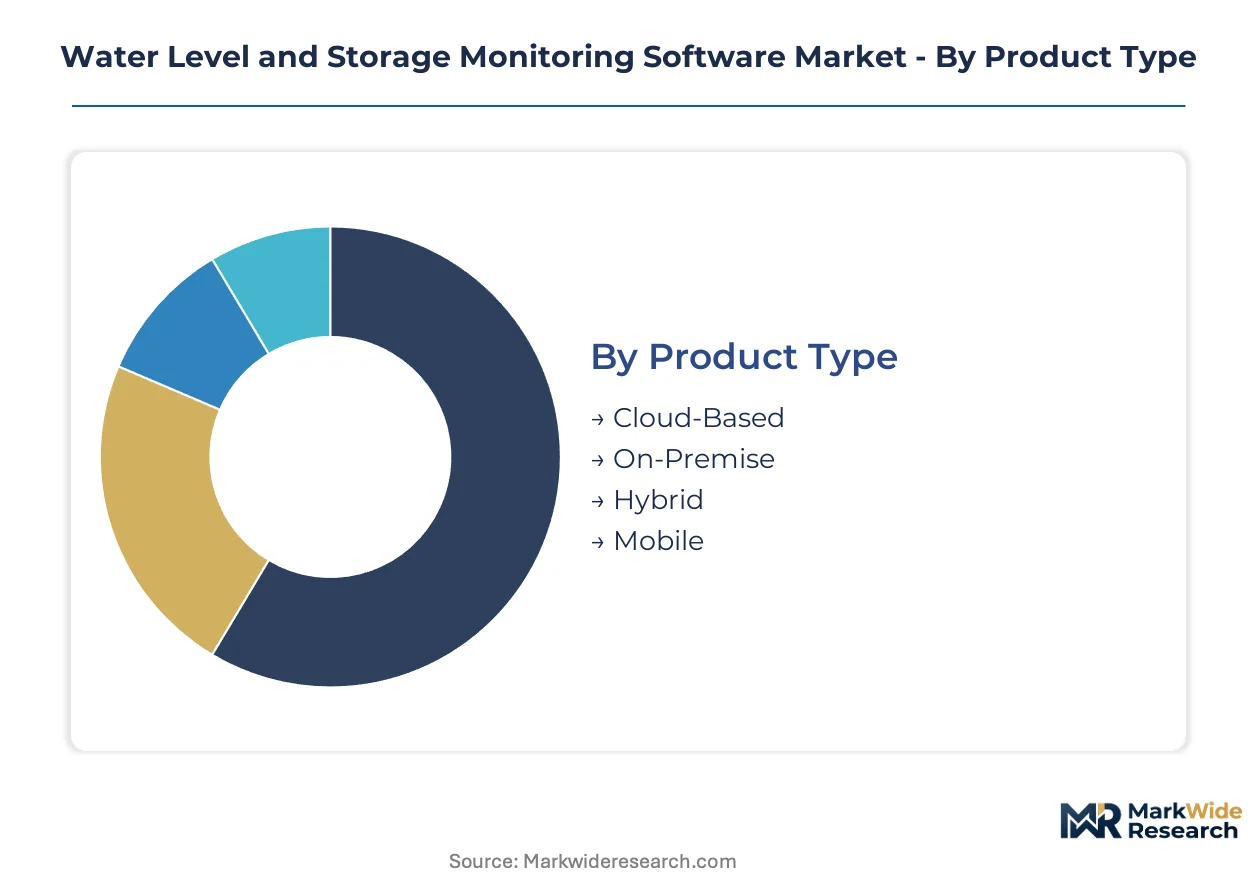
Water level and storage monitoring software vendors configure product architectures around deployment infrastructure, sensor integration depth, and regulatory compliance requirements. Segmentation choices directly determine capital expenditure profiles and recurring revenue potential across municipal, industrial, and agricultural buyer segments.
Product Type:
Standalone deployments dominate utility procurement where legacy SCADA replacement cycles favor discrete software purchases; embedded configurations concentrate in industrial captive water treatment facilities.
- Cloud-Based:Multi-tenant SaaS platforms eliminate server maintenance burdens for mid-sized water utilities. Demand concentrates in the United States Southwest where drought conditions accelerate monitoring investment regardless of upfront integration costs.
- Hybrid:Split architectures process sensitive volumetric data locally while pushing analytics to remote servers. German chemical manufacturers with captive treatment plants absorb certification complexity faster than fragmented municipal districts.
- On-Premise:Single-tenant installations persist in facilities with strict data sovereignty requirements.
- Mobile:Field technician applications extend dashboard functionality to remote reservoir inspection workflows.
Cloud-Based leads volumes today; Hybrid is gaining share fastest.
Technology:
Cost tier separation shapes adoption patterns where premium sensing stacks command maintenance contracts and budget telemetry competes on hardware margins alone.
- IoT:Battery-powered submersible probes transmitting at fifteen-minute intervals enable cost-effective sensor networks for mid-sized reservoir operators. California and Texas agricultural irrigation districts deploy these units at three times the rate of municipal utilities.
- Data Analytics:Machine learning inference engines process pressure differential patterns to predict probe calibration drift. Industrial facility operators face twelve-month recertification cycles that freeze procurement decisions.
- Sensors:Ultrasonic and pressure-based instrumentation measures volumetric capacity across tank and reservoir configurations.
- Cloud Computing:Elastic compute resources support seasonal demand spikes during flood monitoring periods.
IoT leads volumes today; Data Analytics is expanding most quickly.
End User:
Application urgency varies sharply across buyer types where water scarcity economics override procurement friction in agricultural segments.
- Water Utilities:Municipal operators replace legacy SCADA interfaces to meet EPA Safe Drinking Water Act continuous reporting mandates. Digitization of reservoir networks is expanding across United States water districts.
- Industrial:Captive treatment plants at German chemical manufacturers integrate laboratory information management systems to satisfy EU REACH discharge standards.
- Agriculture:Large-scale irrigation districts optimize pumping schedules against volumetric allocation limits.
- Environmental Agencies:Regulatory bodies deploy monitoring networks to enforce watershed protection boundaries.
Water Utilities leads volumes today; Industrial is climbing the fastest.
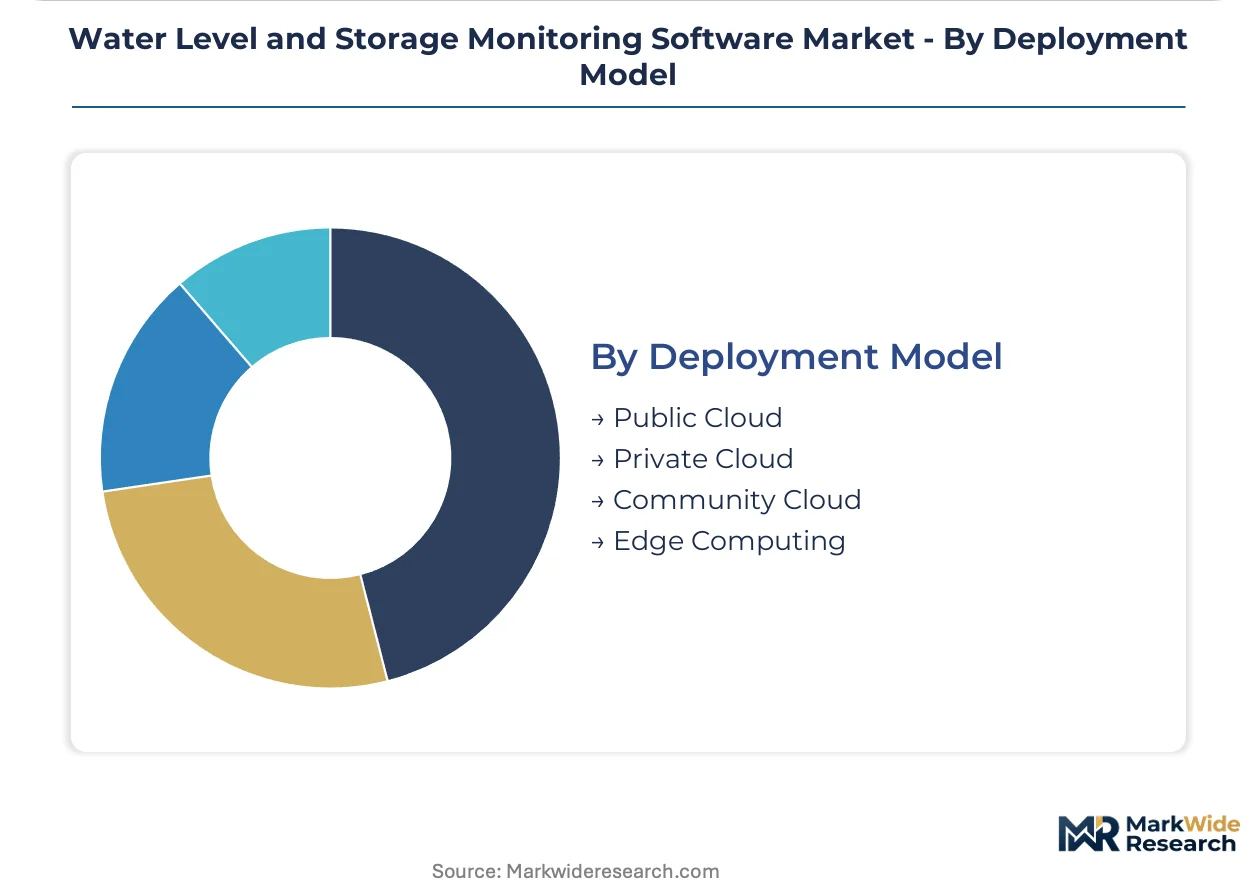
Deployment Model:
Customer type concentration determines architecture selection where public infrastructure favors shared resources and defense-adjacent facilities demand air-gapped systems.
- Edge Computing:Localized gateways process telemetry without cloud transmission latency. EU Cybersecurity Act IEC 62443 certification requirements compel vendors to reengineer authentication protocols for these deployments.
- Private Cloud:Single-tenant virtualized infrastructure serves industrial clients requiring localized data sovereignty.
- Public Cloud:Shared infrastructure reduces capital expenditure for mid-sized municipal operators.
- Community Cloud:Multi-utility shared services consolidate procurement across regional water districts.
Edge Computing leads volumes today; Private Cloud is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in water infrastructure compliance costs is reshaping procurement patterns, with utilities in jurisdictions featuring stricter EPA mandates absorbing premium pricing while operators in emerging markets prioritize cost-optimized telemetry hardware. This divergence concentrates vendor R&D investment toward modular platforms capable of tiered certification.
United States
Municipal water districts across the Southwest confront severe drought-driven allocation pressures, accelerating reservoir digitization timelines. EPA Safe Drinking Water Act amendments enforce continuous level reporting mandates that obsolete legacy SCADA installations. California's Central Valley agricultural irrigation cooperatives deploy IoT sensor networks at triple the rate of municipal utilities, prioritizing volumetric efficiency over integration depth.
Germany
Aging concrete dam infrastructure in Bavaria and North Rhine-Westphalia drives replacement cycles for predictive failure analytics systems. EU Water Framework Directive discharge thresholds tighten compliance windows, compelling chemical manufacturers with captive treatment plants to integrate laboratory information management systems. Baden-Württemberg's industrial clusters absorb IEC 62443 cybersecurity certification costs faster than fragmented municipal districts.
China
Dual carbon goals and watershed conservation policies accelerate smart reservoir deployment across the Yangtze River Delta. Provincial water authorities integrate edge computing gateways with localized data sovereignty requirements. Sichuan-Chongqing's hydropower-dependent grid operators prioritize real-time storage optimization to balance intermittent renewable generation.
India
Central Electricity Authority mandates for dam safety instrumentation create procurement windows for volumetric monitoring platforms. Maharashtra and Gujarat's industrial corridors deploy hybrid cloud architectures to satisfy data localization requirements while accessing remote analytics. Tamil Nadu's agricultural districts optimize pumping schedules against groundwater extraction limits enforced by state regulators.
Australia
Murray-Darling Basin water buyback programs intensify demand for precise storage measurement across agricultural holdings. New South Wales and Victoria enforce telemetry reporting for environmental flow compliance. Queensland's mining-adjacent water treatment facilities adopt edge-to-cloud architectures to manage tailings dam monitoring obligations.
Water Level and Storage Monitoring Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automation heritage conglomerates anchoring long-term service contracts while pure-play software houses capture mid-utility SaaS conversions. Market structure exhibits tiered consolidation: three diversified industrial technology groups control premium-tier municipal procurement, while fragmented specialists compete on hardware margins in agricultural and small-utility segments. Strategic archetypes include automation-platform incumbents extending into water verticals, ultrasonic instrumentation specialists bundling cloud dashboards, and telemetry-software pure-plays unbundling analytics from sensor warranties. Dominant competitive moves encompass predictive maintenance module integration and cybersecurity certification pre-engineering to compress procurement cycles.
Within the automation-platform tier, Emerson Electric Co. and Siemens occupy positions defined by integrated IoT architectures and legacy SCADA replacement capabilities. Badger Meter, Inc. exemplifies the instrumentation-specialist archetype, with cloud-native deployment models targeting capital-constrained municipal operators. These three entities represent distinct competitive vectors: full-stack automation, bundled sensor-software offerings, and unbundled telemetry analytics respectively.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens |
| Honeywell International Inc. |
| ABB Group |
| Schneider Electric |
| IBM Corporation |
| Endress+Hauser AG |
| KROHNE Group |
| Badger Meter, Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between IEC 62443-compliant platforms and uncertified alternatives splits both pricing power and sourcing strategies across vendor tiers. Premium deployments absorb twelve-month recertification cycles and encrypted telemetry engineering costs that commodity hardware margins cannot support, while budget-tier suppliers concentrate procurement in unvalidated chipsets from concentrated East Asian foundries.
Pricing Analysis
Distributor margins on edge gateway hardware compress SaaS-tiered subscription economics for mid-sized utilities. Three-tier pricing structure across premium, standard, and economy levels separates predictive maintenance bundles from basic telemetry dashboards. Pricing pressure stems from semiconductor supply bottlenecks that extend hardware delivery timelines. Agricultural irrigation districts in California and Texas exhibit highest price sensitivity, while German chemical manufacturers with captive treatment plants absorb premium certification costs.
Supply Chain Analysis
Freight costs on battery-powered submersible probes from Taiwan and South Korean foundries amplify landed costs for North American utilities. Edge gateway chip fabrication draws from Taiwan, South Korea, and mainland China. Raw material dependencies include lithium-ion cells, MEMS pressure sensors, and LoRaWAN radio modules. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through automation distributors and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in water monitoring software rests on subscription telemetry conversion and predictive maintenance bundling that extends customer lifetime value beyond hardware replacement cycles.
For Market Incumbents: Deepen predictive analytics integration to anchor long-term service contracts against pure-play software entrants. Consolidate sensor-software bundles to defend against unbundling trends where smaller operators mix Badger Meter hardware with third-party dashboards. Invest in IEC 62443 pre-certification to compress German procurement cycles.
For New Entrants and Emerging Players: Enter via cloud-native SaaS deployments targeting capital-constrained mid-sized utilities in the United States Southwest where drought conditions override integration depth preferences. White-space concentrates in agricultural irrigation districts deploying IoT sensor networks at triple municipal rates. Partner with regional water district cooperatives for community cloud procurement consolidation.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented municipal procurement favors specialized telemetry software houses over full-stack automation conglomerates. Five-to-ten year viability favors vendors with cybersecurity certification pipelines and hybrid architecture capabilities. Target acquisition archetype: ultrasonic instrumentation specialists with cloud dashboard bundling capacity. Monitor EPA enforcement intensity on Safe Drinking Water Act amendments as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Module Integration | Extends ultrasonic probe lifecycles through automated calibration scheduling for utilities. |
| IEC 62443 Certification Pre-Engineering | Compresses procurement cycles for German chemical manufacturers facing EU Cybersecurity Act mandates. |
| Edge-to-Cloud Architecture Convergence | Captures industrial margin pools requiring localized data sovereignty with remote analytics access. |
| After-Sales Service Unbundling | Allows smaller operators to mix vendor sensors with specialized software house dashboards. |
| LoRaWAN Protocol Standardization | Enables cost-effective fifteen-minute interval telemetry for mid-sized reservoir operators. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Australia, with primary inputs from each regional cluster combining utility operations directors, municipal procurement officers, and industrial facility engineers with secondary validation. Secondary sources include EPA enforcement databases, EU Water Framework Directive implementation reports, SEC 10-K filings from listed automation vendors, and customs records on telemetry hardware trade flows. Bottom-up sensor deployment counts triangulate against top-down software revenue estimates.
Granularity-level modeling disaggregates revenue across cloud-based, hybrid, and on-premise deployment configurations; IoT, data analytics, sensor, and cloud computing technology tiers; and water utility, industrial, agricultural, and environmental agency end-user segments. CAGRs derive from logistic adoption curves fitted to regulatory mandate timelines and infrastructure replacement cycles. Forecast inputs incorporate dam safety instrumentation mandates from India's Central Electricity Authority and drought-driven allocation pressures across California's Central Valley.
Inputs from utility procurement databases and vendor revenue disclosures were available through the study window; gaps in private SaaS subscription pricing introduce uncertainty bands around mid-sized operator segment estimates. Forecasts reflect assumptions on regulatory enforcement continuity and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Change Management Software Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Data Converter Market
Digital Solutions
Connected Stadium Solution Market