
 Business As a Service Market | 2026-2036
Business As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Business As a Service Market Outlook
The premium managed services tier is repositioning around sovereign cloud and industry-specific compliance, while commodity infrastructure is fragmenting into spot-priced compute pools. Microsoft Corporation leverages its hybrid Azure stack to anchor enterprise workloads across regulated verticals. IBM Corporation specializes in mainframe-to-cloud migration services for financial institutions. Amazon Web Services dominates the raw infrastructure layer through hyperscale data center density and direct fiber investments.
Business As a Service denotes the delivery of complete operational capabilities—including software platforms, infrastructure, and specialized business processes—through subscription or consumption-based contracts rather than perpetual ownership. Providers orchestrate multi-tenant architectures with automated provisioning, API-first integration, and guaranteed uptime thresholds measured in nines. Software as a Service captures the largest revenue pool among service types due to its low deployment friction and recurring revenue predictability. Platform as a Service is expanding fastest as enterprises adopt low-code environments and container orchestration without managing underlying servers. Hybrid Cloud deployment models concentrate margin pools where clients demand workload portability between on-premises systems and public infrastructure.
The EU AI Act imposes risk-tiered obligations on automated decision systems, compelling providers to embed audit trails and human oversight into service architectures. GDPR and HIPAA constrain cross-border data flows, forcing vendors to construct region-specific instance isolation and encryption key management. ISO 27001 and SOC 2 Type II certifications have become table stakes for procurement eligibility in financial services and healthcare. Stakeholders must evaluate whether their vendor portfolios can absorb impending algorithmic accountability mandates without fragmenting operational consistency.
Market Dynamics
The Business As a Service market is undergoing structural compression as sovereign data requirements fragment previously unified cloud architectures into geography-bound instance clusters. This regulatory-driven balkanization forces providers to replicate infrastructure across jurisdictional boundaries, fundamentally altering cost structures and competitive positioning.
Growth Catalysts
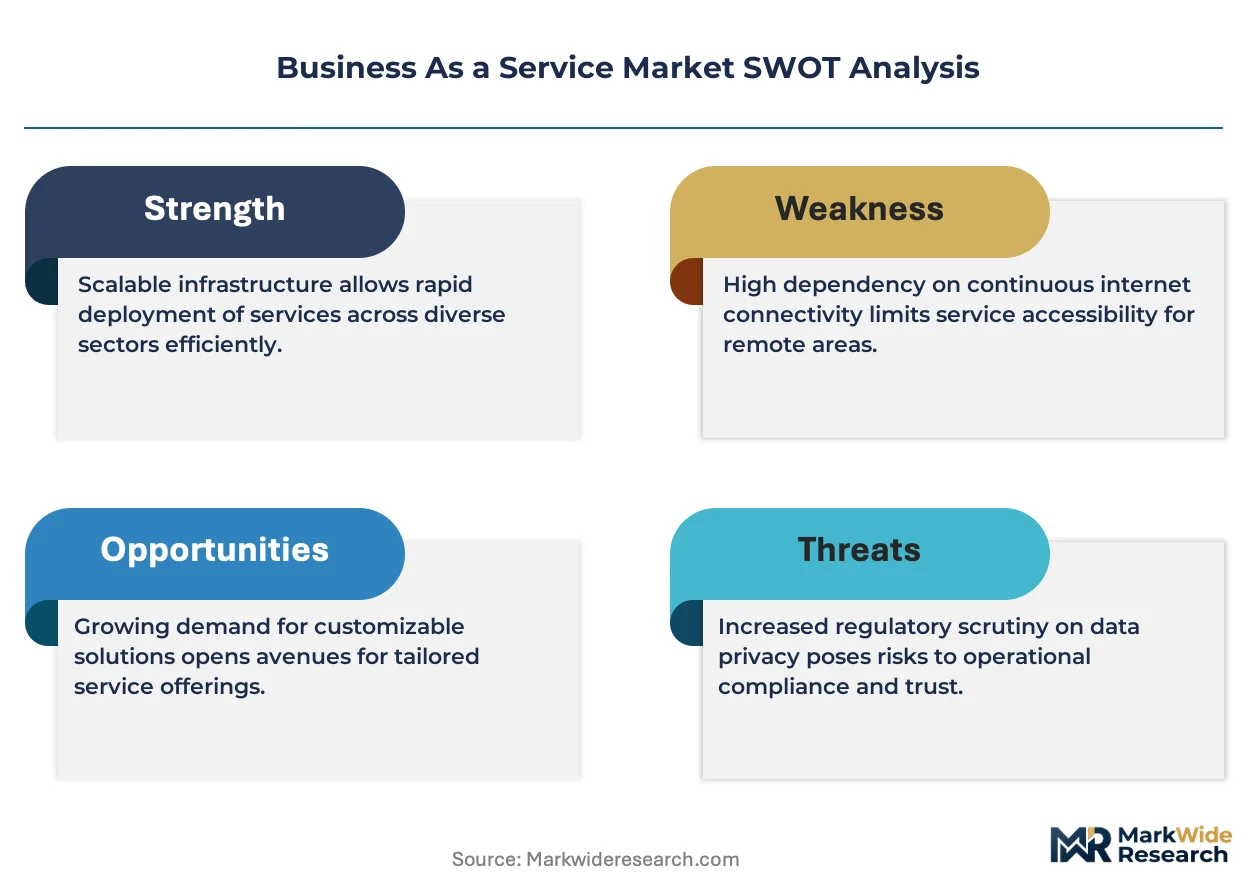
- EU AI Act compliance mandates:Risk-tiered obligations on automated decision systems are compelling enterprises to migrate from self-managed deployments to certified managed service architectures with embedded audit trails and human oversight mechanisms.
- Healthcare cloud migration:HIPAA-constrained providers are accelerating procurement of platform services offering pre-configured compliance, encryption key management, and business associate agreement automation.
- German Mittelstand outsourcing:Industrial digitization among mid-sized manufacturers is concentrating demand for infrastructure and platform services in Europe's largest industrial economy.
Market Restraints
- Cross-border data friction:GDPR's data localization requirements and Schrems II rulings are fragmenting operational consistency, forcing redundant infrastructure deployment and inflating total cost of ownership for multinational workloads.
- Hyperscale supply concentration:Raw compute and storage capacity concentrates among three dominant providers, creating vendor lock-in risks and limiting negotiation leverage for enterprise procurement functions.
- Legacy system entanglement:Mainframe-dependent financial institutions face technical debt barriers when migrating core transaction processing to API-first service architectures without service disruption.
Strategic Opportunities
- India's digital infrastructure buildout:PLI scheme incentives and BIS certification frameworks are creating entry pathways for managed service providers to capture public sector and banking modernization contracts.
- Edge-to-cloud orchestration:Convergence of 5G network slicing with container orchestration is enabling latency-sensitive manufacturing and autonomous vehicle applications previously excluded from centralized cloud models.
- CSRD reporting automation:The EU's Corporate Sustainability Reporting Directive is generating demand for ESG data collection and disclosure platforms delivered as managed services with audit-ready documentation chains.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Kubernetes, Terraform, and FinOps skill shortages are constraining enterprise ability to optimize workload placement across hybrid environments without managed service intermediation.
- ISO 27001 certification bottlenecks:Financial services and healthcare procurement eligibility requires current certifications, but audit backlogs and assessor capacity constraints are extending vendor onboarding timelines.
- API integration complexity:Enterprise legacy systems with proprietary protocols require custom middleware development, inflating implementation costs and delaying time-to-value for service transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business As a Service Market |
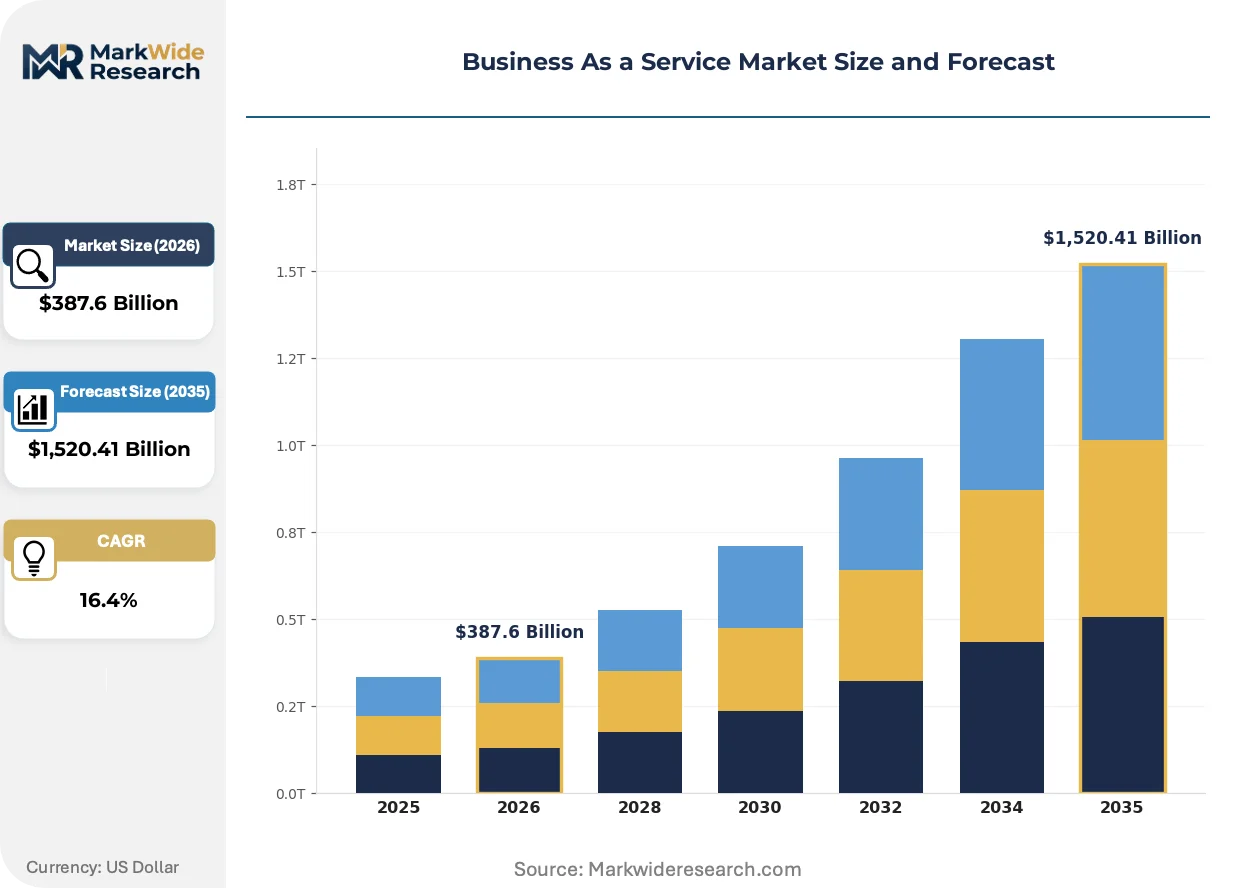
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,520.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Software as a Service, Platform as a Service, Infrastructure as a Service, Communication as a Service End User: SMEs, Large Enterprises, Startups, Government Agencies Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Industry Vertical: IT Services, Financial Services, Retail, Healthcare |
| Companies Covered | Amazon Web Services, Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP, Google, Salesforce, Accenture, Adobe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business As a Service Market Strategic Shifts
Container orchestration and low-code development environments are consolidating control over the platform layer, compressing traditional infrastructure management into automated, self-service consumption models. This architectural shift is redistributing value capture toward abstraction layers that hide server complexity from enterprise developers.
Kubernetes-based container orchestration is consolidating heterogeneous workload management into unified control planes. Manufacturing and logistics enterprises are adopting these platforms at accelerating pace to standardize deployment across factory floors and distribution networks. This technology is consolidating previously fragmented infrastructure teams into platform engineering functions with centralized governance.
The EU AI Act's risk classification framework is mandating algorithmic accountability documentation for high-risk automated systems. Providers must now embed technical documentation, human oversight interfaces, and conformity assessment trails into service architectures. Healthcare diagnostic AI and credit scoring platforms in Germany and France are restructuring development pipelines to accommodate these pre-market compliance requirements.
Enterprise buyers are unbundling professional services from subscription contracts, preferring à-la-carte implementation support over bundled onboarding. Systems integrators and managed service providers are capturing this disintermediated spend through outcome-defined SOW structures. This pattern is most pronounced in US financial services and UK public sector procurements, where capital efficiency pressures favor consumption-aligned cost models.
Business As a Service Market Segmentation
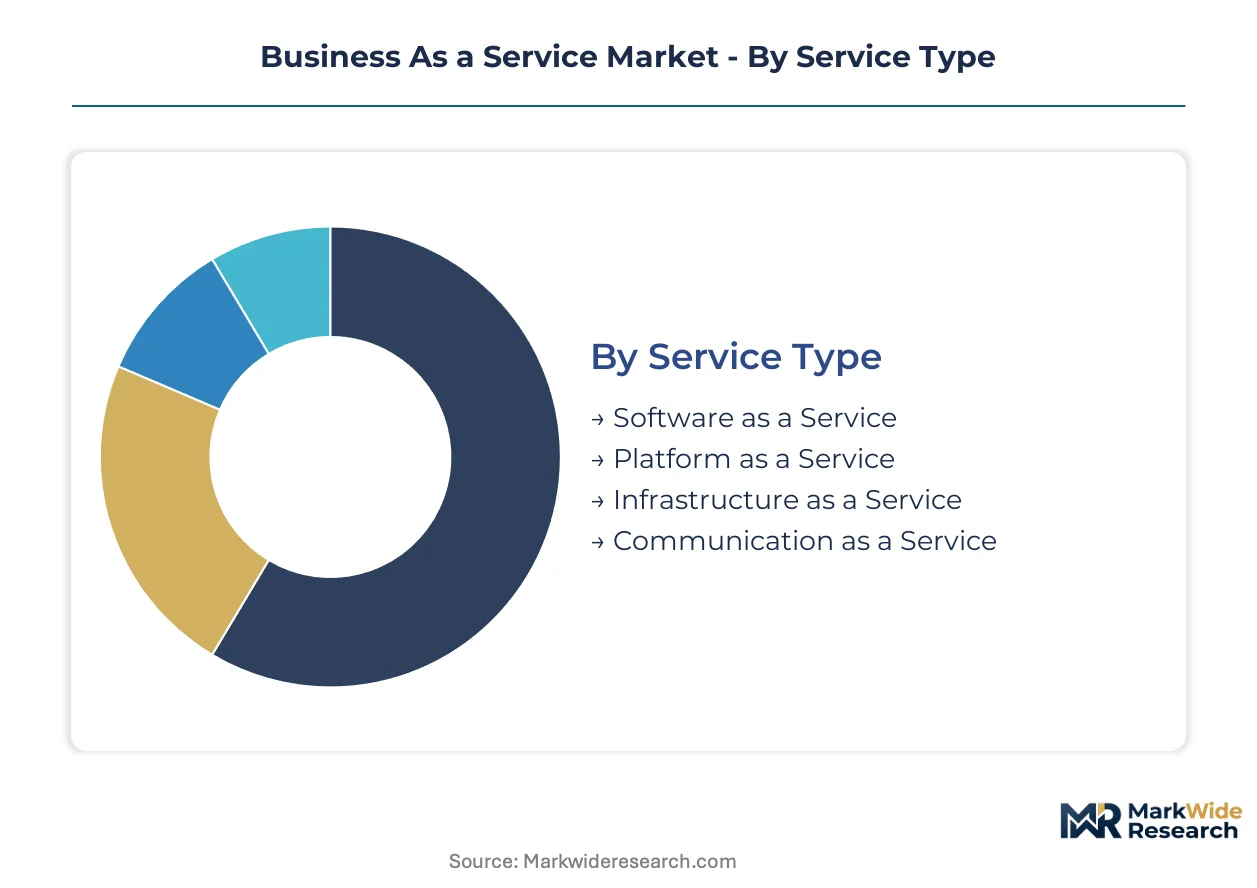
Segmentation in Business As a Service reveals how procurement patterns diverge across integration depths. Service type determines whether clients consume standalone applications or embed capabilities into operational workflows. Deployment model and end-user scale further fragment vendor strategies across compliance tiers and consumption volumes.
Service Type:
Standalone SaaS applications operate at the surface integration layer, while PaaS and IaaS embed deeper into enterprise architecture with varying control trade-offs.
- Software as a Service:Delivers complete applications through web browsers and mobile endpoints without local installation. Healthcare providers in Germany and France are consolidating diagnostic workflows onto pre-certified SaaS platforms to satisfy EU AI Act documentation requirements. Subscription pricing and low deployment friction concentrate demand among mid-market enterprises seeking rapid capability deployment without infrastructure overhead.
- Platform as a Service:Abstracts server management through container orchestration and low-code development environments. Manufacturing Mittelstand firms leverage PaaS to standardize factory-floor application deployment across distributed production sites. Kubernetes-based control planes enable these enterprises to maintain workload portability between on-premises systems and public infrastructure without dedicated DevOps staffing.
- Infrastructure as a Service:Provides raw compute, storage, and networking resources through API-driven provisioning.
- Communication as a Service:Delivers unified messaging, voice, and video infrastructure through cloud-hosted subscription models.
Software as a Service leads volumes today; Platform as a Service is gaining share fastest.
End User:
Procurement scale and compliance sophistication separate segments, with government mandates creating distinct certification requirements that reshape vendor qualification pathways.
- SMEs:Mid-sized manufacturers and professional services firms consume standardized service tiers with limited customization. German Mittelstand enterprises dominate this segment, outsourcing IT infrastructure to focus capital on core production capabilities.
- Large Enterprises:Global financial institutions and healthcare systems negotiate bespoke service architectures with dedicated instance isolation. HIPAA and GDPR constraints force these buyers toward hybrid deployments with region-specific encryption key management.
- Startups:Venture-backed technology firms prioritize consumption-aligned pricing and rapid scaling without long-term contracts.
- Government Agencies:Public sector bodies in France, Germany, and India mandate sovereign cloud instance isolation and domestic data residency.
Large Enterprises anchor revenue concentration; Government Agencies show steepest expansion trajectory as digital sovereignty mandates proliferate.
Deployment Model:
Control-retention preferences and data gravity requirements determine whether workloads distribute across shared infrastructure or isolate within perimeter-bound environments.
- Public Cloud:Shared multi-tenant infrastructure delivers economies of scale for variable workloads without capital commitment. Retail and media enterprises leverage public cloud burst capacity to absorb seasonal demand spikes without overprovisioning baseline infrastructure.
- Hybrid Cloud:Orchestrates workload portability between on-premises systems and public infrastructure through unified management planes. Financial services institutions in Frankfurt and Paris deploy hybrid architectures to retain core transaction processing on mainframes while extending customer-facing applications to scalable cloud tiers.
- Private Cloud:Dedicated single-tenant infrastructure serves regulated verticals with strict data residency mandates.
- Multi-Cloud:Distributes workloads across competing hyperscale providers to mitigate vendor lock-in and optimize service-specific capabilities.
Hybrid Cloud commands premium pricing today; Multi-Cloud adoption is climbing the fastest as procurement functions seek negotiation leverage against hyperscale concentration.
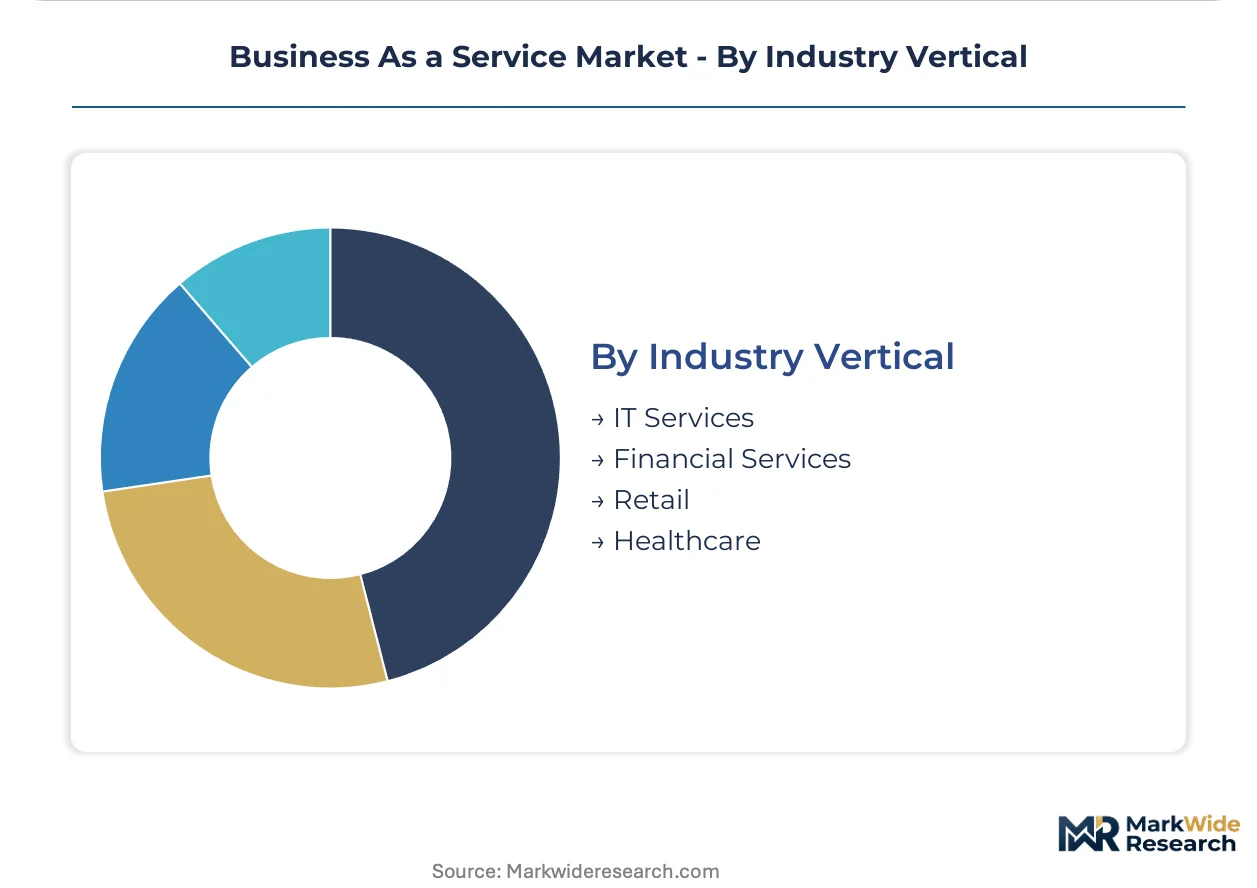
Industry Vertical:
Regulatory intensity and legacy system entanglement create divergent migration pathways, with compliance-forward sectors demanding pre-certified service architectures.
- IT Services:Technology consultancies and systems integrators consume platform services to deliver client solutions without captive infrastructure investment. These firms represent both demand concentration and channel intermediation, reselling managed service capabilities to downstream verticals.
- Healthcare:Hospitals and diagnostic networks accelerate procurement of HIPAA-compliant platforms with embedded business associate agreement automation. German university hospitals and French regional health authorities are restructuring procurement specifications around EU AI Act conformity assessment requirements.
- Financial Services:Banks and insurers face mainframe-to-cloud migration complexity with strict audit trail preservation.
- Retail:Omnichannel merchants deploy elastic infrastructure to synchronize inventory and customer data across physical and digital touchpoints.
IT Services generates the highest transaction volumes; Healthcare procurement is expanding most quickly as diagnostic AI and patient data platforms restructure around algorithmic accountability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates industrial outsourcing demand while the United States anchors hyperscale infrastructure investment. Compliance mandates fragment procurement patterns across jurisdictions. Sovereign cloud requirements reshape vendor qualification pathways in regulated verticals.
United States
Financial institutions and healthcare systems drive procurement of HIPAA-compliant managed services with embedded audit trails. The SEC and FTC impose algorithmic accountability requirements on automated decision systems. New York and San Francisco metropolitan areas concentrate fintech and healthtech adoption of platform services.
Germany
Mittelstand manufacturers outsource IT infrastructure to focus capital on core production capabilities. The EU AI Act and GDPR compel providers to embed conformity assessment trails into service architectures. Bavaria and Baden-Württemberg industrial clusters standardize factory-floor deployment through Kubernetes-based control planes.
France
Regional health authorities restructure procurement around EU AI Act requirements for diagnostic AI platforms. ANSM and CNIL enforce strict data residency and algorithmic transparency obligations. Île-de-France anchors public sector and banking modernization contracts requiring sovereign cloud isolation.
India
Public sector digitization and banking modernization generate demand for managed service platforms with BIS certification. The PLI scheme and RBI guidelines create entry pathways for infrastructure providers. Maharashtra and Karnataka technology corridors concentrate startup adoption of consumption-aligned pricing models.
United Kingdom
Financial services firms migrate core systems to hybrid architectures retaining transaction processing onshore. The Financial Conduct Authority and Information Commissioner's Office mandate audit-ready documentation chains. London anchors European headquarters for hyperscale providers serving regulated verticals.
Business As a Service Market Competitive Environment
Top-tier vendors anchor hyperscale infrastructure provision, while mid-tier specialists capture compliance-forward verticals. The market exhibits tiered concentration with three dominant players controlling raw compute capacity. Strategic archetypes include sovereign cloud architects, mainframe migration specialists, and industry-specific compliance enablers. Competitive moves center on geographic infrastructure replication and vertical certification acquisition.
Within the hyperscale tier, Amazon Web Services, Microsoft Corporation, and IBM Corporation exemplify divergent positioning strategies. Amazon Web Services occupies the raw infrastructure layer through data center density investments. Microsoft Corporation leverages hybrid stack integration to anchor enterprise workloads across regulated verticals. IBM Corporation represents the mainframe-to-cloud migration archetype for financial institutions confronting technical debt barriers.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP |
| Salesforce |
| Accenture |
| Adobe Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up managed service specialists are consolidating regional data center footprints across Germany and France, compressing unit economics while extracting pricing power through sovereign cloud certifications that commodity hyperscalers cannot replicate.
Pricing Analysis
The bundled-vs-unbundled service split is fragmenting procurement patterns across the Business As a Service landscape. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification grade and dedicated instance isolation, with HIPAA and EU AI Act conformity assessments commanding substantial premiums. Cost compression in the commodity infrastructure tier is intensifying because spot-priced compute pools are commoditizing raw capacity. Mid-market manufacturers in the German Mittelstand demonstrate highest price sensitivity, while financial institutions in Frankfurt and Paris accept premium positioning for audit-ready documentation chains.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme are reshaping sourcing patterns for managed service providers seeking public sector contracts. Hyperscale infrastructure draws from concentrated data center buildouts in the United States, Germany, and India, with specialized hardware components resting on Taiwan semiconductor fabrication and South Korean memory supply. Single-source vulnerability concentrates in submarine fiber cable landing stations connecting European and Asian instance clusters. Distribution runs through direct enterprise sales organizations and systems integrator channel partners with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Business As a Service rests on automation-driven cost compression in platform operations and the premium-tier shift toward sovereign cloud architectures with embedded compliance tooling.
For Market Incumbents: Lock in enterprise relationships through multi-year hybrid cloud contracts with guaranteed workload portability clauses. Deepen vertical certification moats by accelerating ISO 27001 and SOC 2 Type II audit completions ahead of procurement eligibility windows. Threat substitution from niche sovereign cloud specialists in France and Germany demands preemptive geographic infrastructure replication. For New Entrants and Emerging Players: Kubernetes-native edge orchestration capabilities represent the most penetrable technology-first wedge for manufacturing and logistics applications previously excluded from centralized cloud models. White-space concentration sits with mid-sized German manufacturers seeking factory-floor deployment standardization without captive DevOps staffing. Go-to-market execution should anchor on outcome-based SOW structures that disintermediate incumbent professional services bundling. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier compliance specialists with concentrated healthcare or financial services certification depth and limited geographic footprint. Long-term viability favors providers with demonstrated capability to absorb algorithmic accountability mandates without fragmenting operational consistency. The signal to watch is regulatory enforcement velocity under the EU AI Act's risk-tiered framework.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act compliance mandates in Germany and France create procurement eligibility barriers for non-certified providers. |
| Vertical Integration into Edge Infrastructure | 5G network slicing convergence enables latency-sensitive manufacturing applications outside hyperscale data centers. |
| Platform Integration | Kubernetes-based control planes consolidate fragmented infrastructure teams into centralized platform engineering functions. |
| Acquisition of Compliance Specialist | HIPAA and GDPR expertise accelerates onboarding timelines constrained by ISO 27001 certification bottlenecks. |
| Geographic Expansion | India's PLI scheme and BIS certification frameworks create entry pathways for public sector modernization contracts. |
Study Parameters
Coverage spans Germany, France, the United States, India, and the United Kingdom, with primary inputs from each market gathered through structured interviews with cloud procurement officers, platform engineering directors, healthcare IT compliance leads, and systems integrator practice heads. Secondary validation draws from SEC filings of hyperscale providers, EU regulatory implementation guidance, BIS certification registries, and hospital procurement database records. Bottom-up demand modeling triangulates against top-down infrastructure investment tracking across the analysis window.
Rate-of-change decomposition separates volume expansion from pricing tier mix shifts across service type, deployment model, organization scale, vertical regulatory intensity, and regional adoption pattern. CAGRs were derived from fitted growth curves applied to segment-level baseline estimates. Forecast inputs include EU AI Act implementation timelines, Mittelstand outsourcing survey data, and hyperscale data center capex disclosure patterns.
The model holds under steady regulatory enforcement and stable sovereign cloud demand; deviation in EU AI Act penalty severity or Schrems II data flow restrictions would shift trajectory. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Web Content Management Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Consent Management Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Media Asset Management (MAM) Solutions Market