
 Global Customer Experience Management Software Market | 2026-2036
Global Customer Experience Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Experience Management Software Market Foresight
The capability gap between cloud-native architectures and legacy on-premises stacks is unwinding competitive dynamics across the sector. Oracle Corporation leverages its database heritage to sustain large-enterprise deployments with deep data integration. Zendesk competes aggressively in the mid-market with streamlined ticketing-to-engagement workflows. SAP SE anchors its position through embedded CX modules within broader enterprise resource planning ecosystems.
Customer experience management software comprises integrated applications that capture, analyze, and act upon customer interactions across touchpoints using real-time data pipelines, natural language processing engines, and predictive analytics models to optimize satisfaction metrics and lifetime value. Cloud-based deployment leads structural growth as organizations abandon capital-intensive infrastructure maintenance, while omnichannel solution types capture expanding margin pools by unifying fragmented engagement channels. Feedback management retains mature revenue streams in regulated industries requiring audit-ready complaint resolution trails.
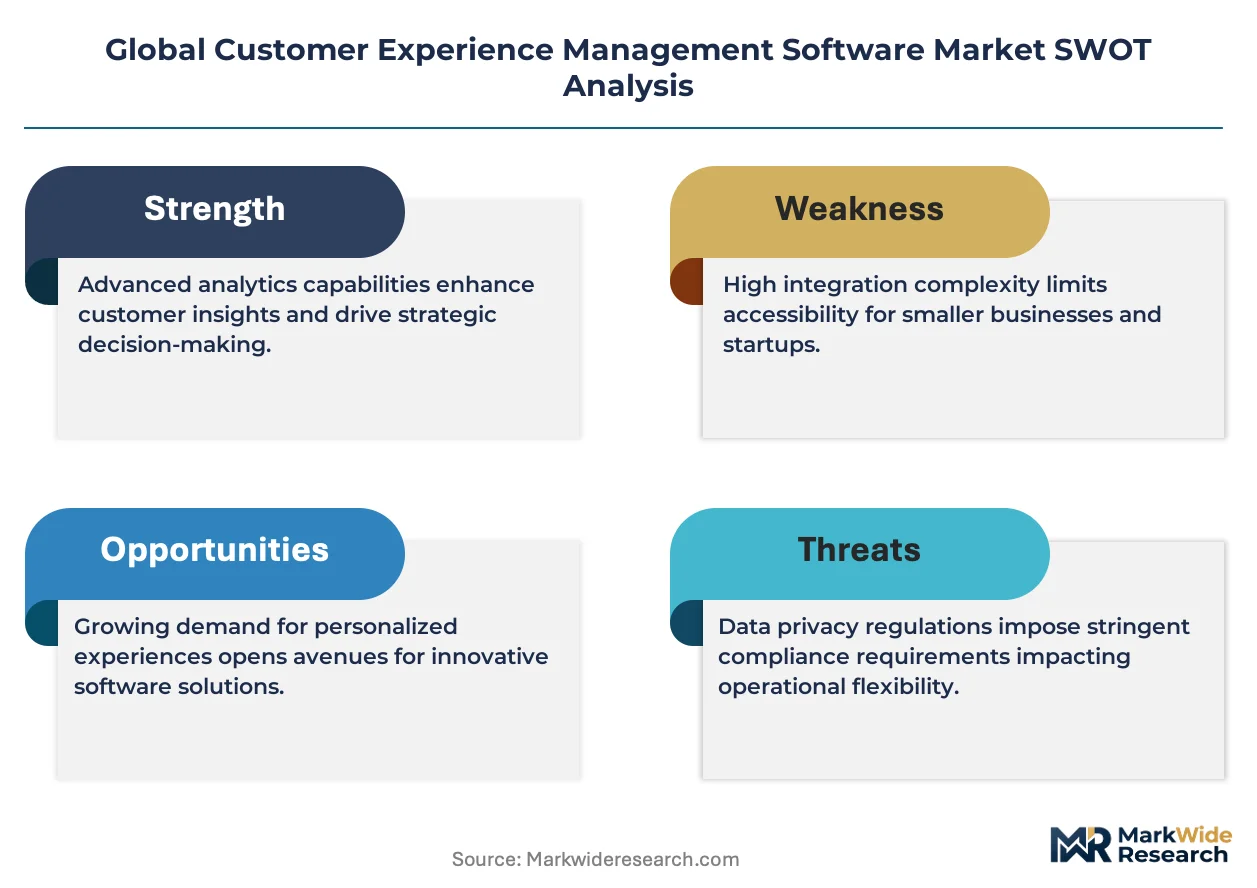
The EU AI Act and GDPR impose algorithmic transparency and consent requirements on automated sentiment classification and predictive churn models, forcing vendors to reengineer processing architectures. The US Federal Trade Commission scrutinizes dark pattern design and deceptive personalization practices under Section 5 authority, elevating compliance costs for engagement optimization features. Stakeholders must monitor evolving interoperability mandates from ISO standards bodies and assess whether vertical-specific certifications from health-data frameworks will become prerequisites for sector entry.
Market Dynamics
Cloud-native architectures are compressing deployment timelines from months to weeks, forcing legacy vendors to reengineer their delivery models or cede mid-market share to API-first competitors.
Growth Catalysts
- Journey Orchestration Platforms:Retail banking institutions in the United States deploy real-time journey mapping to reduce churn. This technology integrates behavioral signals across mobile, branch, and contact center touchpoints.
- EU AI Act Compliance:Automated sentiment classification vendors redesign processing pipelines to meet algorithmic transparency mandates. European enterprises prioritize audit-ready complaint resolution systems.
- Unified CX Consolidation:Enterprises abandon point solutions for integrated platforms. Procurement teams in Germany and Japan demand single-vendor accountability across voice, chat, and social channels.
Market Restraints
- Data Residency Requirements:China's data localization rules fragment cloud architectures. Vendors must maintain separate infrastructure stacks, duplicating operational overhead.
- Specialized Talent Scarcity:Natural language processing engineers command premium compensation. Hiring cycles in India and Brazil extend four to six months beyond software development norms.
- Legacy Integration Debt:On-premises CRM systems in Japanese manufacturing resist API connectivity. Custom middleware consumes thirty to forty percent of implementation budgets.
Strategic Opportunities
- Voice-of-Customer in Healthcare:Patient experience mandates from the Department of Health and Human Services accelerate hospital adoption. Feedback management platforms capture audit-ready complaint trails.
- Real-Time Personalization:Convergence of edge computing and streaming analytics enables sub-second recommendation engines. Brazilian e-commerce platforms pilot location-aware engagement triggers.
- Embedded Finance CX:Non-bank lenders in Nigeria and Kenya integrate white-label journey orchestration. Mobile-first deployment bypasses desktop-era infrastructure constraints.
Industry Challenges
- Cross-Border Data Architecture:GDPR right-to-erasure conflicts with India's data retention requirements. Engineering teams maintain parallel processing streams, increasing system complexity.
- ISO 27001 Certification Timelines:Security audits for financial services deployments extend nine to fourteen months. Delayed go-lives compress annual recurring revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Experience Management Software Market |
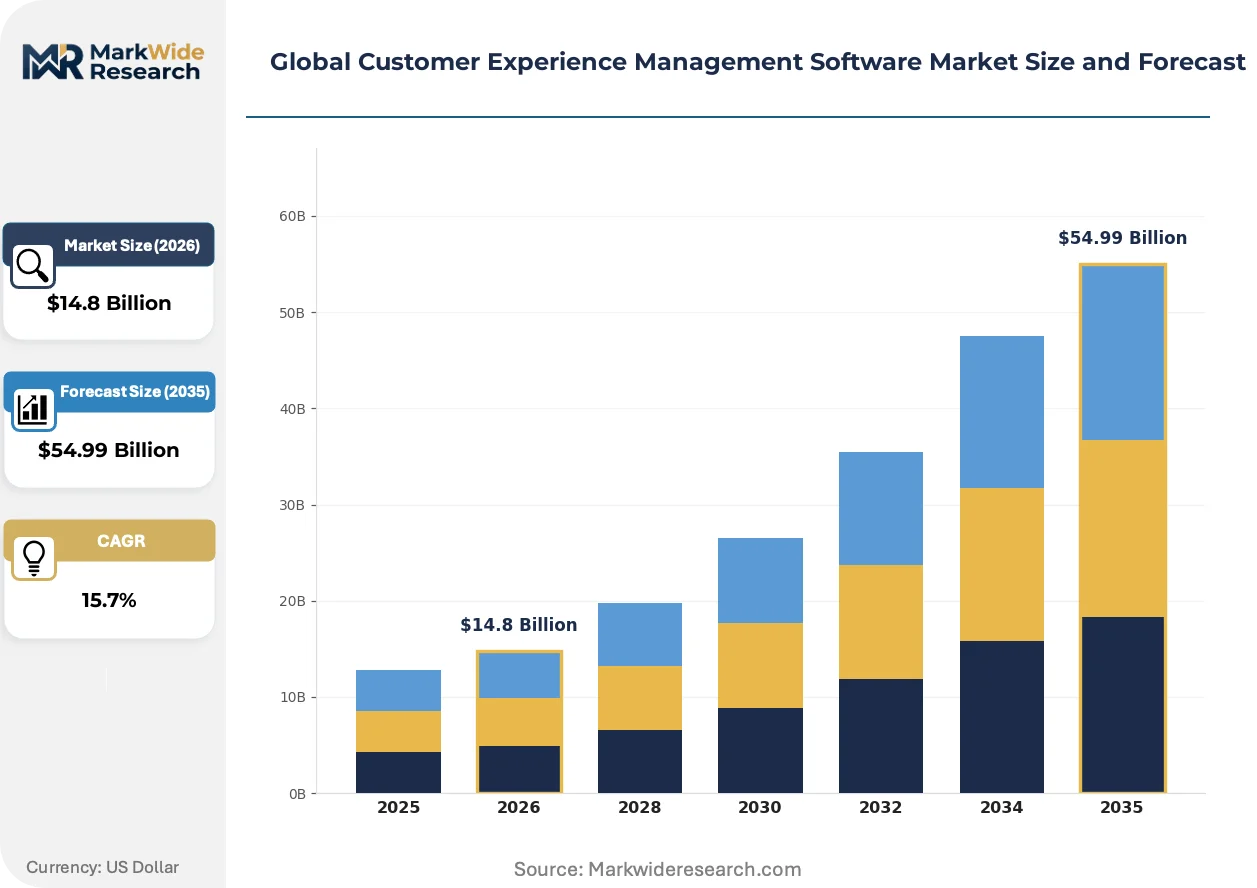
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $54.99 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud, Multi-Cloud Solution Type: Customer Analytics, Feedback Management, Contact Center, Omnichannel, Personalization, Journey Mapping Application: Customer Retention, Lead Generation, Service Optimization, Brand Loyalty, Complaint Management, Sales Enablement End User Industry: BFSI, Telecommunications, Media Entertainment, Travel Hospitality, E-Commerce, Education |
| Companies Covered | IBM Corporation, Zendesk, Adobe Inc., Qualtrics, OpenText Corporation, Oracle Corporation, Medallia Inc., Genesys, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Experience Management Software Market Shifts & Advancements
Generative AI is compressing content production cycles for customer communications, while regulatory pressure on algorithmic decision-making forces architectural redesigns across vendor stacks.
Large language models for automated response generation are bifurcating the vendor landscape. Enterprise buyers in the United States and United Kingdom deploy these systems for Tier-1 support deflection. The technology compresses average handle times while elevating compliance risk for unmonitored outputs.
Algorithmic transparency mandates under the EU AI Act reshape sentiment analysis deployments. Automated churn prediction models now require human-in-the-loop review architectures. European financial services firms delay rollout timelines to embed explainability interfaces.
Subscription pricing for journey orchestration displaces perpetual licenses in mid-market procurement. Value-based contracts tie vendor compensation to net promoter score improvements. This shift concentrates most visibly among Australian telecommunications providers restructuring vendor relationships.
Global Customer Experience Management Software Market Segmentation
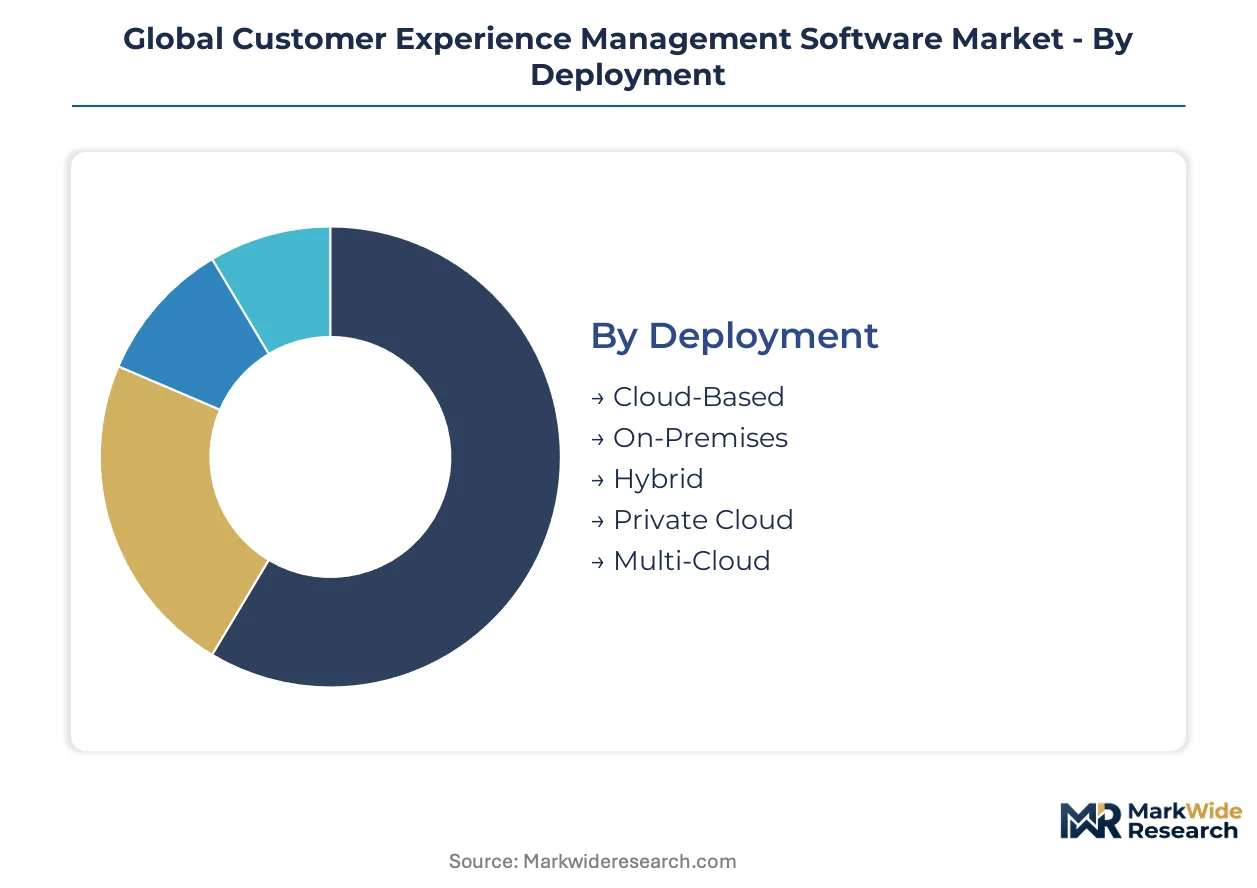
Segmentation in customer experience management software reveals how deployment choices, solution architectures, and industry-specific compliance requirements reshape vendor competitive positioning. Procurement patterns diverge sharply between regulated financial services and agile e-commerce operators.
Deployment:
Cloud-native architectures dominate North American and Western European procurement, while data sovereignty mandates in Asia-Pacific and Middle Eastern markets sustain hybrid and private cloud demand.
- Cloud-Based:Multi-tenant SaaS delivery eliminates capital expenditure cycles and accelerates time-to-value for mid-market enterprises. United States technology firms and United Kingdom retail banks prioritize API-first platforms with auto-scaling compute resources.
- On-Premises:Legacy installations persist where data residency regulations or air-gapped security requirements override cloud migration economics. Japanese manufacturing conglomerates and German automotive suppliers maintain captive infrastructure for sensitive customer records.
- Hybrid:Split architectures route transactional workloads to cloud while retaining regulated data on-premises. Australian healthcare providers and Canadian financial institutions deploy this model to satisfy HIPAA and PIPEDA constraints simultaneously.
- Private Cloud:Single-tenant dedicated environments serve defense contractors and government agencies with classified customer interaction requirements. United Arab Emirates sovereign wealth entities and Saudi Arabian energy firms mandate this deployment mode.
- Multi-Cloud:Workload distribution across AWS, Azure, and GCP reduces vendor lock-in and improves geographic redundancy. Brazilian fintech startups and Indian IT services exporters adopt this approach for resilience against regional outages.
Cloud-Based deployment commands the established base. The steepest expansion runs through Multi-Cloud configurations.
Solution Type:
Solution selection tracks organizational maturity — enterprises with fragmented point solutions consolidate toward omnichannel platforms, while digitally native firms leapfrog directly to AI-driven personalization engines.
- Customer Analytics:Predictive models processing behavioral signals across touchpoints to forecast lifetime value and churn probability. United States telecommunications carriers and United Kingdom insurers invest heavily in real-time segmentation capabilities.
- Feedback Management:Structured collection and audit-trail documentation of customer sentiment for regulatory compliance. European banks under EU AI Act mandates and Australian hospitals facing HHS-style patient experience requirements deploy these systems.
- Contact Center:Voice and digital channel routing with workforce optimization and quality management. Philippine business process outsourcing hubs and Indian IT-enabled services clusters represent concentrated demand centers.
- Omnichannel:Unified interaction history across voice, chat, email, social, and in-person touchpoints. German automotive retailers and Japanese department store chains prioritize seamless handoff capabilities.
- Personalization:Real-time content and offer tailoring using machine learning on streaming behavioral data. Brazilian e-commerce marketplaces and Nigerian mobile banking platforms drive adoption in emerging markets.
- Journey Mapping:Visual workflow design connecting discrete interactions into coherent customer lifecycle narratives. United States retail banks and Singaporean hospitality groups use these tools to identify friction points.
Feedback Management anchors revenue in regulated verticals. Personalization engines are climbing the fastest as generative AI reduces implementation complexity.
Application:
Application priorities shift with economic cycle position — retention and complaint management accelerate during contraction phases, while lead generation and sales enablement dominate expansion periods.
- Customer Retention:Proactive intervention systems triggering at-risk alerts based on behavioral decay patterns. Subscription software vendors in Israel and subscription box retailers in the United States deploy predictive churn models.
- Lead Generation:Prospecting workflow automation integrating marketing automation with sales development representative tooling. Business-to-business technology vendors in Ireland and cybersecurity firms in Estonia concentrate demand here.
- Service Optimization:Operational efficiency improvements reducing average handle time and first-contact resolution metrics. Contact center operators in Colombia and customer support hubs in Malaysia prioritize these deployments.
- Brand Loyalty:Gamification and rewards program management sustaining repeat purchase behavior. Quick-service restaurant chains in Mexico and fashion retailers in Italy invest in emotional connection metrics.
- Complaint Management:Escalation routing and regulatory reporting for consumer protection compliance. Utilities in Spain and telecommunications providers in South Africa face mandatory resolution timelines.
- Sales Enablement:Real-time coaching and competitive intelligence for field and inside sales teams. Medical device representatives in Switzerland and industrial automation sellers in South Korea require mobile-first tools.
Customer Retention captures mature spending. Sales Enablement is gaining share fastest as vendor compensation models shift to outcome-based contracts.
End User Industry:
Industry verticals exhibit divergent procurement authority patterns — BFSI and telecommunications centralize enterprise-wide platform decisions, while travel and hospitality permit property-level solution selection.
- BFSI:Banking, financial services, and insurance with stringent audit requirements and real-time transaction monitoring needs. United States regional banks and German cooperative banking networks represent substantial contract values.
- Telecommunications:Subscriber lifecycle management across prepaid and postpaid segments with network quality correlation. Brazilian mobile operators and Indonesian tower companies integrate network performance data.
- Media Entertainment:Content recommendation and subscriber churn prediction for streaming platforms. South Korean drama producers and Nordic public broadcasters deploy sentiment analysis on social conversation.
- Travel Hospitality:Guest experience orchestration spanning booking, stay, and post-departure advocacy. Dubai hotel groups and Thai resort operators prioritize review management and direct booking conversion.
- E-Commerce:Conversion funnel optimization and cart abandonment recovery at massive transaction scale. Polish marketplace sellers and Vietnamese direct-to-consumer brands operate on thin margins requiring precise attribution.
- Education:Student lifecycle management from prospect inquiry through alumni engagement. Australian universities and Canadian community colleges compete for international enrollment using personalized outreach.
BFSI holds the largest installed base. E-Commerce shows the steepest trajectory as digital commerce penetration accelerates in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity as enterprises consolidate onto unified platforms, while procurement teams in Brazil and India negotiate aggressively on subscription terms. German and Japanese buyers occupy a middle tier, prioritizing compliance over cost. Australian telecommunications providers pioneer value-based contracting models.
United States
Retail banking institutions deploy real-time journey orchestration to reduce churn across mobile, branch, and contact center touchpoints. The FTC scrutinizes dark pattern design and deceptive personalization practices under Section 5 authority, elevating compliance costs. Silicon Valley technology firms and New York financial services clusters drive API-first platform procurement with auto-scaling compute resources.
Germany
Automotive suppliers and cooperative banking networks prioritize seamless handoff capabilities across omnichannel touchpoints. The EU AI Act imposes algorithmic transparency mandates on automated sentiment classification, forcing vendors to reengineer processing architectures. Frankfurt financial services and Stuttgart manufacturing clusters demand single-vendor accountability with embedded ERP integration.
Japan
Manufacturing conglomerates maintain captive on-premises infrastructure for sensitive customer records, resisting API connectivity. METI guidelines shape data governance expectations for enterprise software procurement. Tokyo and Osaka industrial clusters consume thirty to forty percent of implementation budgets on custom middleware for legacy CRM integration.
Brazil
E-commerce marketplaces pilot location-aware engagement triggers using edge computing and streaming analytics. ANVISA and central bank regulations govern data handling for financial services deployments. São Paulo fintech startups adopt multi-cloud configurations across AWS, Azure, and GCP to improve resilience against regional outages.
Australia
Healthcare providers deploy hybrid architectures to satisfy HIPAA-aligned privacy constraints simultaneously with local regulations. The TGA and national privacy framework influence procurement specifications for patient experience platforms. Sydney and Melbourne telecommunications providers restructure vendor relationships around net promoter score improvement guarantees.
Global Customer Experience Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with database heritage vendors and cloud-native challengers occupying distinct competitive zones. Enterprise resource planning incumbents embed CX modules within broader suites, while API-first specialists capture mid-market share with streamlined deployment timelines. Consolidation pressure intensifies as procurement teams demand single-vendor accountability. Strategic moves concentrate on portfolio diversification through acquisition and vertical integration into adjacent workflow automation.
Within the integrated platform tier, Oracle Corporation and SAP SE exemplify contrasting archetypes—one leveraging database infrastructure for large-enterprise retention, the other anchoring position through ERP ecosystem embedding. Zendesk occupies a position among streamlined workflow specialists competing aggressively for mid-market consolidation opportunities. These three represent the structural fault lines between legacy stack extension and cloud-native displacement.
| Leading Market Players |
|---|
| IBM Corporation |
| Zendesk |
| Adobe Inc. |
| Qualtrics |
| OpenText Corporation |
| Oracle Corporation |
| Medallia Inc. |
| Genesys |
| SAP SE |
| Others |
Supply & Pricing Matrix
Multi-tenant SaaS infrastructure economics compress marginal delivery costs below on-premises alternatives, concentrating pricing power among hyperscaler-backed vendors while forcing legacy stack providers toward hybrid cost structures. Scale advantages in automated provisioning and API standardization reshape both supply concentration and price floors across deployment tiers.
Pricing Analysis
Professional services and extended implementation support drive lifetime value beyond base subscription tiers. Subscription pricing stratifies across premium, standard, and economy tiers with differentiation anchored in data residency options, ISO 27001 certification status, and integration complexity. Cost compression in mid-market seats intensifies as API-first challengers automate onboarding workflows. Procurement teams in Brazil and India negotiate most aggressively on per-seat terms, while United States enterprise buyers prioritize outcome-based contracts with net promoter score guarantees.
Supply Chain Analysis
Inventory velocity for cloud infrastructure provisioning runs through quarterly capacity reservation cycles with hyperscalers. Engineering talent concentrates in India, Poland, and the United States, with natural language processing specialists commanding premium compensation. Cloud compute and storage dependencies draw from AWS, Azure, and GCP regional availability zones. Single-source vulnerability in specialized AI chip supply elevates risk for real-time personalization vendors. Distribution runs through direct enterprise sales, systems integrator partnerships, and marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control scarce integration engineering capacity, as enterprise procurement teams prioritize single-vendor accountability over point solution sophistication. Natural language processing expertise and legacy system connectivity represent the critical asset gaps separating consolidators from casualties.
For Market Incumbents: Fortify large-enterprise retention through captive professional services capacity in Frankfurt and Singapore financial services clusters. Accelerate ISO 27001 certification pipelines to compress nine-to-fourteen-month security audit timelines. Defend against API-first displacement by embedding journey orchestration modules within existing ERP installations. For New Entrants and Emerging Players: SOC 2 Type II fast-track programs unlock mid-market procurement cycles previously blocked by compliance gates. White-space concentration sits in Nigerian and Kenyan embedded finance CX, where mobile-first deployment bypasses desktop-era infrastructure constraints. Pursue vertical-specific positioning around ANVISA-aligned healthcare feedback management to differentiate from horizontal platform competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among journey orchestration specialists with existing banking sector deployments. Five-to-ten-year viability favors vendors with demonstrated EU AI Act compliance architecture and explainable sentiment classification pipelines. Monitor ISO 27001 certification backlog as an inflection indicator for financial services go-live velocity and annual recurring revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented ticketing, analytics, and engagement modules into single-vendor accountability structures. |
| Acquisition of Specialist Firm | Captures scarce natural language processing engineering capacity and pre-trained sentiment models. |
| Geographic Expansion | Establishes local data residency infrastructure to satisfy China's SAMR localization mandates. |
| Strategic Partnership | Accelerates ISO 27001 certification through hyperscaler security compliance inheritance. |
| Product Launch | Introduces human-in-the-loop explainability interfaces to satisfy EU AI Act algorithmic transparency requirements. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and integration specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and ISO certification registries. Bottom-up deployment estimates triangulated against top-down enterprise software spending benchmarks.
Sensitivity analysis tested forecast robustness across cloud migration velocity scenarios and regulatory implementation timelines. Segmentation dimensions spanned deployment model, organization size, vertical compliance requirements, integration complexity, and regional adoption patterns. CAGRs derived from fitted growth curves incorporating vendor reported bookings, systems integrator pipeline data, and enterprise procurement survey responses.
The analysis sits within stated boundaries; outcomes outside sustained cloud infrastructure investment cycles or accelerated EU AI Act enforcement would require recalibration. Forecasts reflect documented assumptions regarding hyperscaler pricing trajectories and talent availability in India and Brazil. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market