
 Digital Evidence Management System Market | 2026-2036
Digital Evidence Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Evidence Management System Market Analysis
CJIS Security Policy certification is rotating vendor eligibility for law enforcement contracts, forcing platform providers to demonstrate FedRAMP-equivalent controls and state-level criminal justice integration. Motorola Solutions leverages its installed radio infrastructure to bundle evidence management with existing command-center workflows. Axon Enterprise sustains dominance in body-worn camera-to-cloud pipelines, competing on seamless ingest-to-archive automation. Cellebrite differentiates through mobile forensics extraction that feeds directly into centralized evidence repositories.
A digital evidence management system is a software platform that ingests, stores, indexes, and retrieves multimedia evidence from body cameras, CCTV, mobile devices, and IoT sensors, enforcing cryptographic chain-of-custody logs and role-based access controls to preserve legal admissibility. Cloud-based deployments lead product type segments because agencies trade capital expenditure for operational scalability, while hybrid architectures capture fastest-growing demand from jurisdictions requiring local storage with cloud failover. Chain of custody application modules command premium pricing due to audit-trail litigation exposure, whereas incident reporting functions have matured into commodity feature sets with thinner margins.
FBI CJIS Security Policy, GDPR evidence-handling protocols, and state-level public records statutes collectively shape procurement specifications and data residency obligations for vendors and buyers. The SEC's expanding interest in corporate digital communications retention is extending compliance pressure beyond traditional criminal justice into enterprise security deployments. Stakeholders must monitor evolving encryption standards and cross-border data transfer rulings that could fragment platform architectures or trigger costly retrofit cycles.
Market Dynamics
Law enforcement agencies are forcing platform architectures toward hybrid cloud-local storage models as CJIS Security Policy audits tighten cryptographic chain-of-custody requirements and disqualify pure-cloud vendors from federal procurement pools.
Growth Catalysts
- FBI CJIS Security Policy:Compliance mandates rotate vendor eligibility for state and municipal contracts, compelling platform providers to demonstrate FedRAMP-equivalent controls and criminal justice integration capabilities.
- Body-worn camera proliferation:Police departments generate petabyte-scale video evidence daily, creating infrastructure demand for automated ingest-to-archive pipelines with tamper-proof audit trails.
- GDPR chain-of-custody protocols:European evidence-handling standards extend data residency obligations to cross-border criminal investigations, requiring vendors to architect region-specific storage nodes.
Market Restraints
- Encryption standard volatility:NIST post-quantum cryptography migration timelines force premature platform re-engineering, compressing depreciation schedules for recently deployed systems.
- Cloud concentration risk:Three hyperscalers dominate criminal justice cloud infrastructure, creating single-point-of-failure exposure for evidence availability during critical investigations.
- Legacy system entrenchment:On-premise digital asset management installations from the 2010s resist API-based integration, fragmenting evidence repositories across incompatible silos.
Strategic Opportunities
- SEC digital communications retention:Expanding enforcement interest in corporate messaging platforms extends compliance pressure into enterprise security deployments beyond traditional criminal justice.
- IoT sensor evidence streams:Smart city traffic cameras, drone footage, and connected vehicle black boxes create new ingestion workloads requiring real-time chain-of-custody automation.
- Mobile forensics convergence:Extraction tools for encrypted smartphones and wearable devices feed directly into centralized repositories, eliminating manual transfer vulnerabilities.
Industry Challenges
- Forensic analyst talent scarcity:Certified digital evidence examiners command premium compensation, constraining agency capacity to process backlog volumes within statutory deadlines.
- Interoperability certification delays:State-level criminal justice information system integration requires 18-24 month validation cycles, freezing procurement decisions until connectivity is proven.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Evidence Management System Market |
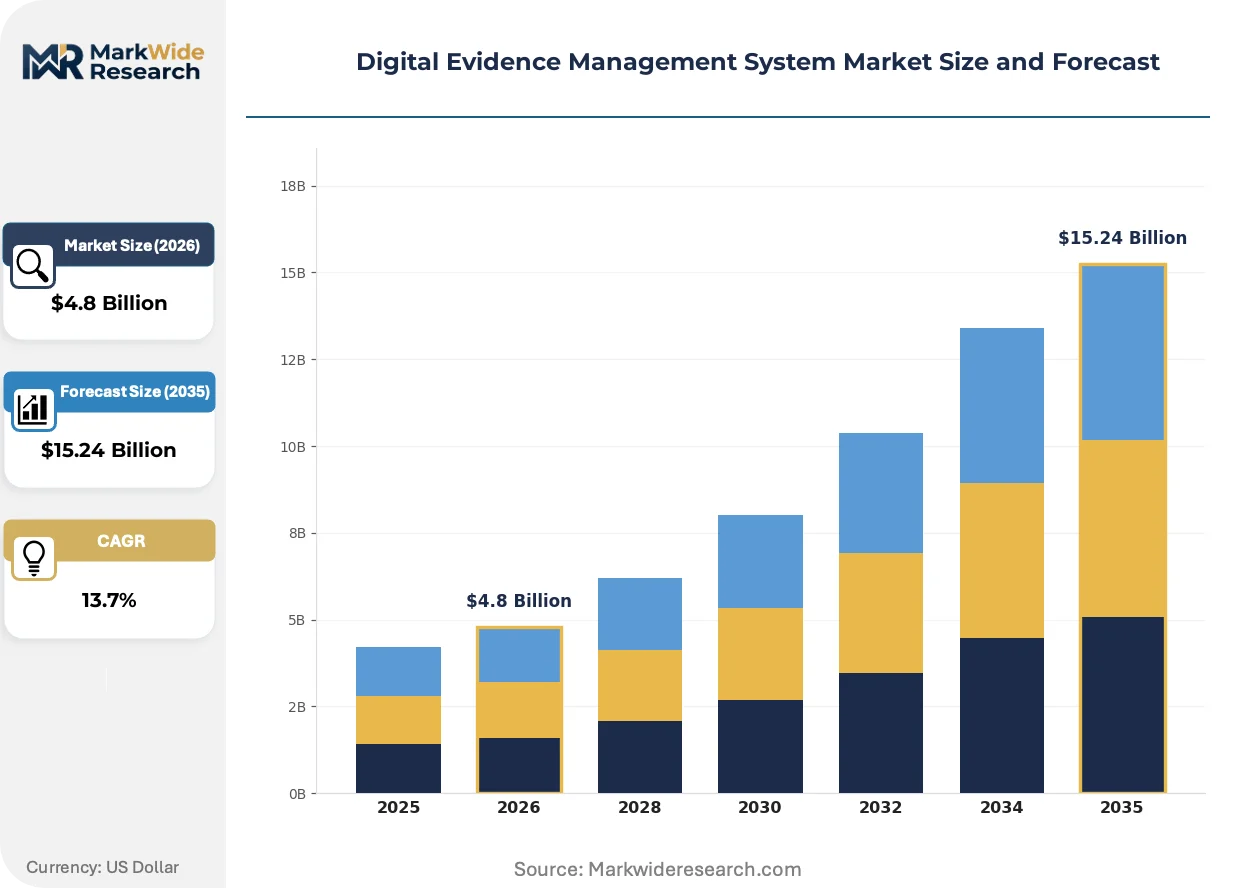
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile End User: Law Enforcement, Courts, Legal Firms, Corporate Security Deployment Model: Public Cloud, Private Cloud, Community Cloud, On-Premises Application: Case Management, Incident Reporting, Digital Forensics, Chain of Custody |
| Companies Covered | Motorola Solutions, Axon Enterprise, Cellebrite, NICE Ltd., IBM Corporation, Panasonic Corporation, OpenText Corporation, Verint Systems, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Evidence Management System Market Emerging Trajectories
Evidence management architectures are fragmenting between cloud-native automation and hardened local storage as regulatory jurisdictions impose incompatible data sovereignty requirements on the same vendor base.
Blockchain-anchored audit trails are bifurcating vendor competitive positioning. Cryptographic hashing tied to distributed ledger timestamps creates immutable custody records admissible under Federal Rules of Evidence. Large metropolitan police departments deploy these capabilities for high-profile case files, while smaller agencies delay adoption pending cost reduction. The technology is compressing differentiation timelines for legacy log-based systems.
GDPR Article 17 right-to-erasure conflicts with criminal evidence retention mandates across EU member states. National data protection authorities issue contradictory guidance on whether convicted offender data qualifies for deletion requests. Vendors serving cross-border law enforcement must architect jurisdictional partitioning that satisfies both preservation and privacy obligations. German federal police and French gendarmerie have adopted divergent technical implementations.
Subscription-based procurement displaces perpetual licensing for municipal evidence platforms. Police departments trade upfront capital expenditure for operational scalability aligned with grant funding cycles. Value-added resellers and systems integrators capture recurring revenue streams previously retained by original equipment manufacturers. This pattern concentrates in United States jurisdictions where federal justice assistance grants finance multi-year service contracts rather than equipment purchases.
Digital Evidence Management System Market Segmentation
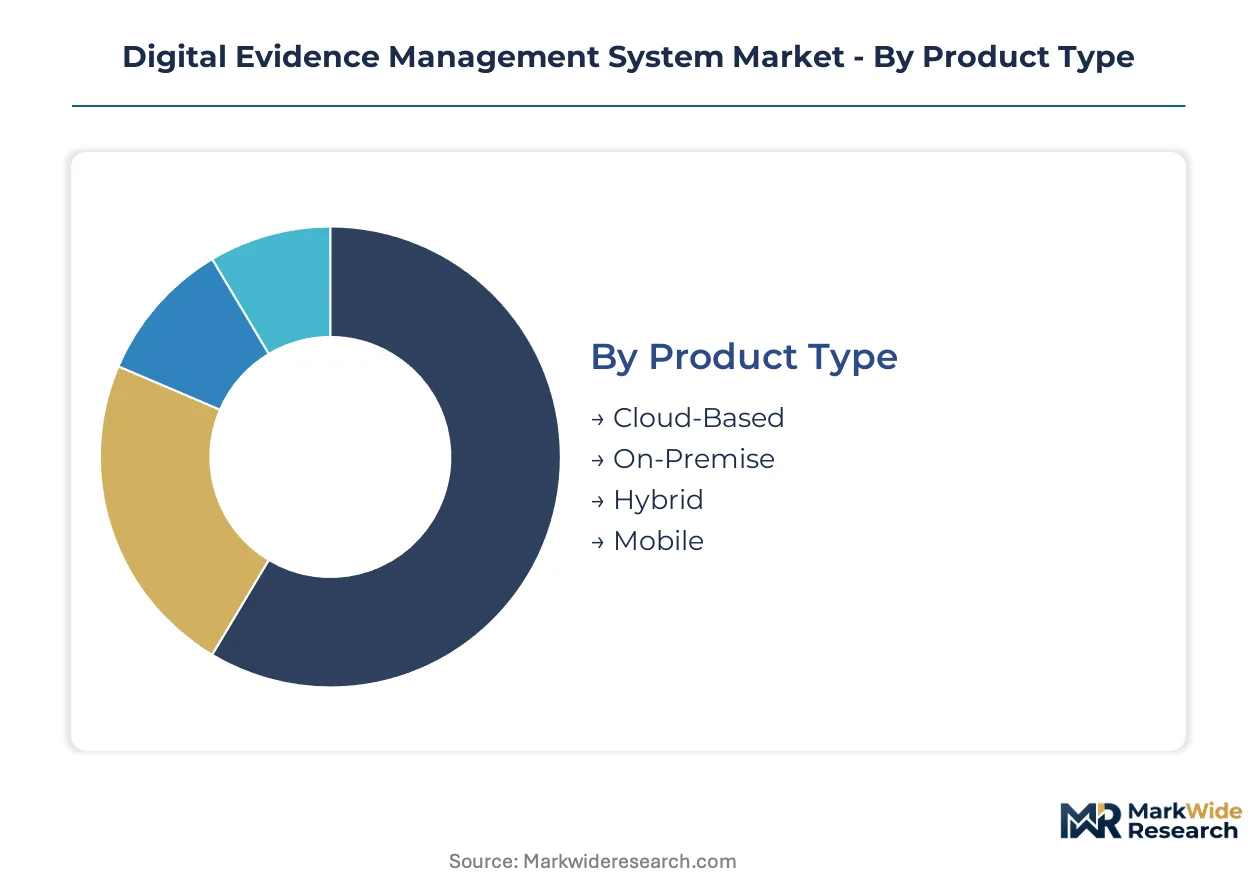
Evidence management procurement fractures across incompatible compliance regimes, forcing vendors to architect segment-specific encryption standards and residency configurations. Buyers select product types and deployment models based on audit exposure, budget cycles, and integration complexity with legacy criminal justice systems.
Product Type:
FBI CJIS Security Policy and GDPR chain-of-custody mandates impose divergent cryptographic requirements that rotate vendor eligibility across cloud, on-premise, and hybrid configurations.
- Cloud-Based:Multi-tenant architectures with FedRAMP-equivalent controls dominate municipal police departments seeking operational scalability without capital expenditure. CJIS Security Policy audits disqualify pure-cloud vendors from federal procurement pools in the United States, compressing addressable market share for hyperscaler-dependent platforms.
- Hybrid:Local storage nodes with cloud failover satisfy jurisdictions requiring tamper-proof custody logs on-premise while leveraging elastic compute for archival retrieval. German federal police and French gendarmerie deploy divergent technical implementations of this architecture to reconcile GDPR Article 17 erasure requests with evidence preservation mandates.
- On-Premise:Hardened appliances in classified facility environments serve intelligence agencies and military criminal investigative divisions with air-gapped operational security.
- Mobile:Smartphone-native ingestion applications extend chain-of-custody automation to field officers without workstation dependency.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
End User:
Procurement authority concentrates in agencies with statutory evidence retention obligations and dedicated forensic examiner staffing.
- Law Enforcement:Body-worn camera deployments generate petabyte-scale video evidence daily, creating infrastructure demand for automated ingest-to-archive pipelines. Police departments trade upfront capital expenditure for subscription-based operational scalability aligned with federal justice assistance grant cycles.
- Courts:Clerks require tamper-proof exhibit repositories with role-based access controls satisfying judicial admissibility standards under Federal Rules of Evidence.
- Legal Firms:Defense practices and civil litigation boutiques adopt cloud-native platforms for discovery document management without CJIS-level security investment.
- Corporate Security:SEC digital communications retention enforcement extends compliance pressure into enterprise security deployments beyond traditional criminal justice.
Procurement concentration sits with Law Enforcement; Corporate Security represents the steepest expansion trajectory.
Deployment Model:
Cost tier differentiation separates hyperscaler-dependent public offerings from sovereign-controlled private infrastructure with 40-60% pricing premiums.
- Public Cloud:Shared infrastructure with consumption-based pricing captures small-to-midsize municipal agencies lacking dedicated IT security personnel.
- Private Cloud:Single-tenant environments with dedicated encryption key management serve state-level criminal justice information systems requiring 18-24 month interoperability certification cycles.
- Community Cloud:Multi-agency federated deployments share operational costs across county sheriff departments and municipal police within unified judicial districts.
- On-Premises:Capital-intensive installations persist in legacy-entrenched jurisdictions from the 2010s resisting API-based integration with modern evidence repositories.
Budget compression favors Public Cloud; audit exposure favors Private Cloud.
Application:
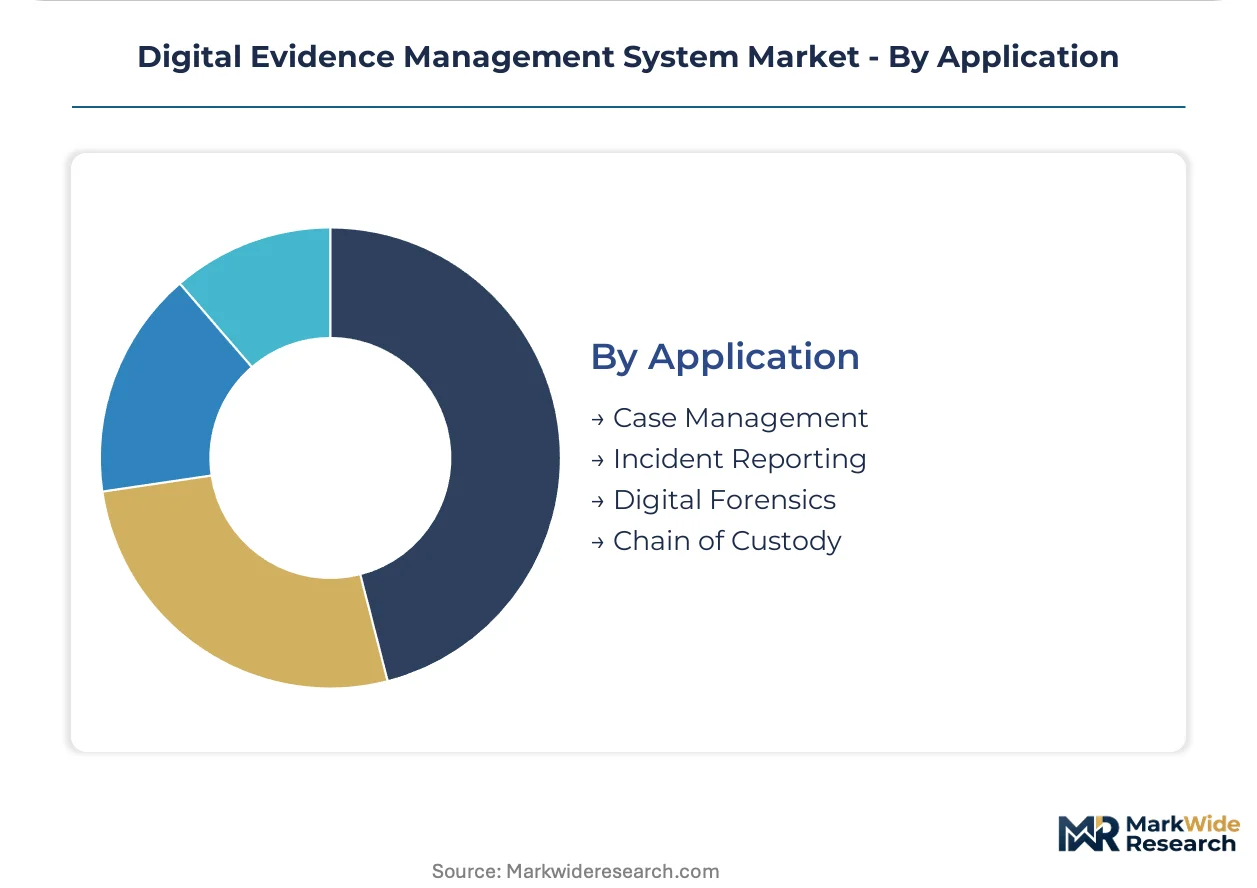
Margin structure inverts between commoditized incident reporting and premium chain-of-custody modules with litigation-driven pricing power.
- Chain of Custody:Cryptographic hashing with blockchain-anchored timestamps creates immutable audit trails admissible under Federal Rules of Evidence. Large metropolitan police departments deploy these capabilities for high-profile case files while smaller agencies delay adoption pending cost reduction.
- Case Management:Workflow automation for prosecutor discovery obligations and defense access requests integrates with court scheduling systems and statutory deadline tracking.
- Digital Forensics:Mobile device extraction and wearable data parsing feed directly into centralized repositories, eliminating manual transfer vulnerabilities.
- Incident Reporting:Mature feature sets with standardized data fields command thinner margins as competitive differentiation compresses to user interface refinement.
Revenue concentration sits with Chain of Custody; automation investment favors Digital Forensics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal justice assistance grants accelerate procurement cycles in the United States, while GDPR chain-of-custody protocols reshape European data residency obligations. CJIS Security Policy audits disqualify pure-cloud vendors from state contracts, fragmenting vendor eligibility across jurisdictions.
United States
FBI CJIS Security Policy compliance rotates vendor eligibility for law enforcement contracts, compelling platform providers to demonstrate FedRAMP-equivalent controls. Federal grants for police modernization finance multi-year service contracts rather than equipment purchases. Metropolitan police departments in Chicago and Los Angeles deploy petabyte-scale body-worn camera infrastructure with automated ingest-to-archive pipelines.
Germany
GDPR Article 17 right-to-erasure conflicts with criminal evidence retention mandates, forcing federal police to architect jurisdictional partitioning. The country's national data protection authority issues guidance on convicted offender data deletion requests. Berlin and Munich host divergent technical implementations of hybrid cloud-local storage models.
France
CNIL guidance on cross-border criminal investigations extends data residency obligations to evidence handling protocols. The gendarmerie deploys hardened local storage nodes with cloud failover distinct from German federal implementations. Paris and Lyon concentrate procurement authority for national criminal justice information system integration.
United Kingdom
Public records statutes and evidence-handling standards shape procurement specifications for municipal police departments. The Metropolitan Police Service generates substantial video evidence volumes requiring operational scalability without capital expenditure. London anchors demand for subscription-based evidence platforms aligned with grant funding cycles.
Australia
State-level criminal justice agencies enforce chain-of-custody requirements for body-worn camera deployments across territorial police forces. The country's national cybersecurity framework influences encryption standards for evidence repositories. Sydney and Melbourne host federated multi-agency deployments sharing operational costs across unified judicial districts.
Digital Evidence Management System Market Vendor Landscape
Player mix skews toward diversified technology conglomerates with adjacent public safety portfolios. Market structure concentrates around vendors with installed infrastructure in radio communications, body-worn cameras, or enterprise software. Three strategic archetypes dominate: radio infrastructure bundlers, camera-to-cloud pipeline operators, and mobile forensics specialists. Competitive moves center on interoperability certification and grant-funded subscription conversion.
Within the infrastructure-bundling tier, Motorola Solutions leverages installed radio networks to integrate evidence management with command-center workflows. Axon Enterprise exemplifies the camera-native archetype through seamless ingest-to-archive automation from body-worn devices. Cellebrite occupies a distinct position as mobile forensics extraction feeds directly into centralized repositories, eliminating manual transfer vulnerabilities.
| Leading Market Players |
|---|
| Motorola Solutions |
| Axon Enterprise |
| Cellebrite |
| NICE Ltd. |
| IBM Corporation |
| Panasonic Corporation |
| OpenText Corporation |
| Verint Systems |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month interoperability certification cycles for state-level criminal justice information systems concentrate vendor pricing power with established platform providers holding validated integrations, while subscription-based SaaS procurement compresses upfront capital barriers for municipal buyers. CJIS Security Policy compliance costs and FedRAMP-equivalent control investments create tiered entry thresholds that stratify pricing across certification-holding incumbents and uncertified challengers.
Pricing Analysis
Certification level—CJIS Security Policy, FedRAMP authorization, GDPR Article 17 jurisdictional partitioning—creates the primary spread between premium hybrid deployments and commodity public cloud offerings. Three-tier pricing structure across CJIS-certified premium, state-compliant standard, and municipal-economy levels reflects audit exposure and integration complexity. Cost compression in the public cloud tier intensifies as hyperscaler competition commoditizes storage infrastructure. Municipal police departments exhibit highest price sensitivity due to grant-dependent budget cycles, while federal agencies prioritize compliance assurance over cost optimization.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native deployments where hyperscalers maintain elastic compute reserves, whereas strategic stockpiling of cryptographic hardware security modules characterizes hybrid and on-premise jurisdictions with air-gapped requirements. Supply concentrates in the United States for CJIS-certified infrastructure, Germany and France for GDPR-compliant jurisdictional partitioning, and Israel for mobile forensics extraction capabilities. Component dependencies include FIPS 140-2 validated encryption modules, tamper-evident storage appliances, and blockchain-anchored timestamping services. Single-source vulnerability in CJIS audit certification bodies creates bottleneck risk for vendor market entry. Distribution runs through value-added resellers with existing criminal justice relationships and federal grant administration expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in digital evidence management are inflecting toward ecosystem orchestration as CJIS interoperability certification becomes the gating mechanism for procurement eligibility, consolidating vendor power with integrated suite providers.
For Market Incumbents: Compound defensive positioning through exclusive interoperability certification fast-tracks with state criminal justice information systems and backward integration into body-worn camera hardware manufacturing to lock ingest-to-archive pipelines. Threat substitution from mobile-native field ingestion applications demands counter-investment in smartphone SDK deployment. Certification investment in emerging GDPR Article 17 jurisdictional partitioning capabilities secures European expansion against regional specialists. For New Entrants and Emerging Players: CJIS Security Policy certification fast-tracks through partnership with established audit consultancies unlock municipal procurement pools currently frozen to unvalidated vendors. White-space targets include corporate security segments under SEC digital communications retention pressure and mid-size county sheriff departments underserved by metropolitan-focused incumbents. Go-to-market angle emphasizes grant-funded subscription conversion with operational expenditure alignment replacing capital-intensive perpetual licensing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as hyperscaler infrastructure eliminates data center buildout requirements, compressing barrier-to-entry timelines for platform challengers. Long-term viability favors vendors with installed radio or camera hardware ecosystems generating captive evidence management demand. Acquisition target archetype: mobile forensics specialists with direct-to-repository extraction capabilities. Signal to watch: state-level interoperability certification backlog clearance rates as leading indicator of vendor rotation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CJIS-certified interoperability with state criminal justice information systems unlocks frozen procurement pipelines. |
| Acquisition of Specialist Firm | Mobile forensics extraction capabilities eliminate manual transfer vulnerabilities in smartphone evidence handling. |
| Strategic Partnership | Federal grant administration partnerships with value-added resellers accelerate subscription conversion cycles. |
| Geographic Expansion | GDPR Article 17 jurisdictional partitioning architectures capture cross-border law enforcement contracts. |
| Product Launch | Blockchain-anchored audit trail modules command premium pricing in high-profile case file segments. |
Methodological Framework
Cross-validation between primary interviews with law enforcement IT directors, CJIS compliance officers, state procurement managers, and digital forensics examiners and secondary validation through FBI CJIS Security Policy documentation, federal grant administration databases, and state public records statutes anchors the qualitative findings. Bottom-up triangulation aggregates municipal agency deployment data with top-down reconciliation against hyperscaler criminal justice cloud infrastructure disclosures.
Sensitivity analysis across deployment model, end-user agency tier, application module mix, and regional regulatory cluster dimensions informs the analytical framework over the projection horizon. CAGRs derive from segment-level adoption curves weighted by grant funding cycle timing and interoperability certification pipeline status. Forecast inputs include body-worn camera shipment volumes and CJIS audit queue clearance rates.
Underlying assumptions cover CJIS Security Policy stability, hyperscaler criminal justice cloud availability, and GDPR Article 17 guidance convergence, with deviation risk concentrated in NIST post-quantum cryptography migration timelines and cross-border data transfer ruling fragmentation. Revision becomes warranted when state-level interoperability certification backlogs exceed statutory procurement deadlines or federal grant structures shift from operational expenditure toward capital equipment financing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
P2P Rental Apps Market
Digital Solutions
Captioning and Subtitling Solutions Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Email Marketing Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Premium Messaging Market
Digital Solutions
G2P Systems Market